
 Aliphatic Solvents and Thinners Market | 2026-2036
Aliphatic Solvents and Thinners Market Size, Share, and Industry Trends Forecast 2026-2036
Aliphatic Solvents and Thinners Market Analysis
High-purity low-aromatic grades is bifurcating the competitive landscape as coatings manufacturers reject conventional mineral spirits for VOC-compliant alternatives. ExxonMobil Corporation leverages its integrated refinery network to secure consistent feedstock quality across North American and Asian supply points. Shell plc anchors its position through dedicated solvent production trains at Jurong Island and Rotterdam that sustain pharmaceutical-grade hexane output. Haltermann Carless Group GmbH differentiates via specialty narrow-cut hydrocarbons for precision adhesive applications where evaporation profiles determine bond performance.
Aliphatic solvents and thinners comprise saturated hydrocarbon liquids—primarily C5-C12 paraffinic and cycloparaffinic fractions distilled from petroleum or synthesized via Fischer-Tropsch routes—with boiling ranges typically between 30°C and 220°C, formulated to dissolve oils, resins, and polymers while exhibiting controlled evaporation rates. Their primary commercial purpose centers on reducing viscosity of coating systems, cleaning industrial equipment, and preparing surfaces prior to adhesive bonding or painting. Mineral spirits retains the largest volume share within product type segments as construction maintenance and DIY channels consume steady quantities, though hexane gains structural importance from lithium-ion battery electrode manufacturing expansion. Application-level margin pools concentrate in adhesive solvents where semiconductor and electronics assembly demand ultra-low residue specifications that command premium pricing over commodity paint thinning grades.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain benzene content in commercial solvent formulations, while REACH registration requirements in Europe enforce full toxicological dossiers for C9-C14 aliphatic import volumes above one tonne annually. China's GB standards administered by SAMR set flash point and aromatic ceiling thresholds that determine market access for imported thinner products. Stakeholders must monitor evolving state-level VOC rules in California and New York that often prefigure federal standards, while tracking battery sector qualification protocols that are reshaping hexane purity requirements.
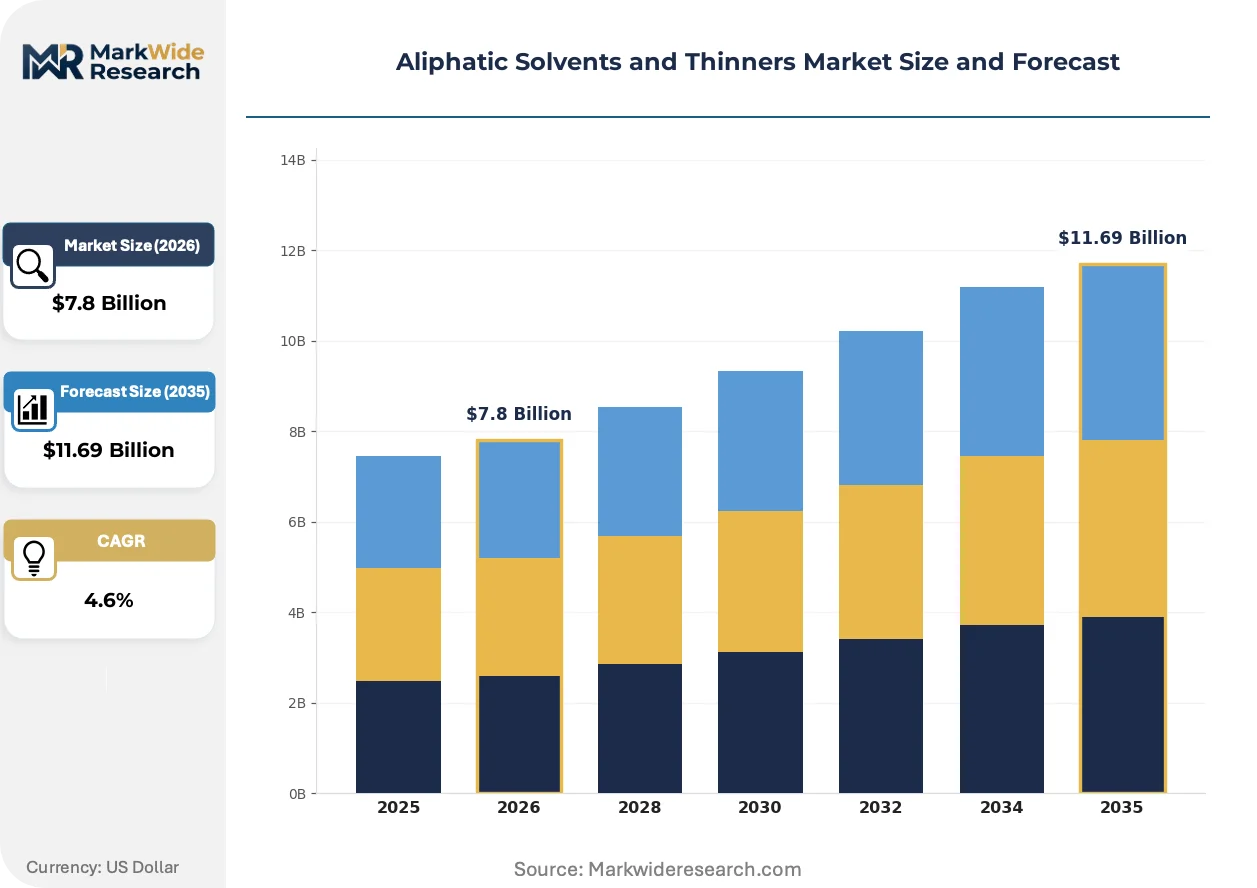
Market Dynamics
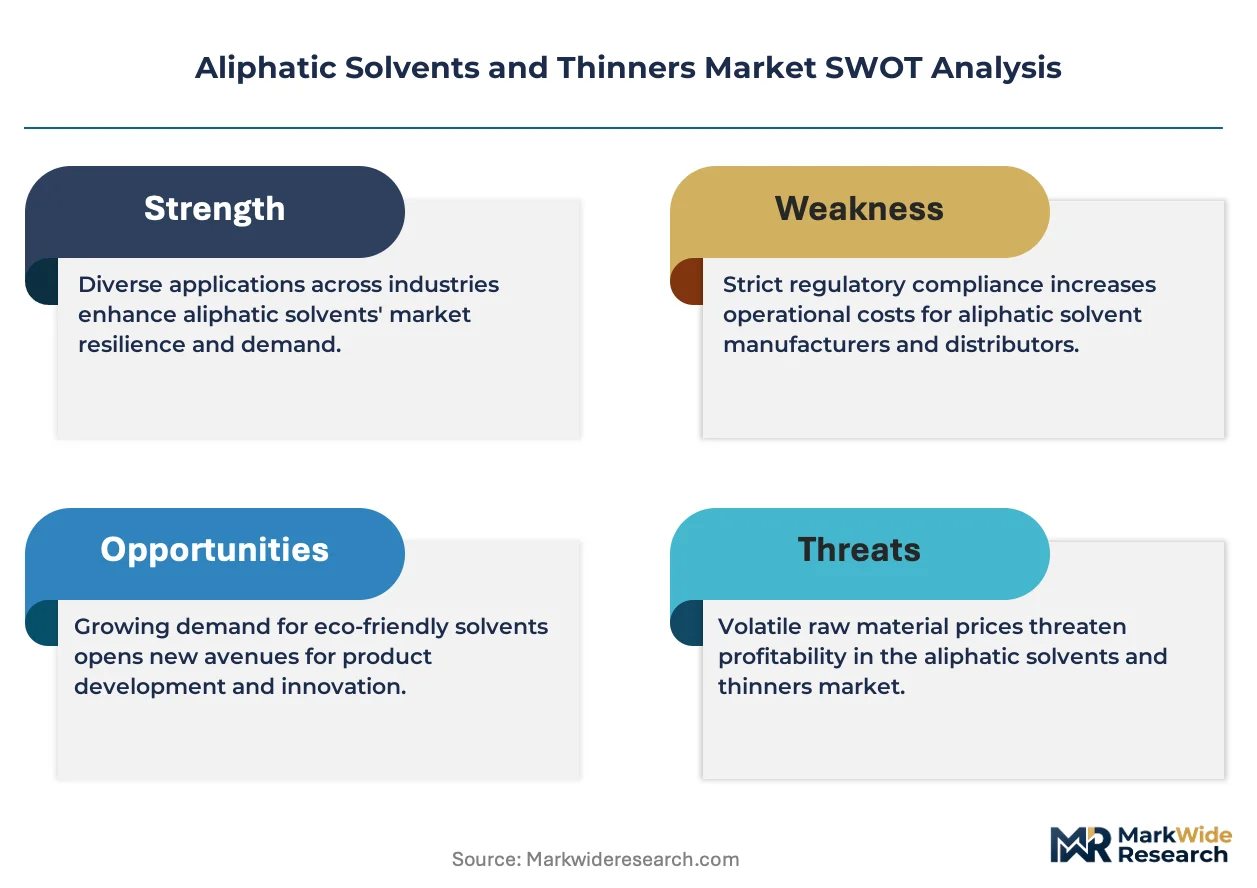
REACH restrictions on volatile organic compounds are forcing coatings manufacturers across Europe to abandon conventional mineral spirits, redirecting formulation investments toward compliant low-aromatic hydrocarbon blends that command premium positioning.
Growth Catalysts
- Lithium-ion electrode manufacturing:Battery producers in China and South Korea consume pharmaceutical-grade hexane for cathode slurry preparation, creating dedicated demand streams that insulate suppliers from paint-sector cyclicality.
- EPA NESHAP benzene limits:US refiners have invested in hydrotreating capacity to produce sub-0.1% aromatic mineral spirits, opening federal contracting channels previously closed to higher-aromatic imports.
- Yangtze River Delta cluster expansion:Chemical processing hubs around Shanghai and Ningbo absorb naphtha-derived thinners at scale, anchoring regional throughput for integrated solvent producers.
Market Restraints
- Crude oil feedstock volatility:Paraffinic base stock costs track Brent crude differentials, compressing blender margins during upstream price spikes without corresponding downstream pricing power.
- Jurong Island supply concentration:Singapore hosts disproportionate specialty hexane distillation capacity; operational disruptions at Shell's Pulau Bukom complex cascade through Asia-Pacific pharmaceutical and electronics supply chains.
- Waterborne coating substitution:Architectural paint formulators in California and New York are eliminating hydrocarbon thinners entirely, displacing volume in the largest regional construction maintenance market.
Strategic Opportunities
- Semiconductor adhesive solvents:Ultra-low residue specifications for die-attach applications in Taiwan and South Korea command 3-4x pricing multiples over commodity grades, rewarding narrow-cut purification investments.
- India PLI scheme for battery manufacturing:Domestic cell production incentives are attracting electrode coating operations that will require hexane supply localization, creating import substitution openings.
- EU Green Deal carbon border adjustments:Fischer-Tropsch synthetic aliphatics with verified low-carbon intensity will receive preferential treatment, advantaging gas-to-liquids producers over conventional petroleum refiners.
Industry Challenges
- Hydrotreater catalyst expertise scarcity:Deep desulfurization and aromatic saturation operations require specialized chemical engineering talent concentrated at a handful of European and Gulf Coast refiners.
- Pharmaceutical-grade certification timelines:Hexane qualification for USP/NF applications demands 18-24 month stability documentation, locking out new entrants during periods of supply shortage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aliphatic Solvents and Thinners Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Spirits, Naphtha, Hexane, Acetone Application: Paint Thinning, Cleaning Agents, Adhesive Solvents, Degreasing End User: Construction, Automotive, Manufacturing, Chemical Processing Distribution Channel: Direct Sales, Online Retail, Wholesale, Re-sellers |
| Companies Covered | ExxonMobil Corporation, Shell plc, Phillips 66, SK Geocentric Co., Ltd., Calumet, Inc., TotalEnergies, BASF, Chevron Phillips Chemical Company LLC, Haltermann Carless Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aliphatic Solvents and Thinners Market Emerging Trajectories
Formulation chemistry and regulatory compliance are converging to reshape product specifications, with purity thresholds and carbon intensity metrics displacing traditional price-per-gallon procurement criteria across industrial buyer segments.
Advanced membrane separation technology for narrow-cut hydrocarbon distillation is fragmenting the competitive landscape between integrated refiners and standalone solvent specialists. Battery manufacturers in South Korea and Japan are specifying sub-50 ppm sulfur hexane for electrode production, forcing suppliers to choose between dedicated purification asset deployment or exit from premium segments. This technology is fragmenting margin pools across the value chain as purification capabilities become the primary differentiation lever.
REACH authorization requirements for C9-C14 aliphatic hydrocarbons are tightening toxicological dossier standards for import volumes exceeding one tonne annually. European coatings formulators face registration cost burdens that favor larger suppliers with dedicated regulatory affairs infrastructure, accelerating consolidation in mid-tier mineral spirits distribution. Specialty adhesive solvent segments are responding by migrating toward pre-registered Fischer-Tropsch feedstocks that circumvent petroleum-derived substance complexity.
Specification-driven procurement is compressing supplier qualification cycles in semiconductor and pharmaceutical end-uses. Electronics assemblers in Taiwan and Malaysia now require solvent certificates of analysis with every delivery, replacing spot-market purchasing with approved-vendor list constraints. This behavioral shift concentrates volume with integrated producers capable of batch-level traceability, disadvantaging traders and re-packagers in precision applications.
Aliphatic Solvents and Thinners Market Segmentation
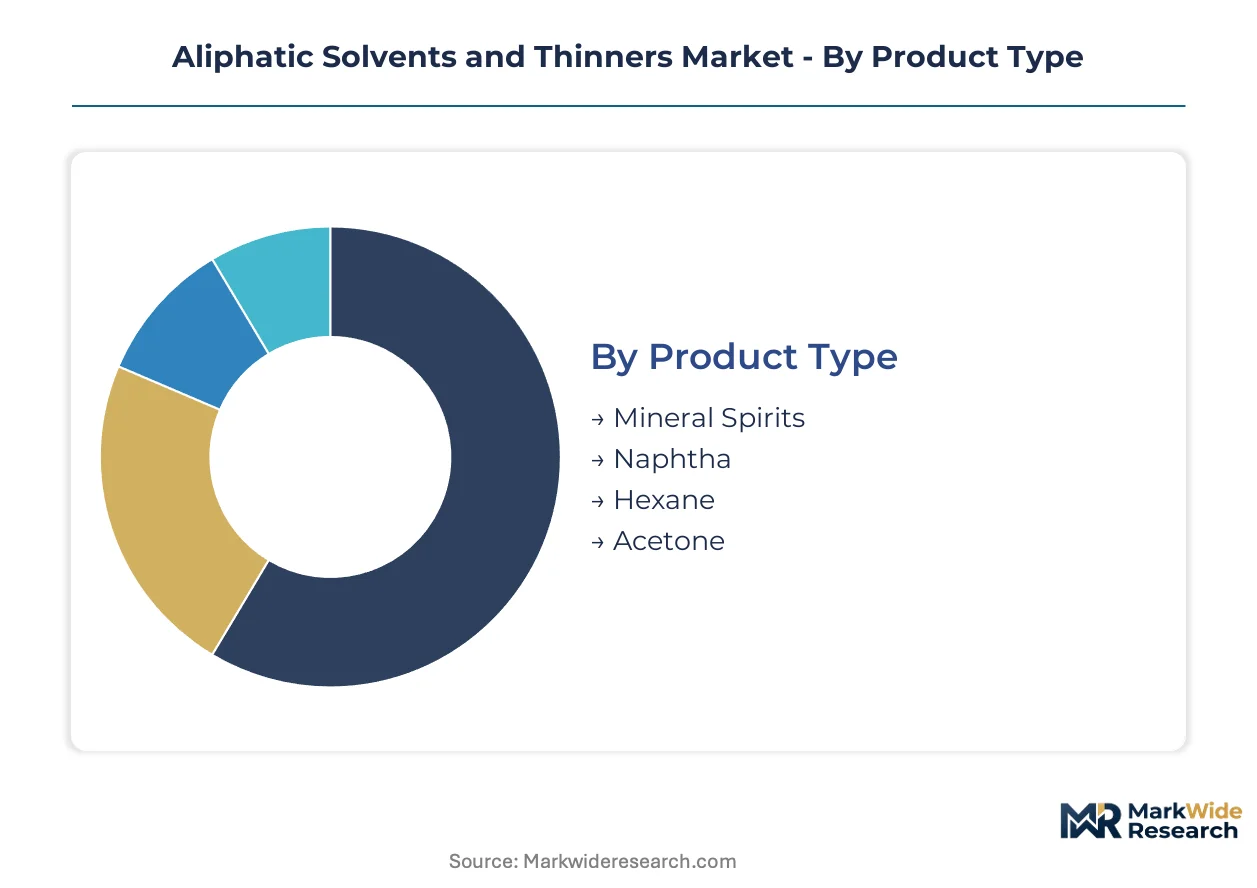
Aliphatic solvent procurement patterns diverge sharply across end-use specifications, with coating formulators prioritizing evaporation profile control while battery manufacturers enforce ultra-low residue thresholds. Segmentation clarity enables suppliers to align distillation investments with margin concentration points rather than commodity volume pools.
Product Type:
Waterborne coating substitution pressures fall unevenly across hydrocarbon grades, with aromatic-bearing mineral spirits facing displacement while high-purity hexane escapes direct replacement.
- Mineral Spirits:Petroleum-derived C5-C12 paraffinic and cycloparaffinic fractions with boiling ranges between 150°C and 220°C, formulated for viscosity reduction in oil-based coatings. Construction maintenance channels across the United States absorb steady volumes, though California and New York state-level VOC rules are eliminating hydrocarbon thinners entirely from architectural paint formulations.
- Hexane:Narrow-cut C6 saturated hydrocarbon with stringent purity requirements for pharmaceutical and electronics applications. Battery producers in China and South Korea consume pharmaceutical-grade material for cathode slurry preparation, creating dedicated demand streams insulated from paint-sector cyclicality.
- Naphtha:Light hydrocarbon feedstock serving as precursor for steam cracking and solvent extraction processes. Chemical processing clusters along China's Yangtze River Delta consume substantial naphtha-derived thinners for industrial coatings at scale.
- Acetone:Oxygenated solvent with distinct solubility parameters for resin dissolution and surface preparation. Electronics assemblers in Taiwan and Malaysia specify certificates of analysis with every delivery, replacing spot-market purchasing with approved-vendor constraints.
Mineral spirits anchors the volume base while hexane gains share at the steepest rate.
Application:
Margin pools concentrate where specification stringency exceeds commodity availability, with precision applications commanding substantial premia over standard thinning operations.
- Paint Thinning:Viscosity reduction for coating application across automotive refinishing and industrial maintenance operations. Automotive refinishing operations are absorbing higher volumes of low-aromatic mineral spirits as OEM specifications tighten.
- Adhesive Solvents:Surface preparation and bond activation for industrial assembly. Semiconductor and electronics assembly demand ultra-low residue specifications that command premium pricing over commodity paint thinning grades.
- Cleaning Agents:Equipment and surface degreasing for manufacturing maintenance. REACH restrictions on volatile organic compounds in Europe are redirecting formulation investments toward compliant hydrocarbon blends.
- Degreasing:Heavy-duty oil and contaminant removal for metal fabrication and machinery overhaul. EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain benzene content in commercial solvent formulations.
Paint thinning retains the largest volume position while adhesive solvents deliver the highest margin realization.
End User:
Customer concentration patterns reflect regional industrial clustering, with procurement authority consolidating at integrated chemical processors.
- Construction:Maintenance painting and surface preparation for commercial and residential building upkeep. DIY channels consume steady quantities of mineral spirits despite waterborne substitution in professional architectural segments.
- Automotive:OEM coating operations and aftermarket refinishing services. Paint thinning applications across automotive refinishing operations are absorbing higher volumes of low-aromatic mineral spirits.
- Manufacturing:General industrial coating and cleaning applications across fabricated metal and machinery sectors. Electronics assemblers in Taiwan and Malaysia now require solvent certificates of analysis with every delivery.
- Chemical Processing:Intermediate production and formulation operations serving downstream specialty chemical markets. Chemical processing clusters along China's Yangtze River Delta consume substantial naphtha-derived thinners for industrial coatings.
Construction anchors volume throughput while chemical processing expands most quickly on battery electrode manufacturing demand.
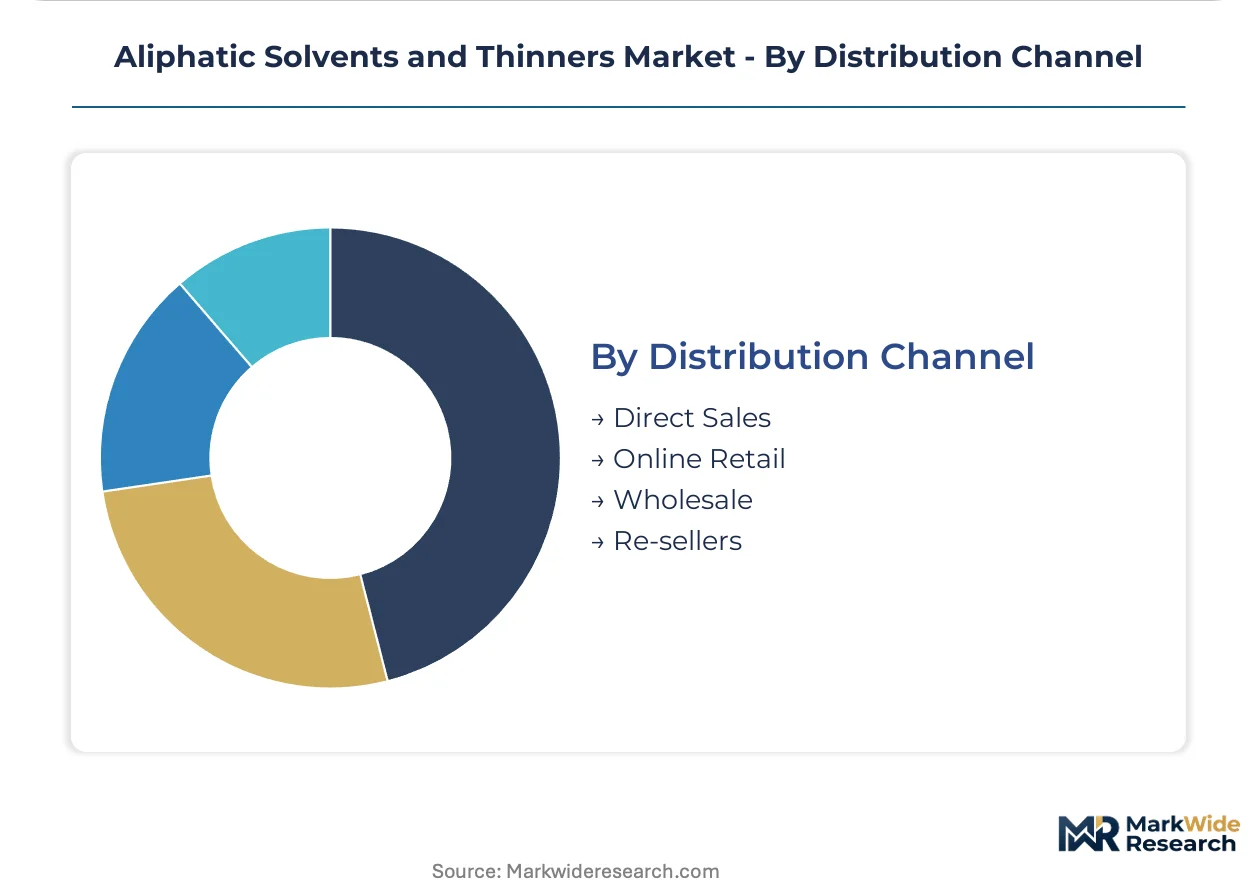
Distribution Channel:
Channel selection correlates with batch traceability requirements, with precision end-users bypassing intermediaries entirely.
- Direct Sales:Manufacturer-to-end-user supply relationships for high-volume or specification-critical accounts. Battery manufacturers in South Korea and Japan are specifying sub-50 ppm sulfur hexane for electrode production.
- Wholesale:Bulk distribution to industrial distributors and formulators with established storage infrastructure. Mid-tier mineral spirits distribution is accelerating consolidation as REACH registration cost burdens favor larger suppliers.
- Online Retail:E-commerce platforms serving small-volume maintenance and DIY purchasers. Specification-driven procurement is compressing supplier qualification cycles in semiconductor and pharmaceutical end-uses.
- Re-sellers:Independent traders and repackagers serving fragmented regional demand. Batch-level traceability requirements are disadvantaging traders and re-packagers in precision applications.
Direct sales commands the premium segment while wholesale retains the broadest volume coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty hexane distillation capacity concentrates disproportionately at Singapore's Jurong Island complex, while integrated refinery-solvent operations anchor supply security across North American and European demand centers. Battery electrode manufacturing and automotive refinishing are redrawing procurement maps as specification requirements diverge by end-use.
United States
Automotive refinishing operations in Michigan and Ohio absorb expanding volumes of low-aromatic mineral spirits as OEM coating specifications tighten. EPA NESHAP benzene limits below 0.1% aromatic content have unlocked federal contracting channels previously closed to higher-aromatic imports. Gulf Coast hydrotreater investments near Houston sustain pharmaceutical-grade output for domestic battery material suppliers.
China
Cathode slurry preparation for lithium-ion cells drives pharmaceutical-grade hexane consumption at battery plants in Fujian and Jiangsu provinces. SAMR-administered GB standards enforce flash point and aromatic ceiling thresholds that filter imported thinner products. Chemical processing clusters along the Yangtze River Delta around Shanghai and Ningbo consume naphtha-derived thinners for industrial coatings at substantial scale.
Germany
REACH authorization requirements for C9-C14 aliphatic hydrocarbons impose toxicological dossier burdens on coatings formulators importing above one tonne annually. ECHA registration costs favor larger suppliers with dedicated regulatory infrastructure, accelerating consolidation in mid-tier mineral spirits distribution. Industrial coatings demand concentrates in the Ruhr region and Bavarian manufacturing corridors.
South Korea
Battery producers specify sub-50 ppm sulfur hexane for electrode production, forcing suppliers to deploy dedicated purification assets or exit premium segments. MFDS pharmaceutical-grade certification timelines demand 18-24 month stability documentation, locking supply relationships during shortage periods. Electronics assemblers in Gyeonggi Province require solvent certificates of analysis with every delivery.
Singapore
Jurong Island hosts disproportionate specialty hexane distillation capacity serving Asia-Pacific pharmaceutical and electronics supply chains. Operational disruptions at Shell's Pulau Bukom complex cascade through regional semiconductor adhesive solvent markets. The city-state's position as a hydrocarbon trading hub attracts Fischer-Tropsch synthetic aliphatic volumes seeking EU Green Deal carbon border preferential treatment.
Aliphatic Solvents and Thinners Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petroleum refiners commanding feedstock security while standalone solvent specialists capture specification-driven premia. The market structure tiers into three clusters: global majors with refinery-integrated solvent trains, regional blenders with hydrotreating capabilities, and narrow-cut purification specialists serving semiconductor and pharmaceutical end-uses. Consolidation pressures concentrate in European distribution as REACH registration costs rise, while Asian battery sector expansion attracts new purification capacity investments. M&A activity targets hydrotreater asset access, and strategic partnerships between refiners and battery material producers are locking in long-term hexane offtake.
Among integrated majors, ExxonMobil Corporation and Shell plc anchor the refinery-integrated tier with geographic diversification across North American and Asian supply points. Haltermann Carless Group GmbH exemplifies the narrow-cut specialist archetype, occupying a position where evaporation profile precision determines adhesive bond performance and commands premium positioning. These three represent distinct competitive vectors: feedstock security at scale, global logistics integration, and specification-driven purification expertise.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Phillips 66 |
| SK Geocentric Co., Ltd. |
| Calumet, Inc. |
| TotalEnergies |
| BASF |
| Chevron Phillips Chemical Company LLC |
| Haltermann Carless Group GmbH |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between battery material producers and hexane suppliers lock in both supply access and price visibility, insulating pharmaceutical-grade volumes from spot-market volatility while compressing margins for traders excluded from these arrangements. EPA NESHAP compliance costs and REACH registration burdens feed directly into contract premia, stratifying the market between integrated refiners with captive hydrotreater capacity and distributors exposed to feedstock volatility.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure across European mineral spirits distribution, forcing three-tier pricing stratification across premium low-aromatic, standard hydrotreated, and economy high-aromatic grades. Certification grade and volume scale drive price differentiation, with pharmaceutical-grade hexane commanding substantial premia over paint-thinning mineral spirits. Cost compression in standard grades is intensifying because waterborne coating substitution in California and New York eliminates hydrocarbon demand entirely. DIY construction channels exhibit highest price sensitivity, while semiconductor adhesive solvent buyers prioritize residue specifications over unit cost.
Supply Chain Analysis
Port congestion on Singapore-Japan trade lanes elevates inbound logistics costs for specialty hexane shipments, amplifying delivered-price volatility for electronics assemblers in Taiwan and Malaysia. Production gravity centers on Singapore, the United States, and Germany, with raw material dependencies on paraffinic base stocks from Gulf Coast refiners, naphtha feedstocks from Yangtze River Delta crackers, and Fischer-Tropsch synthetic streams seeking EU carbon border preferential treatment. Single-source vulnerability concentrates at Shell's Pulau Bukom complex on Jurong Island, where operational disruptions cascade through Asia-Pacific pharmaceutical supply chains. Distribution runs through direct sales relationships for battery and semiconductor end-users, with wholesale channels retaining construction and automotive refinishing volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electrode manufacturing specifications are functioning as a platform standard, with sub-50 ppm sulfur hexane requirements creating interoperability lock-in that advantages qualified suppliers and excludes re-packagers from premium segments.
For Market Incumbents: Fortify hydrotreater asset control through backward integration into catalyst supply relationships and capacity expansion in South Korea's Gyeonggi Province to serve local battery producers. Waterborne coating substitution in North American architectural paint segments threatens mineral spirits volume, making pharmaceutical-grade certification investments the priority lever for margin defense.
For New Entrants and Emerging Players: USP/NF hexane certification fast-track programs offer entry into battery electrode supply chains previously closed to unqualified suppliers, with India's PLI scheme for domestic cell production representing the most penetrable geography. Target adhesive solvent applications in Taiwan and Malaysia where batch-level traceability requirements disadvantage traders, deploying direct sales teams with certificates of analysis capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a specification-intensification phase that favors narrow-cut purification specialists with existing pharmaceutical-grade infrastructure over commodity mineral spirits distributors. Long-term viability over the next decade rests on positioning for Fischer-Tropsch synthetic aliphatics with verified low-carbon intensity as EU Green Deal carbon border adjustments reshape competitive economics. The signal to watch is battery manufacturer qualification protocol evolution, where sulfur thresholds and stability documentation timelines serve as inflection indicators for supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrotreater Assets | Captive desulfurization capacity secures pharmaceutical-grade hexane supply for battery electrode manufacturers. |
| Long-term Supply Agreement with Battery Producers | Locked offtake volumes insulate suppliers from paint-sector cyclicality and spot-price volatility. |
| Green Manufacturing Transition to Fischer-Tropsch Feedstocks | Low-carbon intensity aliphatics receive preferential treatment under EU Green Deal carbon border adjustments. |
| Capacity Expansion in South Korea | Proximity to cathode slurry operations reduces logistics costs and meets MFDS certification timelines. |
| Joint Venture with Semiconductor Adhesive Formulators | Ultra-low residue specifications for die-attach applications command premium pricing multiples. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with refinery operations managers, battery material procurement leads, coatings formulators, and pharmaceutical solvent distributors; and secondary validation through customs trade data, ECHA registration databases, SEC 10-K filings, and ACC solvent market reports. Bottom-up triangulation across plant-level capacity disclosures and top-down reconciliation with end-use consumption patterns anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand evolution across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from segment-level growth rate blending, with hexane purity requirements for lithium-ion electrodes and REACH authorization cost burdens for European mineral spirits serving as primary forecast inputs.
Underlying assumptions cover regulatory stability in EPA NESHAP and REACH frameworks, with deviation risk concentrated in state-level VOC rule acceleration in California and New York, and battery sector sulfur threshold tightening beyond current sub-50 ppm specifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
North America Acetonitrile Market
Solvents
Propylene Glycol Ether Market
Solvents
Allyl Cyanide Market
Solvents
Fluorinated Solvents Market
Solvents
Ethane Market
Solvents
Hydrogen Cyanamide Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Diethanolamine (DEA) Market
Solvents
Saudi Arabia Methanol Market
Solvents
Chloromethane Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Europe Acetonitrile Market
Solvents
Phenylacetonitrile Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Solvent Green 7 Market