
 Bio-Based Polycarbonate Market | 2026-2036
Bio-Based Polycarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Polycarbonate Market Analytics
ASTM D6866 biogenic carbon certification is bifurcating the supplier landscape into qualified and non-qualified tiers. Covestro AG leverages its Leverkusen R&D campus to sustain pilot-scale production of isosorbide-derived polycarbonate grades. Teijin Limited anchors its position through backward integration into bio-based bisphenol precursors at its Matsuyama facility. Mitsubishi Chemical Group competes via proprietary high-purity dimethyl carbonate routes that reduce fossil carbon intensity in optical-grade sheets.
Bio-based polycarbonate denotes thermoplastic polymers synthesized from renewable feedstocks such as isosorbide or bio-derived bisphenol-A substitutes, typically achieving 25-75% biogenic carbon content per ASTM D6866 while retaining optical clarity above 90% light transmission and Vicat softening points of 145-160°C for engineering applications. The material serves as a drop-in replacement for conventional polycarbonate in transparent structural components, medical device housings, and lightweight automotive glazing where petrochemical attribution carries regulatory or brand risk. General Purpose grades occupy the volume base due to broad processability across injection molding and extrusion lines, while Optical Grade commands premium positioning in display diffuser films and LED lens arrays where birefringence control below 5 nm determines performance. High Heat formulations represent the fastest structural expansion as under-hood automotive specifications migrate toward 150°C continuous-use thresholds.
The EU Green Deal and REACH restrictions on bisphenol-A derivatives shape product formulation mandates across European value chains, while FDA biocompatibility requirements under ISO 10993 govern medical device adoption in the United States. Japan's METI has established preferential procurement guidelines for bio-based engineering plastics in public infrastructure projects, creating tiered market access conditions. Stakeholders must monitor feedstock cost parity milestones between bio-derived and fossil-derived bisphenol streams, as this crossover point will determine the pace of capacity conversion decisions across integrated resin producers.
Market Dynamics
Isosorbide-based bisphenol synthesis routes are compressing fossil-carbon intensity thresholds across engineering thermoplastic value chains, forcing integrated producers to reconfigure feedstock procurement before ASTM D6866 certification becomes a mandatory tender requirement.
Growth Catalysts
- EU Green Deal bisphenol-A substitution mandates:REACH restrictions on petroleum-derived precursors are compelling automotive OEMs and electronics assemblers to specify bio-based polycarbonate in transparent structural components.
- East Asian electronics manufacturing corridors:South Korean display panel producers and Chinese EV battery housing suppliers are concentrating procurement of optical-grade bio-based polycarbonate for LED lens arrays and thermal management enclosures.
- High Heat formulation specifications:Under-hood automotive applications migrating toward 150°C continuous-use thresholds are pulling demand for isosorbide-derived grades with Vicat softening points above 145°C.
Market Restraints
- Feedstock cost parity gaps:Bio-derived bisphenol streams remain structurally elevated versus fossil counterparts, delaying capacity conversion decisions at integrated resin producers.
- Supplier concentration in qualified tiers:ASTM D6866 biogenic carbon certification has bifurcated the landscape, concentrating qualified supply among backward-integrated players with captive precursor production.
- Optical-grade birefringence limitations:Bio-based polycarbonate grades struggle to achieve sub-5 nm birefringence control required for premium display diffuser films, constraining penetration in high-resolution panel applications.
Strategic Opportunities
- Japanese public infrastructure procurement:METI preferential procurement guidelines for bio-based engineering plastics are creating tiered market access conditions for qualified suppliers in municipal lighting and transportation glazing projects.
- Medical device biocompatibility positioning:FDA ISO 10993 compliance pathways offer white-space positioning for bio-based polycarbonate in transparent housings for diagnostic equipment and surgical instruments.
- Dimethyl carbonate process convergence:Proprietary high-purity DMC routes enabling fossil carbon intensity reduction in optical-grade sheets represent technology licensing opportunities for regional compounders.
Industry Challenges
- ASTM D6866 certification timeline compression:Accelerating tender requirements are outpacing laboratory testing capacity, creating bottlenecks for mid-scale producers seeking qualified tier status.
- Legacy injection molding line reconfiguration:Drop-in replacement claims require validation across variable temperature and pressure profiles, demanding technical service investment that strains commercial teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Polycarbonate Market |
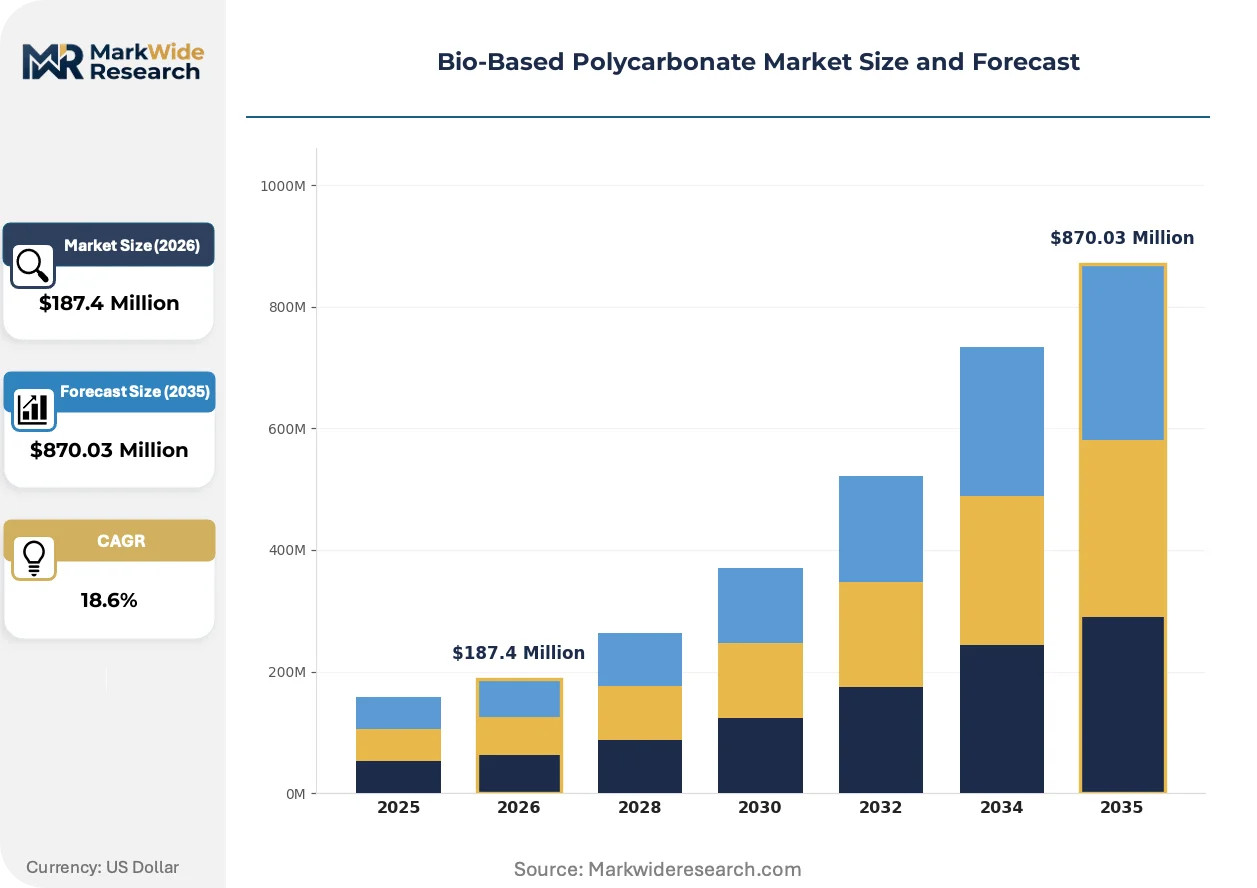
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Heat, Low Weight, Optical Grade Application: Automotive, Electronics, Medical Devices, Construction End User: Manufacturers, Designers, Retailers, Distributors Distribution Channel: Online, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Covestro AG, Teijin Limited, Mitsubishi Chemical Group, SABIC, Chimei Corporation, NatureWorks LLC, Evonik Industries AG, Asahi Kasei Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Polycarbonate Market Evolving Landscape
Feedstock molecular engineering and regulatory carbon accounting are converging to redefine competitive positioning in transparent thermoplastics, with certification-driven procurement now filtering supplier qualification before price negotiation begins.
High-purity isosorbide-derived bisphenol-A substitutes are displacing fossil-based feedstocks in optical-grade polycarbonate production. German automotive OEMs and Japanese lighting manufacturers are specifying these grades for interior panels and LED lens arrays at accelerating volumes. This displacement is compressing the qualified supplier base into tiers defined by backward-integrated precursor control and ASTM D6866 certification status.
REACH restrictions on bisphenol-A derivatives are mandating formulation reformulation across European value chains. Industrial consequence includes accelerated R&D allocation toward bio-based alternative verification and supply chain requalification. Medical device and food-contact segments are most affected, with manufacturers pre-emptively substituting petroleum-derived polycarbonate to avoid future compliance exposure.
Buyer specification of biogenic carbon content is fragmenting procurement into certified and uncertified supply tiers. Tier-one automotive and electronics assemblers are consolidating supplier panels around ASTM D6866-qualified producers, displacing traditional commodity distributors from premium specification flows. This concentration is most visible in German and South Korean manufacturing corridors where OEM sustainability scorecards directly influence contract renewal decisions.
Bio-Based Polycarbonate Market Segmentation
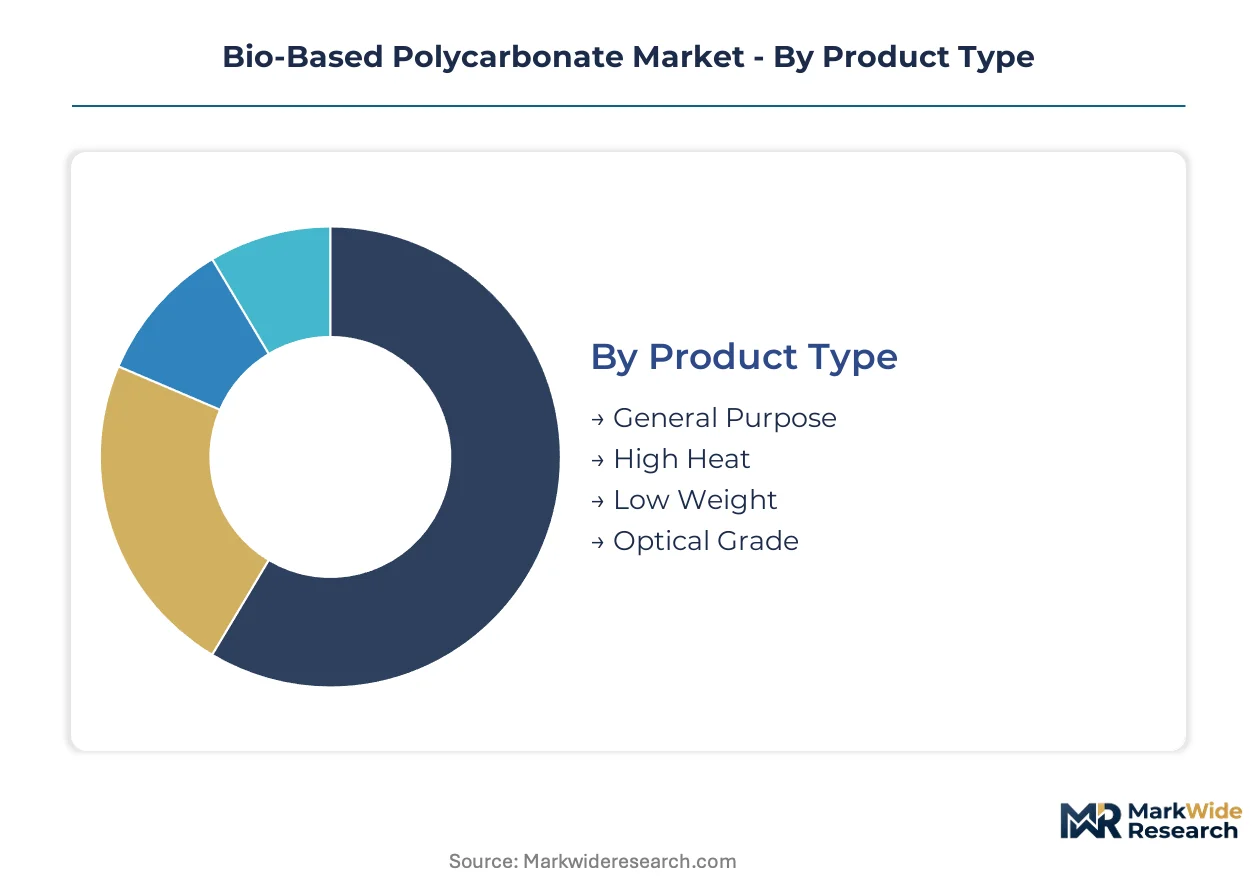
Segmentation in bio-based polycarbonate reveals how certification tiers, thermal performance thresholds, and end-use compliance requirements fragment procurement patterns across automotive glazing, electronics housings, and medical device markets.
Product Type:
General Purpose grades dominate domestic consumption in injection molding corridors, while Optical and High Heat variants drive export-led demand from German and Japanese production clusters.
- General Purpose:Broad-processability formulations achieving 25-50% biogenic carbon content serve as drop-in replacements across legacy extrusion and injection molding lines. Demand concentrates in Chinese EV battery housing suppliers seeking REACH-compliant alternatives without line reconfiguration.
- Optical Grade:High-purity grades with light transmission above 90% target LED lens arrays and display diffuser films. South Korean panel producers specify these for premium applications despite birefringence control challenges below 5 nm thresholds.
- High Heat:Isosorbide-derived formulations with Vicat softening points above 145°C address under-hood automotive specifications.
- Low Weight:Density-reduced grades for interior automotive panels and portable electronics enclosures.
General Purpose holds the largest share; momentum sits with High Heat as thermal specifications migrate toward 150°C continuous-use thresholds.
Application:
Cost tier stratification separates premium specification flows in medical and optical electronics from volume-driven automotive and construction procurement.
- Automotive:Interior panels, lighting lenses, and lightweight glazing applications. German OEMs expand procurement of isosorbide-derived grades for sustainability scorecard compliance.
- Electronics:Display housings, LED lens arrays, and thermal management enclosures. South Korean and Chinese manufacturers concentrate demand for ASTM D6866-certified optical grades.
- Medical Devices:Transparent housings for diagnostic equipment and surgical instruments. FDA ISO 10993 biocompatibility requirements govern adoption in United States markets.
- Construction:Municipal lighting and transportation glazing projects. Japanese METI preferential procurement guidelines create tiered access conditions for qualified suppliers.
Electronics commands premium pricing; medical devices are climbing the fastest as pre-emptive bisphenol-A substitution accelerates.
End User:
Customer type fragmentation concentrates specification authority among backward-integrated manufacturers while designers and retailers handle commoditized General Purpose flows.
- Manufacturers:Automotive OEMs, electronics assemblers, and medical device producers with direct ASTM D6866 certification requirements and sustainability scorecard mandates.
- Designers:Industrial design firms specifying material grades for client product development cycles.
- Retailers:Distributors of standard-grade polycarbonate for construction and consumer applications.
- Distributors:Commodity resin traders increasingly displaced from premium specification flows by qualified tier consolidation.
Manufacturers hold the largest share; momentum sits with designers as early-stage material selection increasingly predetermines certification compliance.
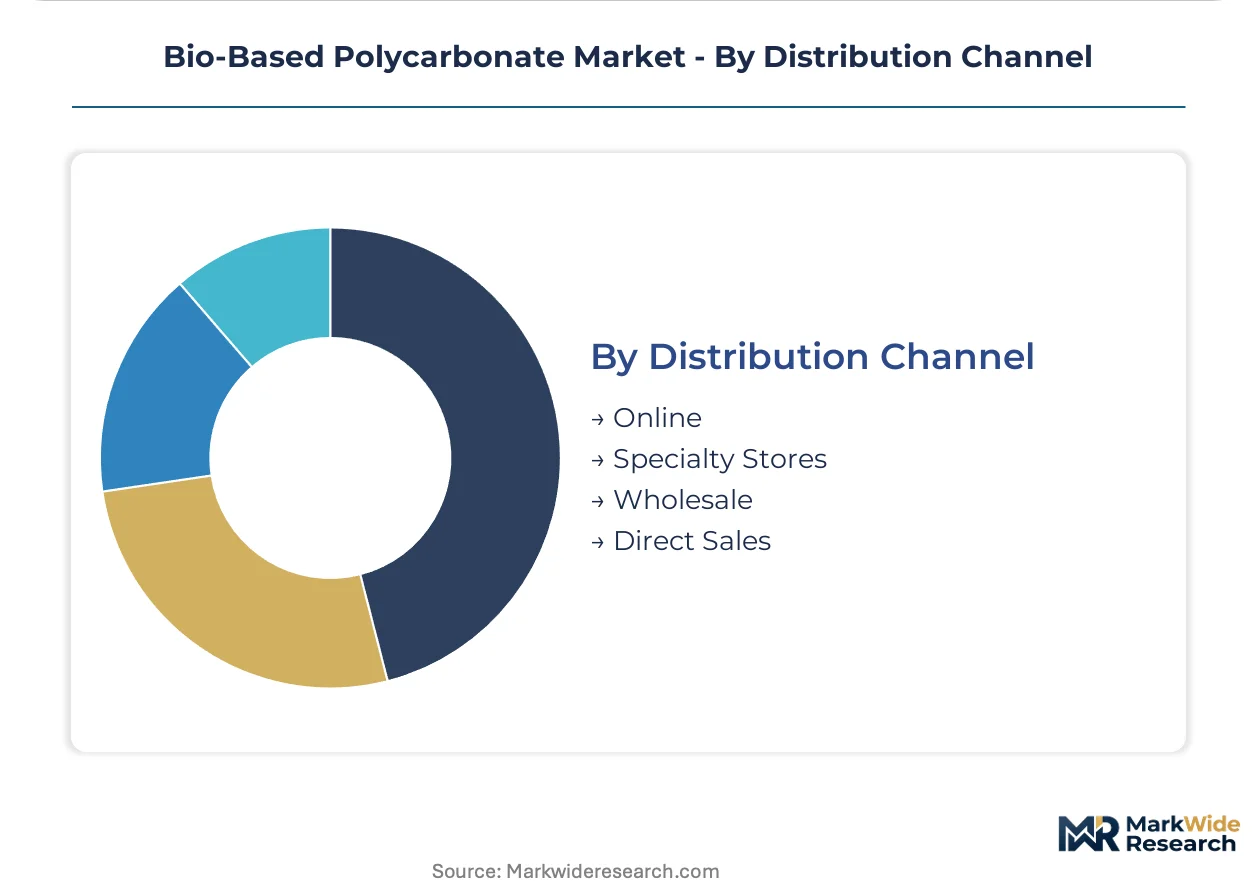
Distribution Channel:
Supply concentration in qualified producer tiers reshapes channel economics, with direct sales capturing premium specifications and online platforms absorbing commoditized General Purpose volume.
- Direct Sales:Long-term contracts between integrated resin producers and tier-one automotive and electronics assemblers. ASTM D6866 certification documentation flows through these channels exclusively.
- Specialty Stores:Technical distributors serving medical device and optical electronics manufacturers with ISO 10993 and birefringence compliance verification.
- Wholesale:Volume distributors of General Purpose grades for construction and consumer applications with less stringent certification requirements.
- Online:E-procurement platforms for standard grades where price transparency outweighs technical service requirements.
Direct Sales holds the largest share; momentum sits with Specialty Stores as medical and optical specifications demand verified compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal incentives and Japan's METI procurement guidelines are redrawing procurement maps for bio-based polycarbonate, concentrating qualified supply around specific industrial corridors with backward-integrated precursor capabilities.
Germany
Automotive OEMs in Stuttgart and Munich corridors specify isosorbide-derived grades for interior panels and lighting lenses. REACH restrictions on bisphenol-A derivatives compel formulation reformulation across Tier-1 supplier networks. Covestro's Leverkusen R&D campus anchors pilot-scale production serving German OEM sustainability scorecards.
Japan
METI preferential procurement guidelines for bio-based engineering plastics create tiered market access in municipal lighting and transportation glazing. Teijin's Matsuyama facility backward-integrates into bio-based bisphenol precursors. Chubu and Kansai manufacturing belts concentrate optical-grade demand from LED lens array producers.
South Korea
Display panel producers in Gyeonggi Province specify ASTM D6866-certified optical grades despite birefringence control challenges below 5 nm thresholds. The country's national chemical regulator enforces biogenic carbon disclosure in public tenders. Seoul-Incheon electronics corridors concentrate procurement for thermal management enclosures.
China
EV battery housing suppliers in Jiangsu and Zhejiang provinces seek REACH-compliant General Purpose grades without line reconfiguration. Dual carbon goals accelerate substitution mandates in state-owned automotive procurement. Yangtze River Delta manufacturing clusters absorb volume flows from qualified tier producers.
United States
FDA ISO 10993 biocompatibility requirements govern medical device adoption in transparent housings for diagnostic equipment. EPA frameworks on sustainable chemistry influence federal procurement preferences. Midwest medical device manufacturing corridors and Texas-based energy infrastructure projects drive specification authority.
Bio-Based Polycarbonate Market Competitive Landscape
Player mix skews toward backward-integrated chemical conglomerates with captive precursor production. ASTM D6866 certification bifurcation has compressed the qualified tier to a handful of integrated producers. Two strategic archetypes dominate: European-Japanese conglomerates with R&D campus leverage, and Asian diversified chemical groups with high-purity process routes. Competitive moves center on capacity conversion decisions at existing polycarbonate assets and technology licensing of dimethyl carbonate process innovations.
Within the backward-integrated tier, Covestro AG and Teijin Limited exemplify archetypes built on precursor control and certification authority. Covestro's German corporate structure positions it within European regulatory orbits, while Teijin's Japanese limited company format anchors Asia-Pacific procurement networks. Mitsubishi Chemical Group occupies a position bridging optical-grade specialization with proprietary high-purity process routes. These three entities represent the concentration of qualified supply capable of serving tier-one automotive and electronics assembler requirements.
| Leading Market Players |
|---|
| Covestro AG |
| Teijin Limited |
| Mitsubishi Chemical Group |
| SABIC |
| Chimei Corporation |
| NatureWorks LLC |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for isosorbide-derived feedstocks concentrate pricing power among backward-integrated producers with captive precursor production, while spot-market buyers face widening spreads between ASTM D6866-certified and uncertified supply tiers.
Pricing Analysis
Certification level under ASTM D6866 creates the primary spread between qualified and non-qualified supply tiers. Three-tier pricing structure across premium optical grades, standard engineering grades, and commoditized General Purpose formulations dominates contract negotiations. Cost compression in General Purpose tiers is intensifying because Chinese EV battery housing suppliers are consolidating procurement volumes. Medical device manufacturers show least price sensitivity due to FDA ISO 10993 compliance requirements that lock in qualified suppliers.
Supply Chain Analysis
Port congestion on Rotterdam-Singapore trade lanes elevates inbound logistics costs for European compounders sourcing bio-derived bisphenol precursors. Supply concentrates in Germany, Japan, and South Korea where integrated producers control isosorbide conversion capabilities. The chain draws from agricultural feedstock suppliers for sorbitol-isosorbide pathways and from petrochemical channels for dimethyl carbonate co-feeds. Single-source vulnerability in high-purity optical-grade resin exposes display panel producers to allocation risk. Distribution runs through direct sales channels for tier-one automotive and electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for injection molding line validation and certification documentation support are expanding faster than resin volume, creating recurring-revenue layers that outperform hardware margins.
For Market Incumbents: Consolidate supplier panel positions by accelerating ASTM D6866 certification timelines before tender requirements compress testing capacity. Deepen backward integration into bio-based bisphenol precursors at Leverkusen and Matsuyama-scale facilities to defend against emerging Asian compounders with high-purity DMC process licensing. For New Entrants and Emerging Players: Differentiate on medical device biocompatibility positioning where FDA ISO 10993 compliance creates white-space barriers for incumbent commodity producers. Target United States Midwest manufacturing corridors for transparent diagnostic housings, leveraging specialty store distribution channels that demand verified compliance documentation rather than volume scale. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized polycarbonate assets and stranded precursor capabilities. Long-term viability hinges on feedstock cost parity milestones between bio-derived and fossil bisphenol streams. Watch for capacity conversion announcements at integrated resin producers as the inflection signal for qualified supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive isosorbide production at Teijin's Matsuyama facility secures ASTM D6866 certification authority. |
| Green Manufacturing Transition | High-purity DMC routes at Mitsubishi Chemical reduce fossil carbon intensity in optical-grade sheets. |
| Long-term Supply Agreement | German automotive OEMs lock in isosorbide-derived grades for sustainability scorecard compliance. |
| Joint Venture | East Asian electronics corridors partner with qualified producers for thermal management enclosure supply. |
| Capacity Expansion | Pilot-scale production at Covestro's Leverkusen R&D campus anchors European qualified supply. |
Research Methodology
Desk research of customs trade data, SEC filings from integrated chemical producers, and REACH regulatory databases preceded structured interviews with procurement leads at automotive OEMs, technical R&D directors at resin compounders, plant managers at precursor facilities, and distribution channel partners. Bottom-up volume estimates from grade-level production data triangulated against top-down demand aggregation across end-use applications.
Variance decomposition across product type, application, thermal performance tier, and regional production hub segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted substitution curves modeling petroleum-to-bio-based feedstock conversion rates. Forecast inputs incorporated EU Green Deal implementation timelines and METI procurement guideline enforcement patterns.
Material uncertainties — feedstock cost parity crossover timing, ASTM D6866 certification capacity bottlenecks, and birefringence control breakthroughs in optical grades — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as REACH restriction expansion and dual carbon goal acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market