
 China Engineering Plastics Market | 2026-2036
China Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
China Engineering Plastics Market Outlook
The domestic supply chain is rewriting procurement patterns across China's engineering plastics sector. Sinopec leverages its integrated refinery-polymer operations to dominate bulk nylon and polycarbonate feedstock supply. Kingfa specializes in modified polypropylene compounds for automotive lightweighting programs. BASF sustains premium positioning through localized compounding facilities serving electrical insulation demand.
Engineering plastics encompass thermoplastic polymers engineered to withstand mechanical stress, thermal loads, and chemical exposure beyond commodity plastics, with polycarbonate achieving impact strength exceeding 800 J/m and continuous service temperatures from 120°C to 150°C depending on grade and filler content. These materials serve as metal replacements in precision components requiring dimensional stability under cyclic loading. Polycarbonate and nylon lead product type revenue contribution due to entrenched automotive glazing and under-hood applications. Molded parts capture the dominant form share as injection molding enables complex geometries for medical devices and electrical housings. Automotive components anchor application demand though electrical insulation represents the fastest-expanding margin pool.
MIIT enforces GB standards governing flame retardancy and recyclability thresholds for engineering plastics deployed in electrical and automotive applications. SAMR oversees market access compliance through product certification schemes that filter substandard imports. The dual carbon goals framework is forcing producers to document lifecycle emissions and shift toward bio-based feedstock pathways. Stakeholders must track evolving MEE enforcement intensity around chemical sector carbon intensity benchmarks.
Market Dynamics
Automotive electrification is compressing material qualification cycles and forcing compounders to certify flame-retardant grades under accelerated timelines. MIIT's tightened GB standards for battery housings and thermal management systems are reshaping supplier qualification protocols across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- New Energy Vehicle Penetration:Battery enclosure demand for nylon 66 and PBT compounds is pulling capacity expansion from domestic polymer producers. MIIT production quotas for NEVs mandate lightweighting solutions that displace metal brackets and cooling lines.
- Dual Carbon Goals Framework:MEE enforcement of lifecycle carbon accounting is accelerating bio-based feedstock adoption. Producers documenting Scope 3 emissions gain preferential access to state procurement channels for infrastructure projects.
- 5G Base Station Deployment:Low-Dk/Df LCP and PPS compounds for high-frequency connectors are seeing qualification surges. Ministry of Industry and Information Technology infrastructure tenders specify halogen-free flame retardancy thresholds.
Market Restraints
- Caprolactam Supply Concentration:Over 60 percent of domestic nylon 6 feedstock flows from Sinopec's integrated refinery operations. Disruptions at Cangzhou or Maoming facilities transmit directly to modified compounders in Zhejiang and Jiangsu provinces.
- Bisphenol A Import Dependency:Polycarbonate producers remain exposed to Middle Eastern and Korean feedstock pricing volatility. Tariff fluctuations and shipping bottlenecks compress blending margins for optical-grade distributors.
- High-Temperature Performance Ceiling:Standard PPS and PEEK grades face thermal limitations above 260°C in electric motor housings. Ceramic-filled alternatives carry 3-4x material cost penalties that freeze adoption in mass-market vehicle platforms.
Strategic Opportunities
- Western China Manufacturing Relocation:Chongqing and Chengdu automotive clusters are underpenetrated by localized compounding capacity. Producers establishing captive facilities in Sichuan gain logistics advantages for BYD and Changan supply chains.
- Chemical Recycling Infrastructure:Pyrolysis-based feedstock recovery for engineering plastics remains nascent. Early movers partnering with MEE-licensed waste treatment operators can secure circular material certifications ahead of mandatory recycled content quotas.
- Medical Device Reshoring:COVID-era supply vulnerabilities are driving surgical instrument and diagnostic housing production back to domestic molders. US FDA and EU MDR compliance capabilities differentiate premium compounders in this migration.
Industry Challenges
- Color-Matching Technical Talent Scarcity:Automotive OEMs demand batch-to-batch Delta E consistency below 0.5 for interior trim applications. Compounders struggle to recruit spectrophotometry specialists and masterbatch formulation chemists in secondary cities.
- Multi-Standard Certification Burden:Simultaneous GB, UL, and OEM-specific qualification timelines stretch 18-24 months for new flame-retardant grades. Testing backlog at SAMR-accredited laboratories creates first-mover disadvantages for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Engineering Plastics Market |
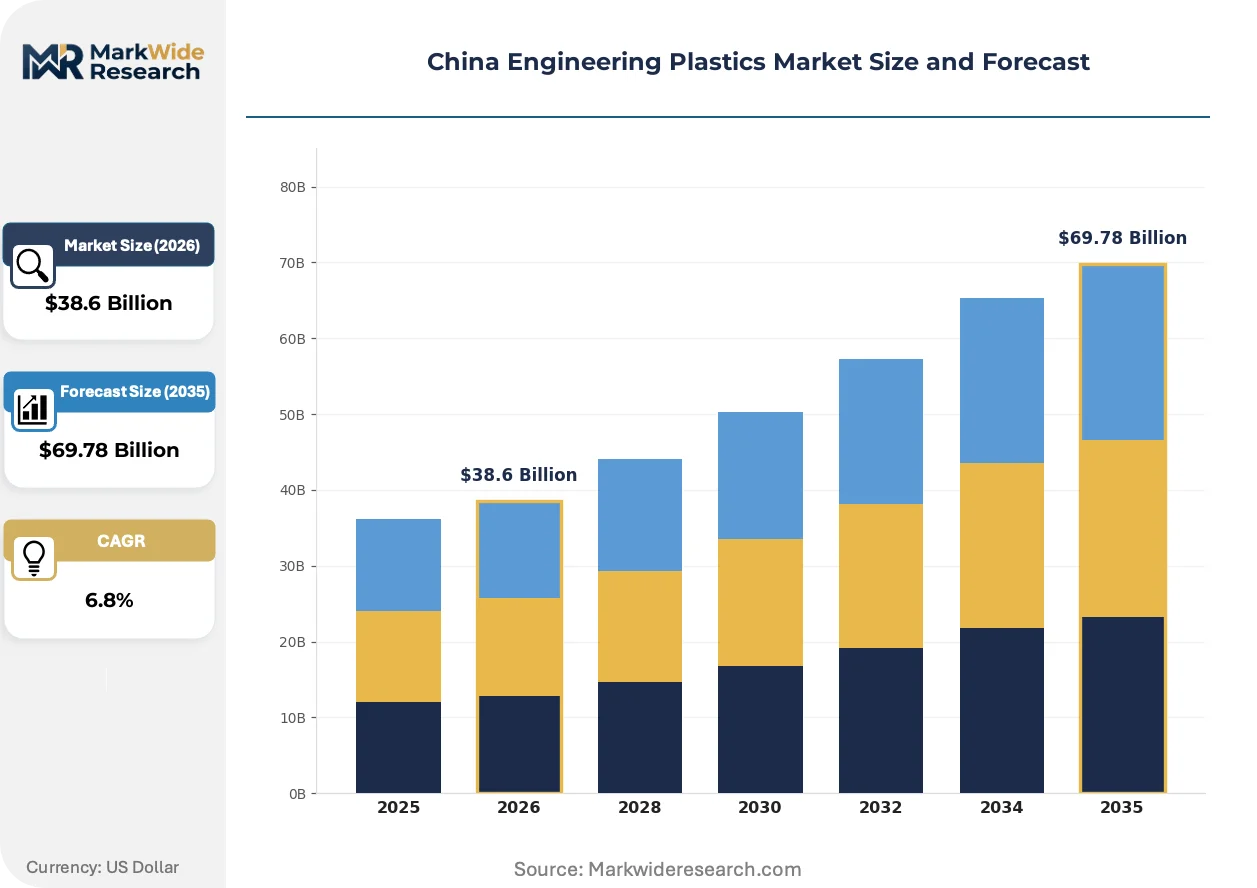
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, Polypropylene, Polyethylene Terephthalate End User: Automotive, Aerospace, Electrical, Consumer Goods Form: Sheets, Films, Molded Parts, Fibers Application: Automotive Components, Electrical Insulation, Packaging, Medical Devices |
| Companies Covered | China Petroleum & Chemical Corporation, PetroChina Company Limited, CHIMEI, Covestro AG, Formosa Plastics Group, BASF, LG Chem, Kingfa, Sinopec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Engineering Plastics Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine performance benchmarks across China's engineering plastics value chain. Three developments are actively reshaping competitive positioning and investment priorities.
High-heat polymer formulations are migrating from aerospace heritage applications into mainstream electric vehicle powertrains. PEEK and PPA compounds previously reserved for aircraft engine components now qualify for 800V battery busbar insulation. Domestic automakers including NIO and XPeng are compressing traditional 36-month material validation cycles into 14-month programs to match platform launch velocities.
MIIT's updated GB/T 2408 flame retardancy standards are eliminating halogenated additive packages from electrical enclosure specifications. Compounders must reformulate with phosphorus-nitrogen intumescent systems or mineral hydrates to maintain market access. The transition is most acute in Guangdong province, where SAMR enforcement audits have intensified for export-oriented molding facilities serving European appliance OEMs.
Consolidated procurement by tier-one automotive suppliers is displacing fragmented distributor networks for engineering plastics. CATL and BYD's battery divisions now negotiate direct master service agreements with Sinopec and Kingfa for specified resin grades. This concentration is most visible in Ningbo and Suzhou, where former trading houses are restructuring as technical service providers or exiting commodity nylon distribution entirely.
China Engineering Plastics Market Segmentation
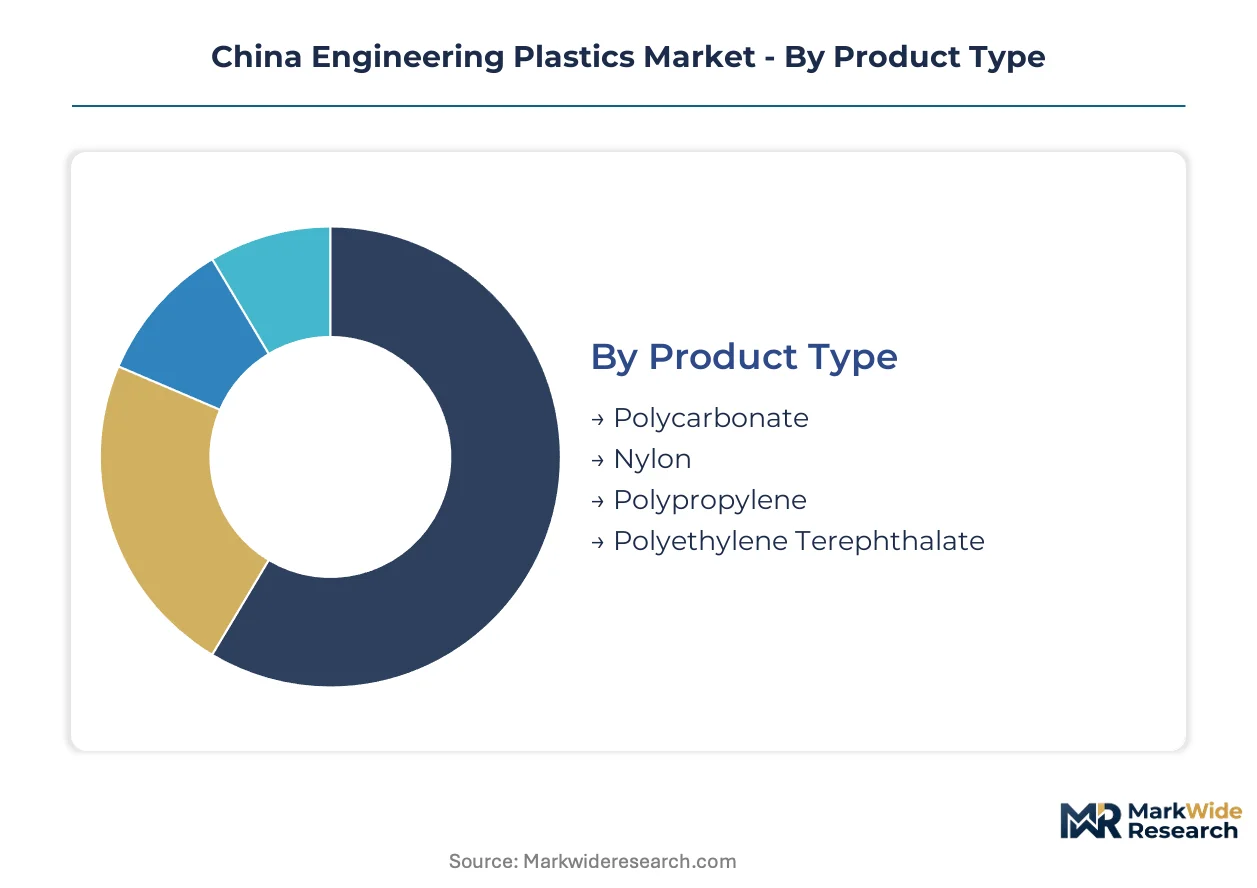
Engineering plastics segmentation in China reflects divergent technical requirements across automotive electrification, 5G infrastructure buildout, and medical device reshoring. Each dimension—product chemistry, end-use industry, physical form, and functional application—carries distinct qualification protocols and margin structures that reshape supplier positioning.
Product Type:
Material selection spans impact-resistant glazing polymers to high-temperature aromatic compounds, with cost-performance trade-offs determining adoption depth.
- Polycarbonate:Amorphous thermoplastic delivering impact resistance exceeding 800 J/m and optical clarity for headlamp lenses and instrument cluster covers. Demand concentrates in Ningbo automotive glazing clusters where BYD and Geely specify optical-grade resins with UV-stabilized coextrusion layers.
- Nylon:Semicrystalline polyamide family spanning aliphatic grades (nylon 6, 66) to high-heat aromatic variants (PPA). Under-hood applications in Yangtze River Delta EV battery plants drive specification for hydrolysis-resistant compounds with continuous service temperatures above 150°C.
- Polypropylene:Lightweight olefin modified with mineral fillers or elastomer blends for interior trim and bumper fascia. Kingfa compounds dominate domestic automotive lightweighting programs targeting metal replacement in seat structures.
- Polyethylene Terephthalate:Crystalline polyester engineered for dimensional stability in electrical connectors and relay housings. Reinforced grades with glass fiber loadings serve high-voltage isolation barriers in charging infrastructure.
Established volume favors polycarbonate in legacy automotive glazing; emerging adoption favors nylon in thermal management systems.
End User:
Customer industries impose divergent certification burdens, with automotive and electrical sectors driving the steepest specification escalation.
- Automotive:Dominant demand source spanning interior, exterior, and powertrain applications. MIIT NEV production quotas force accelerated material qualification cycles as OEMs compress 36-month validation timelines to 14 months for battery enclosure platforms.
- Aerospace:Niche but high-margin segment requiring flame-retardant PEEK and PPS compounds for cabin interior components. Certification to CCAR-25 airworthiness standards limits qualified domestic compounders to state-owned aviation material suppliers.
- Electrical:Fastest-expanding margin pool driven by 5G base station deployment and high-voltage connector demand. Ministry of Industry and Information Technology tenders specify halogen-free GB/T 2408 compliance that eliminates legacy brominated formulations.
- Consumer Goods:Price-sensitive applications in appliance housings and personal electronics. SAMR market access audits in Guangdong export corridors intensify compliance scrutiny for European-bound shipments.
Procurement concentration favors automotive direct agreements; margin expansion favors electrical infrastructure qualification.
Form:
Physical presentation determines processing economics and supply chain configuration from resin producer to molder.
- Molded Parts:Injection-molded components capture dominant value share through complex geometry realization for medical device housings and electrical enclosures. Suzhou and Shenzhen mold clusters specialize in multi-cavity tooling for high-volume consumer electronics.
- Sheets:Extruded flat products for thermoformed automotive interior panels and aircraft cabin components. Optical-grade polycarbonate sheets require cleanroom extrusion lines concentrated in Jiangsu province.
- Films:Thin-gauge products for flexible printed circuit substrates and battery separator coatings. Biaxially oriented nylon films serve high-barrier food packaging adjacent to engineering plastics applications.
- Fibers:High-tenacity filaments for industrial reinforcement and technical textiles. Aramid and PPS fiber grades penetrate filter media and composite preform markets.
Processing value capture favors molded parts complexity; specialty margin favors films in 5G substrate applications.
Application:
Functional use cases determine performance thresholds from mechanical load-bearing to dielectric isolation.
- Automotive Components:Structural and aesthetic parts spanning powertrain mounts to illuminated badges. Thermal management module demand in 800V architectures pulls high-heat PPA compounds into battery busbar insulation.
- Electrical Insulation:Dielectric materials for connectors, relays, and motor housings. Low-Dk/Df LCP formulations for millimeter-wave 5G antennas represent the steepest technology trajectory in the segment.
- Packaging:High-barrier containers and transport trays for semiconductor and pharmaceutical logistics. ESD-dissipative compounds protect sensitive electronic components during Yangtze River Delta distribution.
- Medical Devices:Surgical instruments, diagnostic housings, and drug delivery components. COVID-era supply vulnerabilities accelerate reshoring of FDA-registered molding capacity to domestic facilities.
Volume foundation anchors automotive; technology premium concentrates in electrical insulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Yangtze River Delta commands a premium over interior provinces due to logistics density and qualification proximity. Sichuan-Chongqing clusters trade margin for volume as automakers relocate assembly capacity westward. Regional divergence in MIIT enforcement intensity creates arbitrage opportunities for compounders with multi-site certification.
Yangtze River Delta
Ningbo and Suzhou concentrate polycarbonate glazing demand from BYD and Geely while battery enclosure programs pull nylon 66 compounds. MIIT's tightened GB standards for thermal management systems force 14-month qualification cycles versus traditional 36-month timelines. Compounders in Zhejiang province face SAMR audit intensity that filters substandard imports from Korean feedstock distributors.
Pearl River Delta
Guangdong's export-oriented molding corridors drive halogen-free flame retardant adoption for European appliance OEMs. SAMR enforcement audits intensified through 2024 under MEE's dual carbon goals framework. Shenzhen and Dongguan clusters specialize in multi-cavity tooling for high-volume consumer electronics housings.
Sichuan-Chongqing
BYD and Changan supply chains anchor underpenetrated compounding demand in western China. Provincial industrial policy incentivizes captive resin facilities with tax preferences for NEV component localization. Chengdu automotive clusters lack localized high-heat PPA supply, forcing inbound logistics from Yangtze River Delta producers.
Beijing-Tianjin-Hebei
State procurement channels for infrastructure projects concentrate in the capital region under MEE lifecycle carbon accounting mandates. Producers documenting Scope 3 emissions gain preferential access to rail and 5G base station tenders. Tianjin port facilities handle bisphenol A import flows that supply polycarbonate blending operations.
Shandong Peninsula
Petrochemical feedstock integration dominates with Sinopec's refinery-polymer operations supplying caprolactam to modified compounders. Cangzhou facility disruptions transmit directly to Zhejiang and Jiangsu downstream processors. Qingdao molding clusters serve medical device reshoring programs with FDA-registered capacity.
China Engineering Plastics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing formulation premiums. The vendor base stratifies across three tiers: state-owned petrochemical giants with captive feedstock, foreign compounders with localized technical service, and domestic modifiers with automotive lightweighting specialization. Competitive moves concentrate on backward integration into refinery operations and geographic expansion into underpenetrated western clusters. M&A activity targets spectrophotometry talent and masterbatch formulation capabilities.
Among state-owned petrochemical enterprises, China Petroleum & Chemical Corporation and PetroChina Company Limited exemplify feedstock-integrated archetypes with refinery-polymer operations spanning caprolactam and bisphenol A supply. Covestro AG and BASF occupy positions as foreign technical compounders with localized facilities serving electrical insulation demand. Kingfa represents the domestic automotive modifier archetype with modified polypropylene specialization for metal replacement programs. These three groupings anchor competitive dynamics as procurement concentrates through direct master service agreements.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| PetroChina Company Limited |
| CHIMEI |
| Covestro AG |
| Formosa Plastics Group |
| BASF |
| LG Chem |
| Kingfa |
| Sinopec |
| Others |
Value Chain & Pricing Dynamics
Sinopec's integrated refinery-polymer operations at Cangzhou and Maoming concentrate caprolactam supply for over sixty percent of domestic nylon 6 production. This upstream concentration funnels margin capture toward bulk feedstock producers while compounders in Zhejiang and Jiangsu provinces absorb price volatility transmission.
Pricing Analysis
Configured-to-order pricing for flame-retardant and color-matched compounds commands spreads of thirty to fifty percent above standard resin grades. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and volume scale, with UL-listed electrical grades sitting at the premium tier and undifferentiated commodity nylon at the base. Cost compression in optical-grade polycarbonate is intensifying because Middle Eastern and Korean bisphenol A feedstock faces shipping bottlenecks and tariff fluctuations. Tier-one automotive OEMs show least price sensitivity for battery enclosure compounds, while appliance exporters to Europe absorb margin pressure most acutely.
Supply Chain Analysis
Extended payment terms of ninety to one hundred twenty days from CATL and BYD battery divisions strain working capital for mid-tier compounders. Geographic supply concentration centers on China for modified compounds, South Korea for specialty PPS and LCP resins, and Germany for optical-grade polycarbonate technology. Raw material dependencies rest on caprolactam for nylon, bisphenol A for polycarbonate, and purified terephthalic acid for PBT compounds. Single-source vulnerability at Sinopec's Cangzhou facility poses structural risk to Yangtze River Delta processors. Distribution runs through direct master service agreements with tier-one automotive suppliers, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification and 5G infrastructure buildout fragment demand into specialized qualification niches that reward targeted capability investment over broad portfolio coverage.
For Market Incumbents: Pre-empt qualification backlog advantages by expanding SAMR-accredited laboratory partnerships to compress eighteen-month certification timelines for halogen-free flame-retardant grades. Secure backward integration into bio-based feedstock pathways ahead of MEE mandatory recycled content quotas. Defend against domestic automotive modifier encroachment by locking multi-year direct agreements with CATL and BYD battery divisions. For New Entrants and Emerging Players: Establish a beachhead in western China by building captive compounding capacity in Chengdu to serve BYD and Changan supply chains with localized high-heat PPA compounds. Target medical device reshoring programs in Qingdao where FDA-registered molding capacity differentiates premium compounders. Lead with technical service capabilities around color-matching and spectrophotometry to offset incumbent feedstock cost advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed domestic modifiers lacking refinery integration but holding automotive lightweighting qualifications. Long-term viability hinges on positioning for circular material certifications and bio-based feedstock transitions over a five-to-ten year window. Target compounders with MEE-licensed waste treatment partnerships for pyrolysis-based chemical recycling infrastructure. Watch MIIT enforcement intensity around GB/T 2408 flame retardancy standards as the inflection indicator for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock | MEE lifecycle carbon accounting mandates favor producers documenting Scope 3 emissions for state procurement access. |
| Capacity Expansion in Western China | Sichuan-Chongqing automotive clusters lack localized high-heat compound supply, creating logistics advantages for early movers. |
| Long-Term Supply Agreement with Battery OEMs | CATL and BYD direct master service agreements displace distributor networks and lock volume commitments. |
| Joint Venture with MEE-Licensed Waste Operators | Circular material certifications ahead of mandatory recycled content quotas secure regulatory positioning. |
| Acquisition of Spectrophotometry Talent | Automotive OEM Delta E consistency demands below 0.5 create scarcity premiums for color-matching specialists. |
Study Parameters
Desk research of MIIT regulatory filings, SAMR certification databases, customs trade records, and Sinopec operational disclosures preceded structured interviews with polymer plant managers, procurement leads at BYD and CATL battery divisions, technical R&D directors at domestic modifiers, and distribution channel partners in Ningbo and Suzhou. Bottom-up volume estimates from compounder capacity utilization and top-down demand triangulation from automotive production quotas and 5G base station deployment targets were cross-validated.
Assumptions around MIIT NEV production quota enforcement, MEE carbon intensity benchmark stringency, and GB standards adoption timelines were held fixed across scenarios while feedstock price volatility and western China manufacturing relocation velocity were stress-tested. Segmentation modeling spanned product chemistry grades, end-use industry qualification protocols, physical form processing economics, and functional application performance thresholds. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window.
Sensitivities concentrate around caprolactam supply disruptions at Sinopec facilities, bisphenol A import tariff fluctuations, and MIIT acceleration of material qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Semi-Crystalline Polymers Market