
 3D Printing Powder Market | 2026-2036
3D Printing Powder Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Powder Market Analysis
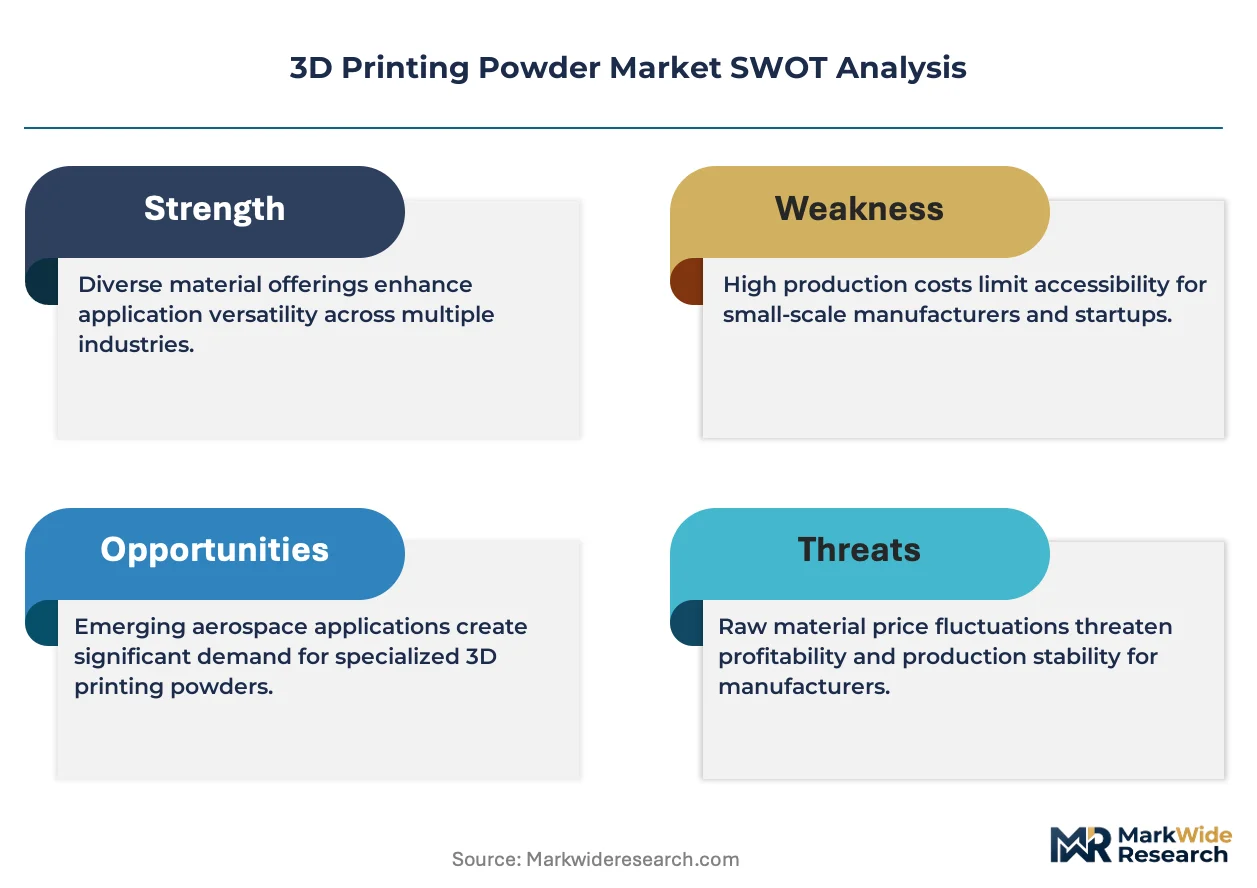
Layer-thickness control in multi-laser systems is narrowing the performance gap between conventionally machined and additively manufactured aerospace components. EOS GmbH leverages its installed base of metal laser sintering platforms to sustain service revenue across European aviation hubs. Sandvik AB anchors titanium powder supply through captive atomization assets in Sweden and North America. Höganäs AB differentiates via water-atomized steel grades optimized for binder jetting throughput.
3D printing powder comprises finely divided metallic, polymeric, ceramic, or composite feedstock engineered to specific particle size distributions, typically 15-45 microns for laser-based processes, enabling layer-by-layer consolidation into dense functional parts. Metal powder commands the dominant value share due to aerospace and medical qualification requirements, while polymer powder competes on prototyping velocity and lower equipment barriers. Selective laser sintering occupies the technology lead in installed capacity, though binder jetting is gaining structural traction for stainless steel serial production without thermal support structures.
FDA device regulations and EMA MDR frameworks govern powder traceability and biocompatibility for patient-contact implants, while REACH and OSHA exposure limits shape workplace handling standards and material substitution incentives. The EU AI Act and emerging quality certification protocols for autonomous process control will further tighten documentation requirements across the supply chain. Stakeholders must monitor evolving powder reuse guidelines and national stockpiling policies for critical alloying elements.
Market Dynamics
Multi-laser powder bed fusion is compressing qualification timelines for aerospace structural components, forcing incumbent suppliers to recertify legacy alloys under tightened EU F-Gas and REACH protocols.
Growth Catalysts
- Aerospace Repair Mandates:Airlines are expanding powder bed fusion adoption for turbine blade refurbishment, driven by FAA airworthiness directives demanding faster turnaround on critical engine components.
- REACH Material Certification:Stricter EU chemical registration requirements are accelerating qualified supplier consolidation, benefiting powder producers with captive atomization and in-house testing capabilities.
- German Industrial Clustering:Automotive suppliers in Bavaria and Baden-Württemberg are scaling binder jetting for stainless steel tooling, anchoring regional metal powder consumption.
Market Restraints
- Nickel Superalloy Feedstock Volatility:Price swings in cobalt and rhenium concentrates constrain margin predictability for turbine-grade powder producers.
- Swedish Supply Concentration:Captive titanium sponge-to-powder assets in Sandviken and North American satellite plants create single-source vulnerability for aerospace Tier-1s.
- Particle Size Distribution Limitations:Narrow 15-45 micron specifications for laser processes exclude broader atomized fractions, elevating scrap rates in gas atomization.
Strategic Opportunities
- Indian Medical Device Localization:CDSCO's phased MDR alignment and PLI scheme incentives create entry points for biocompatible titanium powder in orthopedic implant manufacturing.
- Copper-Alloy Thermal Management:Binder jetting of pure copper and chrome-zirconium grades is opening heat sink applications in power electronics and EV charging infrastructure.
- EU AI Act Process Control:Autonomous melt pool monitoring and real-time powder layer inspection will become mandatory documentation points, favoring sensor-integrated equipment vendors.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Shortages in computational thermodynamics and laser-matter interaction modeling slow process parameter optimization for new alloy introductions.
- Recertification Timeline Compression:FAA and EASA parallel qualification tracks for powder reuse protocols demand redundant testing budgets without guaranteed approval synchronization.
- Legacy ERP Integration Friction:Powder lot traceability requirements collide with existing MRO software architectures, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Powder Market |
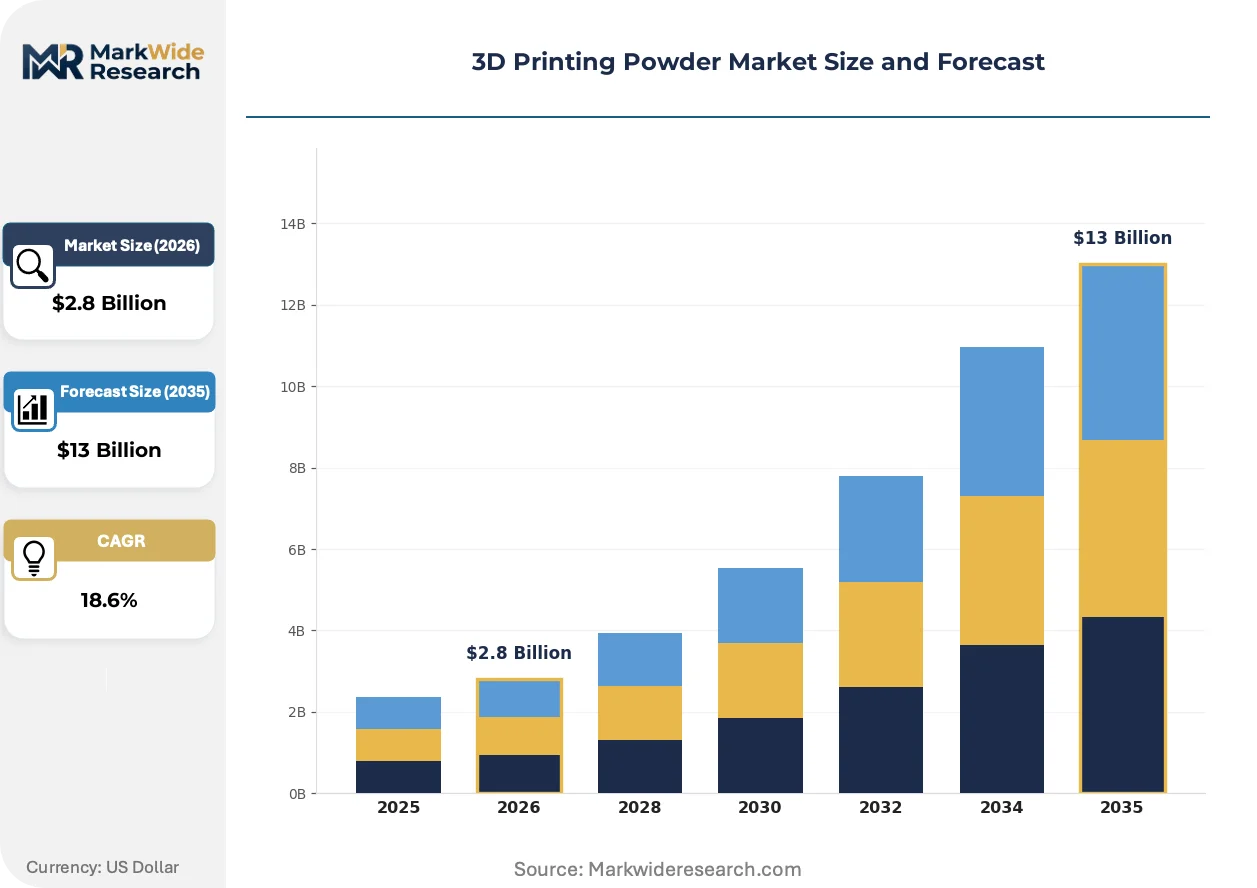
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal Powder, Polymer Powder, Ceramic Powder, Composite Powder Application: Aerospace Components, Medical Devices, Automotive Parts, Prototyping End User: Manufacturers, Research Institutions, Educational Institutes, Aerospace Firms Technology: Selective Laser Sintering, Fused Deposition Modeling, Binder Jetting, Stereolithography |
| Companies Covered | Sandvik AB, Arkema, BASF SE, EOS GmbH, Carpenter Technology Corporation, Höganäs AB, GKN Powder Metallurgy, Evonik Industries AG, ERASTEEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Powder Market Emerging Trajectories
Digital thread architectures are collapsing the boundary between powder production, part fabrication, and performance validation, enabling closed-loop quality assurance that was previously impractical at industrial scale.
Plasma rotating electrode atomization is virtualizing the traditional gas atomization supply chain for reactive alloys. Medical implant manufacturers in Switzerland and Japan are adopting PREP titanium for its superior sphericity and reduced satellite particles. This process is virtualizing inventory models by enabling just-in-time powder production adjacent to point-of-use manufacturing cells.
The EU AI Act's quality system requirements for autonomous manufacturing equipment are mandating algorithmic audit trails for melt pool monitoring systems. Powder bed fusion OEMs must now document training data provenance and model drift detection protocols. German aviation suppliers are responding by embedding edge-computing nodes directly into build chambers to satisfy real-time logging mandates.
Consignment powder inventory models are displacing traditional spot purchasing in high-volume aerospace programs. Tier-1 manufacturers in France and Italy now require suppliers to maintain buffer stocks at regional logistics hubs, transferring working capital burden upstream. This shift is most pronounced in nickel superalloy grades where lot-to-lot consistency requirements preclude multi-source blending.
3D Printing Powder Market Segmentation
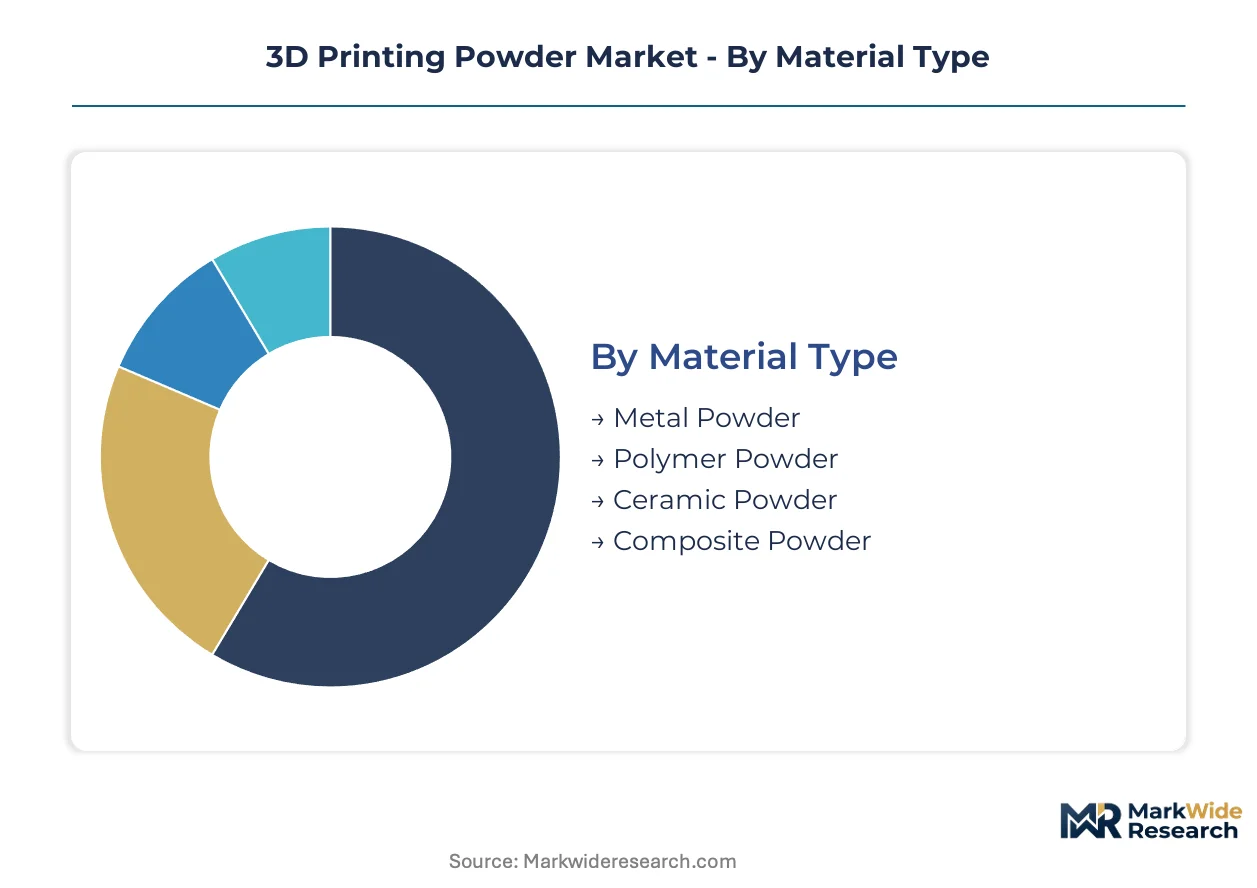
3D printing powder segmentation reflects divergent qualification burdens across material classes and the technology-specific particle engineering that locks suppliers into distinct value tiers. Material type and application segmentation together determine pricing power, with aerospace and medical end-uses commanding premium certification premiums over prototyping volumes.
Material Type:
Cost tier stratification separates qualified aerospace alloys from commodity prototyping feedstock, with atomization method and traceability documentation driving margin dispersion.
- Metal Powder:Nickel-based superalloys and titanium grades for turbine blades and orthopedic implants require vacuum induction melt gas atomization and lot-level chemistry certification. Demand concentrates in Germany and Sweden where EOS GmbH and Sandvik AB anchor captive atomization capacity for aviation Tier-1s facing tightened EU F-Gas and REACH protocols.
- Polymer Powder:Nylon 12 and TPU formulations dominate selective laser sintering workflows for functional prototyping and medical device housings. German automotive suppliers in Bavaria scale PA11 and PA12 consumption for tooling fixtures, exploiting lower equipment barriers and faster iteration cycles than metal alternatives.
- Ceramic Powder:Alumina and zirconia feedstock serves dental crown production and high-temperature insulator applications in Japan and Switzerland.
- Composite Powder:Carbon fiber-reinforced nylon and glass-filled polymers bridge stiffness and printability for drone airframes and robotic end-effectors.
Metal powder holds installed capacity. Polymer powder is rotating up the share rankings.
Application:
End-use maturity separates flight-qualified structural brackets from non-certified prototyping, with regulatory burden determining supplier qualification timelines and customer stickiness.
- Aerospace Components:Turbine blade repair and lightweight structural brackets demand powder bed fusion of Inconel 718 and Ti-6Al-4V with FAA and EASA airworthiness documentation. French and Italian Tier-1 manufacturers now mandate consignment inventory at regional hubs, transferring working capital burden to nickel superalloy suppliers.
- Medical Devices:Patient-contact implants require FDA and EMA MDR traceability with biocompatibility testing per ISO 10993. Swiss and Japanese orthopedic manufacturers adopt plasma rotating electrode atomization titanium for superior sphericity and reduced satellite particles in spinal fusion cages.
- Automotive Parts:Stainless steel tooling and aluminum heat exchangers exploit binder jetting throughput without thermal support structures in Baden-Württemberg supplier parks.
- Prototyping:Design validation and form-fit testing consume polymer and composite powders with minimal qualification overhead, concentrating in research institutions and educational institutes.
Aerospace components command premium pricing. Medical devices are climbing the fastest on regulatory tailwinds.
End User:
Customer type determines procurement sophistication, with manufacturers demanding consignment models and research institutions accepting spot purchasing with lower documentation burdens.
- Manufacturers:Serial production of aerospace brackets and medical implants requires lot traceability, powder reuse protocols, and ERP integration for quality system compliance.
- Research Institutions:Alloy development and process parameter studies consume experimental powder batches with flexible specifications and lower volume commitments.
- Educational Institutes:Workforce training and curriculum development drive polymer powder consumption for accessible equipment platforms.
- Aerospace Firms:In-house repair stations and additive manufacturing centers consolidate powder sourcing under long-term agreements with Sandvik AB and Höganäs AB for captive supply security.
Manufacturers anchor volume demand. Aerospace firms are expanding fastest on MRO insourcing.
Technology:
Process physics dictate particle size distribution requirements, with laser-based systems demanding narrow 15-45 micron fractions and binder jetting accommodating broader atomized feedstock.
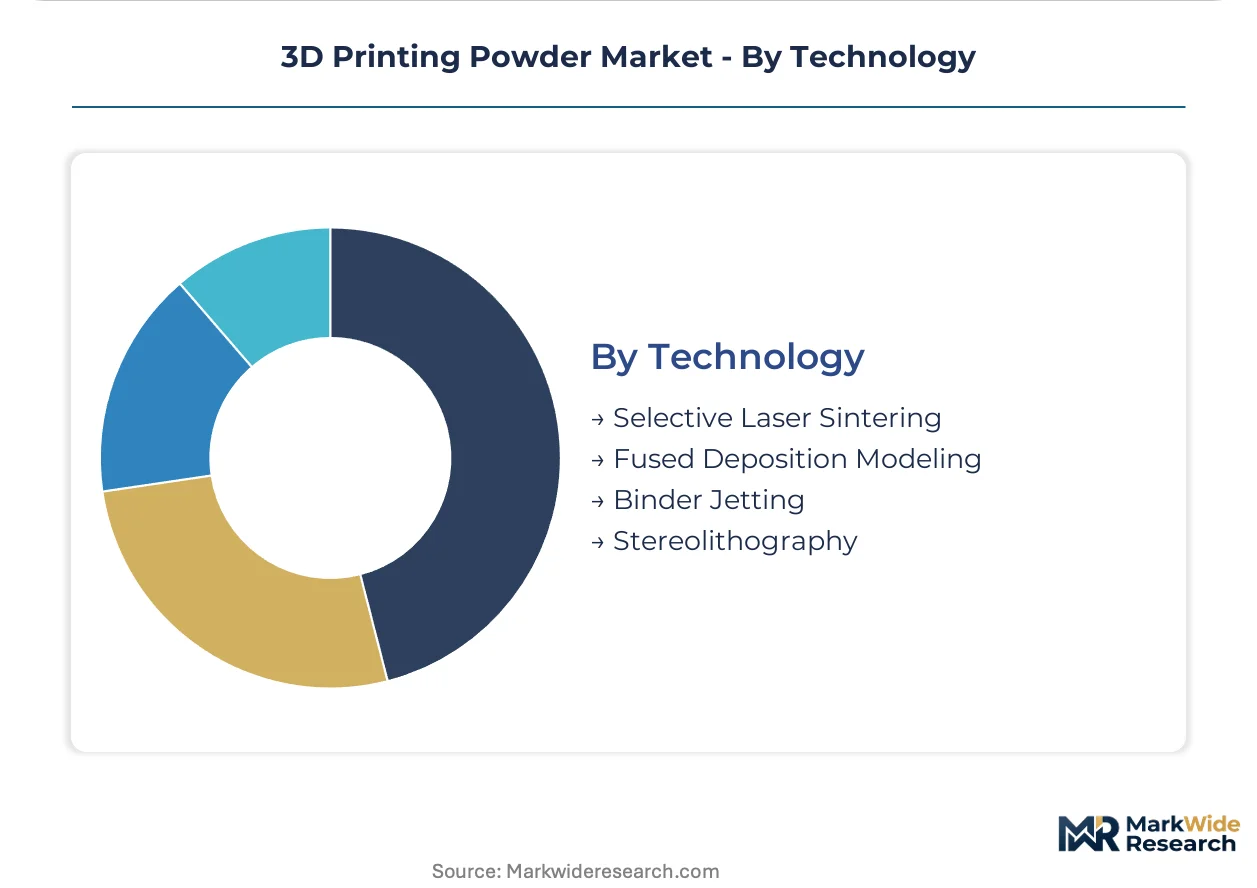
- Selective Laser Sintering:Polymer and metal laser sintering dominates installed industrial capacity, with EOS GmbH leveraging its European platform base for service revenue retention.
- Fused Deposition Modeling:Filament-fed systems compete at the prototyping tier with minimal powder handling, though pellet-to-filament conversion creates indirect powder demand upstream.
- Binder Jetting:Stainless steel serial production without thermal support structures is gaining structural traction in German automotive tooling, with Höganäs AB optimizing water-atomized steel grades for throughput.
- Stereolithography:Photopolymer resin systems serve dental and jewelry applications with distinct feedstock chemistry, limiting powder market overlap.
Selective laser sintering holds installed capacity. Binder jetting is gaining share fastest on serial production economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German powder producers dominate European supply chains, exporting nickel superalloy and titanium grades to French and Italian aerospace Tier-1s under tightened REACH and EU F-Gas protocols. Swedish captive atomization assets anchor Nordic supply security for aviation MRO networks.
Germany
Bavarian and Baden-Württemberg automotive clusters scale binder-jetted stainless steel tooling, while EOS GmbH sustains service revenue across metal laser sintering platforms. REACH compliance requirements accelerate qualified supplier consolidation. Frankfurt-Rhine-Main aviation hubs concentrate turbine blade repair powder consumption.
United States
FAA airworthiness directives drive powder bed fusion adoption for engine component refurbishment at domestic MRO facilities. OSHA exposure limits and EPA reporting requirements shape workplace handling standards for reactive metal powders. Texas and California aerospace clusters anchor regional nickel superalloy demand.
Sweden
Sandviken-based captive titanium sponge-to-powder assets supply aerospace Tier-1s with vacuum induction melt gas atomization grades. The country's national chemical regulator enforces stringent occupational exposure protocols for fine metallic dusts. Greater Stockholm medical device manufacturers adopt plasma rotating electrode atomization for orthopedic implant feedstock.
France
ANSM and EASA parallel qualification tracks govern powder reuse protocols for turbine blade repair stations. French Tier-1 manufacturers mandate consignment inventory at regional logistics hubs, transferring working capital burden upstream. Toulouse and Bordeaux aerospace clusters concentrate Inconel 718 consumption for structural bracket production.
India
CDSCO's phased MDR alignment and PLI scheme incentives create entry points for biocompatible titanium powder in orthopedic implant manufacturing. The country's national pharmaceutical regulator tightens traceability documentation for patient-contact devices. Gujarat and Maharashtra industrial corridors attract powder producers serving domestic medical device localization.
3D Printing Powder Market Vendor Landscape
On the supply side, the industry is consolidating around captive atomization capabilities and in-house testing infrastructure. Tier-1 aerospace qualification requirements favor suppliers with integrated vacuum induction melt gas atomization and lot-level chemistry certification. Three strategic archetypes dominate: integrated powder-to-part platforms, specialty alloy specialists with medical-grade sphericity, and water-atomized steel suppliers optimized for binder jetting throughput. Dominant competitive moves include backward integration into sponge production and strategic partnerships for regional logistics hub placement.
Among European-integrated platforms, EOS GmbH and Sandvik AB exemplify the captive supply archetype, anchoring service revenue and atomization capacity respectively. Höganäs AB occupies a position within the water-atomized steel tier, representing throughput-optimized grades for serial production workflows.
| Leading Market Players |
|---|
| Sandvik AB |
| Arkema |
| BASF SE |
| EOS GmbH |
| Carpenter Technology Corporation |
| Höganäs AB |
| GKN Powder Metallurgy |
| Evonik Industries AG |
| ERASTEEL |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors transmit cost volatility from nickel concentrate arrivals through to vacuum induction melt gas atomization facilities, concentrating pricing power among German and Swedish producers while forcing tiered premiums on aerospace-qualified powder grades.
Pricing Analysis
Prior-generation water-atomized steel grades for binder jetting now trade at mid-tier positioning against current-generation vacuum induction melt nickel superalloys commanding certification premiums, while next-generation plasma rotating electrode atomization titanium holds nascent premium positioning. Three-tier pricing structure separates flight-qualified aerospace grades from medical-device certified tiers from commodity prototyping feedstock, with REACH documentation and FAA airworthiness certification as primary differentiation drivers. Cost compression in water-atomized steel is intensifying because Höganäs AB and regional competitors scale throughput for automotive tooling demand. Research institutions and educational institutes exhibit highest price sensitivity, while French and Italian aerospace Tier-1s accept premium positioning for lot-traceable consignment inventory.
Supply Chain Analysis
Export-control restrictions on plasma rotating electrode atomization equipment limit technology transfer to Indian and Chinese medical device manufacturers, constraining supply expansion for high-sphericity titanium grades. Captive atomization capacity concentrates in Germany, Sweden, and the United States, with sponge-to-powder integration at Sandviken and North American satellite plants. The supply chain draws from cobalt and rhenium concentrates, titanium sponge feedstock, and polymer resin precursors as core inputs. Single-source vulnerability pervades aerospace Tier-1 procurement, particularly for Inconel 718 and Ti-6Al-4V grades with restricted qualified supplier lists. Distribution runs through consignment inventory models at regional logistics hubs mandated by French and Italian manufacturers, displacing traditional spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across powder qualification tiers, as divergent regulatory timelines for EU AI Act compliance and FAA-EASA parallel tracks create specialist niches between integrated platforms and commodity suppliers.
For Market Incumbents: Pre-empt emerging binder jetting specialists by securing captive water-atomized steel capacity in Baden-Württemberg supplier parks, while accelerating REACH documentation automation to compress recertification timelines threatened by EU AI Act audit trail mandates. Backward integration into titanium sponge production and regional logistics hub placement in Toulouse and Bordeaux aviation clusters defend margin position against consignment inventory burden transfers.
For New Entrants and Emerging Players: Pursue CDSCO-aligned biocompatible titanium powder production for Indian orthopedic implant manufacturing, exploiting PLI scheme incentives and phased MDR alignment before incumbent qualification completion. Target copper-alloy thermal management grades for power electronics and EV charging infrastructure as the most penetrable segment, leveraging binder jetting throughput advantages without legacy aerospace certification overhead.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive atomization assets lacking medical-device certification infrastructure, presenting buy-and-build platforms for REACH-compliant specialty alloy consolidation. Long-term viability centers on sensor-integrated equipment vendors positioned for EU AI Act mandatory documentation, with autonomous melt pool monitoring algorithmic audit trails as the critical inflection signal for valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Atomization Capacity Expansion | Sandvik AB's sponge-to-powder integration secures aerospace Tier-1 supply security against Swedish concentration risk. |
| Consignment Inventory Model Adoption | French Tier-1 mandates transfer working capital burden upstream to nickel superalloy suppliers. |
| Plasma Rotating Electrode Atomization Technology Licensing | Swiss and Japanese medical implant manufacturers adopt PREP titanium for superior sphericity in spinal fusion cages. |
| EU AI Act Compliance Infrastructure Investment | German aviation suppliers embed edge-computing nodes into build chambers for real-time logging mandates. |
| Regional Logistics Hub Placement | Buffer stock positioning in Frankfurt-Rhine-Main aviation clusters compresses turbine blade repair turnaround times. |
Methodological Framework
Operator-level perspectives from powder metallurgy plant managers, aerospace Tier-1 procurement leads, medical device quality assurance directors, and additive manufacturing platform engineers anchored the qualitative base, triangulated against vacuum induction melt gas atomization equipment filings, ECHA REACH registration databases, FAA airworthiness directive records, and customs trade data for nickel and titanium concentrate flows. Bottom-up powder consumption modeling across laser sintering and binder jetting installed bases converged with top-down aerospace MRO spend allocation analysis.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning material type, application end-use, technology platform, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories, powder-to-part yield assumptions, and qualification timeline compression curves. Industry-specific inputs incorporated EU F-Gas phase-down schedules and CDSCO MDR alignment phases for Indian medical device localization.
Sensitivities concentrate around REACH substance restriction expansions, FAA-EASA approval synchronization failures for powder reuse protocols, and nickel superalloy feedstock price volatility from cobalt concentrate supply disruptions. Material shifts in autonomous process control regulatory mandates or national stockpiling policies for critical alloying elements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global 3D Printing Construction Material Market