
 Antiviral Polymers for Packaging Market | 2026-2036
Antiviral Polymers for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Antiviral Polymers for Packaging Market Outlook
Copper-ion infusion and quaternary ammonium surface functionalization is tilting the antiviral packaging technology stack away from passive barrier films toward actively biocidal materials. BASF SE leverages its polymer additives portfolio to supply masterbatches with validated antiviral efficacy for food-contact applications. Dow Inc. anchors North American polyethylene production with integrated antiviral additive compounding capabilities. DuPont de Nemours, Inc. differentiates through fluoropolymer and ionomer expertise applied to medical-grade packaging films.
Antiviral polymers for packaging are macromolecular materials engineered with copper nanoparticles, silver salts, or cationic quaternary ammonium compounds, typically achieving greater than 99% viral load reduction within 24 hours per ISO 21702 surface testing protocols. These materials serve the primary commercial purpose of preventing pathogen transmission through frequently handled packaged goods in healthcare and retail environments. Flexible films lead current volume adoption due to their compatibility with existing form-fill-seal equipment across food and medical supply chains. Nano-coating technology captures expanding interest as brand owners seek thin-film antiviral functionality without altering base polymer mechanical properties. Biodegradable solutions remain nascent but attract capital as European single-use plastics directives tighten compliance requirements.
FDA food-contact notification pathways and EFSA migration limit frameworks govern antiviral additive approval, while EPA antimicrobial device registrations shape claims permissible in US commerce. REACH substance authorization in Europe constrains silver nanoparticle formulations, redirecting R&D toward copper-based and organosilane quaternary alternatives. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid reformulation costs and market access delays.
Market Dynamics
Copper-ion masterbatch compounding is concentrating technical capability among polymer additive specialists with validated ISO 21702 testing infrastructure, forcing downstream converters to qualify fewer approved supply sources for healthcare and food-contact applications.
Growth Catalysts
- Post-pandemic FDA and EMA material safety protocols:Sterile medical supply packaging procurement now mandates validated antiviral surface performance, expanding addressable demand for biocidal polymer films in hospital and pharmaceutical logistics.
- Quaternary ammonium surface functionalization:Cationic organosilane chemistry achieves viral load reduction without heavy metal migration concerns, opening food-contact applications previously restricted by EFSA silver nanoparticle limits.
- German industrial cluster concentration:BASF SE and specialty compounders in Ludwigshafen anchor European masterbatch production, creating regional supply security that accelerates healthcare sector adoption.
Market Restraints
- Copper salt input cost volatility:Electrification demand from renewable energy infrastructure competes for refined copper supply, compressing masterbatch producer margins and creating pricing friction for converters.
- REACH substance authorization constraints:ECHA's evolving restrictions on nanosilver formulations force reformulation cycles and regulatory resubmission costs for existing product portfolios.
- Passive barrier film substitution:High-performance multilayer oxygen and moisture barriers without antiviral claims retain cost advantage in non-healthcare retail packaging segments.
Strategic Opportunities
- Biodegradable antiviral platforms:European single-use plastics directives create compliance-driven demand for PLA and PHA-based biocidal films that satisfy both antiviral performance and circular economy mandates.
- Nano-coating technology convergence:Ultrathin quaternary ammonium surface treatments applied to conventional films enable antiviral functionality without capital-intensive base polymer modification.
- Indian pharmaceutical export packaging:CDSCO alignment with international material safety standards creates upgrade demand for antiviral sterile barrier systems in generic drug logistics.
Industry Challenges
- ISO 21702 testing capacity scarcity:Viral surface efficacy validation requires BSL-3 laboratory infrastructure that concentrates with limited third-party providers, extending product qualification timelines.
- Antiviral-mechanical property integration:Copper nanoparticle loading above threshold concentrations degrades polyethylene film flexibility, forcing compounders to optimize dispersion chemistry for form-fill-seal equipment compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiviral Polymers for Packaging Market |
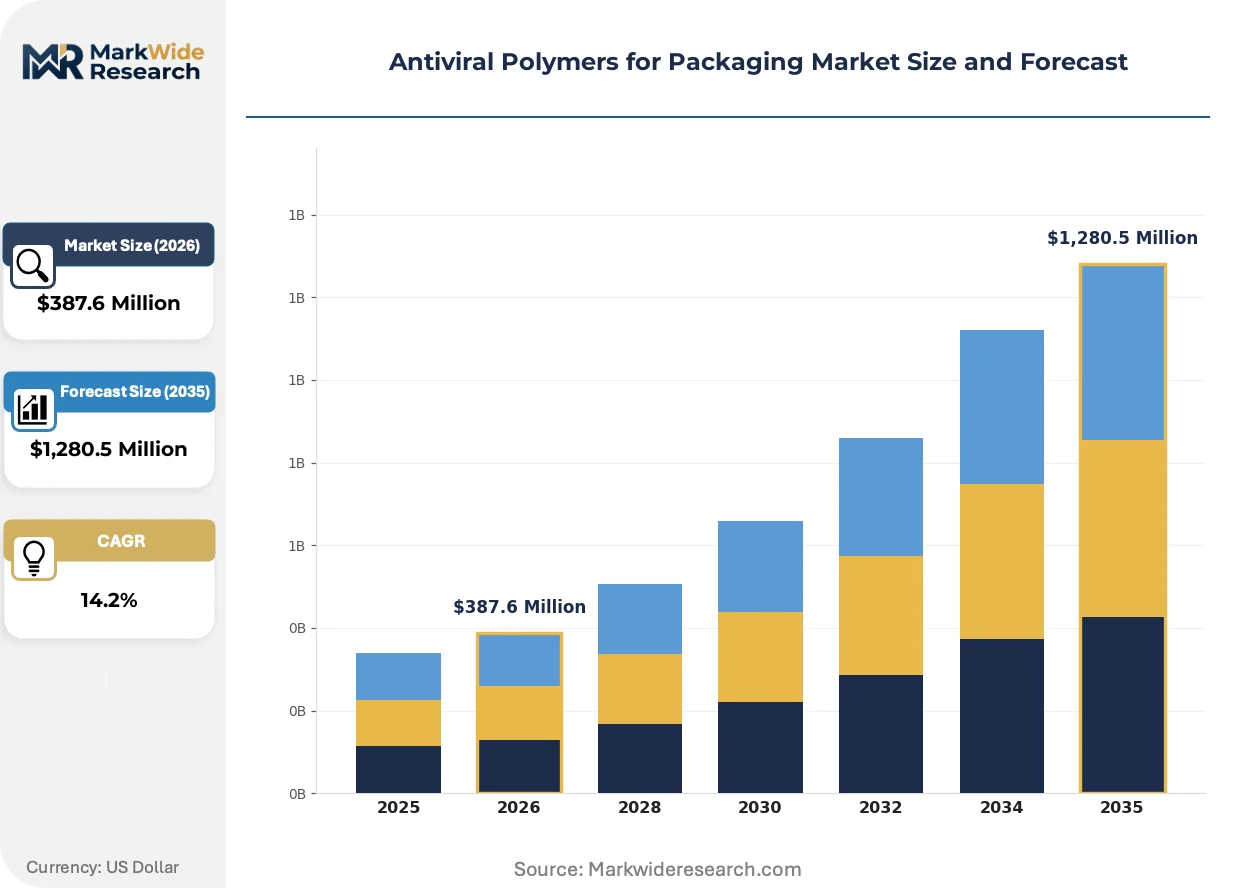
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Containers, Coatings, Adhesives Application: Food Packaging, Medical Supplies, Personal Care, Electronics End User: Healthcare, Food Industry, Consumer Goods, Electronics Manufacturers Technology: Nano-coating, Polymer Blends, Biodegradable Solutions, Surface Modification |
| Companies Covered | BASF SE, Dow Inc., DuPont de Nemours, Inc., Mitsubishi Chemical Corporation, Toray Industries, Inc., Berry Global Inc., Milliken & Company, Amcor plc, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiviral Polymers for Packaging Market Strategic Shifts
Active biocidal functionality is displacing passive protection as the primary value proposition in medical and food packaging, with surface-engineered polymers commanding technical differentiation and procurement preference.
Copper nanoparticle masterbatch technology is migrating from healthcare sterile barriers toward retail food-contact films. Supermarket chains and prepared meal distributors in Germany and France now specify validated antiviral polyethylene for high-touch deli and bakery packaging. This migration is compressing the technology premium and forcing additive suppliers to demonstrate cost parity with conventional films at volume scale.
REACH substance authorization procedures are tightening constraints on silver-based formulations while creating regulatory tailwinds for copper and quaternary ammonium alternatives. ECHA's 2023-2024 evaluation windows for nanomaterial classifications have redirected R&D expenditure toward organosilane chemistry that avoids authorization requirements. Medical device packaging converters in the Netherlands and Belgium are accelerating qualification of copper-ion systems to preempt supply disruption.
Hospital procurement departments are consolidating vendor relationships around integrated material-testing-converting suppliers. Large German healthcare networks now require antiviral packaging specifications bundled with ISO 21702 certificate management and lot traceability documentation. This concentration favors compounders with in-house analytical capabilities and compresses margins for standalone film converters without additive formulation expertise.
Antiviral Polymers for Packaging Market Segmentation
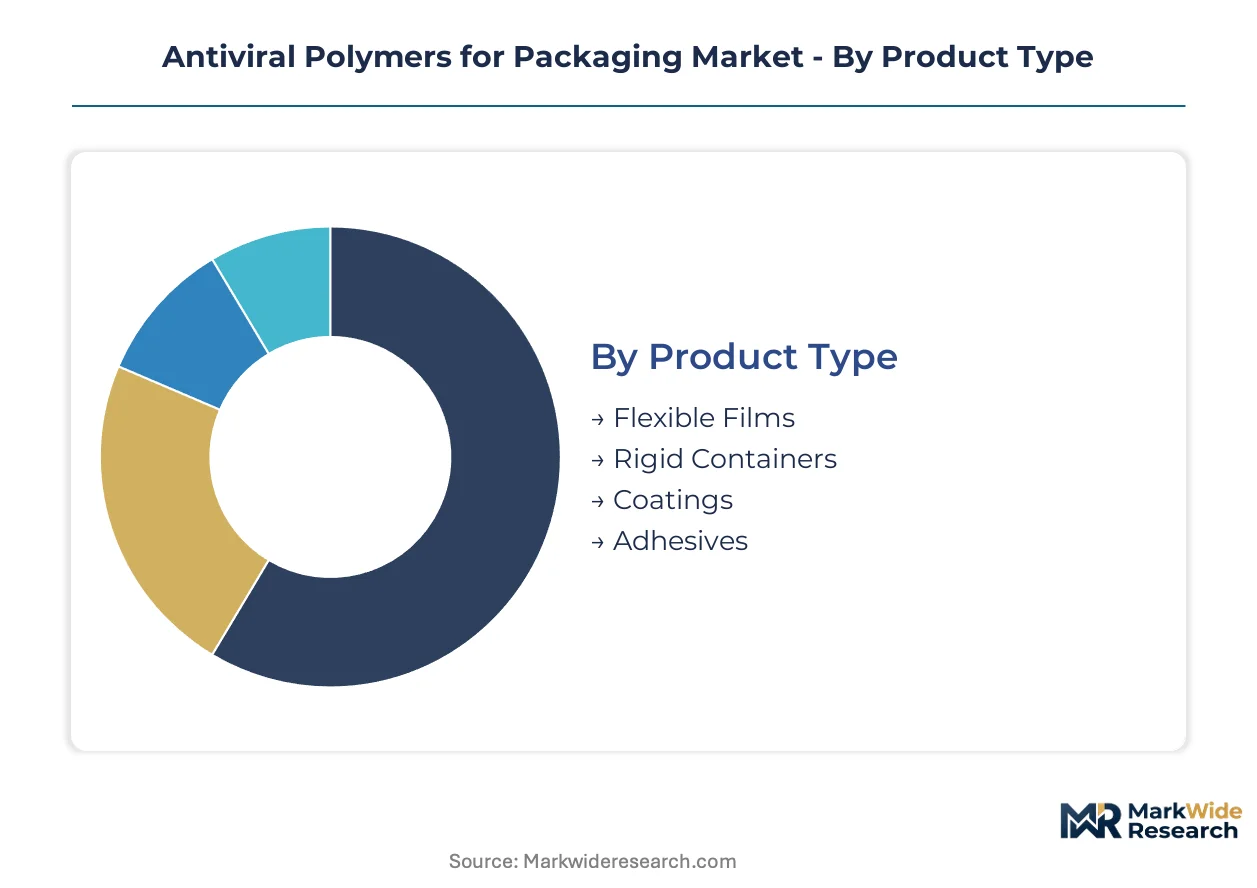
Segmentation in antiviral polymers for packaging reveals divergent technical requirements across sterile medical barriers versus retail food-contact films. Product qualification timelines, regulatory pathways, and capital intensity vary substantially by segment, reshaping how compounders prioritize R&D allocation and converter partnerships.
Product Type:
After-sales technical service intensity concentrates in flexible films and coatings, where converters require ongoing formulation support to maintain ISO 21702 validation across lot variations.
- Flexible Films:Polyethylene and polypropylene substrates infused with copper-ion masterbatches dominate hospital sterile barrier systems. German healthcare networks now mandate lot-traceable antiviral certification bundled with film supply, elevating service obligations for compounders.
- Coatings:Ultrathin quaternary ammonium surface treatments applied to conventional films enable antiviral functionality without base polymer modification. French supermarket chains specify these for high-touch deli packaging to avoid capital-intensive equipment upgrades.
- Rigid Containers:Injection-molded polypropylene with integrated biocidal additives serves pharmaceutical vial packaging and specimen transport.
- Adhesives:Pressure-sensitive and heat-seal formulations with cationic antimicrobial agents bond multilayer sterile barriers.
Flexible films hold the largest share; momentum sits with coatings as brand owners seek antiviral performance without mechanical property trade-offs.
Application:
Cost tier stratification separates premium-validated medical applications from compliance-driven food packaging and price-sensitive consumer segments.
- Medical Supplies:Sterile barrier systems for surgical instruments and pharmaceutical logistics require FDA 510(k) or EMA notified body documentation. BASF SE and Dow Inc. compete on integrated masterbatch-converting capabilities with certificate management services.
- Food Packaging:Prepared meal distributors and supermarket chains in Germany and France now specify validated antiviral polyethylene for high-touch surfaces. EFSA migration limits favor copper and quaternary ammonium formulations over silver nanoparticles.
- Personal Care:Wipe packaging and cosmetic containers utilize lower-load biocidal additives where viral claims are secondary to aesthetic preservation.
- Electronics:Antistatic-antiviral films for device shipping protect sensitive components in warehouse environments with minimal regulatory burden.
Medical supplies command premium pricing; food packaging represents the steepest expansion trajectory as retail procurement standards tighten.
End User:
Customer type determines procurement sophistication, with healthcare systems bundling specifications around integrated testing-converting suppliers versus fragmented food industry purchasing.
- Healthcare:Hospital networks and pharmaceutical logistics operators consolidate vendor relationships around compounders with in-house ISO 21702 capabilities. Large German healthcare systems now require antiviral packaging bundled with lot traceability documentation.
- Food Industry:Supermarket chains and prepared meal distributors specify validated films but lack centralized technical qualification resources, creating opportunity for converters with regulatory navigation expertise.
- Consumer Goods:Brand owners in personal care and household products prioritize cost parity with conventional films over maximum viral load reduction.
- Electronics Manufacturers:Warehouse and shipping operations seek dual-function antistatic-antiviral films with minimal certification requirements.
Healthcare generates the highest margins; food industry purchasing is climbing fastest as European single-use plastics directives reshape procurement priorities.
Technology:
Supply concentration among polymer additive specialists with validated testing infrastructure favors nano-coating and surface modification approaches over capital-intensive biodegradable platform development.
- Surface Modification:Covalent grafting of quaternary ammonium organosilanes onto polymer substrates achieves durable antiviral efficacy without heavy metal migration. ECHA's nanosilver restrictions redirect R&D expenditure toward this chemistry.
- Nano-coating:Ultrathin spray or dip coatings apply biocidal functionality to existing film inventories, enabling brand owners to test antiviral claims without base polymer conversion. Dutch and Belgian medical device converters accelerate qualification to preempt supply disruption.
- Polymer Blends:Masterbatch compounding of copper nanoparticles into polyethylene and polypropylene serves high-volume healthcare and food packaging with established supply chains.
- Biodegradable Solutions:PLA and PHA-based biocidal films attract capital as European circular economy mandates tighten, though performance validation lags conventional polymers.
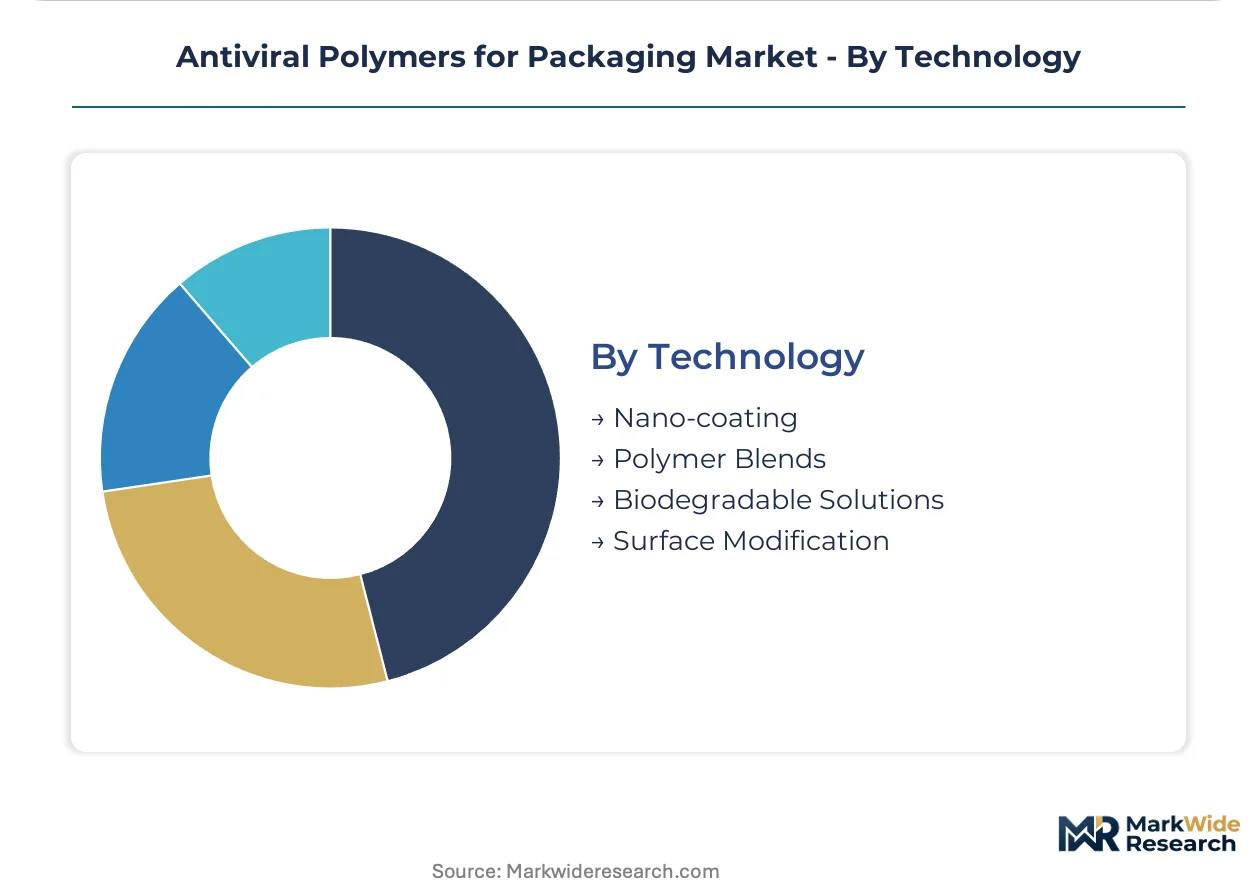
Polymer blends dominate current volume; biodegradable solutions are expanding most quickly as compliance-driven demand intersects with sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German antiviral masterbatch exports flow into French and Dutch medical device packaging supply chains, while US healthcare procurement draws heavily from North American compounders with integrated testing capabilities.
Germany
Ludwigshafen-based BASF SE anchors European copper-ion masterbatch production for hospital sterile barriers. REACH substance authorization procedures redirect R&D toward quaternary ammonium alternatives as ECHA tightens nanosilver classifications. The Rhine-Neckar chemical cluster concentrates validated ISO 21702 testing infrastructure that accelerates healthcare sector qualification timelines.
United States
FDA food-contact notification pathways and EPA antimicrobial device registrations shape permissible claims in domestic commerce. Dow Inc. leverages integrated polyethylene production with antiviral additive compounding capabilities across the Gulf Coast petrochemical corridor. Hospital procurement departments consolidate vendor relationships around suppliers bundling material certificates with lot traceability documentation.
France
Supermarket chains and prepared meal distributors specify validated antiviral polyethylene for high-touch deli and bakery packaging surfaces. ANSM pharmaceutical packaging standards align with EMA post-pandemic material safety protocols for sterile medical logistics. The Paris-Saclay research cluster advances nano-coating technology for ultrathin quaternary ammonium surface treatments on conventional films.
Netherlands
Medical device packaging converters accelerate qualification of copper-ion systems to preempt supply disruption from evolving ECHA restrictions. Rotterdam-Europoort distribution infrastructure facilitates antiviral polymer compound imports from German producers for re-export to Belgian pharmaceutical manufacturers. The Dutch polymer processing sector specializes in multilayer sterile barrier films with integrated biocidal adhesives.
India
CDSCO alignment with international material safety standards creates upgrade demand for antiviral sterile barrier systems in generic drug export packaging. Maharashtra and Gujarat pharmaceutical manufacturing zones drive procurement of validated polyethylene films for temperature-sensitive vaccine logistics. Mumbai-Pune industrial corridor converters seek masterbatch suppliers with certificate management capabilities for EU-bound pharmaceutical shipments.
Antiviral Polymers for Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. BASF SE and Dow Inc. occupy integrated compounder-converter roles with in-house ISO 21702 validation infrastructure, while specialty additive suppliers and regional film processors fill fragmented mid-market segments. Three archetypes dominate: vertically integrated chemical conglomerates with polymer additive portfolios, standalone masterbatch compounders with testing partnerships, and film converters sourcing certified materials from approved supplier lists. Competitive moves concentrate on backward integration into copper salt sourcing and technology licensing for nano-coating application methods.
Among diversified chemical conglomerates, BASF SE and Dow Inc. exemplify the integrated archetype combining base polymer production with antiviral additive formulation. DuPont de Nemours, Inc. occupies a distinct position leveraging fluoropolymer expertise for medical-grade packaging applications. These three entities anchor competitive dynamics as hospital procurement consolidation favors suppliers with bundled material-testing-converting capabilities and certificate management services.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| Berry Global Inc. |
| Milliken & Company |
| Amcor plc |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in ISO 21702 BSL-3 testing laboratories concentrates pricing power with German and Dutch compounders holding validated infrastructure, while copper salt indexation clauses in masterbatch contracts transmit electrification-driven raw material volatility directly to healthcare converters.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate masterbatch supply agreements for healthcare sterile barriers. Pricing stratifies across FDA 510(k)-validated premium tiers, EFSA-compliant food-contact mid-tiers, and uncertified economy grades for consumer goods. Cost compression in food-contact films is intensifying because supermarket chains now demand validated antiviral performance at conventional polyethylene parity. Electronics manufacturers exhibit highest price sensitivity, while hospital procurement departments accept premium positioning for bundled certificate management services.
Supply Chain Analysis
Tariff exposure between Germany and post-Brexit UK pharmaceutical packaging markets dominates supply chain risk planning for masterbatch exporters. Production gravity centers on Germany, the United States, and Japan for copper-ion compounding, while refined copper feedstock draws from Chilean and Peruvian mining operations. Single-source vulnerability concentrates in BSL-3 testing capacity held by limited third-party providers in the Rhine-Neckar and Rotterdam-Europoort clusters. Distribution runs through integrated compounder-converter relationships with hospital networks and pharmaceutical logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across food-contact certification tiers creates niche opportunities as European supermarket procurement standards diverge from legacy healthcare validation requirements.
For Market Incumbents: Harden ISO 21702 certificate management capabilities against emerging nano-coating specialists offering ultrathin quaternary ammonium treatments without base polymer modification. Deepen backward integration into copper salt sourcing to preempt margin compression from electrification demand competing for refined supply. Channel control through bundled material-testing-converting services remains the priority lever against standalone film converters lacking additive formulation expertise. For New Entrants and Emerging Players: Pursue biodegradable antiviral platforms for European single-use plastics compliance as PLA and PHA performance validation gaps create white-space before incumbent compounders redirect R&D expenditure. Target Indian pharmaceutical export packaging where CDSCO alignment with international material safety standards drives upgrade demand for sterile barrier systems. A regulatory navigation service model offering certificate management for EU-bound shipments provides the most penetrable go-to-market angle against established German suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with in-house BSL-3 testing infrastructure and multi-year hospital network contracts. Five-to-ten year viability favors acquisition targets combining copper-ion masterbatch expertise with nano-coating application technology to span both healthcare and retail food-contact demand. Watch ECHA nanomaterial classification decisions as the inflection signal for silver formulation obsolescence and copper-quaternary ammonium substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Salt Sourcing | Captive supply of refined copper insulates margins from electrification demand competition in renewable infrastructure. |
| ISO 21702 Testing Infrastructure Expansion | In-house BSL-3 viral efficacy validation accelerates product qualification timelines for hospital procurement consolidation. |
| Nano-coating Technology Licensing | Ultrathin quaternary ammonium surface treatments enable antiviral functionality without capital-intensive base polymer conversion. |
| Biodegradable Platform Development | PLA and PHA-based biocidal films satisfy European circular economy mandates while antiviral performance validation matures. |
| Certificate Management Service Bundling | Lot-traceable documentation services differentiate compounders as hospital networks consolidate vendor relationships around integrated suppliers. |
Study Parameters
The analysis maps flexible film masterbatch compounding, nano-coating surface modification, rigid container injection molding, and biodegradable polymer development, each validated through primary interviews with polymer additive R&D directors, hospital procurement managers, pharmaceutical packaging engineers, and food industry regulatory affairs leads. Secondary sources include ECHA substance authorization databases, FDA food-contact notification filings, ISO 21702 testing facility accreditations, and customs trade data for copper salt and masterbatch flows. Bottom-up segment sizing triangulates against top-down chemical industry production estimates.
Forecast assumptions hold fixed REACH substance authorization timelines, EFSA migration limit frameworks, and FDA post-pandemic material safety protocol enforcement intensity, while varying copper price trajectories and European single-use plastics directive implementation pace across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology platform, with CAGRs derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific inputs incorporate BSL-3 testing capacity buildout announcements and hospital procurement consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in refined copper prices, healthcare capital expenditure cycles, or European regulatory enforcement intensity would shift the trajectory for masterbatch demand and pricing power concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market