
 Polypropylene Powder Market | 2026-2036
Polypropylene Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Powder Market Analysis
Food-grade specification upgrades across the Polypropylene Powder Market is bifurcating supply chains into pharmaceutical-compliant and general industrial tiers. Sinopec leverages its Daqing and Maoming complexes to dominate domestic homopolymer output. Braskem sustains its bio-based polypropylene program from Triunfo, differentiating its portfolio against fossil-derived alternatives. BASF competes through catalyst technology leadership in metallocene-based random copolymers.
Polypropylene powder consists of fine particulate thermoplastic resin produced via Ziegler-Natta or metallocene catalytic polymerization, typically with melt flow indices between 3 and 50 g/10 min and particle sizes ranging from 100 to 500 microns for rotomolding and powder coating applications. Homopolymer grades anchor volume demand in rigid packaging and automotive underbody shields where stiffness and chemical resistance matter most. Copolymer formulations, particularly random copolymers, capture expanding margin pools in healthcare sterilization trays and flexible food containers requiring clarity and impact balance. The Application dimension shows Automotive Components gaining traction as OEMs specify lightweight under-hood parts to meet emissions standards.
REACH registration requirements in Europe and FDA food contact notifications in the United States shape product migration testing protocols and compositional disclosure obligations for suppliers seeking multi-regional approval. China's GB standards and NMPA medical device material filings add further compliance layers for healthcare-grade powder entrants. Stakeholders must monitor catalyst cost trajectories and recycled-content certification schemes as these variables determine which specification tiers achieve sustainable profitability.
Market Dynamics
Homopolymer supply concentration in China's integrated petrochemical corridors is compressing margin structures for regional converters in Europe and North America, forcing differentiation through catalyst technology and certification tiers.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' recyclability targets are accelerating mono-material food container adoption, pulling virgin-compatible powder grades into circular supply chains.
- Automotive lightweighting specifications:OEM under-hood thermal shield requirements are displacing metal stampings with rotomolded polypropylene in Germany and Japan assembly plants.
- Metallocene catalyst diffusion:Random copolymer clarity improvements are unlocking healthcare sterilization tray applications previously served by polycarbonate.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics tie powder margins to regional olefin spreads, particularly acute for European non-integrated producers.
- REACH registration cost barriers:ECHA substance data requirements create fixed compliance burdens that disadvantage specialty-grade entrants below 5,000-tonne annual volumes.
- Mechanical recycling substitution:Post-industrial regrind from injection molding scrap competes on price for non-food rotomolding applications in price-sensitive construction segments.
Strategic Opportunities
- India's medical device localization:CDSCO material registration harmonization with ISO 10993 biocompatibility standards opens import-substitution pathways for healthcare-grade random copolymers.
- Rotational molding of EV battery housings:Thermal management enclosure specifications are creating new demand pools distinct from traditional tank and playground equipment applications.
- Bio-attributed mass balance certification:ISCC PLUS chain-of-custody schemes allow fossil-asset producers to capture premium positioning without capital-intensive biorefinery builds.
Industry Challenges
- Multi-jurisdiction food contact dossier assembly:Simultaneous FDA notification, EU 10/2011 compliance, and China's GB 4806 migration testing stretches technical regulatory teams at mid-scale suppliers.
- Ziegler-Natta catalyst talent scarcity:Retiring polymerization specialists in Europe and North America constrain process optimization for legacy plant retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Powder Market |
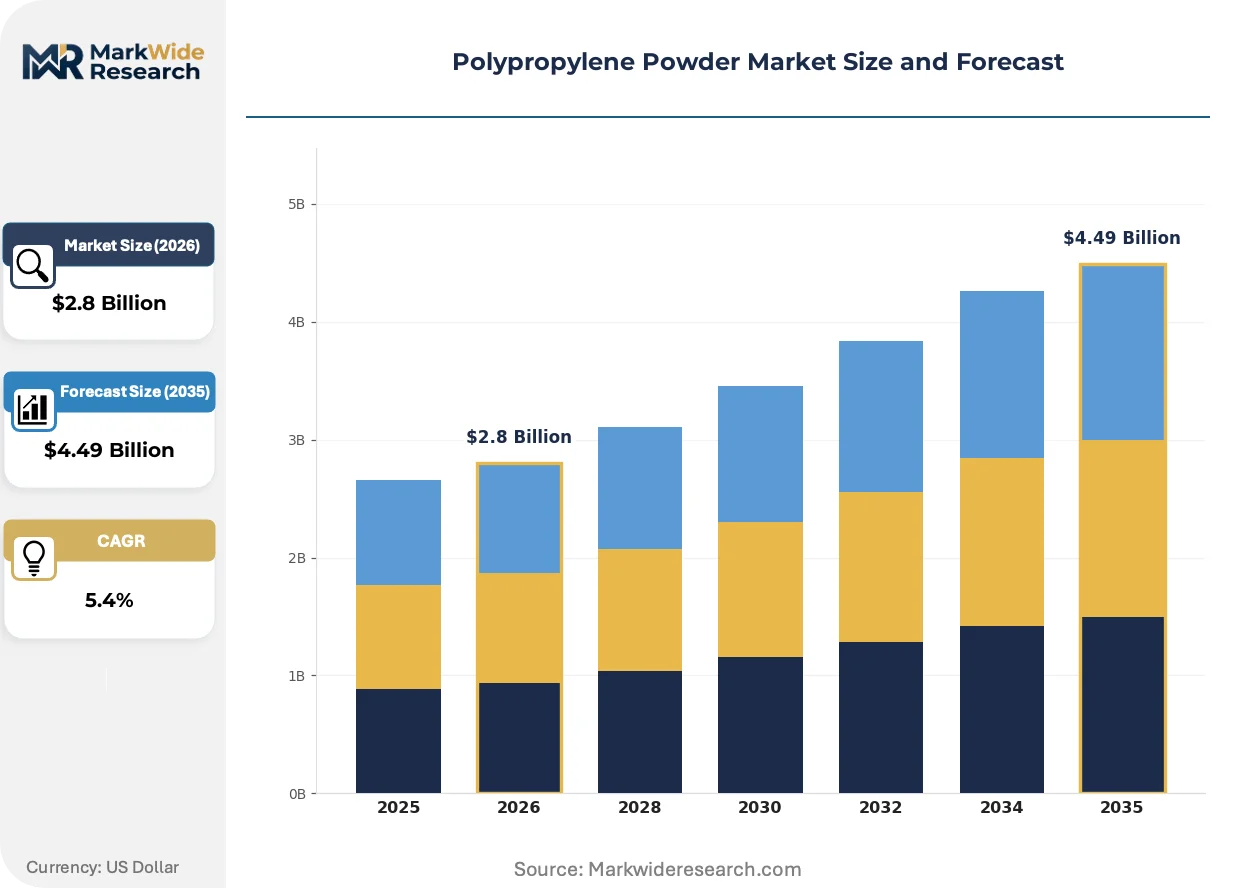
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Random Copolymer, Block Copolymer Application: Packaging, Automotive Components, Consumer Goods, Textiles End Use Industry: Food & Beverages, Healthcare, Construction, Electronics Form: Powder, Granules, Pellets, Beads |
| Companies Covered | Sinopec, Nanjing Petrochemical, Braskem, BASF, Chambroad Petrochemicals, CNPC, Hong Ji Petrochemical, Jianyuanchun Chemical, Yongxing Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Powder Market Emerging Trajectories
Catalyst technology divergence and regulatory disclosure requirements are bifurcating the supplier base into specification-grade specialists and commodity volume players.
Metallocene single-site catalyst systems are fragmenting the traditional Ziegler-Natta homopolymer dominance in rotomolding applications. Tier-one automotive suppliers in Germany and Japan are specifying narrow molecular weight distribution grades for dimensional stability in under-hood components. This catalyst shift is compressing the addressable market for conventional medium-flow homopolymers in premium segments.
REACH Article 33 substance disclosure obligations are forcing downstream certification of entire formulation chains including catalyst residues and processing aids. European converters serving food contact applications now require full SCIP database registration from powder suppliers. The compliance burden falls heaviest on small-batch custom compounders lacking dedicated regulatory affairs functions.
Direct mill relationships are displacing distributor intermediaries in North American rotomolding compound procurement. Large tank and marine OEMs in the US Gulf Coast and Great Lakes regions are consolidating purchase volumes through toll compounding arrangements with Sinopec and Braskem import channels. This channel compression is most visible in bulk homopolymer grades where specification differentiation is minimal.
Polypropylene Powder Market Segmentation
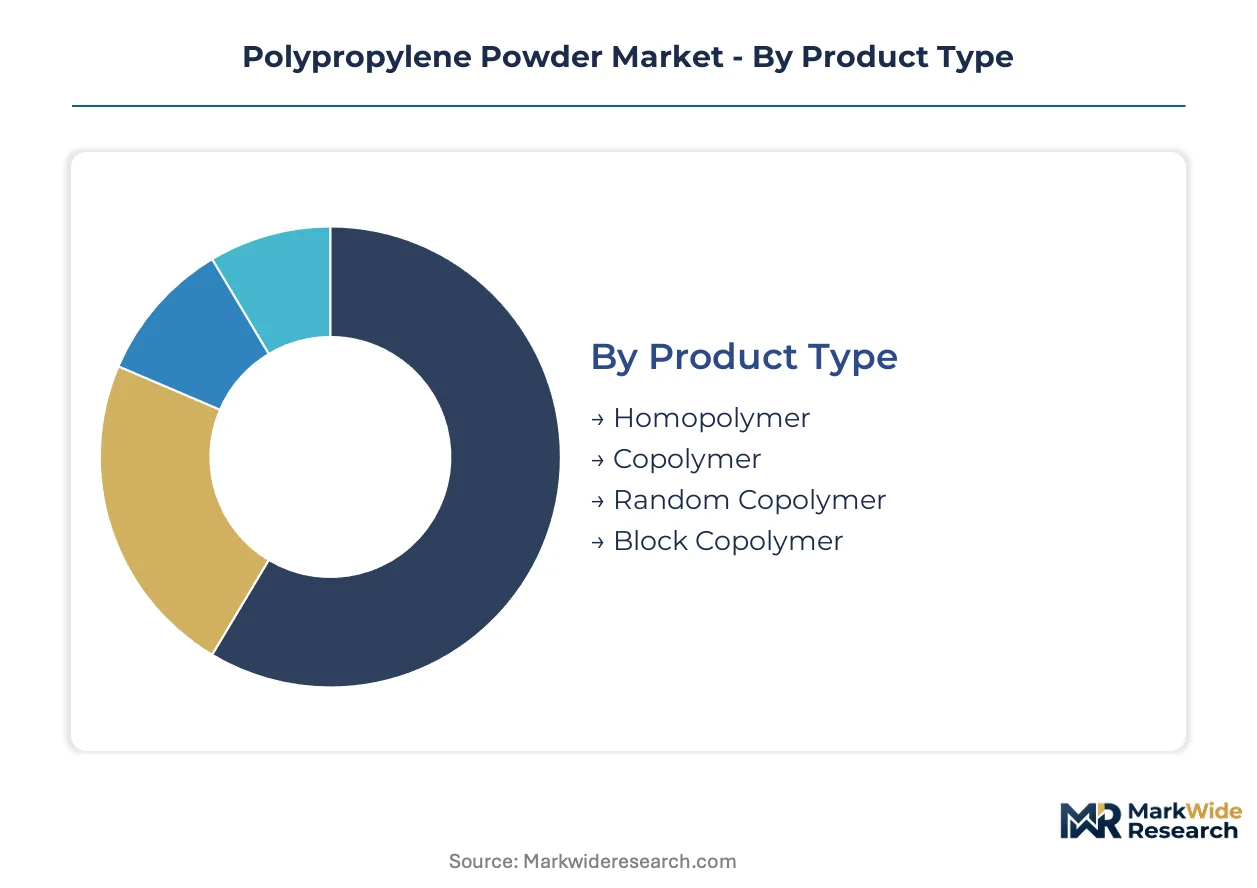
Polypropylene powder segmentation reveals distinct channel economics across product grades. Homopolymer volumes flow through bulk distribution to rotomolders, while specialty copolymers demand direct technical sales for healthcare and food contact certifications.
Product Type:
Channel mix varies sharply by molecular architecture, with commodity grades consolidating through distributors and specialty copolymers requiring direct mill relationships for formulation support.
- Homopolymer:High-crystallinity isotactic polypropylene with melt flow indices of 3–35 g/10 min serves rotomolding compounders and powder coaters. Daqing and Maoming complexes in China push volumes through regional distributors to construction tank manufacturers. Naphtha-cracking economics compress margins for European non-integrated converters.
- Copolymer:Ethylene-modified structures split into random and block configurations for divergent performance requirements. Random copolymers capture sterilization tray demand from polycarbonate incumbents through metallocene catalyst clarity improvements. Block copolymers supply automotive under-hood shields where impact resistance at sub-zero temperatures matters.
- Random Copolymer:Single-site catalyst grades with narrow molecular weight distribution flow through certified channels to healthcare OEMs requiring ISO 10993 biocompatibility documentation.
- Block Copolymer:Heterophasic structures with rubber-toughened matrices serve cold-weather automotive specifications through tier-one supplier direct contracts.
By volume, Homopolymer leads. By growth pace, Random Copolymer is ahead.
Application:
Cost tier stratification separates specification-grade applications with full regulatory dossiers from price-sensitive segments accepting general-purpose certifications.
- Packaging:Mono-material food containers and industrial pails demand virgin-compatible grades for EU Green Deal recyclability mandates. REACH Article 33 SCIP database registration requirements filter supplier eligibility. Migration testing protocols under EU 10/2011 and FDA food contact notifications stretch mid-scale compounders.
- Automotive Components:Under-hood thermal shields and battery enclosures specify narrow-MWD metallocene grades for dimensional stability. OEMs in Germany and Japan assembly plants displace metal stampings with rotomolded polypropylene to meet emissions standards.
- Consumer Goods:Playground equipment and marine tanks utilize medium-flow homopolymers through toll compounding arrangements with import channels.
- Textiles:Nonwoven fiber precursors and carpet backing powders serve through separate distribution networks from molding grades.
Packaging commands the largest revenue pool. Automotive Components shows the steepest expansion trajectory.
End Use Industry:
Customer type divergence splits procurement between centralized buying groups for multinational food brands and fragmented project-based purchasing in construction.
- Food & Beverages:Brand owners specify recyclable mono-material structures compatible with mechanical recycling streams. Multi-jurisdiction compliance—FDA notification, EU 10/2011, China's GB 4806—favors suppliers with dedicated regulatory affairs functions.
- Healthcare:Sterilization trays and medical device housings require NMPA filings in China and CDSCO harmonization with ISO 10993 in India. Random copolymer clarity grades displace incumbent engineering thermoplastics.
- Construction:Water tanks and chemical storage vessels accept post-industrial regrind for non-food applications. Price sensitivity favors mechanical recycling substitution over virgin powder.
- Electronics:Thin-wall housings and connector components demand specialized flow characteristics through niche compounding channels.
Food & Beverages dominates volume throughput. Healthcare achieves the highest margin realization per tonne.
Form:
Supply concentration in integrated petrochemical corridors shapes form factor availability by geography.
- Powder:100–500 micron particulate produced via gas-phase polymerization serves rotomolding and powder coating directly. Particle size distribution requirements vary by application.
- Granules:Intermediate sizing for extrusion compounding bridges powder production and final article manufacturing.
- Pellets:Standardized feedstock for injection molding conversion competes indirectly with powder in overlapping end uses.
- Beads:Spherical morphologies for specialized coating applications command premium positioning through limited supplier base.
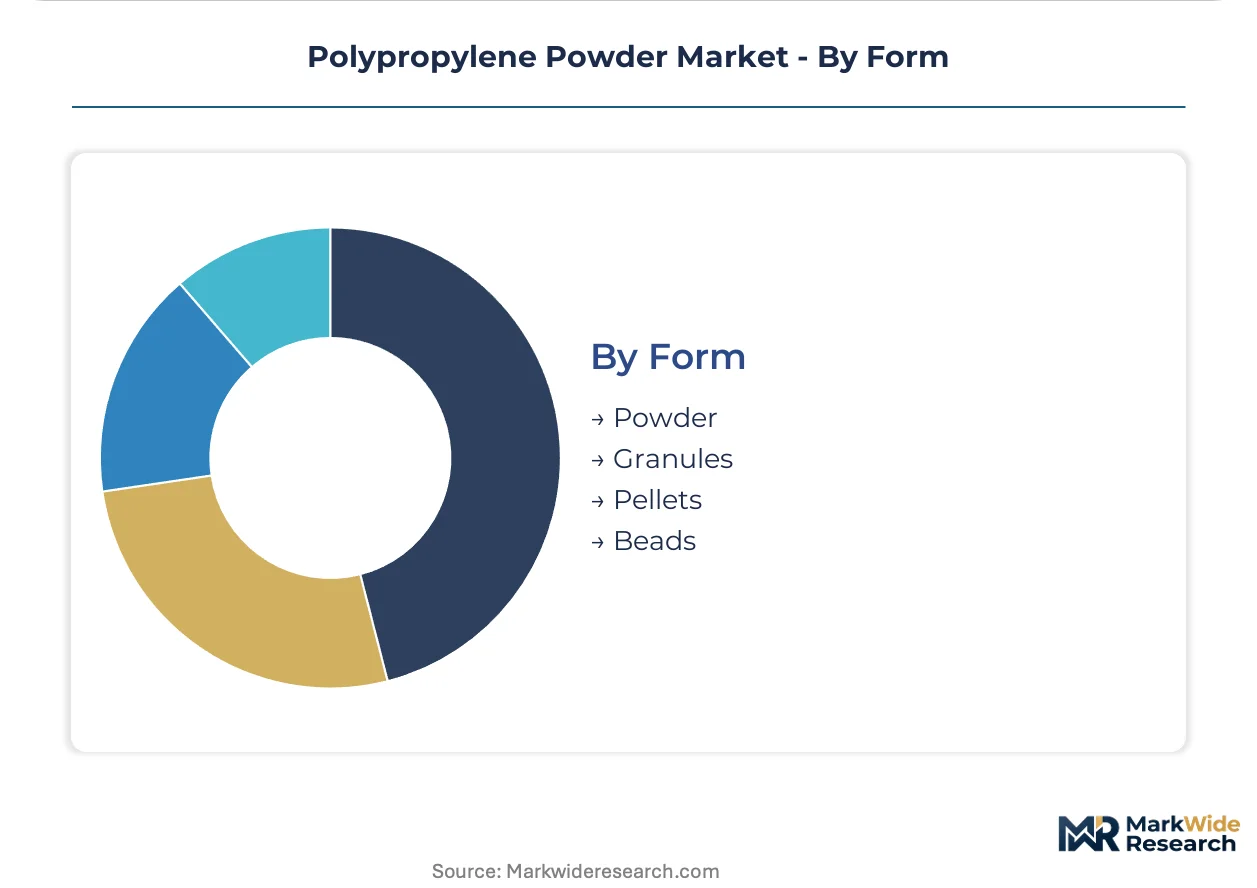
Powder leads in rotomolding-addressable volume. Granules expand most quickly as converters seek processing flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical corridors in China, Germany, and the United States concentrate polypropylene powder supply capacity. Daqing and Maoming complexes anchor Asian output. Gulf Coast crackers and Rhine-Ruhr chemical clusters shape Atlantic basin availability.
China
Rotomolding compounders and powder coaters drive consumption across construction tank and automotive under-hood segments. GB standards for food contact materials and NMPA medical device filings create multi-layer compliance obligations. Sinopec's Daqing and Maoming facilities push homopolymer volumes through regional distributors serving domestic converters.
Germany
Tier-one automotive suppliers specify metallocene-grade random copolymers for thermal shield applications displacing metal stampings. REACH Article 33 SCIP database registration requirements filter supplier eligibility for food contact applications. Rhine-Ruhr chemical corridor producers face margin compression from naphtha-cracking economics tied to regional olefin spreads.
United States
Large tank and marine OEMs in the Gulf Coast and Great Lakes regions consolidate purchase volumes through toll compounding arrangements. FDA food contact notifications shape migration testing protocols for packaging-grade powder entrants. Texas and Louisiana petrochemical complexes supply medium-flow homopolymers through direct mill relationships bypassing distributor channels.
India
Medical device manufacturers seek import-substitution pathways for healthcare-grade random copolymers as CDSCO harmonizes with ISO 10993 biocompatibility standards. FSSAI food safety regulations and BIS certification requirements add compliance layers for packaging applications. Gujarat and Maharashtra industrial corridors attract specialty-grade suppliers targeting sterilization tray and flexible container demand.
Brazil
Consumer goods rotomolders and construction tank fabricators anchor regional consumption of medium-flow homopolymer grades. ANVISA pharmaceutical regulations shape healthcare-grade material registration pathways for random copolymer entrants. São Paulo state petrochemical complexes serve domestic converters while bio-based program differentiation competes against fossil-derived imports.
Polypropylene Powder Market Vendor Landscape
Concentration sits with state-affiliated petrochemical majors and integrated chemical conglomerates. Chinese producers leverage captive propylene feedstock from naphtha crackers to compress regional converter margins. Three archetypes dominate: integrated petrochemical majors with backward control over olefin supply, catalyst technology specialists licensing metallocene systems, and regional compounders toll-processing import volumes. Competitive moves center on capacity expansion in low-cost feedstock corridors and strategic partnerships for healthcare-grade certification dossiers.
Among Asia-Pacific-based integrated producers, Sinopec and CNPC anchor the state-affiliated tier with Daqing and Maoming complex output. Braskem occupies a position exemplifying bio-based differentiation against fossil-derived alternatives. BASF represents catalyst technology leadership in metallocene-based random copolymers serving European automotive and healthcare specifications.
| Leading Market Players |
|---|
| Sinopec |
| Nanjing Petrochemical |
| Braskem |
| BASF |
| Chambroad Petrochemicals |
| CNPC |
| Hong Ji Petrochemical |
| Jianyuanchun Chemical |
| Yongxing Chemical |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Chinese integrated petrochemical majors and Gulf Coast rotomolders lock in both propylene feedstock access and eighteen-month price visibility against naphtha-cracking volatility. These arrangements tie powder grade premiums directly to REACH registration completion status and FDA food contact notification tiers.
Pricing Analysis
EU 10/2011 migration testing protocols dictate the pricing tier structure across food-contact polypropylene powder, separating pharmaceutical-compliant random copolymers from general-purpose homopolymer grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO 10993 biocompatibility documentation commanding the widest spreads. Pricing pressure stems from mechanical recycling substitution in non-food construction tanks, where post-industrial regrind erodes virgin powder premiums. Construction segment buyers exhibit highest price sensitivity, while healthcare OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit lanes underwrite the bulk of Asian propylene feedstock flows feeding Daqing and Maoming complex outputs. Supply concentrates in China, Germany, and the United States, with naphtha, polymerization catalysts, and hydrogen feedstock drawing from integrated crackers and specialty chemical suppliers. Single-source vulnerability sits with metallocene catalyst systems licensed through limited technology holders. Distribution runs through toll compounding arrangements for large rotomolders, while specialty copolymers flow via direct mill relationships with certified channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around multi-jurisdiction food contact dossiers creates formidable defensive moats for established suppliers, as switching costs for brand owners span reformulation trials and migration testing investments.
For Market Incumbents: Compound certification depth in healthcare-grade random copolymers to outpace polycarbonate substitution threats in sterilization tray applications. Deepen backward integration into catalyst technology licensing to secure margin capture from metallocene clarity improvements. Prioritize capacity reservation contracts with automotive OEMs specifying under-hood thermal shield grades. For New Entrants and Emerging Players: CDSCO harmonization with ISO 10993 biocompatibility standards offers the fastest certification pathway into India's import-substitution medical device corridor. Target toll compounding partnerships with Sinopec import channels rather than greenfield production investments. Lead with EV battery housing thermal management specifications as the most penetrable automotive segment. For Investors and Strategic Acquirers: Regional compounders with dedicated regulatory affairs functions and established FDA notification track records represent the most defensible acquisition archetype. Long-term viability hinges on bio-attributed mass balance certification adoption curves. Watch ISCC PLUS chain-of-custody scheme penetration as the inflection signal for premium positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Technology | Metallocene licensing control captures margin pools from clarity-grade random copolymers displacing polycarbonate. |
| Healthcare-Grade Certification Investment | ISO 10993 dossier completion unlocks sterilization tray demand from German and Japanese OEM supply chains. |
| Bio-Attributed Mass Balance Certification | ISCC PLUS accreditation allows fossil-asset producers to command premium positioning without biorefinery capital deployment. |
| EV Battery Housing Specification Development | Thermal management enclosure standards create demand pools distinct from traditional tank and playground equipment rotomolding. |
| Toll Compounding Partnership Expansion | Direct mill relationships with Sinopec and Braskem import channels bypass distributor intermediaries in North American bulk homopolymer procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing rotomolding plant managers, automotive Tier 1 procurement leads, healthcare OEM material engineers, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade flow databases, American Chemistry Council sector reports, SEC 10-K filings of integrated petrochemical majors, and ECHA REACH registration disclosures. Bottom-up volume modeling across grade tiers and end-use segments was triangulated against top-down olefin demand projections.
Across the analysis window, forecasts were constructed through segmented modeling of homopolymer, random copolymer, and block copolymer grade tiers; packaging, automotive, and healthcare application channels; and China, Germany, United States, India, and Brazil regional production clusters. CAGRs were derived from elasticity-adjusted demand projections tied to automotive lightweighting specifications and EU Green Deal packaging mandates. Catalyst cost trajectories and recycled-content certification scheme adoption curves served as key industry-specific forecast inputs.
Underlying assumptions cover sustained naphtha-cracking economics and REACH registration cost stability, with deviation risk concentrated in propylene feedstock volatility and mechanical recycling substitution rates in construction applications. Practitioners should keep alternative scenarios live as EU Green Deal recyclability mandate enforcement timelines and bio-based polypropylene production scale-up curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Biopolymer Tubes Market