
 Saudi Arabia Engineering Plastics Market | 2026-2036
Saudi Arabia Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Engineering Plastics Market Insights
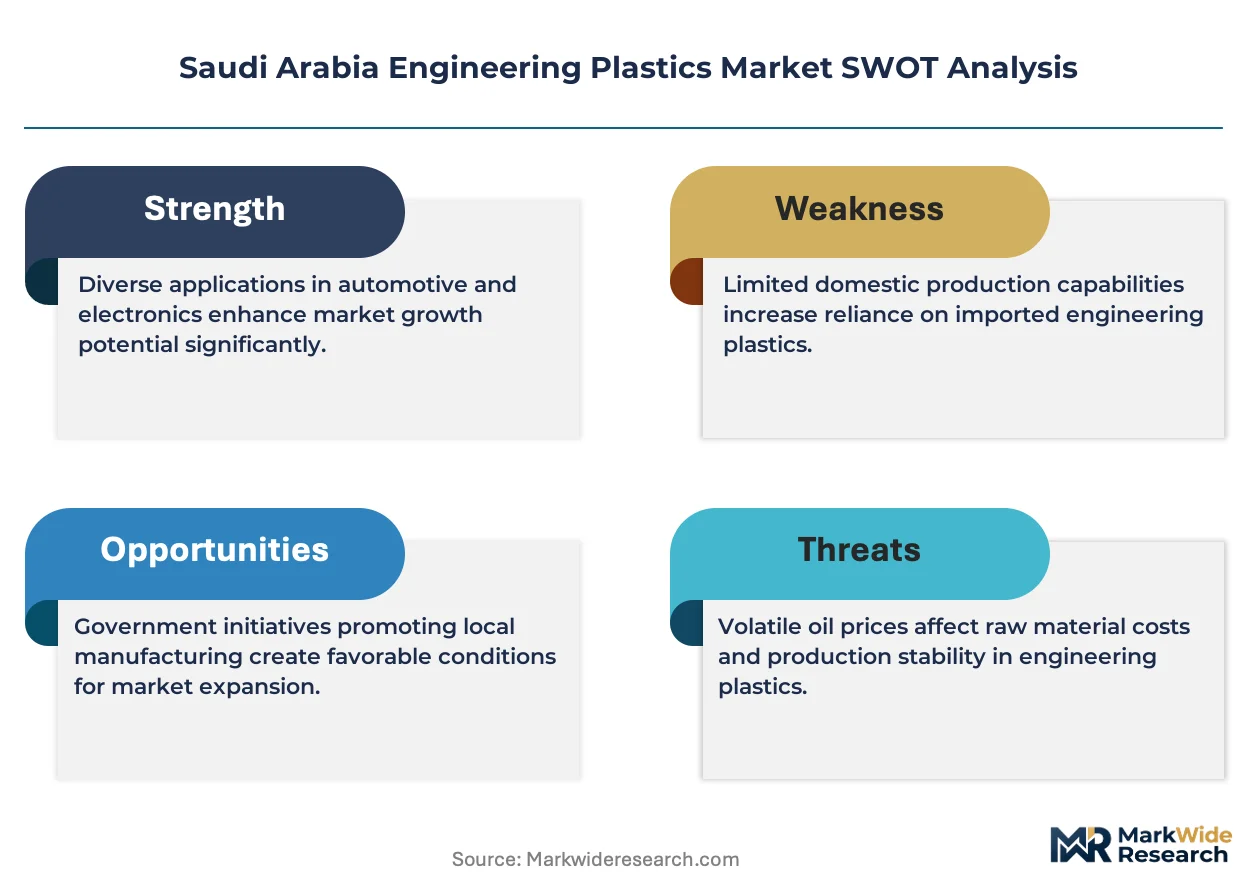
Technical support and formulation customization is pivoting from cost-plus add-ons to core revenue streams for compounders serving the Kingdom. SABIC leverages its integrated cracker-to-polymer position to control feedstock economics for polycarbonate and polyamide grades. Petro Rabigh anchors its Red Sea manufacturing complex with captive aromatics supply for engineering resin precursors. Zamil Plastic competes through specialized compounding services for electrical and electronic applications.
Saudi Arabia engineering plastics encompass thermoplastic polymers with mechanical strength and thermal resistance exceeding commodity grades, typically featuring continuous service temperatures above 150°C and tensile strengths surpassing 40 MPa for load-bearing industrial components. These materials replace metal and ceramic parts in automotive under-hood assemblies, electrical connectors, and aircraft interior structures where weight reduction and corrosion resistance prove critical. Polyamide dominates volume flows into automotive and consumer goods segments due to established processing infrastructure and cost-performance ratios in injection molding operations. Polycarbonate captures premium positioning in electronics and aerospace applications where optical clarity and flame-retardant specifications command higher margin pools.
SFDA material safety protocols and SASO quality conformity requirements shape product certification pathways for engineering plastics entering medical device and food-contact applications within Saudi Arabia. The PLI scheme and Saudi Vision 2030 industrial localization directives are redirecting petrochemical downstream investment toward specialized polymer grades rather than commodity resin exports. Stakeholders must monitor feedstock allocation policies under the Kingdom's dual carbon goals as these determine competitive positioning between local compounders and import-dependent distributors.
Market Dynamics
Automotive lightweighting mandates are compressing metal-to-polymer substitution timelines across Saudi Arabia's Eastern Province manufacturing clusters. Feedstock allocation policies under Vision 2030 dual carbon targets are redirecting cracker output toward higher-margin engineering resin precursors.
Growth Catalysts
- Automotive lightweighting programs:OEMs in Jubail Industrial City are substituting polyamide and polycarbonate for aluminum engine components to meet fuel efficiency targets.
- SASO quality conformity requirements:Electrical and electronics manufacturers must source certified engineering plastics for connector housings, pulling demand toward qualified local compounders.
- Petrochemical downstream localization:Saudi Vision 2030 industrial mandates are redirecting ethylene and benzene streams from commodity exports into captive polyamide and polycarbonate production.
Market Restraints
- Feedstock price volatility:Naphtha and benzene costs fluctuate with crude oil benchmarks, squeezing margin predictability for polycarbonate and polyamide producers.
- Specialized compounding concentration:Technical formulation capabilities cluster around Jubail and Yanbu, creating geographic supply risk for inland manufacturers.
- High-performance thermoset competition:Epoxy and phenolic resins retain cost advantages in extreme-temperature automotive under-hood applications above 200°C continuous service.
Strategic Opportunities
- Medical device certification gap:SFDA material safety protocols for implantable and diagnostic equipment create first-mover advantage for polycarbonate suppliers achieving biocompatibility clearance.
- Red Sea logistics corridor:Petro Rabigh's aromatics-to-resins complex can serve African and Levantine markets with shorter transit than Asian suppliers.
- Recycled-content mandates:Circular economy provisions in Vision 2030 green financing frameworks will reward post-industrial recycled polyamide compounders with preferential credit terms.
Industry Challenges
- Polymer processing engineering shortage:Injection molding technicians with engineering plastics expertise are concentrated at SABIC and Petro Rabigh, leaving mid-tier compounders competing for talent.
- Multi-grade certification timelines:SASO and SFDA parallel approval processes for flame-retardant and food-contact specifications extend product launch cycles by eight to fourteen months.
- Legacy ERP integration:Smaller compounders struggle to connect batch traceability systems with Saudi Aramco feedstock allocation platforms for real-time inventory optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Engineering Plastics Market |
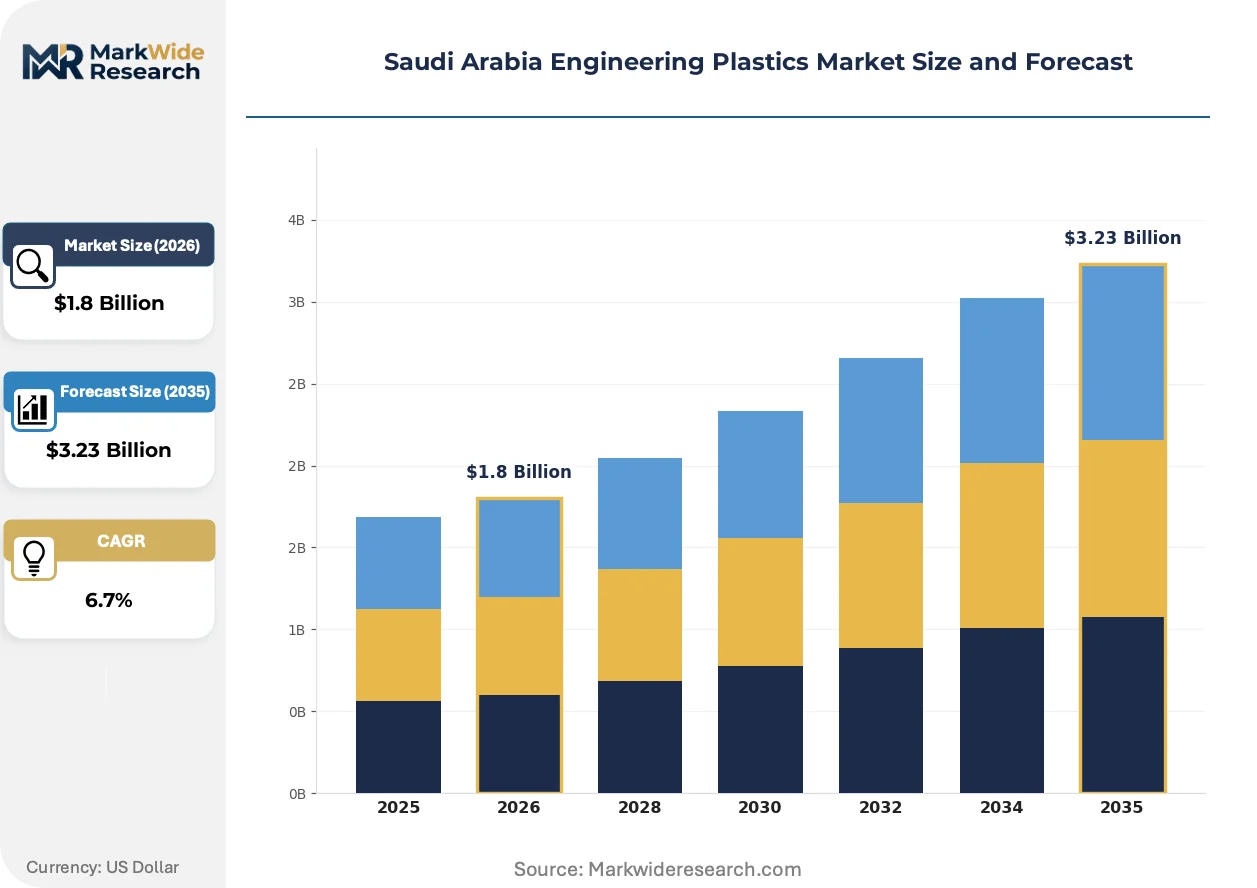
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polystyrene, Polyethylene Terephthalate Application: Automotive, Electronics, Aerospace, Consumer Goods End User: Manufacturers, OEMs, Retailers, Distributors Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | SABIC, Sipchem Company, Petro Rabigh, Zamil Plastic, Tasnee, BASF, Covestro, Solvay SA, Alfa S.A.B. de C.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Engineering Plastics Market Trends and Innovations
Long-fiber thermoplastic injection molding is compressing cycle times and expanding metal replacement possibilities across Saudi Arabia's automotive supply base. Three convergent developments are restructuring competitive positioning.
Long-fiber reinforced polypropylene compounds are overtaking short-glass grades in structural automotive components. Tier-1 suppliers in Jubail are adopting these materials for bumper beams and seat structures, achieving 40% weight reduction versus steel while maintaining crash performance. The technology is overtaking conventional compounding methods by eliminating secondary assembly steps and enabling part consolidation.
SASO technical regulations for electrical equipment safety are tightening flame-retardant specifications for connector housings and switchgear. Manufacturers must reformulate halogen-free polycarbonate and polyamide grades to meet updated smoke density and toxicity thresholds. Medical device and aerospace wire harness segments are absorbing the highest compliance costs, accelerating supplier consolidation around compounders with in-house testing laboratories.
Compounders are unbundling technical support from resin supply contracts, selling formulation development and processing optimization as standalone services. Electrical and electronics OEMs in Riyadh and Dammam are purchasing these services separately from material volumes, shifting supplier relationships from transactional procurement to capability partnerships. This restructuring is most visible in high-mix, low-volume custom compounding for 5G infrastructure and renewable energy connectors.
Saudi Arabia Engineering Plastics Market Segmentation
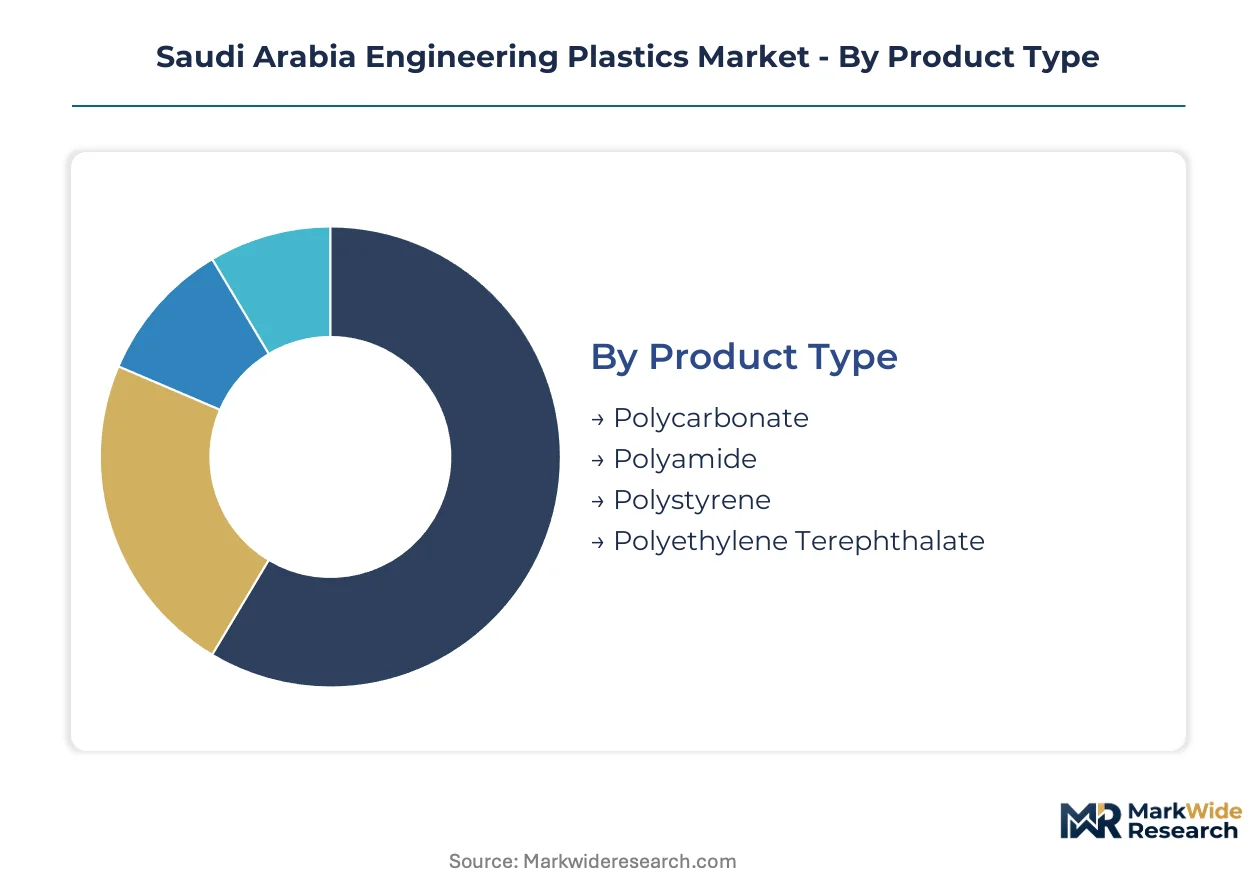
Engineering plastics buyers in Saudi Arabia differentiate sharply by technical specification tolerance, regulatory compliance burden, and feedstock integration requirements. Segmentation reveals where margin pools concentrate and which conversion technologies are capturing capital allocation across Jubail and Yanbu industrial clusters.
Product Type:
Buyers in this category separate by thermal performance thresholds and optical clarity requirements rather than price sensitivity alone.
- Polycarbonate:Amorphous thermoplastic with glass-like transparency and impact resistance exceeding 80 kJ/m². Demand concentrates in electronics housings and medical device manufacturers around Riyadh where SFDA biocompatibility certification creates qualification barriers for imported alternatives.
- Polyamide:Semi-crystalline polymer with continuous service temperatures reaching 150°C and tensile modulus above 2 GPa. Automotive under-hood applications in Jubail Industrial City drive volume, with OEMs substituting glass-filled grades for aluminum intake manifolds to meet fuel efficiency mandates.
- Polystyrene:Rigid amorphous polymer offering dimensional stability and ease of thermoforming for consumer electronics packaging.
- Polyethylene Terephthalate:Crystalline polyester with excellent chemical resistance and barrier properties for food-contact and beverage applications.
Volume sits with polyamide; growth tilts toward polycarbonate as medical device and aerospace wire harness specifications tighten.
Application:
End-use differentiation tracks regulatory intensity and metal replacement potential across Saudi Vision 2030 industrial targets.
- Automotive:Lightweighting programs mandate polymer substitution for powertrain and structural components. Tier-1 suppliers in the Eastern Province are adopting long-fiber reinforced grades for bumper beams, achieving crash performance parity with steel at 40% lower mass.
- Electronics:Connector housings and switchgear require halogen-free flame-retardant formulations meeting revised SASO smoke density thresholds. 5G infrastructure deployments in Riyadh and Dammam are pulling specialized polycarbonate compounds with enhanced signal transparency.
- Aerospace:Interior panel and wire harness applications demand FAR 25.853 fire-smoke-toxicity compliance, limiting qualified supplier pools.
- Consumer Goods:Appliance housings and power tool enclosures prioritize cost-performance balance over extreme thermal specifications.
Revenue concentrates in automotive; margin expansion is steepest in aerospace as certification scarcity protects pricing power.
End User:
Procurement sophistication and formulation development needs distinguish buyers in this dimension.
- Manufacturers:Compounders and converters with captive injection molding capacity seek resin supply with embedded technical support for process optimization.
- OEMs:Automotive and electronics original equipment manufacturers drive specification-setting and qualify suppliers through multi-grade SASO certification timelines.
- Retailers:Distributors serving inland markets beyond Jubail and Yanbu clusters absorb geographic supply risk premiums.
- Distributors:Import-dependent traders face margin pressure from SABIC and Petro Rabigh captive production expansion.
Procurement volume flows through OEMs; technical service revenue is climbing fastest with manufacturers unbundling formulation support from resin contracts.
Technology:
Conversion method selection determines part complexity tolerance and cycle economics for engineering grade polymers.
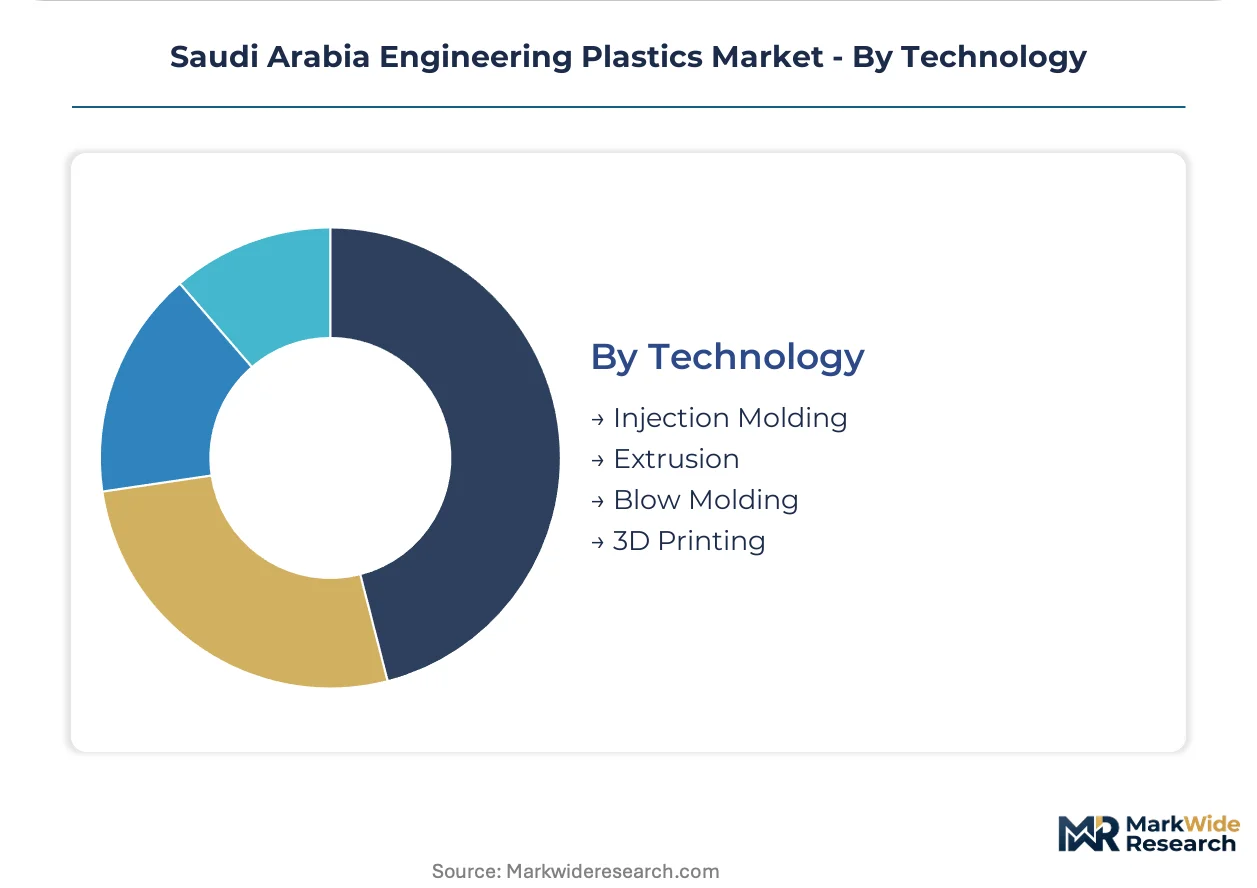
- Injection Molding:Dominant conversion method for high-precision automotive and electronics components. Long-fiber thermoplastic variants are compressing cycle times and enabling part consolidation for structural applications in Jubail manufacturing clusters.
- Extrusion:Profile and sheet production for aerospace interior panels and electrical conduit, requiring melt strength optimization for polycarbonate and polyamide grades.
- Blow Molding:Hollow part production for fluid handling components and technical packaging with barrier layer requirements.
- 3D Printing:Additive manufacturing of prototypes and low-volume end-use parts, with filament suppliers developing carbon-fiber reinforced polyamide for tooling applications.
Installed capacity centers on injection molding; capital allocation is shifting fastest toward 3D printing as OEMs compress prototype-to-production timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors Saudi Arabia's engineering plastics demand through its integrated petrochemical corridor, where SABIC and Petro Rabigh co-locate feedstock production with downstream conversion. The Eastern Province concentrates over sixty percent of domestic compounding capacity. Vision 2030 localization mandates are redirecting investment flows toward specialized polymer grades rather than commodity resin exports.
Eastern Province
Automotive lightweighting programs in Jubail and Yanbu industrial clusters drive polyamide consumption for under-hood metal replacement. SFDA and SASO certification requirements pull electrical manufacturers toward qualified local compounders. Ras Al-Khair Minerals Industrial City is emerging as a secondary conversion hub for mining equipment applications requiring abrasion-resistant engineering grades.
Riyadh
Electronics OEMs and medical device manufacturers in the capital generate premium polycarbonate demand for connector housings and diagnostic equipment. SASO technical regulations for electrical safety tighten flame-retardant specifications, extending supplier qualification timelines. King Salman Energy Park (SPARK) is attracting compounders seeking proximity to renewable energy and 5G infrastructure projects.
Western Region
Red Sea logistics corridors through Yanbu and Jeddah enable export-oriented production serving African and Levantine markets. Petro Rabigh's captive aromatics supply anchors polycarbonate precursor production with shorter transit than Asian competitors. King Abdullah Economic City is developing specialized warehousing for temperature-sensitive engineering resin distribution.
NEOM Northwest
Circular economy provisions in Vision 2030 green financing frameworks are incentivizing post-industrial recycled polyamide compounders to establish pilot facilities. The zone's renewable energy infrastructure supports low-carbon polymer processing for export to European markets with carbon border adjustment exposure. Oxagon industrial city plans include dedicated zones for advanced materials R&D.
Saudi Arabia Engineering Plastics Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light specialized compounders for specification-setting influence with OEMs. The market structures around three tiers: petrochemical majors with cracker-to-polymer control, regional compounders with formulation expertise, and import-dependent distributors serving inland markets. Dominant competitive moves include backward integration into precursor production and unbundling of technical services from resin supply contracts.
Within the integrated producer tier, SABIC and Petro Rabigh anchor feedstock economics for polycarbonate and polyamide grades through captive ethylene and aromatics supply. Among specialized compounders, Zamil Plastic occupies a position serving electrical and electronics applications with customized formulation capabilities. BASF and Covestro represent the multinational archetype, leveraging global R&D networks to introduce halogen-free flame-retardant grades for SASO compliance. These players exemplify how technical support and certification management are displacing price as the primary procurement criterion.
| Leading Market Players |
|---|
| SABIC |
| Sipchem Company |
| Petro Rabigh |
| Zamil Plastic |
| Tasnee |
| BASF |
| Covestro |
| Solvay SA |
| Alfa S.A.B. de C.V. |
| Others |
Pricing and Supply Chain Analysis
SASO flame-retardant certification upgrades for electrical connectors are forcing compounders to absorb reformulation costs or pass them downstream, compressing margins for distributors lacking in-house testing capabilities. This specification tightening concentrates procurement power with Jubail-based suppliers possessing captive SASO laboratory access, widening price spreads between qualified and unqualified resin sources.
Pricing Analysis
Margin tightening in standard-grade polyamide reflects SABIC and Petro Rabigh captive production expansion, which eliminates import arbitrage for distributors. Pricing stratifies across medical-grade polycarbonate, automotive-certified polyamide, and general-purpose compounds, with SFDA biocompatibility clearance commanding substantial premiums. Cost-down pressure on commodity grades accelerates because inland manufacturers face freight disadvantages versus Eastern Province clusters. Electrical OEMs in Riyadh demonstrate highest price sensitivity, while aerospace wire harness buyers accept premium positioning for FAR 25.853 compliance.
Supply Chain Analysis
SFDA and SASO parallel approval processes extending product launch cycles by eight to fourteen months are gating supply relationships and favoring compounders with embedded regulatory affairs teams. Feedstock supply concentrates in Saudi Arabia, South Korea, and Germany for benzene-derived polycarbonate precursors, while naphtha-based polyamide chains draw from Singapore and Japan. Raw material dependencies rest on naphtha, benzene, and adipic acid streams tied to crude oil benchmarks. Single-source vulnerability emerges from concentrated aromatics production at Petro Rabigh. Distribution runs through Jubail and Yanbu industrial clusters for domestic offtake, with Red Sea corridors serving African re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where SFDA material safety protocols and SASO quality conformity requirements erect barrier-to-entry moats protecting compounders with invested certification infrastructure.
For Market Incumbents: Hedge against margin erosion in commodity grades by deepening captive feedstock integration through Saudi Aramco allocation platform connectivity. Secure technical talent pools through apprenticeship pipelines with King Fahd University polymer engineering programs, addressing the acute shortage of injection molding specialists. Defensive positioning requires unbundling formulation services as standalone revenue streams before import-dependent distributors develop comparable capabilities. For New Entrants and Emerging Players: Long-fiber thermoplastic compounding expertise offers entry leverage into automotive structural component supply chains where Tier-1 suppliers seek qualified second sources. White-space concentration sits with post-industrial recycled polyamide for NEOM circular economy pilots, where green financing frameworks reward early movers with preferential credit terms. Target medical device polycarbonate segments in Riyadh where SFDA biocompatibility clearance scarcity protects pricing power. Go-to-market positioning should emphasize rapid SASO certification completion versus established players' backlog. For Investors and Strategic Acquirers: The window for entry favors specialized compounders with demonstrated SASO and SFDA approval track records over commodity resin traders facing margin compression. Long-term viability across the analysis window hinges on feedstock allocation security under Vision 2030 dual carbon policies. Acquisition screening should prioritize firms with embedded testing laboratories and OEM qualification relationships. The signal to watch is Saudi Aramco cracker output reallocation announcements, which would indicate feedstock cost inflection for integrated versus non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatics | Petro Rabigh's captive benzene supply anchors polycarbonate cost competitiveness versus Asian imports. |
| Long-term Supply Agreement | SABIC leverages integrated cracker-to-polymer position to lock in automotive OEM volume commitments. |
| Green Manufacturing Transition | NEOM renewable energy infrastructure enables low-carbon polyamide processing for European export markets. |
| Joint Venture | Zamil Plastic partnerships with electrical OEMs embed formulation services within customer R&D cycles. |
| Capacity Expansion | Jubail cluster compounders add long-fiber thermoplastic lines to capture automotive metal replacement demand. |
Research Methodology
Trade statistics from Saudi Customs Authority, SABIC annual disclosures, and SASO technical regulation filings formed the secondary backbone, cross-referenced with primary interviews involving polymer plant managers, automotive Tier-1 procurement leads, electrical OEM technical directors, and compounder distribution channel partners. Bottom-up volume estimates derived from injection molding machine installation data across Jubail and Yanbu industrial clusters were reconciled with top-down petrochemical feedstock allocation flows from Saudi Aramco.
Bottom-up modeling tracked grade-specific consumption across automotive under-hood, electronics housing, medical device, and aerospace interior applications, while top-down validation assessed cracker output redirection under Vision 2030 localization mandates. Segmentation dimensions included product type, application vertical, end-user procurement sophistication, and conversion technology. CAGRs were computed from normalized baseline values through iterative reconciliation of demand-side uptake curves and supply-side capacity announcements. Industry-specific forecast inputs incorporated SFDA certification pipeline timelines and long-fiber thermoplastic adoption rates in structural automotive components.
Several conditions sit outside the modeled scope, including potential feedstock price volatility from crude oil benchmark movements, abrupt SASO regulatory amendments, and geopolitical disruptions to Red Sea logistics corridors. Forecasts reflect assumptions regarding sustained automotive lightweighting program commitment and stable Vision 2030 industrial localization policy continuity. A model refresh is warranted upon material change in Saudi Aramco aromatics allocation policy or SFDA medical device material safety protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
N-Vinylformamide Market