
 Europe Pressure Sensitive Adhesives (PSA) Market | 2026-2036
Europe Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pressure Sensitive Adhesives (PSA) Market Foresight
Automotive Suppliers is repositioning demand toward high-performance bonding tapes as electric vehicle platforms shed mechanical fasteners. Henkel AG & Co. KGaA leverages its European manufacturing footprint to serve this transition with tailored acrylic systems. H.B. Fuller Company anchors its position through specialized adhesive films for interior laminate assemblies. Dow competes on silicone chemistry leadership for thermal management applications in battery modules.
Pressure Sensitive Adhesives are viscoelastic materials that bond to surfaces upon light pressure without solvent activation or heat curing, typically formulated with tackifying resins in acrylic, rubber, or silicone bases and applied at coating weights between 20-100 grams per square meter for industrial tapes and labels. Acrylic formulations dominate volume in Europe due to their UV stability and broad substrate compatibility, while silicone commands premium positioning in electronics and medical applications where temperature resistance exceeds 150 degrees Celsius. The Tapes form captures substantial share through logistics and e-commerce fulfillment channels, whereas Protective Films applications are expanding fastest as display manufacturers adopt temporary surface guarding during assembly.
REACH and the EU Green Deal shape formulation requirements by restricting volatile organic compounds and mandating recyclability disclosures across adhesive supply chains. ECHA substance evaluations periodically reclassify tackifier chemistries, forcing reformulation investments among European producers. Stakeholders must monitor upcoming polymer registration obligations and assess bio-based feedstock partnerships before compliance deadlines tighten raw material sourcing options.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing solvent-free formulation transitions across European adhesive supply chains, compressing reformulation timelines while opening premium positioning for compliant producers.
Growth Catalysts
- Electric vehicle platform expansion:Automotive OEMs are specifying pressure-sensitive bonding tapes to replace mechanical fasteners in battery module assembly, pulling demand toward high-performance acrylic systems.
- REACH substance restrictions:ECHA reclassifications of legacy tackifier chemistries are accelerating investment in bio-based resin alternatives among German and French formulators.
- Display manufacturing clustering:Temporary protective film applications are expanding as Czech and Polish electronics assembly hubs deepen procurement for surface guarding during panel production.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and tackifier resin costs fluctuate with naphtha and crude oil pricing, compressing margin stability for European coaters.
- Specialty silicone supply concentration:Precursor chemicals for high-temperature PSA grades concentrate among a limited set of German and Swiss suppliers, creating bottleneck risk.
- Recyclability disclosure mandates:CSRD and EU Green Deal reporting requirements impose documentation burdens that smaller formulators lack systems to satisfy.
Strategic Opportunities
- Eastern European packaging expansion:Underpenetrated demand in Hungary and Romania offers volume growth as e-commerce fulfillment infrastructure modernizes.
- Medical-grade silicone tapes:Emerging wound care and wearable device applications in Scandinavia command premium pricing for biocompatible, hypoallergenic formulations.
- Removable adhesive innovation:Circular economy mandates under the EU Green Deal are creating specification pull for debondable tapes in recyclable packaging designs.
Industry Challenges
- Polymer registration expertise gaps:ECHA polymer registration obligations require toxicology and dossier preparation capabilities that mid-tier formulators struggle to staff.
- Coating line reconfiguration costs:Solvent-to-hotmelt process conversions demand capital outlays for drying system replacement that strain balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pressure Sensitive Adhesives (PSA) Market |
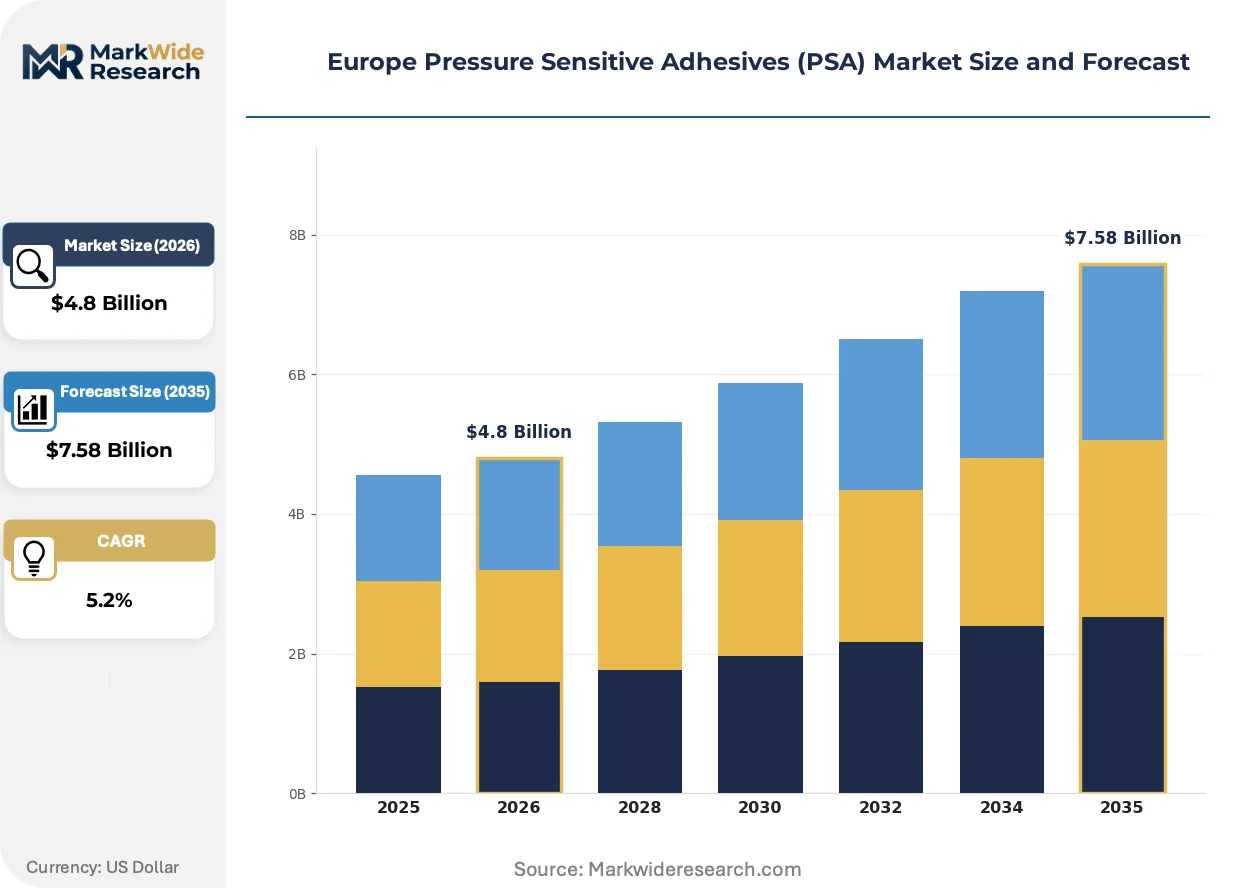
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Rubber-Based, Silicone, Polyurethane, Ethylene-Vinyl Acetate Form: Rolls, Sheets, Tapes, Films, Dots Application: Packaging, Electronics Assembly, Labeling, Protective Films, Decorative Laminates End User Industry: Consumer Goods Manufacturers, Electronics Fabricators, Printing Services, Construction Firms, Automotive Suppliers |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, Dow, Sika AG, Wacker Chemie AG, Jowat SE, Avery Dennison, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pressure Sensitive Adhesives (PSA) Market Shifts & Advancements
Hotmelt coating technology is displacing solvent-based processes as the dominant European production method, while digital printing integration and bio-based feedstock development reshape product specifications across end-use verticals.
UV-curable acrylic hotmelt systems are integrating into European tape manufacturing lines to eliminate solvent emissions and reduce energy consumption during coating operations. Automotive suppliers in Stuttgart and Wolfsburg are specifying these systems for interior laminate bonding where VOC thresholds have tightened. The technology is integrating thermal management and acoustic damping functions into single-layer adhesive constructions that previously required multi-material stacks.
REACH authorization requirements for diisocyanates and certain tackifier derivatives are compelling reformulation investments across the European supply base. Formulators must submit substitution plans or cease use of restricted substances by designated sunset dates. Medical device and electronics segments in Germany and the Netherlands are responding fastest, qualifying alternative chemistries ahead of compliance deadlines to secure supply continuity.
Direct procurement relationships between large automotive OEMs and adhesive coaters are compressing distributor roles in the European supply chain. Tier-1 suppliers in Bavaria and Baden-Württemberg are establishing qualification programs that bypass traditional chemical distribution for specified bonding tape grades. This pattern is most visible in electric vehicle battery assembly, where OEMs specify adhesive performance parameters directly to secure thermal runaway protection and crashworthiness certification.
Europe Pressure Sensitive Adhesives (PSA) Market Segmentation
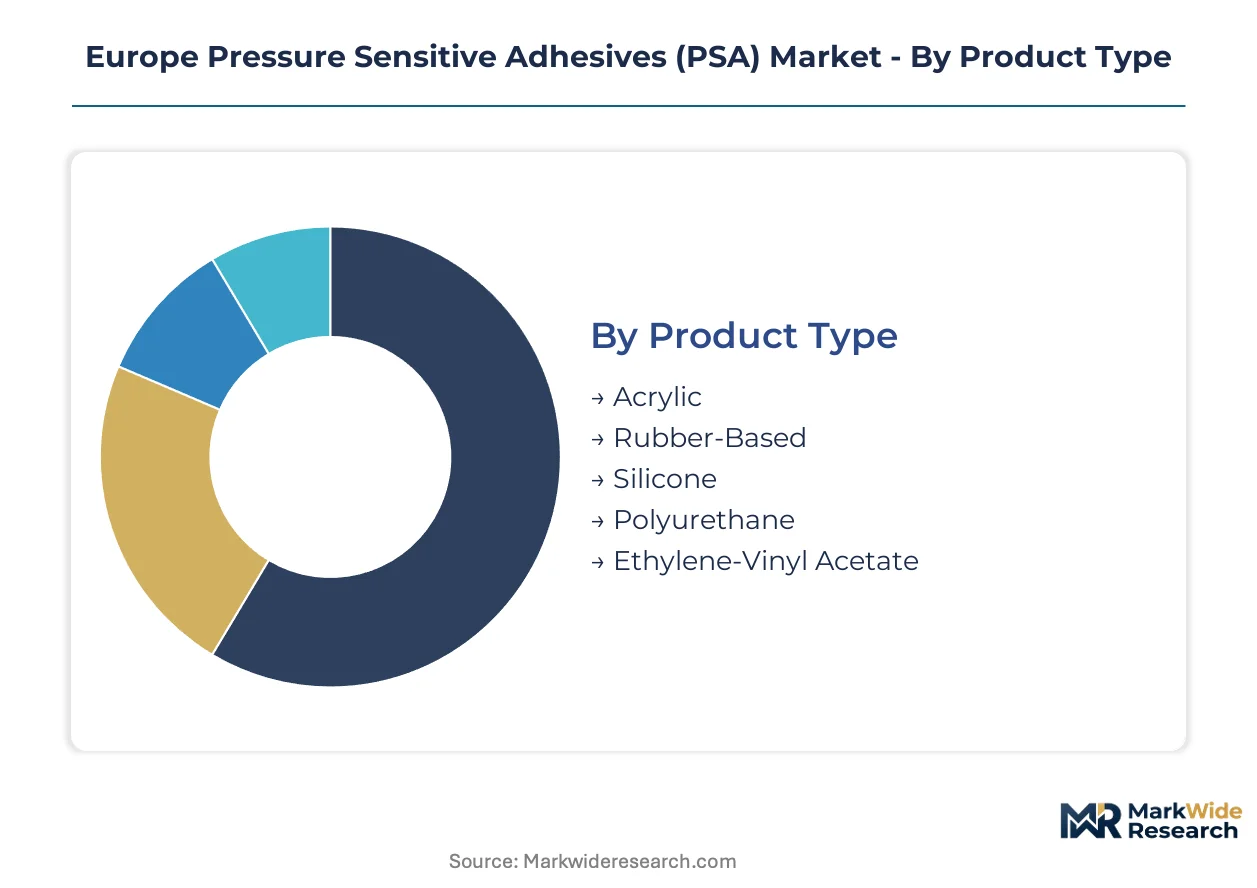
Segmentation in the European PSA market reveals how formulation chemistry, physical format, and end-use specifications create distinct competitive arenas. Each axis carries different margin profiles, regulatory exposure, and customer concentration patterns that reshape supplier priorities across the region.
Product Type:
Technology leadership and temperature performance separate the chemistry tiers, with acrylic and silicone commanding distinct specification roles.
- Acrylic:UV-stable copolymers formulated with tackifying resins deliver broad substrate compatibility and outdoor durability. German packaging converters and French automotive suppliers concentrate procurement here for cost-performance balance under REACH substance evaluations.
- Silicone:Polydimethylsiloxane-based systems tolerate continuous exposure above 150 degrees Celsius without degradation. Electronics fabricators in the Netherlands and medical device manufacturers in Scandinavia specify these for thermal management and biocompatible skin contact applications.
- Rubber-Based:Natural and synthetic rubber formulations with rosin or hydrocarbon tackifiers serve cost-sensitive industrial bonding.
- Polyurethane:Moisture-curable systems offer aggressive adhesion to low-surface-energy plastics.
- Ethylene-Vinyl Acetate:Hotmelt-compatible copolymers integrate into high-speed coating operations for disposable applications.
Mature deployment sits with Acrylic. Newer deployment is concentrated in Silicone.
Form:
Physical configuration dictates coating capital intensity and logistics economics, with rolls and tapes capturing divergent value chain positions.
- Tapes:Slit rolls with defined width and length specifications serve logistics, automotive assembly, and construction sealing. E-commerce fulfillment infrastructure expansion across Poland and Czechia pulls demand toward pressure-sensitive carton sealing and temporary holding applications.
- Films:Cast or extruded carrier layers with thin adhesive coatings guard surfaces during manufacturing and shipping. Display panel producers in Slovakia and Hungary specify temporary protective films for scratch prevention during module assembly.
- Rolls:Master rolls for downstream slitting and converting operations supply label stock and industrial tape manufacturers.
- Sheets:Die-cut or rectangular formats serve point-of-purchase display and gasketing applications.
- Dots:Pre-cut circular or shaped adhesive elements enable automated assembly in electronics and medical device production.
Volume concentration centers on Rolls for downstream conversion. Value capture is climbing fastest in Films.
Application:
Functional purpose determines specification stringency, with temporary versus permanent bonding creating divergent qualification barriers.
- Packaging:Corrugated box sealing, flexible film lamination, and retail label attachment consume the largest volume share. German and Italian food and beverage producers drive specification for recyclable adhesive compatibility under EU Green Deal circular economy mandates.
- Electronics Assembly:Component mounting, thermal interface materials, and display bonding require cleanroom-grade formulations. Battery module assemblers in Stuttgart and Wolfsburg specify pressure-sensitive alternatives to mechanical fasteners for electric vehicle platform weight reduction.
- Labeling:Pressure-sensitive face stocks with release liners serve retail, logistics, and pharmaceutical identification.
- Protective Films:Temporary surface guarding during manufacturing and installation prevents scratch damage on delicate substrates.
- Decorative Laminates:Furniture, automotive interior, and architectural panel bonding combine aesthetic and functional requirements.
Specification maturity resides in Packaging. Steepest expansion trajectory appears in Electronics Assembly.
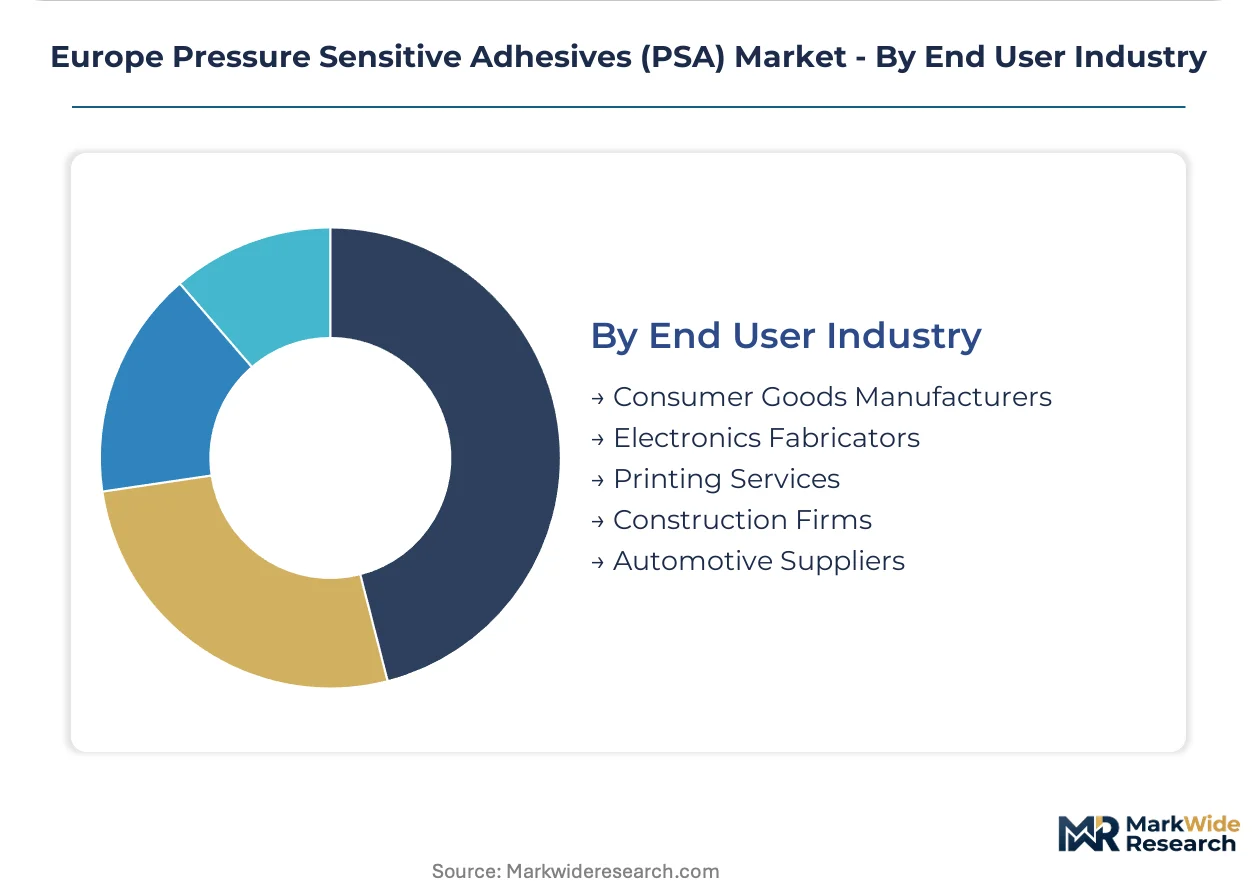
End User Industry:
Customer scale and technical capability separate procurement patterns, with automotive and electronics demanding direct supplier relationships.
- Automotive Suppliers:Tier-1 and Tier-2 manufacturers specify bonding tapes for interior lamination, exterior trim attachment, and battery module assembly. Bavarian and Baden-Württemberg suppliers establish direct qualification programs with adhesive coaters, bypassing traditional distribution channels for critical bonding grades.
- Electronics Fabricators:Display, semiconductor, and device assembly operations require ultra-clean, low-outgassing formulations. Czech and Polish electronics clusters deepen procurement for temporary surface protection and component mounting as regional manufacturing capacity expands.
- Consumer Goods Manufacturers:Personal care, household product, and food packaging producers specify labels and sealing tapes.
- Printing Services:Commercial label converters and flexible packaging printers purchase master roll stock for downstream finishing.
- Construction Firms:Building envelope sealing, flooring installation, and temporary protection applications utilize industrial-grade tapes and membranes.
Established relationships dominate Consumer Goods Manufacturers. Procurement restructuring is most pronounced in Automotive Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and France while consumption spreads across Central European manufacturing clusters. REACH compliance costs and F-Gas Regulation mandates reshape competitive positioning between coating hubs and downstream converting centers.
Germany
Automotive battery assembly and packaging machinery drive specification intensity for acrylic hotmelt systems. ECHA polymer registration obligations force mid-tier coaters toward specialized toxicology consulting partnerships. Stuttgart and Wolfsburg clusters anchor direct procurement relationships between OEMs and adhesive suppliers for electric vehicle platform bonding.
France
Food packaging converters and luxury goods label producers pull demand toward recyclable adhesive compatibility. EU Green Deal circular economy mandates accelerate bio-based resin qualification programs among Paris-region formulators. Lyon and Grenoble electronics fabricators expand temporary protective film consumption for display module surface guarding.
Netherlands
Semiconductor packaging and medical device assembly require ultra-clean silicone formulations with low outgassing profiles. CSRD reporting requirements impose documentation systems that smaller coaters struggle to implement. Eindhoven and Amsterdam logistics hubs deepen procurement for e-commerce carton sealing tapes as fulfillment infrastructure scales.
Poland
Electronics manufacturing clustering and automotive supplier relocation pull coating capacity eastward. F-Gas Regulation compliance timelines compress reformulation windows for solvent-dependent producers. Warsaw and Krakow display assembly operations expand temporary protective film specifications for panel production surface protection.
Italy
Furniture laminate and decorative panel bonding sustain rubber-based adhesive demand in cost-sensitive segments. REACH substance evaluations periodically reclassify tackifier chemistries, forcing reformulation investments. Milan and Turin packaging converters qualify removable adhesive systems for recyclable packaging designs under extended producer responsibility frameworks.
Europe Pressure Sensitive Adhesives (PSA) Market Competitive Landscape
Top-tier vendors anchor specification-driven premium tiers, while mid-cap specialists occupy regional converting niches. The European PSA market structures around three strategic archetypes: integrated chemical conglomerates with captive resin supply, specialized adhesive coaters with vertical control over formulation IP, and regional converters with logistics-scale coating assets. Competitive moves concentrate on solvent-to-hotmelt process conversions and direct OEM qualification programs that bypass traditional distribution channels.
Among diversified chemical conglomerates, 3M, Henkel AG & Co. KGaA, and Dow exemplify scale-driven positioning across multiple chemistry platforms. These entities occupy positions where regulatory compliance capabilities and polymer registration expertise create defensive moats against mid-tier competitors. Their geographic footprints span multiple European coating sites, enabling localized service to automotive and electronics clusters without cross-border logistics exposure.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| Dow |
| Sika AG |
| Wacker Chemie AG |
| Jowat SE |
| Avery Dennison |
| Others |
Supply & Pricing Matrix
The EU Green Deal gates qualified supply and premium-tier pricing access by mandating solvent-free formulations that only capitalized coaters can deliver. REACH polymer registration obligations concentrate compliant capacity among German and French producers with toxicology dossier capabilities, compressing availability for standard-grade acrylic systems while elevating pricing power for certified alternatives.
Pricing Analysis
Margin tightening in standard-grade acrylic tapes reflects naphtha-linked monomer cost volatility and Hungarian converter price competition. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered silicone systems from commodity hotmelts and unregistered imports. Cost-down pressure on rubber-based industrial tapes accelerates because Czech and Polish buyers consolidate procurement volumes. Automotive OEMs in Bavaria exhibit lowest price sensitivity for battery module bonding grades, while Italian furniture laminators drive hardest bargain on decorative adhesive films.
Supply Chain Analysis
Reverse-logistics flows for release liner recycling and adhesive waste recovery are emerging as qualification requirements under extended producer responsibility frameworks. Raw material supply concentrates in Germany, Belgium, and the Netherlands where petrochemical crackers feed acrylic monomer and tackifier resin production. Formulation draws from specialty silicone precursors concentrated among Swiss and German suppliers, creating single-source vulnerability for high-temperature grades. Distribution runs through regional converting hubs in Poland and Czechia that slit master rolls for downstream label and tape manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty silicone precursor capacity constraints prop pricing for high-temperature grades, creating supply-constrained conditions that favor incumbents with captive resin relationships.
For Market Incumbents: Lock in polymer registration expertise through ECHA consultant retainers before sunset dates eliminate mid-tier competitors. Secure backward integration into bio-based tackifier supply via Nordic forestry partnerships to defend margin position against REACH-driven reformulation costs. For New Entrants and Emerging Players: Regional converters in Hungary and Romania offer partnership pathways to bypass established distribution channels. Target medical-grade silicone tape specifications in Scandinavian wound care markets where biocompatibility premiums offset qualification investments. Pursue direct qualification with Warsaw and Krakow display assemblers for temporary protective film supply. For Investors and Strategic Acquirers: ECHA polymer registration deadline extensions are the leading indicator that distressed mid-tier coating assets will surface for acquisition. Frame long-term viability around solvent-to-hotmelt conversion capabilities and direct OEM relationships. Monitor F-Gas Regulation enforcement intensity in Poland as the signal for Eastern European capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Secures compliant feedstock supply for EU Green Deal formulations ahead of REACH reclassifications. |
| Hotmelt Coating Line Conversion | Eliminates solvent emissions to satisfy F-Gas Regulation while reducing Stuttgart automotive supplier qualification cycles. |
| Direct OEM Qualification Programs | Bypasses traditional chemical distribution for Bavarian battery module bonding tape specifications. |
| Medical-Grade Silicone Certification | Opens Scandinavian wound care and wearable device markets with biocompatible formulation premiums. |
| Eastern European Converting Partnership | Captures underpenetrated Hungarian and Romanian e-commerce packaging demand with localized slitting capacity. |
Research Methodology
Multi-period observation of acrylic monomer pricing spreads, ECHA substance evaluation timelines, and automotive platform bonding specifications anchored the trend analysis, supplemented by interviews with adhesive plant managers, procurement leads at German Tier 1 suppliers, distribution channel partners in Poland, and technical R&D directors at French formulators. Secondary validation drew from Cefic chemical industry reports, customs trade data for PSA-coated product flows, SEC filings of listed adhesive producers, and REACH registration dossiers. Bottom-up coating capacity estimates and top-down end-use consumption models were triangulated against import-export statistics.
Input-output matrices mapped formulation chemistry, physical form, and end-use application dimensions across the projection horizon to generate segment-level volume and value estimates. Analytical frameworks incorporated grade tier differentiation, regional production hub cost structures, and packaging format requirements. CAGRs were derived from fitted trend extrapolation moderated by technology substitution elasticity parameters. Forecast inputs included electric vehicle platform penetration curves and display manufacturing capacity buildouts in Czechia and Poland.
Caveats apply where ECHA substance reclassifications, petrochemical feedstock price spikes, or F-Gas Regulation enforcement intensity could materially shift the outlook. Practitioners should monitor REACH polymer registration compliance rates and bio-based resin cost parity milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Skin Adhesives Market