
 Africa Automotive Refinish Coatings Market | 2026-2036
Africa Automotive Refinish Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Automotive Refinish Coatings Market Outlook
Automotive refinish distribution across Africa is fragmenting as multinational suppliers compete with regional traders for shelf space in independent body shops. PPG Industries leverages its training center network to anchor technician loyalty in key urban hubs. AkzoNobel N.V. sustains premium positioning through color-matching technology investments. KAPCI Coatings specializes in value-tier formulations that dominate price-sensitive North African markets.
Automotive refinish coatings are solvent-borne or water-borne formulations applied to vehicle exteriors after collision repair or cosmetic restoration, typically requiring 15-25 micron dry film thickness and compatibility with OEM color standards. Their primary purpose is restoring aesthetic finish and corrosion protection to damaged or aged vehicle substrates. Base coat systems lead volume consumption due to color-layer requirements across diverse vehicle fleets, while clear coat segments capture disproportionate margin pools from UV-durability premiums. Professional painters represent the fastest-growing end-user category as fleet operators outsource repair rather than maintain in-house capability.
South Africa's National Regulator for Compulsory Specifications enforces SABS standards for coating VOC content, while Nigeria's Standards Organisation mandates product registration for imported refinish chemicals. Egypt's environmental compliance framework is tightening discharge limits for solvent-borne operations near Cairo industrial zones. Stakeholders must monitor which national regulators harmonize with EU REACH protocols versus those maintaining independent certification requirements.
Market Dynamics
Fleet operators across East Africa are outsourcing collision repair to registered body shops, accelerating professionalization of a historically informal sector. South Africa's Department of Transport enforcement of roadworthiness standards is tightening compliance requirements for bodywork repairs, pushing independent shops toward certified coating systems.
Growth Catalysts
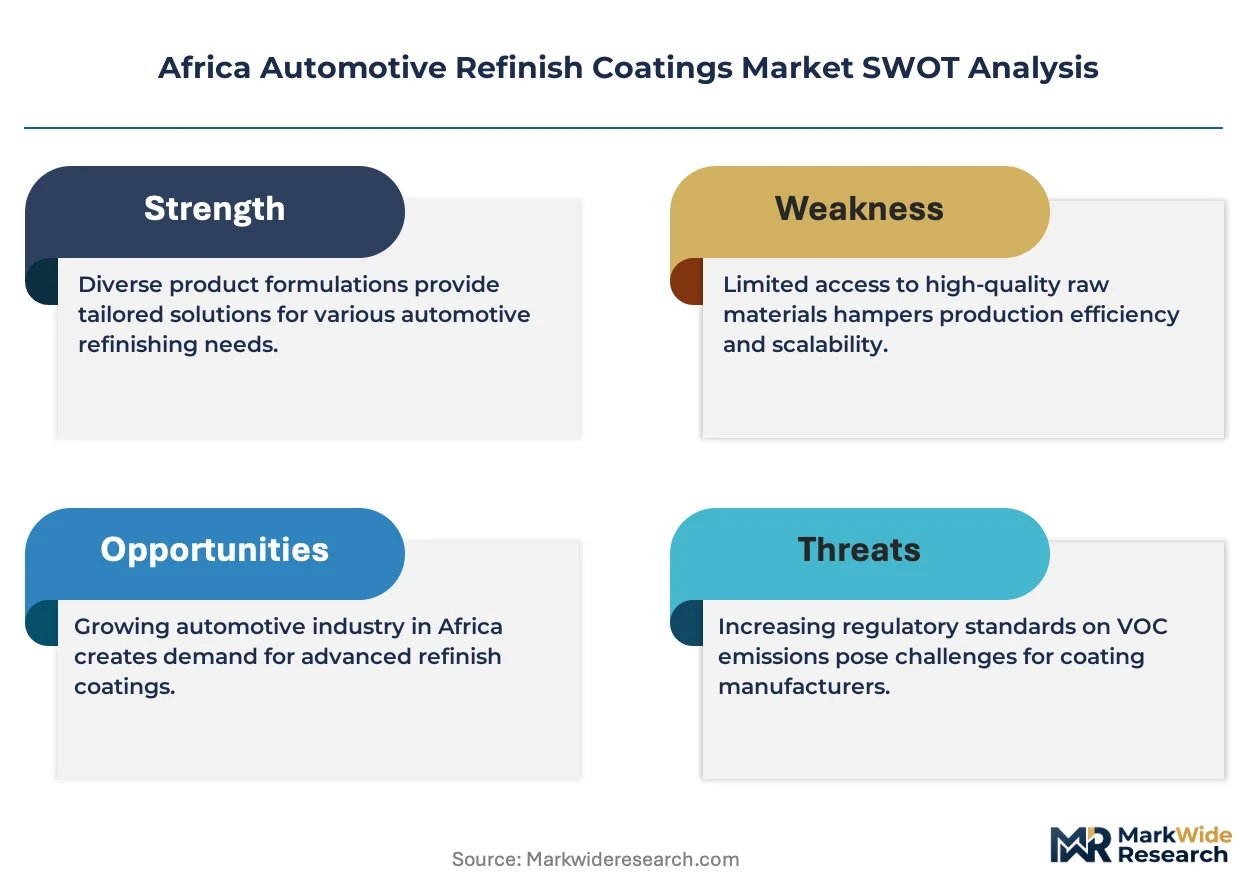
- Vehicle Parc Aging:East African commercial fleets are extending service life beyond 12 years, generating sustained demand for cosmetic restoration and corrosion protection across Kenya and Tanzania transport corridors.
- SABS VOC Standards:South Africa's National Regulator for Compulsory Specifications mandates reduced solvent-borne coating content, forcing shop upgrades that favor compliant professional suppliers.
- Lagos-Ibadan Formalization:Nigeria's informal repair clusters are registering as licensed body shops to access fleet contracts, creating captive demand for standardized refinish systems.
Market Restraints
- Pigment Import Dependency:Specialty colorants and effect pigments concentrate in European and Asian supply bases, exposing African formulators to currency volatility and extended lead times.
- Solvent Cost Volatility:Petrochemical-derived thinners and reducers fluctuate with crude price movements, compressing margins for value-tier water-borne product lines.
- Technical Labor Scarcity:Certified spray booth operators and color-matching technicians remain concentrated in Johannesburg and Cairo, constraining shop expansion into secondary cities.
Strategic Opportunities
- Ethiopian Fleet Privatization:State-owned transport assets are transferring to private operators who lack in-house repair capability, creating first-mover advantage for professional refinish networks.
- Digital Color Matching:Spectrophotometer and cloud-based formula databases are reducing rework rates, enabling remote technical support for isolated body shops.
- Egyptian Environmental Compliance:Cairo industrial zone discharge limits for solvent-borne operations are accelerating water-borne system adoption near the Suez Canal logistics corridor.
Industry Challenges
- Certification Timeline Compression:Nigeria's Standards Organisation mandates product registration for imported refinish chemicals, creating 6-12 month approval delays that disrupt inventory planning.
- Skill Transfer Bottlenecks:PPG Industries' training center model requires sustained technician retention, but migration to Gulf states drains qualified painters from Accra and Nairobi hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Automotive Refinish Coatings Market |
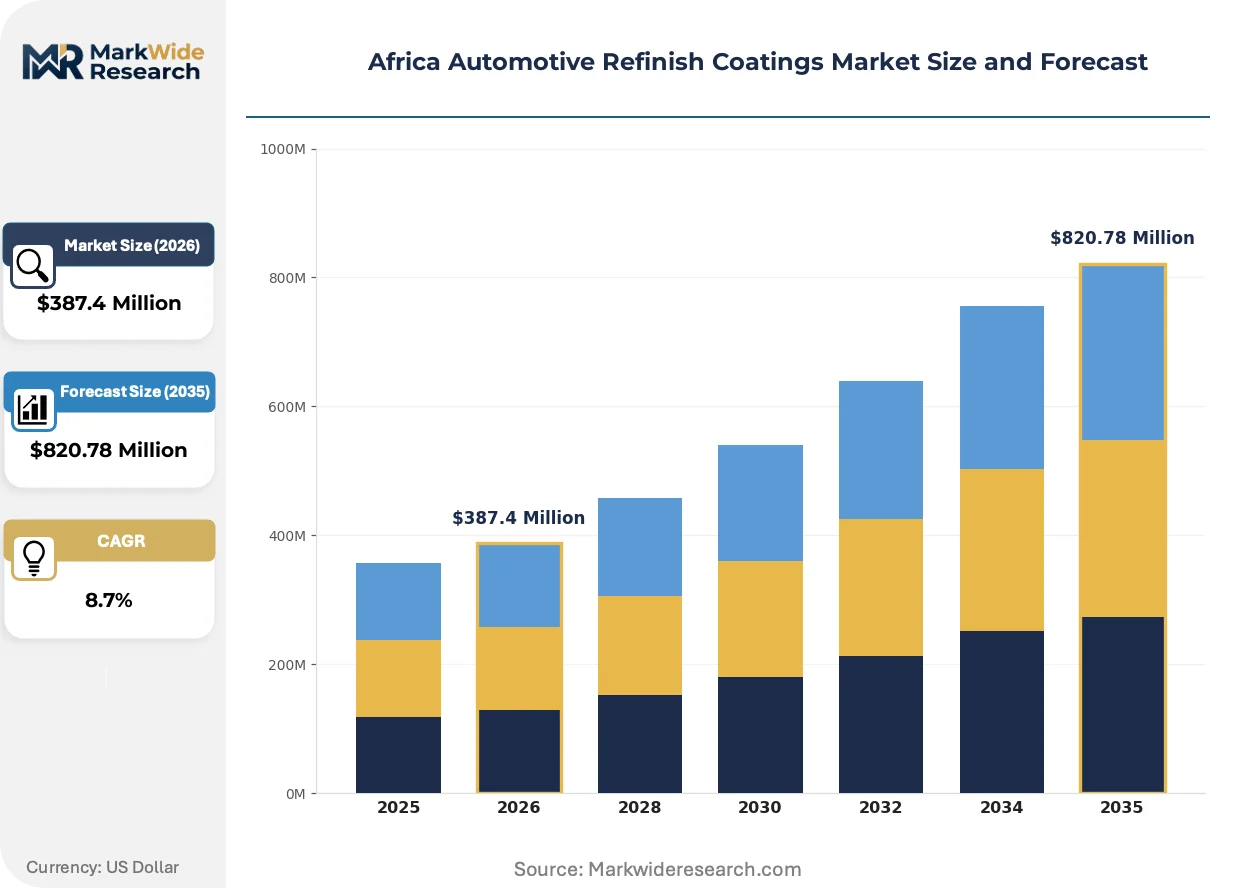
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Base Coat, Clear Coat, Primer, Single Stage Application Type: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Retail, Online, Wholesale, Direct Selling End User: Body Shops, DIY Users, Professional Painters, Fleet Operators |
| Companies Covered | AkzoNobel N.V., PPG Industries, Axalta Coating Systems, BASF SE, 3M Company, Kansai Paint Co., Nippon Paint Holdings Co., KAPCI Coatings, Covestro AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Automotive Refinish Coatings Market Strategic Shifts
Water-borne base coat chemistry is displacing solvent-borne systems across African urban centers, driven by indoor air quality enforcement and technician health liability concerns. Digital color retrieval platforms are compressing the matching cycle from hours to minutes.
Hybrid coating systems are hybridizing water-borne base coat chemistry with UV-curable clear coat technology, enabling same-day vehicle delivery. Professional painters in Johannesburg and Lagos are adopting these stacked formulations to capture fleet maintenance contracts with downtime penalties. The convergence is compressing shop throughput cycles and displacing conventional two-day repair schedules.
South Africa's National Regulator for Compulsory Specifications enforces SABS standards for coating VOC content in spray booth operations. Shops in Durban and Cape Town are retrofitting ventilation and filtration infrastructure to maintain operating licenses. Water-borne base coat segments are capturing disproportionate volume growth in compliance-heavy metropolitan zones.
Fleet procurement departments are unbundling repair services from insurance-mediated claims, establishing direct service contracts with certified body shops. Transport operators in Kenya's Mombasa-Nairobi corridor are consolidating vendor lists to three approved suppliers per region. This concentration is visible in Lagos where registered shops now bid quarterly for petroleum tanker fleet contracts.
Africa Automotive Refinish Coatings Market Segmentation
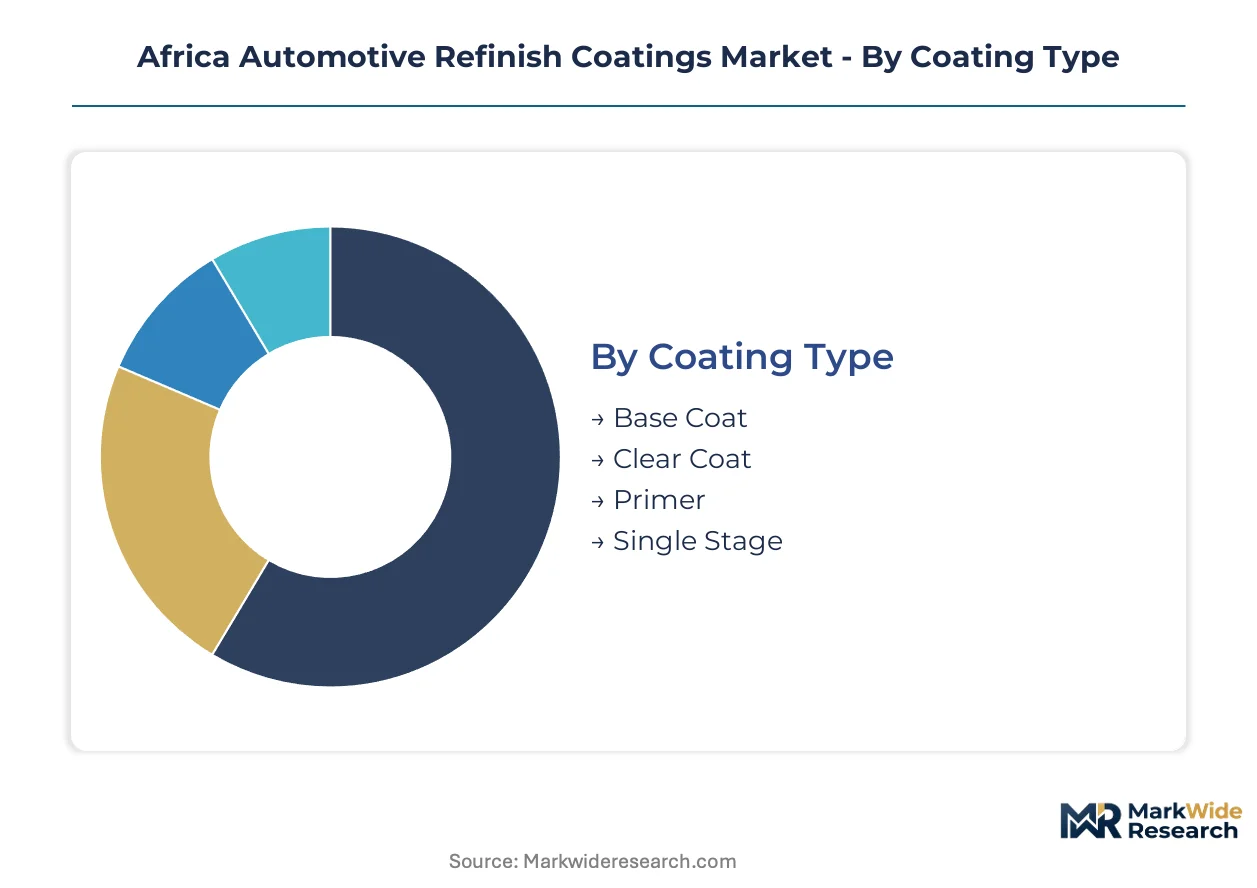
Refinish coating demand across Africa fragments along vehicle type, repair channel maturity, and end-user technical capability. Segmentation reveals where professionalization pressures concentrate versus where informal supply chains retain dominance.
Coating Type:
Use cases span from color restoration requiring multi-layer precision to single-step corrosion protection for aging commercial fleets.
- Base Coat:Pigmented formulations providing color layer coverage at 15-25 micron thickness, compatible with OEM standards. Demand concentrates in Lagos and Johannesburg registered body shops serving fleet operators with exact color-matching requirements.
- Clear Coat:UV-protective top layers delivering gloss retention and weather resistance. Professional painters in Nairobi and Accra prioritize these systems for premium vehicle restoration where durability penalties apply.
- Primer:Surface preparation layers ensuring adhesion on repaired substrates.
- Single Stage:Combined color and protection formulations for cost-sensitive applications.
Established volume favors base coat systems; emerging adoption favors clear coat segments as fleet contracts specify UV-durability terms.
Application Type:
Vehicle category determines coating specification complexity and service channel access.
- Passenger Vehicles:Collision repair and cosmetic restoration on private automobiles requiring precise color-matching to OEM standards. Cairo and Casablanca independent shops dominate this segment as insurance-mediated claims formalize.
- Commercial Vehicles:Fleet trucks and vans operating on Kenya's Mombasa-Nairobi corridor and Nigeria's Lagos-Ibadan axis. Extended service life beyond 12 years generates sustained demand for corrosion protection and cosmetic overhaul.
- Motorcycles:Two-wheeler repair concentrated in urban informal clusters across West Africa.
- Heavy-Duty Trucks:Long-haul fleet assets requiring durable refinish systems for chassis and cab protection.
Commercial vehicle applications expand most quickly as fleet privatization accelerates; passenger vehicle segments retain volume concentration in metropolitan centers.
Distribution Channel:
Channel structure reflects supply chain maturity and buyer technical sophistication across African markets.
- Retail:Counter sales through independent paint stores serving walk-in body shop purchasers. Nairobi and Dar es Salaam retail networks anchor procurement for small independent operators lacking direct supplier relationships.
- Wholesale:Volume distribution to multi-location body shop chains and fleet maintenance depots. South African wholesale channels supply certified coating systems compliant with SABS VOC standards.
- Online:Digital ordering platforms penetrating urban markets with catalog-based colorant selection.
- Direct Selling:Manufacturer-to-shop supply relationships with technical support attachment.
Wholesale channels capture fleet-driven volume; retail maintains penetration among fragmented independent operators.
End User:
Technical capability and procurement authority separate professional from informal demand.
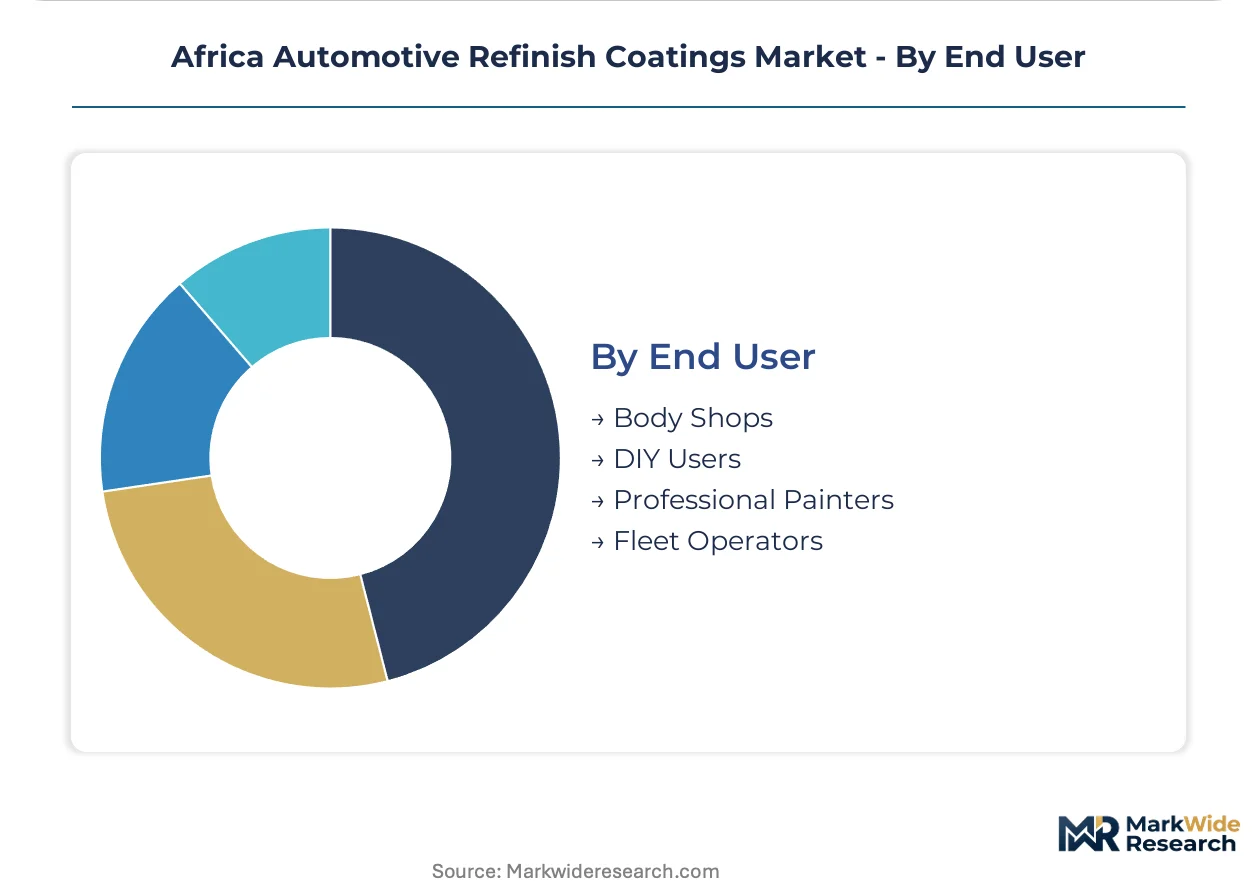
- Professional Painters:Certified spray booth operators delivering warranty-backed finishes for registered body shops. This category climbs the fastest as fleet operators outsource repair rather than maintain in-house capability across East African transport corridors.
- Fleet Operators:Transport companies consolidating vendor lists to three approved suppliers per region, establishing direct service contracts bypassing insurance mediation. Lagos petroleum tanker fleets now bid quarterly for certified shop services.
- Body Shops:Formal repair facilities with spray booth infrastructure and regulatory registration.
- DIY Users:Informal repairers applying basic coatings without professional equipment.
Fleet operators gain procurement leverage fastest; professional painters retain technical influence over specification decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-grade coating systems in South Africa command pricing multiples over Egyptian value-tier imports, reflecting certification infrastructure gaps that fragment procurement power across the continent.
South Africa
Fleet renewal cycles and insurance-mediated collision claims drive refinish demand in Gauteng and Western Cape provinces. The National Regulator for Compulsory Specifications enforces SABS VOC content limits, forcing Durban and Cape Town shops to retrofit spray booth ventilation. Johannesburg anchors the continent's most concentrated certified technician base.
Nigeria
Petroleum tanker fleets and aging commercial parc generate sustained demand along the Lagos-Ibadan transport corridor. The Standards Organisation mandates product registration for imported refinish chemicals, creating six-to-twelve month approval timelines. Lagos repair clusters are formalizing into registered body shops to access fleet contracts.
Egypt
State fleet privatization and Suez Canal logistics traffic sustain refinish coating consumption in Cairo and Alexandria industrial zones. Environmental discharge limits for solvent-borne operations are tightening near Cairo, accelerating water-borne system adoption. Cairo-Giza industrial corridors concentrate the country's spray booth infrastructure.
Kenya
East African commercial fleets extending service life beyond twelve years generate corrosion protection demand along the Mombasa-Nairobi transport axis. The Kenya Bureau of Standards maintains coating import inspection protocols. Nairobi anchors the region's professional painter certification programs.
Morocco
European automotive logistics and domestic fleet aging sustain refinish demand in Casablanca-Rabat industrial zones. The country's environmental regulator is harmonizing discharge standards with EU REACH protocols. Tangier-Med port logistics clusters are emerging as coating distribution hubs for North African markets.
Africa Automotive Refinish Coatings Market Competitive Environment
Multinational formulators and regional specialists split the market along certification-tier lines. Three strategic archetypes dominate: integrated chemical conglomerates with captive resin supply, dedicated coatings specialists with technical training networks, and regional traders optimizing import cost structures. Competitive moves concentrate on distribution partnerships with fleet operators and spray booth certification programs for independent shops.
Among integrated chemical conglomerates, BASF SE and Covestro AG exemplify the upstream-resin-to-formulation archetype. PPG Industries and AkzoNobel N.V. represent the dedicated coatings specialist tier with established technical service infrastructure. KAPCI Coatings occupies a position within the regional value-tier segment serving price-sensitive North African procurement channels.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries |
| Axalta Coating Systems |
| BASF SE |
| 3M Company |
| Kansai Paint Co. |
| Nippon Paint Holdings Co. |
| KAPCI Coatings |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Pigment import dependency from European and Asian supply bases determines both pricing tier spreads and supply chain shape across African refinish coating markets. Currency volatility against the euro and yen widens the gap between premium color-matched systems and value-tier formulations, while extended lead times force distributors to carry deeper inventory buffers that compress working capital.
Pricing Analysis
The customization-premium spread separates fleet-contract base coat systems from retail single-stage formulations. Three-tier pricing structure across premium, standard, and economy levels reflects SABS certification status, color-matching precision, and after-sales technical support bundling. Cost compression in the value tier is intensifying because petrochemical-derived solvent costs fluctuate with crude movements. Fleet operators in Kenya and Nigeria show least price sensitivity due to downtime penalty clauses, while independent Lagos body shops remain most sensitive to per-liter material costs.
Supply Chain Analysis
Tariff exposure between Egypt and EU member states dominates supply chain risk for North African coating formulators. Specialty colorants and effect pigments draw from Germany, Italy, and China, while acrylic resins and isocyanate hardeners rest on South Korean and Japanese production. Single-source vulnerability concentrates in effect pigment supply where three European manufacturers control global output. Distribution runs through Casablanca and Johannesburg wholesale hubs serving registered body shops, with informal retail channels penetrating secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against water-borne system displacement of solvent-borne formulations. Incumbents must navigate the regulatory-driven technology transition while maintaining service infrastructure for aging vehicle parc requirements.
For Market Incumbents: Entrench certification infrastructure as the primary defensive moat. Expand Johannesburg and Cairo training center capacity to offset technician migration to Gulf states. Deepen backward integration into captive resin supply to buffer petrochemical cost volatility and defend margin position against Asian import competition. For New Entrants and Emerging Players: Build out digital color-matching platforms targeting Ethiopia's privatizing fleet sector where professional repair networks remain underdeveloped. The most penetrable segment lies in secondary East African cities lacking certified spray booth operators. A direct-to-fleet technical service model bypasses established distributor relationships in Nairobi and Dar es Salaam. For Investors and Strategic Acquirers: SABS VOC standard enforcement reshapes the acquisition landscape toward compliant formulation assets. Long-term viability centers on water-borne technology transition completion within a decade. Target regional specialists with established product registration in Nigeria's Standards Organisation pipeline. Monitor Egyptian environmental discharge limit implementation as the signal for accelerated solvent-borne asset impairment.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne System Transition | SABS compliance mandates in Johannesburg and Cape Town retrofitting drive premium formulation adoption. |
| Training Center Network Expansion | PPG Industries' technician certification model anchors loyalty among fleet-contract body shops. |
| Digital Color Matching Platform | Spectrophotometer deployment reduces rework rates for isolated Mombasa-Nairobi corridor operators. |
| Direct Fleet Service Contracts | Petroleum tanker operators in Lagos now bypass insurance mediation for quarterly vendor bidding. |
| Product Registration Pipeline Investment | Nigeria's Standards Organisation approval timelines favor early entrants with dedicated regulatory affairs capacity. |
Study Parameters
Initial hypotheses were tested against primary input from body shop operators, fleet procurement managers, coating formulator technical directors, and national standards regulators, then refined through secondary validation. Customs and trade data, SABS certification registries, SEC 10-K filings from listed chemical conglomerates, and vehicle parc aging statistics from national transport authorities anchored quantitative triangulation. Bottom-up volume estimates from registered shop counts across Lagos, Johannesburg, and Cairo converged with top-down formulation consumption models.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled included coating chemistry type, application vehicle category, distribution channel tier, and end-user technical capability. CAGRs derived from logistic curve fitting to professionalization penetration rates in fleet repair outsourcing. Industry-specific inputs incorporated SABS VOC compliance timeline assumptions and Ethiopian fleet privatization transfer schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese water-borne specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Heavy Duty Glass Coating Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Epoxy Powder Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Global Powder Coating Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Epoxy Coating Market
Coatings
2K Protective Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
US Protective Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Global Solar Panel Coatings Market