
 Polymers for Electric Vehicle (EV) Market | 2026-2036
Polymers for Electric Vehicle (EV) Market Size, Share, and Industry Trends Forecast 2026-2036
Polymers for Electric Vehicle (EV) Market Insights
Project finance tied to gigafactory construction is narrowing the field of polymer suppliers capable of securing long-term offtake contracts. BASF SE leverages its integrated precursor-to-compound chain to sustain margin capture across battery housing grades. Covestro AG anchors its position through dedicated polycarbonate capacity serving European OEM platforms. DuPont de Nemours, Inc. differentiates via high-heat polyamide formulations aimed at power electronics thermal management.
Polymers for electric vehicles comprise engineered thermoplastics and elastomeric compounds formulated for dielectric strength, flame retardancy, and thermal stability in electrified powertrains. These materials typically achieve UL 94 V-0 ratings and continuous-use temperatures exceeding 150°C to protect battery modules, inverters, and charging infrastructure from thermal runaway and electrical breakdown. Polypropylene dominates interior component volumes due to its low density and recyclability, while polycarbonate leads exterior panel applications where optical clarity and impact resistance converge. Thermoplastic elastomers represent the fastest-expanding product category as automakers replace conventional rubber seals and gaskets with injection-moldable alternatives that reduce assembly steps.
The EPA tailpipe-emission rules and the EU's F-Gas Regulation are accelerating demand for polymers that enable lighter vehicle structures and eliminate hydrofluorocarbon-based thermal management fluids. China's MIIT enforces GB standards for battery enclosure fire resistance, compelling suppliers to certify materials under stricter test protocols. Stakeholders must track how REACH chemical restrictions and emerging biodegradability mandates in the EU reshape acceptable feedstocks for engineering-grade compounds.
Market Dynamics
Battery pack manufacturers now dominate polymer procurement decisions, forcing compounders to certify materials under stricter thermal-runaway protocols before securing long-term offtake agreements with gigafactory developers.
Growth Catalysts
- China's dual carbon goals:MIIT-enforced GB standards for battery enclosure fire resistance compel automakers to specify UL 94 V-0 rated engineered thermoplastics, expanding addressable material volumes.
- Power electronics thermal management:High-heat polyamide formulations are displacing metal heat sinks in inverter housings as OEMs pursue 15-20% mass reduction targets for next-generation platforms.
- Thermoplastic elastomer substitution:Injection-moldable TPE seals are replacing conventional rubber gaskets across charging infrastructure and battery module assemblies, consolidating multi-step assembly processes.
Market Restraints
- Caprolactam feedstock volatility:Polyamide 6 pricing swings with benzene and cyclohexane spot markets, compressing compounder margins during crude oil disruptions.
- European precursor concentration:Bisphenol A and phosgene supply clusters in Germany's chemical corridor expose polycarbonate converters to single-point disruption risks.
- REACH chemical restrictions:ECHA scrutiny of halogenated flame retardants is narrowing the certified additive palette, forcing reformulation cycles that delay OEM qualification timelines.
Strategic Opportunities
- India's PLI scheme for automotive:Localized battery assembly incentives are drawing polymer compounders to establish compounding facilities near Tamil Nadu and Gujarat cell manufacturing zones.
- Solid-state battery interfaces:Ceramic-polymer hybrid separator films represent uncontracted demand as solid-state prototypes advance toward pilot production.
- F-Gas Regulation phase-down:EU-mandated elimination of hydrofluorocarbon-based thermal management fluids is opening polymer heat exchanger applications previously closed to plastics.
Industry Challenges
- Fire-safety certification bottlenecks:GB 38031 and UL 2594 test protocol divergence forces compounders to maintain parallel qualification tracks, extending development cycles.
- Recyclate feedstock inconsistency:Post-industrial polypropylene streams from automotive interior production exhibit property variance that complicates closed-loop material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymers for Electric Vehicle (EV) Market |
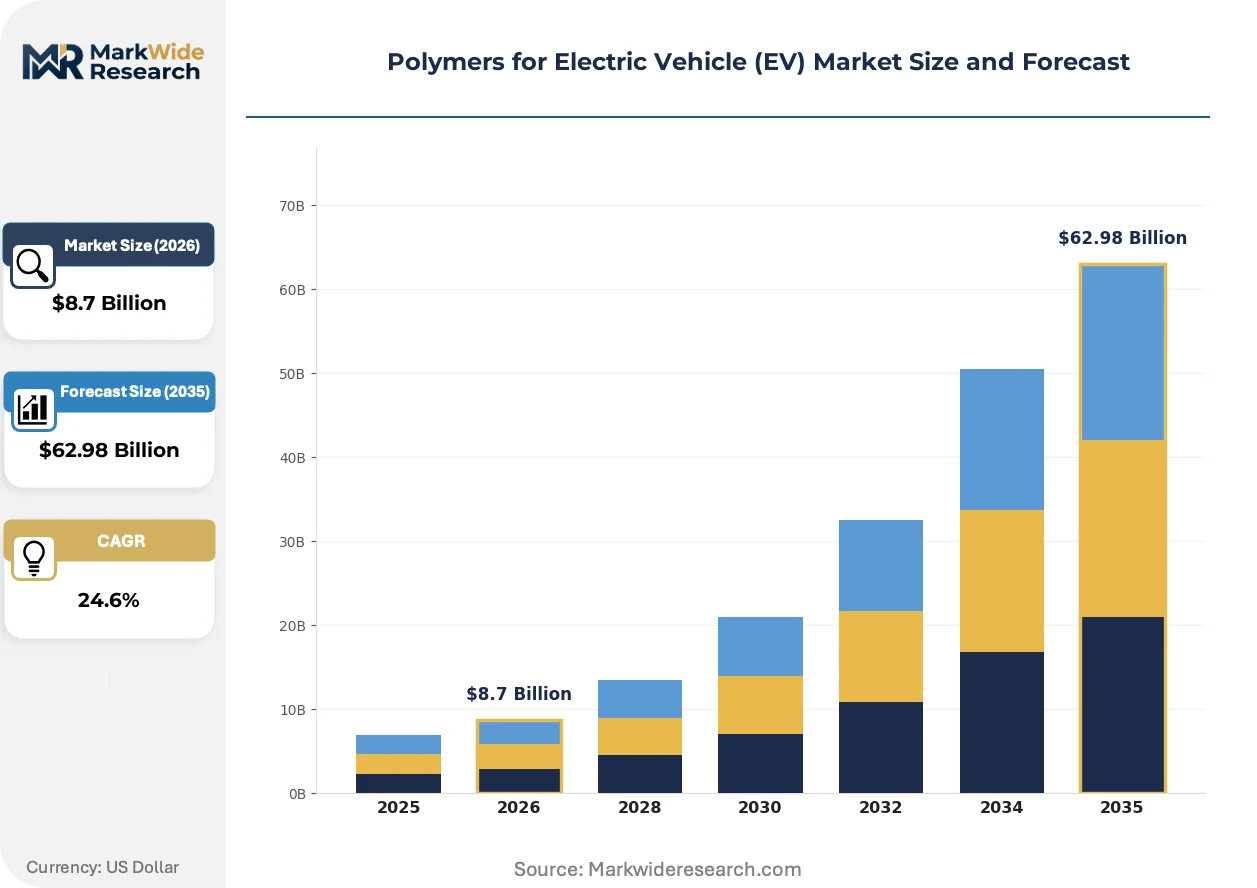
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, Polypropylene, Thermoplastic Elastomers Application: Batteries, Interior Components, Exterior Panels, Insulation End User: OEMs, Aftermarket Suppliers, Parts Manufacturers, Vehicle Assemblers Grade: High-performance, Engineering-grade, Specialty, Biodegradable |
| Companies Covered | BASF SE, Covestro AG, DuPont de Nemours, Inc., LG Chem Ltd., Celanese Corporation, Solvay, LANXESS AG, Asahi Kasei Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymers for Electric Vehicle (EV) Market Trends and Innovations
Material science is converging with electrification architecture, as battery thermal management requirements rewrite polymer specification sheets faster than traditional automotive development cycles can accommodate.
Glass-reinforced polyphthalamide is hybridizing with thermally conductive ceramic fillers to create injection-moldable heat spreaders that replace aluminum die-castings in DC-DC converter housings. Tier-1 power electronics suppliers in Germany's automotive corridor are qualifying these compounds for 150°C continuous-use applications. This substitution is compressing metal-to-polymer conversion timelines from 36-month qualification windows toward 18-month cycles.
REACH authorization procedures for medium-chain chlorinated paraffins are forcing compounders to accelerate phosphorus-nitrogen intumescent system adoption ahead of sunset dates. The restriction is redirecting R&D budgets toward halogen-free formulations that maintain V-0 ratings at sub-millimeter wall thicknesses. Battery housing grades destined for EU-bound EV platforms face the most acute reformulation pressure.
Automotive OEMs are consolidating polymer procurement under dedicated electrification material councils that bypass traditional commodity purchasing hierarchies. These councils bundle battery pack, power electronics, and charging infrastructure specifications to extract volume commitments from compounders. The concentration is most pronounced among German and South Korean manufacturers integrating cell-to-pack architectures.
Polymers for Electric Vehicle (EV) Market Segmentation
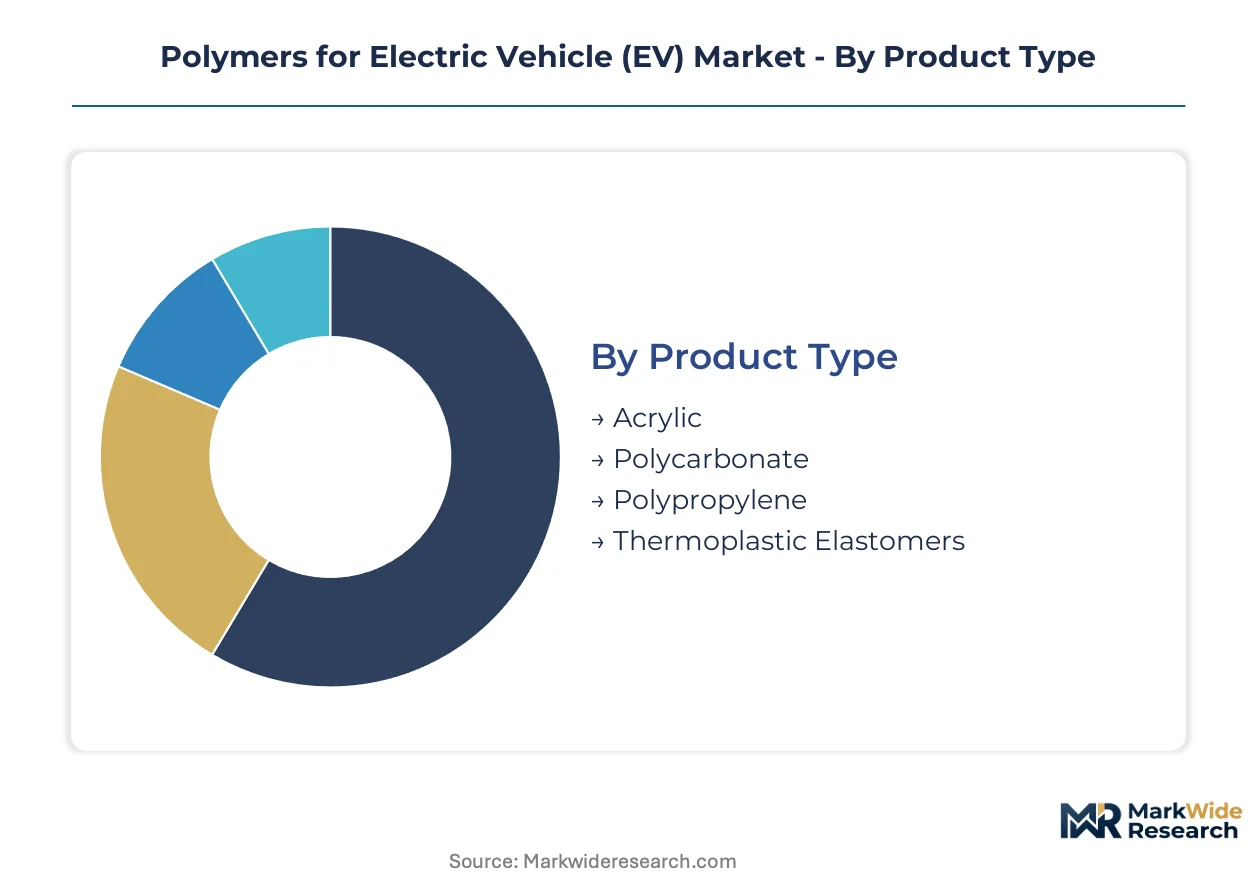
Polymer specification cycles in electric vehicle manufacturing diverge sharply by thermal exposure and regulatory exposure. Segments facing battery thermal runaway protocols refresh formulations every 18-24 months, while interior comfort applications operate on 5-7 year automotive platform cycles.
Product Type:
Thermoplastic elastomers turn over fastest as automakers consolidate multi-part assemblies, while acrylic specifications shift slowest due to entrenched optical clarity standards for lighting applications.
- Acrylic:Optical-grade thermoplastic with 92% light transmission and UV stability for headlamp lenses and interior ambient lighting. Demand concentrates in Germany's automotive corridor where OEMs specify acrylic for signature lighting elements on premium EV platforms, constrained by scratch-resistance limitations versus polycarbonate alternatives.
- Polycarbonate:High-impact amorphous thermoplastic achieving UL 94 V-0 ratings with glass-transition temperatures near 150°C for battery housings and panoramic roof modules. Battery pack manufacturers in China's Yangtze River Delta now specify flame-retardant polycarbonate grades under MIIT-enforced GB 38031 protocols, displacing metal enclosures in cell-to-pack architectures.
- Polypropylene:Semi-crystalline olefin with density below 0.95 g/cm³ serving bumper fascias, door panels, and battery module separators where mass reduction targets dominate material selection.
- Thermoplastic Elastomers:Injection-moldable block copolymers and vulcanizates replacing EPDM rubber seals across charging port covers and battery pack gaskets.
Polypropylene dominates installed base across interior volumes. Thermoplastic elastomers are where expansion concentrates.
Application:
Cost tier separation runs deepest here — battery applications command 3-4x material premiums versus commodity interior trim due to thermal-runaway certification requirements.
- Batteries:Encapsulation films, module separators, and pack housings requiring dielectric strength above 15 kV/mm and continuous-use temperatures exceeding 150°C. Cell manufacturers in South Korea's battery belt specify ceramic-filled polyamides for pouch cell frames, driven by OEM thermal propagation containment mandates.
- Interior Components:Dashboard substrates, door panels, and seating structures prioritizing low volatile organic compound emissions and recyclability. German OEMs source talc-filled polypropylene for instrument panels, constrained by post-industrial recyclate inconsistency in closed-loop specifications.
- Exterior Panels:Body-in-white replacement panels and structural closures where stiffness-to-weight ratios compete with aluminum sheet. China's NEV manufacturers specify long-glass polypropylene for fenders, gaining share against steel in sub-compact urban EV segments.
- Insulation:Wire jacketing and busbar sleeving requiring halogen-free flame retardancy under REACH restrictions on chlorinated additives.
Interior components dominate installed base. Battery applications are where expansion concentrates.
End User:
Procurement authority is concentrating fastest among vehicle assemblers integrating cell-to-pack designs, while aftermarket suppliers face elongating qualification timelines as OEMs restrict material certification access.
- OEMs:Vertically integrated material councils at German and South Korean manufacturers now bundle battery, power electronics, and charging infrastructure specifications to extract volume commitments from compounders, bypassing traditional commodity purchasing hierarchies.
- Aftermarket Suppliers:Independent service part producers facing restricted access to OEM-certified polymer grades as electrification platforms lock repair specifications to proprietary formulations.
- Parts Manufacturers:Tier-1 injection molders serving both OEM direct contracts and aftermarket channels, navigating divergent thermal-runaway certification requirements across GB, UL, and ECE regulatory tracks.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities with limited polymer specification authority under OEM brand-controlled material lists.
Parts manufacturers dominate installed base. OEMs are where expansion concentrates.
Grade:
Supply concentration tilts toward engineering-grade compounds where European precursor clusters in Germany's chemical corridor enable integrated precursor-to-compound production.
- High-performance:Polyphthalamide and PEEK formulations for inverter housings and DC-DC converters requiring 200°C continuous-use capability. Power electronics suppliers in Germany qualify glass-reinforced polyphthalamide with thermally conductive ceramic fillers, displacing aluminum die-castings under 15-20% mass reduction targets.
- Engineering-grade:Standard polyamide, polycarbonate, and PBT compounds for structural battery components and charging infrastructure enclosures. BASF SE and Covestro AG anchor European supply through dedicated capacity serving OEM platform specifications.
- Specialty:Electrically conductive and EMI-shielding grades for sensor housings and high-voltage connector bodies.
- Biodegradable:Emerging polylactic acid and polyhydroxyalkanoate formulations for non-structural interior applications under EU biodegradability mandate development.
Engineering-grade compounds dominate installed base. High-performance grades are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer trade flows for electric vehicle applications increasingly favor manufacturing regions with integrated precursor supply chains. China maintains a substantial export surplus in battery-grade engineered compounds, while Germany and the United States remain net importers of specialized high-heat formulations for power electronics.
China
MIIT-enforced GB 38031 standards for battery enclosure fire resistance compel domestic automakers to specify UL 94 V-0 rated polycarbonate and polyamide grades. The country's dual carbon goals accelerate material substitution timelines across NEV platforms. Cell manufacturers in the Yangtze River Delta now source flame-retardant polymer housings from local compounders, displacing previous import dependence.
Germany
OEM material councils in Stuttgart and Munich bundle battery pack, power electronics, and charging infrastructure specifications to extract volume commitments from compounders. REACH authorization procedures for halogenated flame retardants force accelerated reformulation cycles ahead of sunset dates. The country's chemical corridor in North Rhine-Westphalia anchors integrated precursor-to-compound production for European EV platforms.
United States
EPA tailpipe-emission rules drive mass reduction targets that favor polymer substitution in structural battery components. The Inflation Reduction Act's domestic content incentives reshape procurement patterns for battery pack manufacturers establishing gigafactory capacity. Michigan and Tennessee automotive clusters now qualify thermally conductive polyamide formulations for inverter housings previously specifying aluminum.
South Korea
MFDS-aligned battery safety protocols and OEM thermal propagation containment mandates concentrate demand for ceramic-filled polyamides in pouch cell frames. The country's battery belt around Ulsan and Gwangju anchors cell manufacturing that sources engineered polymers through dedicated offtake contracts. Domestic compounders face qualification pressure from vertically integrated cell-to-pack architectures.
India
PLI scheme incentives for automotive and advanced chemistry cell manufacturing draw polymer compounders toward Tamil Nadu and Gujarat production zones. BIS certification requirements for battery enclosure materials create entry barriers that favor established suppliers with testing infrastructure. Domestic formulators in Pune and Chennai now serve localized assembly operations for European and Japanese OEM joint ventures.
Polymers for Electric Vehicle (EV) Market Competitive Landscape
On the supply side, the industry is consolidating around compounders capable of certifying materials under parallel GB, UL, and ECE thermal-runaway protocols. Three archetypes now dominate: integrated chemical conglomerates with captive precursor supply, specialized engineering polymer houses focused on high-heat formulations, and regional compounders serving localized gigafactory clusters. Strategic moves concentrate on backward integration into flame-retardant additive production and dedicated capacity commitments tied to OEM platform specifications.
Within the integrated chemical tier, BASF SE and Covestro AG exemplify European-based compounders leveraging precursor concentration in Germany's chemical corridor. DuPont de Nemours, Inc. occupies a position among specialty material developers emphasizing high-performance formulations. These three anchors illustrate how supply-side capability now gates access to long-term offtake contracts with battery pack manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| DuPont de Nemours, Inc. |
| LG Chem Ltd. |
| Celanese Corporation |
| Solvay |
| LANXESS AG |
| Asahi Kasei Corporation |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta polycarbonate compounding sector compresses contract margins for battery-grade formulations, compelling suppliers to bundle flame-retardant additive services into long-term offtake agreements with gigafactory developers. This utilization squeeze simultaneously tightens pricing discipline among European compounders and accelerates backward integration into precursor production.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on UL 94 V-0 certification grade and volume commitment scale. Cost compression in standard-grade polypropylene runs through post-industrial recyclate inconsistency, while battery pack manufacturers show least price sensitivity due to thermal-runaway liability exposure.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment as battery enclosure material trade flows face escalating regulatory scrutiny. Production gravity centers on China, Germany, and South Korea, with bisphenol A and caprolactam feedstocks drawing from concentrated precursor clusters in North Rhine-Westphalia and the US Gulf Coast. Distribution runs through dedicated electrification material councils at OEMs that bypass traditional commodity purchasing hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture penetration sits below 15% across major OEM platforms, leaving substantial runway for engineered polymer volume expansion as thermal management requirements intensify.
For Market Incumbents: Build certification moats around parallel GB 38031, UL 2594, and ECE R100 qualification tracks to lock out compounders lacking testing infrastructure. BASF SE and Covestro AG exemplify this defensive posture through dedicated European capacity serving OEM platform specifications. Threat substitution from aluminum die-castings in inverter housings demands accelerated ceramic-polymer hybrid R&D cycles. For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat battery assembly zones represent the most penetrable entry point for regional compounders seeking PLI-linked localization incentives. Ceramic-filled polyamide supply gaps around Ulsan's battery belt offer secondary white-space. Go-to-market execution should anchor on BIS certification pre-investment to compress qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with captive flame-retardant additive production and long-term OEM material council relationships. Five-to-ten-year viability favors integrated chemical conglomerates over specialized engineering houses. Watch solid-state battery pilot production announcements as inflection indicators for ceramic-polymer hybrid separator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame-Retardant Additives | BASF SE and LANXESS AG secure margin capture against REACH-driven reformulation cycles. |
| Long-Term Supply Agreement with Gigafactory Developers | Covestro AG locks polycarbonate volumes under OEM platform specifications. |
| Joint Venture in India PLI Zones | Localized compounding capacity serves Tamil Nadu and Gujarat cell manufacturing clusters. |
| Green Manufacturing Transition | Halogen-free phosphorus-nitrogen intumescent systems displace restricted chlorinated paraffins. |
| Capacity Expansion in Germany's Chemical Corridor | Integrated precursor-to-compound production anchors European EV platform supply. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer procurement leads at battery pack manufacturers, OEM platform engineers, Tier 1 power electronics suppliers, and flame-retardant additive producers; and secondary validation against customs trade data, MIIT GB standard filings, ECHA REACH authorization registers, and SEC 10-K disclosures from listed compounders. Bottom-up polymer consumption modeling triangulated against top-down EV production forecasts across the analysis window.
Forecast inputs encompassed grade tier, application thermal exposure, OEM tier, and regional regulatory cluster segmentation. CAGRs derived from volume elasticity to battery pack production capacity expansion, with explicit modeling of cell-to-pack architecture penetration rates and solid-state battery timeline scenarios. Power electronics thermal management substitution curves and REACH chemical restriction phase-in schedules shaped projection boundaries.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, benzene-cyclohexane spread compression, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and OEM platform standardization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Bio-Based Construction Polymers Market