
 Flame Retardant Thermoplastics Market | 2026-2036
Flame Retardant Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Retardant Thermoplastics Market Analysis
China's petrochemical complex is expanding flame retardant polypropylene compounding lines to serve appliance and automotive wire harness demand. LANXESS sustains a dominant position in halogen-free polyamide grades for electrical connectors through captive phosphorus flame retardant production. BASF SE leverages its Ludwigshafen integrated site to control feedstock costs for engineering thermoplastic compounds. Dow Inc. anchors North American supply with broad polycarbonate and ABS portfolios serving building and electronics segments.
Flame retardant thermoplastics are polymer compounds incorporating halogen, phosphorus, nitrogen, or mineral additives to achieve specified UL 94 V-0 or HB ratings while retaining processability in standard thermoplastic equipment. These materials primarily serve industries requiring ignition resistance without sacrificing the design flexibility and recyclability of conventional plastics. Polypropylene dominates volume consumption in building materials and automotive components where cost sensitivity meets moderate heat requirements, while polyamide commands premium positioning in electrical connectors and relay housings that must survive soldering temperatures and continuous service loads. Polycarbonate grades with brominated or phosphate ester additives occupy the optical and housing segments of electronics, though regulatory pressure on halogen content is shifting technical preference toward silicone-based and sulfonate salt systems.
The EPA administers TSCA Section 6 restrictions on persistent organic pollutants including certain brominated diphenyl ethers, compelling reformulation across US-sourced electrical enclosures. ECHA's REACH Annex XVII listings and the EU RoHS directive jointly restrict halogenated flame retardants in consumer electronics, redirecting compounder R&D toward phosphorus-nitrogen synergists and metal hydroxide hydrates. China's MEE enforces GB standards for building material fire safety that mandate specific oxygen index thresholds in wire insulation and conduit applications. Stakeholders must monitor the divergence between regional chemical restriction lists, as compliance in one jurisdiction no longer guarantees market access in another.
Market Dynamics
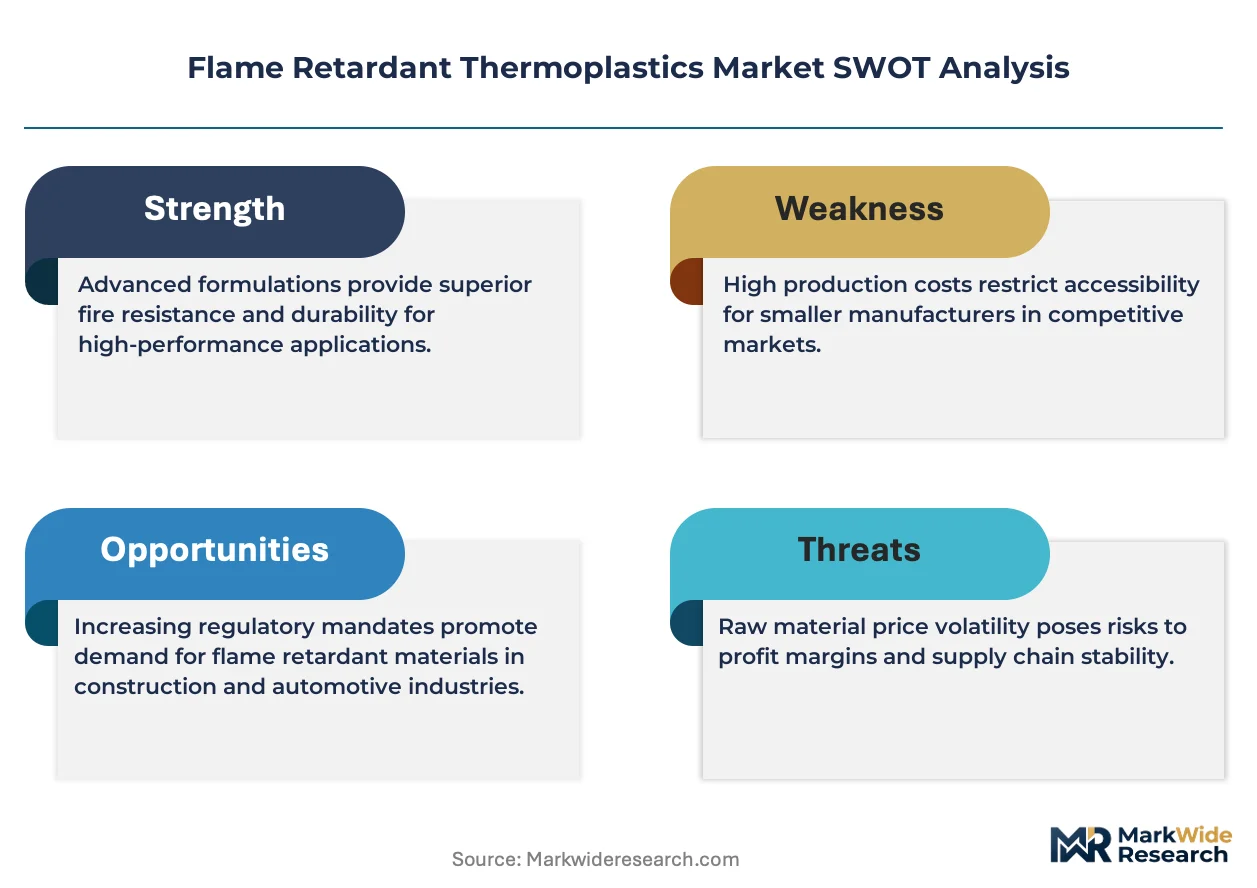
The transition from halogenated to phosphorus-based flame retardant systems is compressing reformulation timelines across compounder R&D pipelines as REACH Annex XVII restrictions harden enforcement boundaries.
Growth Catalysts
- EU REACH Annex XVII:Restrictions on brominated diphenyl ethers are forcing electrical enclosure manufacturers toward halogen-free polyamide and polypropylene grades.
- China's eastern manufacturing corridor:Appliance and automotive wire harness production clusters in Jiangsu and Zhejiang provinces are concentrating demand for V-0 rated compounds.
- Phosphorus-nitrogen synergists:Intumescent systems are achieving equivalent flame suppression at lower loadings, preserving mechanical properties in thin-wall connector applications.
Market Restraints
- Red phosphorus supply concentration:Refining capacity clusters in Yunnan and Guizhou provinces create geographic vulnerability for halogen-free compounders.
- Magnesium hydroxide dehydration kinetics:Processing temperatures above 300°C degrade mineral fillers before polymer dispersion completes, limiting high-heat engineering resin compatibility.
- REACH authorization delays:Pending SVHC listings for certain phosphate esters are freezing procurement decisions at German automotive Tier-1 suppliers.
Strategic Opportunities
- India's BIS certification mandate:IS 694 standards for fire-retardant low-smoke cables in commercial buildings will expand addressable market for mineral-filled polyolefin compounds.
- 5G base station housings:Dielectric-grade flame retardant polycarbonate is penetrating telecom infrastructure as mmWave deployment accelerates outdoor enclosure demand.
- Silicone-based systems:Polysiloxane additives are opening optical transparency applications previously closed to opaque phosphorus or mineral formulations.
Industry Challenges
- UL 94 testing backlog:Certification queue times at Underwriters Laboratories facilities are extending product launch timelines by 4-6 months for new compound grades.
- Compounding equipment retrofit costs:Mineral filler abrasion requires twin-screw extruder barrel and screw replacement cycles that compress margin structures at mid-volume processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Retardant Thermoplastics Market |
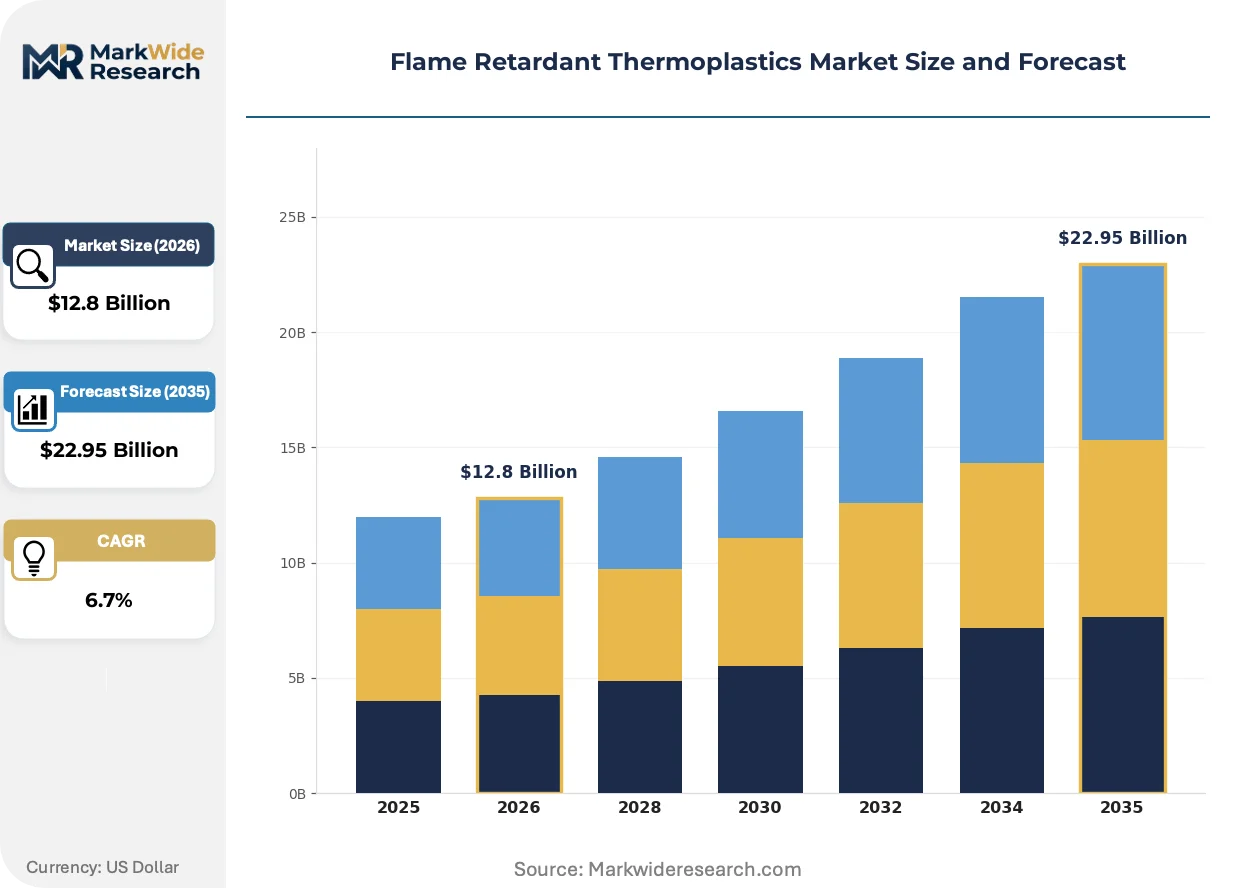
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polypropylene, Polyamide, Acrylonitrile Butadiene Styrene Application: Building Materials, Electrical & Electronics, Automotive Components, Textiles End User: Aerospace, Construction, Consumer Goods, Electronics Technology: Injection Molding, Extrusion, 3D Printing, Blow Molding |
| Companies Covered | BASF SE, LANXESS, Dow Inc., SABIC, ICL, DuPont, Clariant AG, RTP Company, Huber Engineered Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Retardant Thermoplastics Market Emerging Trajectories
Reformulation chemistry is pivoting toward reactive flame retardant architectures that bond permanently to polymer backbones rather than dispersing as extractable additives.
Phosphinate salt technology is electrifying high-temperature polyamide applications by achieving V-0 ratings at sub-15% loadings without compromising CTI performance. Electric vehicle battery module manufacturers are qualifying these grades for busbar insulation and cell frame components. The shift is compressing demand for traditional brominated polystyrene systems in automotive powertrain applications.
ECHA's 2023 update to REACH SVHC candidate list added medium-chain chlorinated paraffins, redirecting polyvinyl chloride cable compounders toward calcium-zinc stabilizer packages. The restriction is accelerating R&D spending at European wire and cable specialists. Asian export-oriented compounders are dual-tracking formulations to maintain EU market access while serving less regulated domestic construction segments.
Automotive OEMs are consolidating approved material lists to reduce supplier qualification overhead, compressing the viable compounder base for platform-critical applications. Tier-1 wiring harness suppliers are responding by demanding multi-site production commitments and locked tolling agreements. The concentration is most visible in Germany's automotive supplier ecosystem, where Volkswagen Group and BMW procurement teams are reducing qualified resin sources from twelve to four per polymer family.
Flame Retardant Thermoplastics Market Segmentation
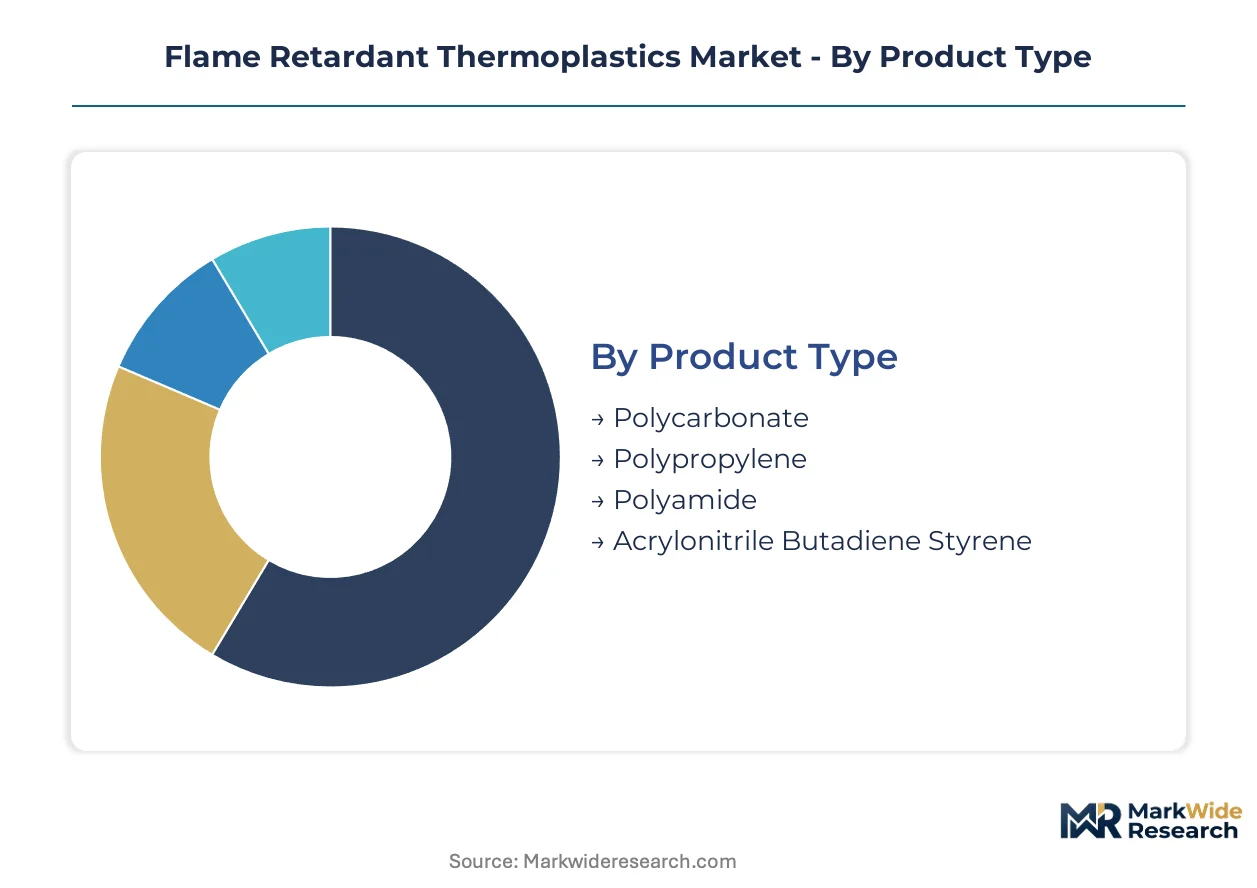
Segmentation in flame retardant thermoplastics reveals divergent capital requirements across polymer families and processing technologies. Compounders must align equipment investments with the thermal stability demands and regulatory loadings specific to each segment.
Product Type:
Capital intensity peaks with high-temperature engineering resins requiring precision compounding infrastructure, while commodity polyolefins run on standardized twin-screw systems.
- Polycarbonate:Optical-grade transparency demands sub-micron additive dispersion in vented extrusion lines. Demand concentrates in 5G base station housings and EV battery module frames where dielectric performance intersects with ignition resistance.
- Polypropylene:Halogen-free mineral systems dominate appliance wire insulation and automotive harness sheathing. Jiangsu and Zhejiang manufacturing clusters in China's eastern corridor absorb the majority of V-0 rated compound offtake.
- Polyamide:Phosphinate salt formulations achieve V-0 ratings at sub-15% loadings for electrical connectors surviving soldering temperatures.
- Acrylonitrile Butadiene Styrene:Brominated and phosphate ester grades serve consumer electronics housings facing REACH-driven reformulation pressure.
Polypropylene absorbs the bulk of installed capacity; polyamide is expanding most quickly.
Application:
Application segments separate by fire code stringency and the economic consequences of material failure.
- Building Materials:Wire insulation and conduit applications face GB standard oxygen index mandates from China's MEE. Construction procurement cycles drive volume but compress margin through specification-grade competition.
- Electrical & Electronics:UL 94 V-0 certification queues at Underwriters Laboratories facilities currently extend launch timelines. RoHS and REACH restrictions are accelerating halogen-free migration in connector and enclosure applications.
- Automotive Components:OEM consolidation of approved material lists is reducing qualified resin sources per polymer family from twelve to four.
- Textiles:Protective apparel and industrial fabrics require specialized fiber-grade compounding with limited processor availability.
Building materials command the deepest installed base; electrical and electronics applications are climbing the fastest.
End User:
End user segments stratify by qualification burden and the technical specificity of flame retardant performance requirements.
- Aerospace:FAR 25.853 compliance mandates smoke toxicity thresholds beyond standard UL ratings. Certification cycles span 18-24 months, locking supplier relationships.
- Construction:India's BIS IS 694 certification for fire-retardant low-smoke cables is expanding addressable market for mineral-filled polyolefin compounds in commercial buildings.
- Consumer Goods:Appliance manufacturers in China's eastern corridor specify V-0 rated polypropylene for internal components.
- Electronics:Dielectric-grade polycarbonate grades are penetrating telecom infrastructure as mmWave deployment accelerates outdoor enclosure demand.
Construction represents the largest volume sink; electronics end users are gaining share fastest.
Technology:
Processing technology selection determines additive dispersion quality, thermal degradation exposure, and per-unit economics.
- Injection Molding:Thin-wall connector applications demand precise intumescent system distribution. Phosphorus-nitrogen synergists achieve equivalent flame suppression at lower loadings, preserving mechanical properties.
- Extrusion:Wire and cable sheathing runs continuous production with mineral filler abrasion requiring frequent screw and barrel replacement.
- 3D Printing:Filament-grade flame retardant formulations face limited commercial availability due to rheology constraints.
- Blow Molding:Hollow electrical enclosures and automotive ducts require parison stability with loaded flame retardant systems.
Extrusion commands the majority of throughput capacity; 3D printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Red phosphorus refining capacity clusters in China's Yunnan and Guizhou provinces anchor upstream supply for halogen-free compounders. This geographic concentration shapes procurement risk profiles across downstream manufacturing corridors.
China
Jiangsu and Zhejiang provinces concentrate appliance and automotive wire harness production, absorbing the majority of V-0 rated polypropylene compound offtake. The MEE enforces GB standards for building material fire safety that mandate specific oxygen index thresholds in wire insulation. Manufacturing clusters in Suzhou and Ningbo are expanding flame retardant polypropylene compounding lines to serve this concentrated demand.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are consolidating approved material lists from twelve to four qualified resin sources per polymer family. ECHA's REACH Annex XVII restrictions on brominated diphenyl ethers redirect formulation strategies toward phosphorus-nitrogen synergists. The Ludwigshafen chemical complex anchors integrated feedstock control for engineering thermoplastic compounds serving electrical connector applications.
United States
The EPA administers TSCA Section 6 restrictions on persistent organic pollutants including certain brominated diphenyl ethers, compelling reformulation across electrical enclosure manufacturing. Dow Inc. anchors North American supply with broad polycarbonate and ABS portfolios. Midwestern automotive wire harness producers face UL 94 certification queue times extending product launch timelines by 4-6 months.
India
BIS certification mandates under IS 694 standards for fire-retardant low-smoke cables in commercial buildings expand addressable market for mineral-filled polyolefin compounds. Maharashtra and Gujarat industrial corridors concentrate wire and cable manufacturing infrastructure. Mumbai-Pune and Ahmedabad-Vadodara clusters are qualifying new compound grades for infrastructure electrification projects.
Japan
METI oversight of chemical substance management aligns domestic formulation standards with REACH-equivalent restrictions on halogenated systems. Kanto and Kansai manufacturing belts concentrate electronics housing and connector production. Tokyo-Osaka industrial corridors are accelerating procurement of halogen-free polyamide grades for high-reliability electrical applications.
Flame Retardant Thermoplastics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized high-temperature applications and regional tolling partnerships. The vendor base stratifies across integrated petrochemical majors, captive additive compounders, and independent toll processors. Three archetypes dominate: phosphorus chemistry specialists, mineral filler compounders, and integrated resin producers with backward additive control. Capacity expansion and strategic tolling agreements constitute the dominant competitive moves, with mid-volume processors retrofitting twin-screw extruder lines to handle abrasive mineral loadings.
Among integrated chemical majors, BASF SE exemplifies the captive feedstock archetype through its Ludwigshafen site operations. LANXESS occupies a position within the phosphorus chemistry specialist tier, while Dow Inc. anchors the broad-portfolio resin supplier category. These three entities represent distinct strategic postures: integrated site economics, additive technology depth, and regional supply chain breadth respectively.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| Dow Inc. |
| SABIC |
| ICL |
| DuPont |
| Clariant AG |
| RTP Company |
| Huber Engineered Materials |
| Others |
Supply Flow & Price Mechanics
Red phosphorus spot indices in Yunnan province cascade through halogen-free compounder cost structures, compressing margin tiers between integrated phosphorus specialists and toll-dependent processors serving appliance wire harness demand.
Pricing Analysis
Certification bundling separates UL 94 pre-qualified compound grades from toll-processed materials requiring customer-funded testing cycles. Three-tier pricing structure across premium, standard, and economy levels reflects phosphorus loading percentages, CTI performance ratings, and locked tolling agreement availability. Cost compression in mineral-filled polypropylene runs through mid-volume processors facing twin-screw extruder retrofit cycles. Appliance OEMs in Jiangsu province exhibit highest price sensitivity; aerospace qualified suppliers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with red phosphorus refining capacity concentrated in China's Yunnan and Guizhou provinces. The supply chain draws from brominated feedstock streams in the US Gulf Coast, phosphinate salt production in Germany's Ludwigshafen complex, and mineral filler extraction in Turkey and Israel. Tariff exposure on Chinese-origin phosphorus compounds threatens halogen-free compounder input costs. Distribution runs through regional compounding hubs co-located with automotive wire harness clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compounders with captive phosphorus chemistry and multi-site production commitments, as automotive OEM approved-material-list reduction from twelve to four sources per polymer family eliminates toll-dependent mid-volume processors.
For Market Incumbents: To counter REACH Annex XVII authorization delays freezing German automotive Tier-1 procurement decisions, backward integration into phosphinate salt production secures formulation flexibility while expanding tolling agreements across China's eastern manufacturing corridor locks in appliance wire harness volume. For New Entrants and Emerging Players: Enter via India's BIS IS 694 certification pipeline for fire-retardant low-smoke cables, where mineral-filled polyolefin compound demand outpaces qualified domestic supply. Target Maharashtra and Gujarat wire and cable manufacturing clusters with toll-processing partnerships offering faster certification queue navigation than established European compounders. For Investors and Strategic Acquirers: Distressed-cycle entries favor phosphorus chemistry specialists with captive Yunnan province feedstock arrangements in China. Long-term viability hinges on regulatory divergence tolerance across REACH-restricted EU markets and GB-standard domestic Chinese construction segments. Watch ECHA SVHC candidate list updates for phosphate ester authorization outcomes as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Chemistry | Captive red phosphorus refining in Yunnan province insulates compounders from supply concentration risk. |
| Multi-Site Production Commitment | Dual Jiangsu and Zhejiang compounding lines satisfy Volkswagen Group and BMW procurement consolidation requirements. |
| UL 94 Pre-Certification Investment | Underwriters Laboratories V-0 rating backlog compression accelerates customer product launch timelines by 4-6 months. |
| Long-Term Tolling Agreement | Locked processing contracts with automotive Tier-1 wiring harness suppliers secure volume through OEM platform cycles. |
| Silicone-Based Formulation R&D | Polysiloxane additive development opens optical transparency applications previously closed to opaque mineral systems. |
Methodological Framework
Multi-period observation of UL 94 certification queue durations, REACH SVHC candidate list additions, and red phosphorus spot price movements anchored the trend analysis, supplemented by interviews with flame retardant compounder plant managers, automotive Tier-1 wiring harness procurement leads, appliance OEM material specification engineers, and phosphorus additive R&D directors. Secondary validation drew from ECHA restriction database entries, EPA TSCA Section 6 enforcement actions, China MEE GB standard updates, and SEC 10-K disclosures from integrated chemical majors. Bottom-up volume modeling across polymer-grade tiers triangulated against top-down market sizing from end-use consumption patterns.
Segment-weighting applied differential growth assumptions across halogen-free versus brominated formulation trajectories, engineering resin versus commodity polyolefin grade premiums, and injection molding versus extrusion processing intensity. CAGR derivation incorporated phosphorus loading substitution elasticities, automotive platform content-per-vehicle forecasts, and 5G infrastructure deployment pacing across telecom enclosure applications. Modeled dimensions included polymer family, flame retardant chemistry type, end-use industry vertical, and regional regulatory cluster alignment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization reversals or red phosphorus export restriction scenarios. Forecasts reflect assumptions on regulatory divergence persistence, OEM material list consolidation velocity, and mineral filler processing temperature compatibility advances. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Welan Gum Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market