
 Thermosetting Plastics Market | 2026-2036
Thermosetting Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Thermosetting Plastics Market Outlook
Modular pre-preg kit configurations for aerospace MRO operations is expanding buyer choice beyond bulk resin contracts. BASF SE leverages its integrated polyurethanes network to anchor European automotive supply relationships. Sumitomo Bakelite dominates phenolic molding compounds for Asian electronics encapsulation, while Solvay specializes in high-performance epoxy systems for aerospace primary structures. Eastman Chemical Company competes through controlled distribution of specialty unsaturated polyester formulations.
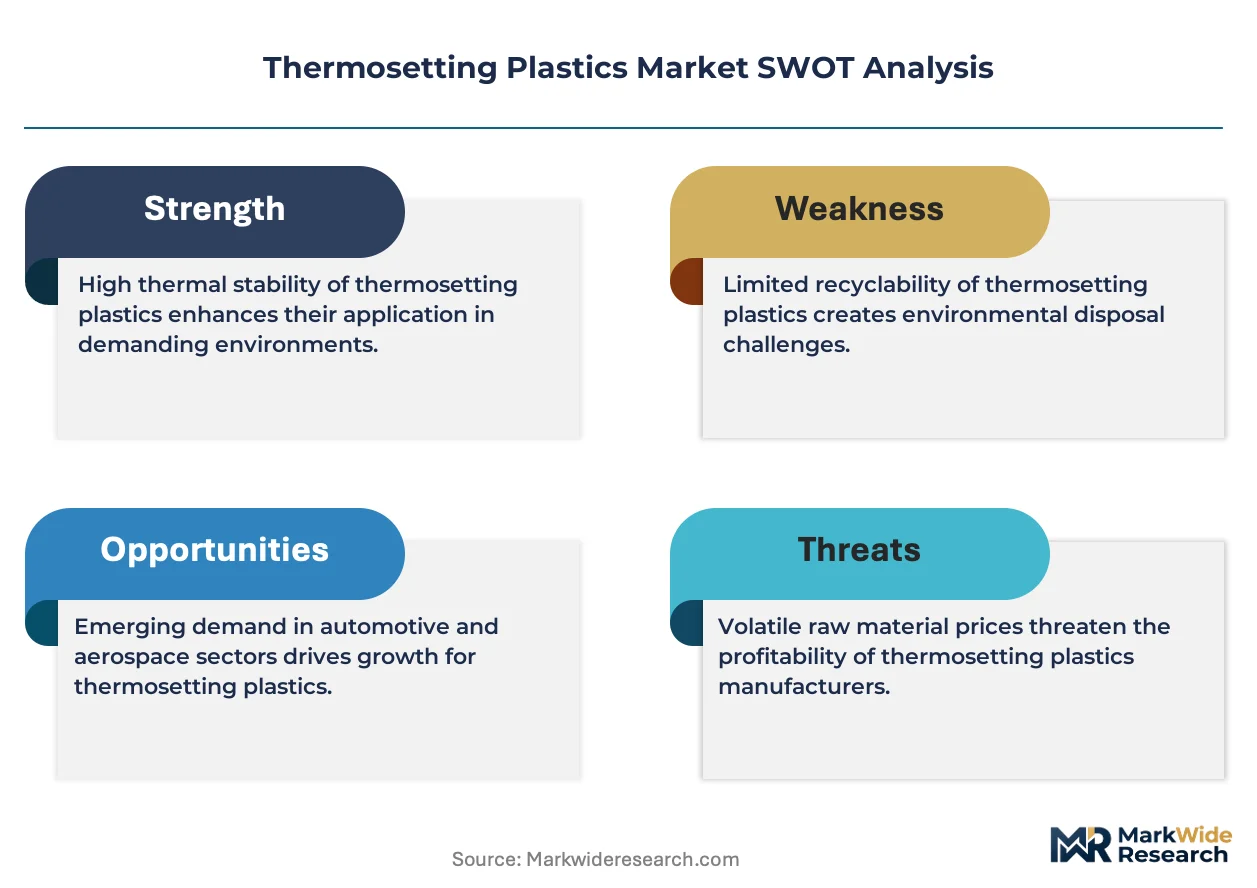
Thermosetting plastics are cross-linked polymers that cure through irreversible chemical reactions, typically requiring heat, catalysts, or radiation to form rigid three-dimensional networks with thermal stability exceeding 150°C and excellent dimensional retention under load. These materials serve critical load-bearing, insulating, and protective functions across transportation, electrical, and construction systems where thermoplastics would soften or deform. Epoxy resins lead the product type landscape due to their adhesion strength and widespread use in fiber-reinforced composites, while polyurethane captures expanding volume in foam insulation and structural adhesives. The coatings application segment generates concentrated margin pools from corrosion-protection specifications in marine and industrial infrastructure, whereas encapsulation demand in electronics tracks semiconductor packaging complexity.
REACH registration requirements administered by ECHA govern monomer and additive compositions entering European manufacturing channels, while China's MEE enforces GB standard emissions limits on phenol and formaldehyde releases from phenolic resin production. The EPA's TSCA framework in the United States imposes pre-manufacture notification obligations on novel thermoset chemistries, shaping R&D investment toward bio-based curing agents. Stakeholders must monitor evolving chemical hazard classifications across these jurisdictions to anticipate reformulation costs and supply qualification timelines.
Market Dynamics
Automotive lightweighting mandates in Germany and China are compressing formulation cycles as OEMs demand epoxy and polyurethane systems with faster cure profiles and higher fiber volume fractions for battery enclosures and structural members.
Growth Catalysts
- REACH chemical registration:ECHA's streamlined substance evaluation is accelerating qualified supplier consolidation across European manufacturing channels, favoring pre-registered resin portfolios.
- Electric vehicle battery housings:Chinese and German OEMs specify thermoset composites for thermal runaway protection, pulling epoxy and phenolic volumes into automotive supply chains.
- Integrated resin-to-composite corridors:Manufacturing clusters in China's eastern provinces reduce logistics friction and qualification timelines for domestic electronics and automotive OEMs.
Market Restraints
- Petrochemical feedstock volatility:Benzene and propylene price swings compress margin visibility for epoxy and polyurethane producers with quarterly contract structures.
- Phenol-formaldehyde supply concentration:Asian phenolic resin production clusters face MEE emissions enforcement, constraining qualified supply for electronics encapsulation grades.
- Thermoplastic composite substitution:High-performance thermoplastics with continuous fiber reinforcement are displacing thermosets in non-structural automotive panels where heat resistance requirements moderate.
Strategic Opportunities
- GB standard emissions compliance:China's volatile organic compound limits create first-mover advantage for waterborne and low-emission curing system developers with pre-certified formulations.
- Modular pre-preg kits:Aerospace MRO operations are fragmenting bulk resin contracts into configured material sets, opening channel margin for specialized distributors.
- Bio-based curing agents:EPA TSCA pre-manufacture notification pathways are redirecting R&D investment toward renewable hardeners with equivalent thermal performance.
Industry Challenges
- Formulation chemist scarcity:Expertise in high-Tg epoxy systems and anhydride curing chemistry is concentrating at specialized compounders, constraining in-house development at mid-tier processors.
- Multi-jurisdiction qualification timelines:Simultaneous ECHA registration, EPA TSCA notification, and China MEE filing requirements extend product launch cycles for novel thermoset chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermosetting Plastics Market |
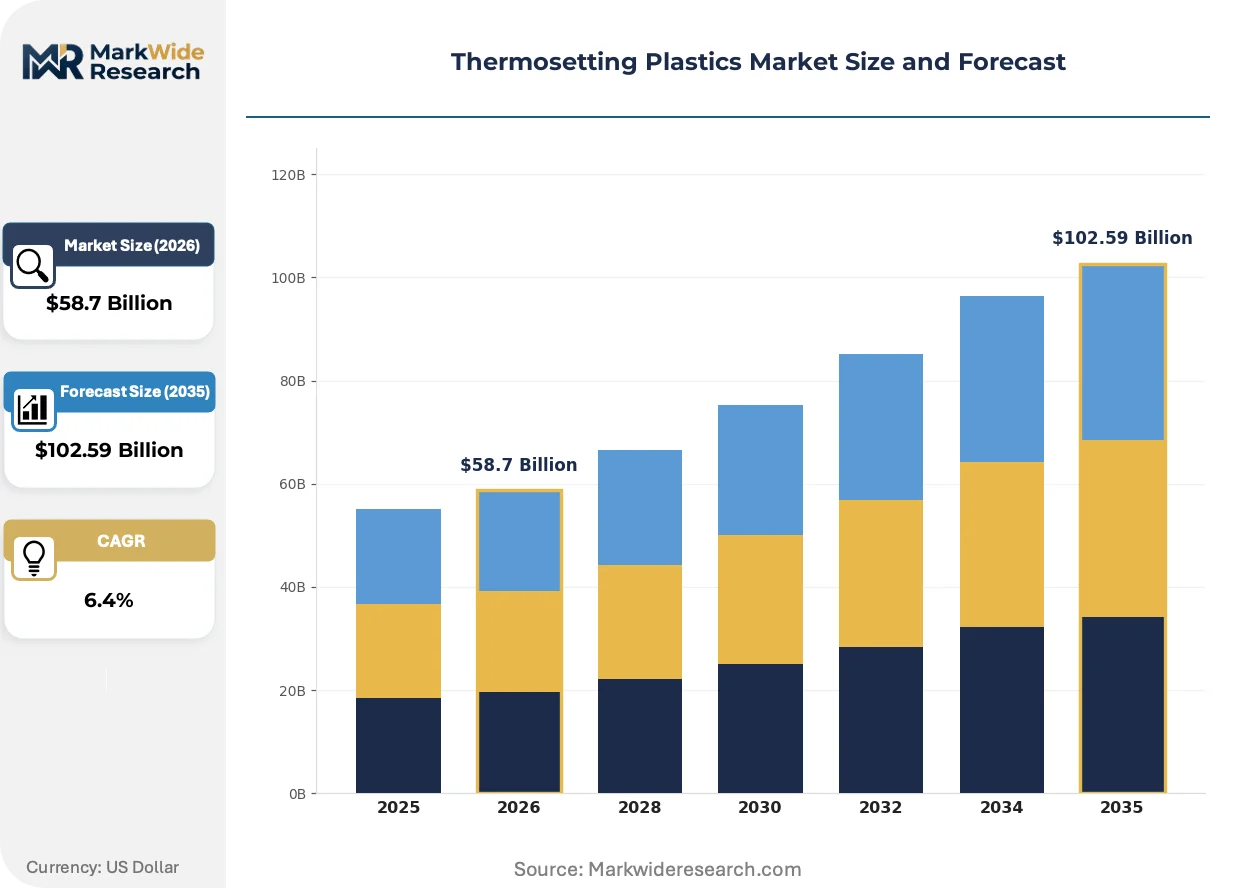
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Unsaturated Polyester, Polyurethane End User: Aerospace, Automotive, Electronics, Construction Application: Adhesives, Coatings, Composites, Encapsulation Form: Powder, Liquid, Sheet, Molding Compound |
| Companies Covered | LANXESS, Daicel Corporation, BASF SE, Asahi Kasei Corporation, Eastman Chemical Company, Celanese Corporation, INEOS, Sumitomo Bakelite, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermosetting Plastics Market Strategic Shifts
Formulation science is converging with process automation as resin suppliers embed sensing and adaptive cure control into production systems, compressing cycle times and reducing scrap rates in high-volume applications.
Dual-cure epoxy systems combining thermal initiation with UV or moisture secondary cure are electrifying throughput in automotive structural bonding and electronics potting operations. Tier-1 suppliers in Germany and China are adopting these platforms for mixed-material assembly lines where heat exposure must be minimized. The technology is electrifying competitive positioning by enabling in-line processing that batch ovens cannot match.
REACH authorization requirements for bisphenol-A derivatives are tightening monomer specifications across European coatings and electronics supply chains. Formulators are qualifying alternative epoxy building blocks with equivalent adhesion and thermal performance. Marine corrosion-protection specifications and semiconductor packaging grades face the steepest reformulation costs and longest requalification timelines.
Specification-driven procurement is fragmenting buyer power as automotive and aerospace OEMs unbundle material supply from processing equipment and technical service. Resin suppliers compete through application engineering support rather than volume pricing alone. This pattern is most pronounced in China's eastern manufacturing corridor where integrated composite processors negotiate direct formulation partnerships.
Thermosetting Plastics Market Segmentation
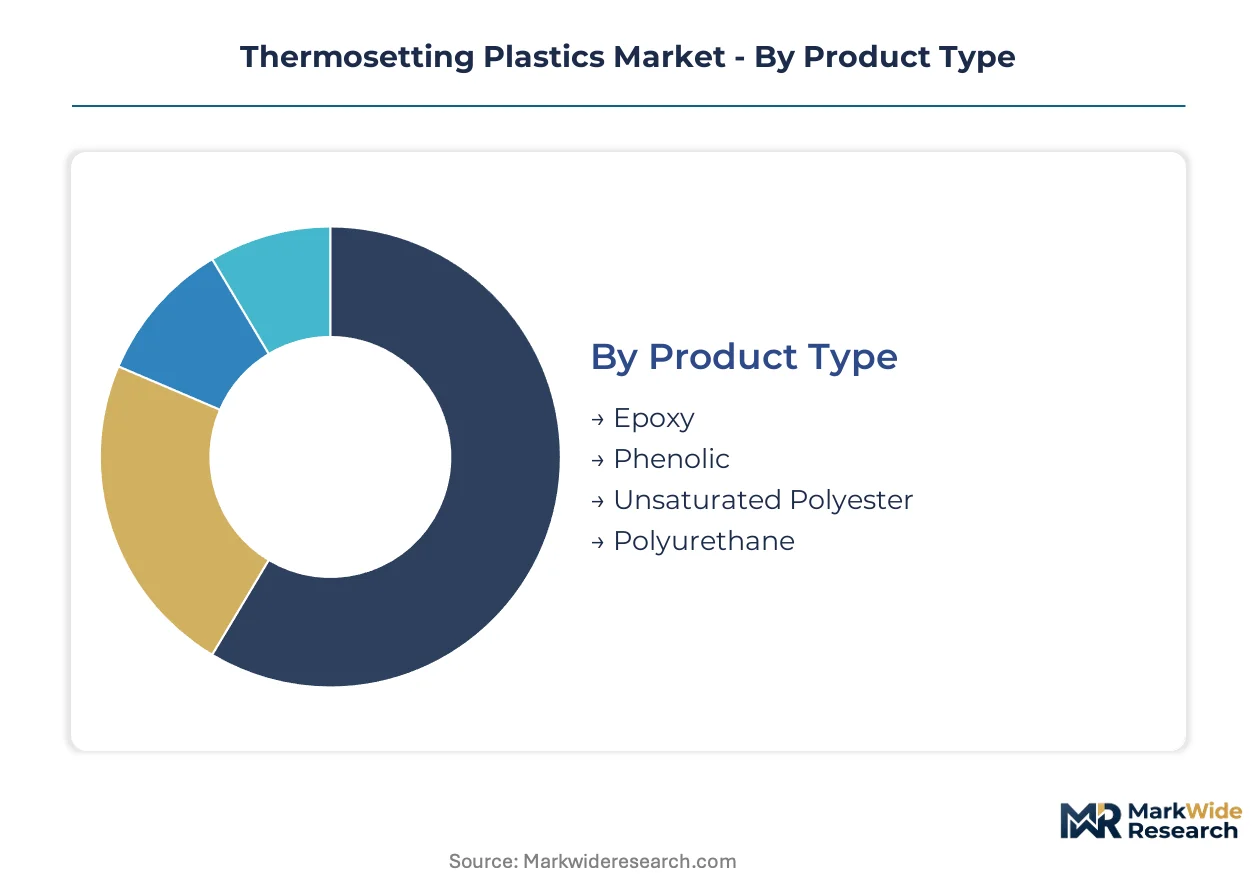
Thermosetting plastics serve both standalone applications and embedded composite systems, with segmentation revealing where formulation complexity commands premium positioning versus where commodity supply dominates. Understanding these integration patterns exposes margin concentration and qualification barriers across supplier tiers.
Product Type:
Epoxy and polyurethane formulations anchor integrated composite supply chains, while phenolic and unsaturated polyester segments serve more discrete component applications with distinct technical service requirements.
- Epoxy:These resins form rigid three-dimensional networks through amine or anhydride curing, delivering adhesion strength above 20 MPa and thermal stability exceeding 180°C. Demand concentrates in German and Chinese automotive battery housings where thermal runaway protection specifications mandate epoxy-based fiber-reinforced composites. REACH authorization pressures on bisphenol-A derivatives are accelerating alternative building block qualification timelines.
- Polyurethane:Isocyanate-polyol reaction chemistry produces tunable density structures from flexible foams to rigid structural adhesives. Chinese eastern corridor manufacturing clusters absorb expanding volumes for electric vehicle structural bonding and insulation systems. BASF's integrated European network anchors automotive supply relationships through just-in-time delivery capabilities.
- Phenolic:Formaldehyde-polycondensation yields excellent flame resistance and low smoke emission for electronics encapsulation and aerospace interior panels.
- Unsaturated Polyester:Styrene-crosslinked formulations dominate marine and corrosion-resistant industrial applications where cost-positioning outweighs thermal performance requirements.
Volume placements concentrate in polyurethane systems; the faster expansion belongs to epoxy formulations serving automotive electrification.
End User:
Customer segments separate by qualification intensity, with aerospace and automotive demanding embedded technical partnerships while electronics and construction procurement favors specification-compliant spot supply.
- Aerospace:Primary structural applications require prepreg systems with glass transition temperatures above 180°C and damage tolerance certification to OEM-specific standards. Solvay's high-performance epoxy platforms dominate European airframe programs where multi-year qualification cycles lock in supplier relationships. Modular pre-preg kit configurations are fragmenting traditional bulk resin contracts into configured material sets.
- Automotive:Lightweighting mandates in Germany and China specify thermoset composites for battery enclosures, floor pans, and structural members. OEMs demand faster cure profiles compatible with 90-second cycle times in high-volume assembly. Dual-cure systems combining thermal and UV initiation are compressing processing windows.
- Electronics:Semiconductor packaging and PCB encapsulation drive phenolic and epoxy molding compound consumption with emphasis on ionic purity and coefficient of thermal expansion matching.
- Construction:Corrosion-resistant piping, panel systems, and architectural composites utilize unsaturated polyester and vinyl ester formulations with lower specification barriers.
Procurement intensity peaks in aerospace; construction applications expand most quickly through infrastructure corrosion-protection specifications.
Application:
Application segmentation tracks where thermosets function as standalone materials versus where they serve as matrix phases in multi-material systems, determining formulation service intensity and margin structure.
- Composites:Fiber-reinforced systems represent the deepest integration point, with resin suppliers co-developing cure cycles and tooling strategies alongside composite processors. China's eastern manufacturing corridor hosts integrated resin-to-fabrication operations serving domestic automotive and electronics OEMs with compressed qualification timelines. Continuous fiber architectures command premium positioning over chopped fiber alternatives.
- Adhesives:Structural bonding applications in mixed-material automotive assembly require tailored rheology and substrate-specific adhesion promoters. Dual-cure epoxy platforms are electrifying throughput by enabling in-line processing without batch oven constraints.
- Coatings:Marine and industrial corrosion-protection specifications generate concentrated margin pools from high-build epoxy and polyurethane systems with extended service life guarantees.
- Encapsulation:Electronics potting and semiconductor packaging demand ultra-low ionic content and precise thermal expansion matching to protect sensitive components.
Specification complexity concentrates in composites; encapsulation climbs fastest alongside semiconductor packaging complexity.
Form:
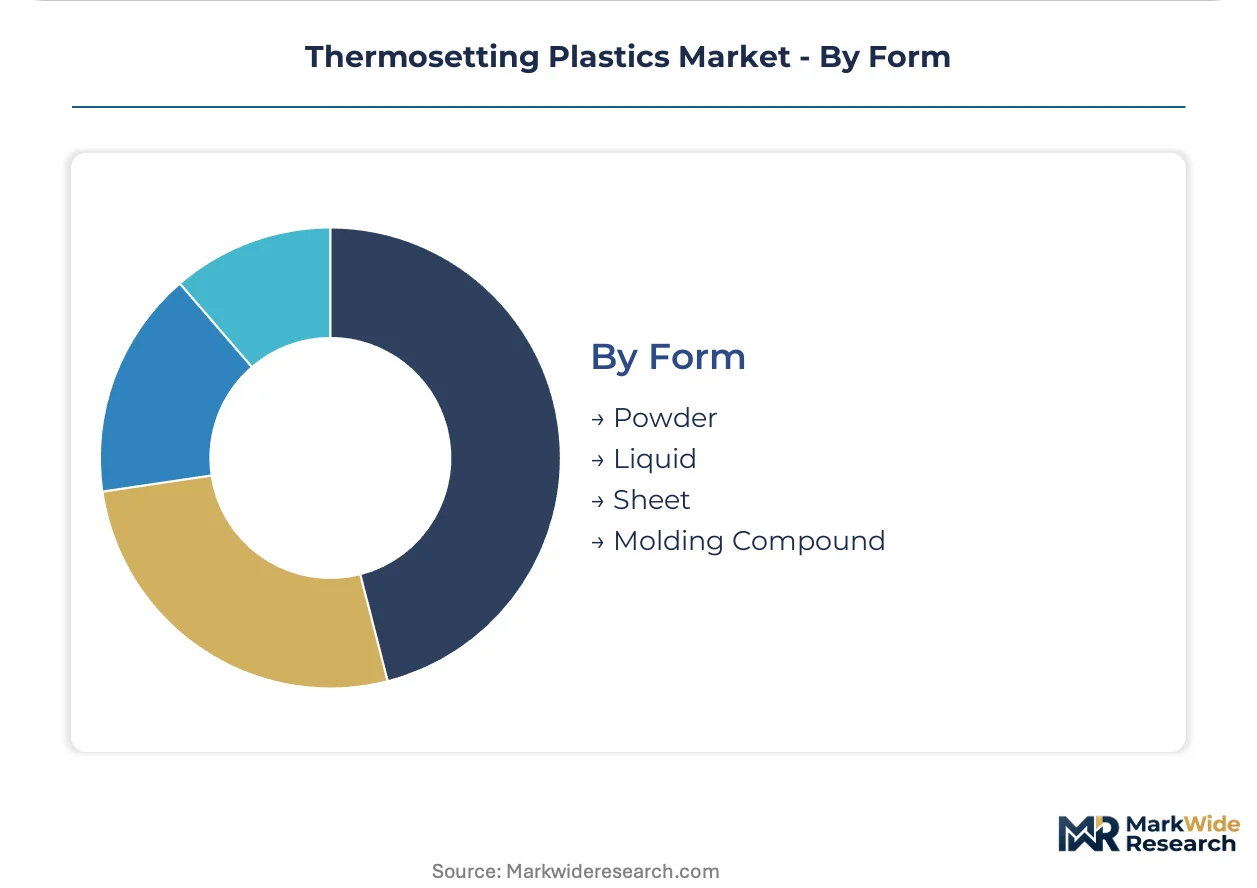
Physical form determines supply chain configuration, with liquid and powder systems enabling dispersed processing while sheet and molding compound formats require specialized handling infrastructure.
- Liquid:Pumpable resin systems support automated metering and mixing in high-volume composite and adhesive operations, with viscosity stabilization critical for consistent fiber wet-out.
- Powder:Solid epoxy and polyester formulations enable electrostatic coating application and extended shelf stability without refrigeration requirements.
- Sheet:Pre-impregnated fiber sheets demand cold-chain logistics and precise tack-life management, fragmenting supply toward specialized distributors with aerospace MRO expertise.
- Molding Compound:Phenolic and epoxy BMC/SMC formats consolidate resin, filler, and reinforcement for direct compression or injection molding in electronics and automotive components.
Processing flexibility favors liquid systems; sheet formats gain share fastest through aerospace MRO channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor operates as a bonded-zone concentration point, drawing resin suppliers and composite fabricators into integrated supply chains that serve domestic automotive and electronics OEMs with compressed logistics friction.
China
Electric vehicle battery housing programs at BYD and CATL pull epoxy and phenolic volumes into automotive supply chains with thermal runaway protection specifications. MEE enforcement of GB standards on volatile organic compound emissions constrains qualified phenol-formaldehyde supply for electronics encapsulation grades. The Yangtze River Delta hosts captive resin-to-composite operations serving semiconductor packaging and automotive tier-1 suppliers.
Germany
BMW and Volkswagen lightweighting mandates specify thermoset composites for floor pans and structural battery enclosures requiring 90-second cure compatibility. ECHA's REACH authorization timelines for bisphenol-A derivatives accelerate alternative epoxy building block qualification. Bavaria's chemical corridor anchors BASF's integrated polyurethanes network with just-in-time delivery to Stuttgart and Munich automotive clusters.
United States
EPA TSCA pre-manufacture notification obligations redirect R&D investment toward bio-based curing agents with equivalent thermal performance. Boeing and Lockheed Martin aerospace programs sustain demand for high-Tg prepreg systems with damage tolerance certification. The Gulf Coast petrochemical corridor supplies benzene and propylene feedstocks to epoxy and polyurethane producers with quarterly contract exposure to price volatility.
Japan
Sumitomo Bakelite concentrates phenolic molding compound production for semiconductor packaging and PCB encapsulation with ionic purity requirements. METI carbon neutrality roadmaps pressure reformulation toward lower-emission curing systems. The Kansai industrial belt hosts integrated electronics materials suppliers serving Osaka-Kyoto semiconductor fabrication clusters.
South Korea
LG Chem and Samsung SDI battery programs absorb expanding epoxy composite volumes for cell-to-pack structural integration. MFDS chemical substance registration aligns with REACH-equivalent hazard classification timelines. The Busan-Ulsan petrochemical complex supplies upstream monomers to domestic resin compounders serving Gyeonggi-do electronics manufacturers.
Thermosetting Plastics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven commodity supply coexists with application-engineered premium positioning. European and Asian chemical majors anchor integrated resin networks with backward control over monomer supply. Three archetypes dominate: integrated petrochemical-resin compounders, specialized high-performance formulators, and regional distributors with technical service capabilities. Competitive moves concentrate on strategic partnerships for automotive qualification and capacity expansion in China's eastern corridor.
Among diversified chemical conglomerates, BASF SE and INEOS occupy positions exemplifying scale-driven supply chain integration. Solvay sits within the high-performance specialist tier, representing archetype positioning around aerospace and electronics qualification intensity. Sumitomo Bakelite anchors the Asia-focused electronics encapsulation segment, reflecting geographic concentration in semiconductor packaging supply chains.
| Leading Market Players |
|---|
| LANXESS |
| Daicel Corporation |
| BASF SE |
| Asahi Kasei Corporation |
| Eastman Chemical Company |
| Celanese Corporation |
| INEOS |
| Sumitomo Bakelite |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
Captive integration into benzene and propylene feedstock supply anchors both cost position and pricing power for epoxy and polyurethane compounders serving German and Chinese automotive OEMs. Quarterly contract structures expose processors to petrochemical volatility, while REACH-registered resin portfolios command premium positioning in European channels.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as automotive OEMs compress qualification cycles for battery housing programs. Three-tier pricing structure across aerospace-qualified, automotive-specified, and industrial-grade formulations separates Solvay's prepreg systems from commodity unsaturated polyester supply. Cost compression in phenolic molding compounds is intensifying because MEE emissions enforcement constrains qualified Asian supply. Electronics encapsulation buyers exhibit lowest price sensitivity due to ionic purity requirements, while construction applications face spot-market volatility.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Shanghai, and Houston fragment bulk resin logistics into just-in-time deliveries for composite processors. Supply concentrates in Germany, China, and the United States, with the Yangtze River Delta hosting captive resin-to-fabrication corridors. Feedstock dependencies rest on benzene derivatives, propylene oxide, and formaldehyde precursors. Single-source vulnerability runs through Asian phenol-formaldehyde clusters facing emissions enforcement. Distribution runs through specialized distributors with cold-chain capabilities for pre-preg sheet formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermosetting plastics occupy a technology-transition phase as dual-cure epoxy systems displace conventional thermal-cure platforms in automotive structural bonding. Formulation automation and embedded sensing compress cycle times beyond legacy batch oven constraints.
For Market Incumbents: Anticipate thermoplastic composite substitution in non-structural automotive panels by accelerating dual-cure platform qualification with Chinese and German OEMs. Defensive consolidation through backward integration into bio-based curing agent supply secures EPA TSCA compliance pathways. Channel control through technical service partnerships with aerospace MRO distributors locks in specification-driven procurement relationships. For New Entrants and Emerging Players: The premium-to-economy price gap in electronics encapsulation compounds opens white-space targeting of mid-tier semiconductor packaging grades with waterborne phenolic formulations. China's eastern corridor manufacturing clusters offer most penetrable geography through direct partnerships with integrated composite processors. Go-to-market positioning through modular pre-preg kit configurations fragments traditional bulk resin contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty high-performance formulators with aerospace qualification depth and automotive electrification exposure. Long-term viability frames around dual-cure technology adoption curves and REACH-compliant alternative building block portfolios. Acquisition target archetypes include regional distributors with cold-chain logistics capabilities and technical service infrastructure. Watch dual-cure system penetration rates in German automotive assembly lines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | EPA TSCA pre-manufacture notification pathways favor renewable hardener portfolios with equivalent thermal performance. |
| Capacity Expansion in Eastern China Corridor | Yangtze River Delta integrated resin-to-composite operations compress qualification timelines for domestic automotive OEMs. |
| Joint Venture for Dual-Cure Platform Development | BASF's polyurethane network partnerships with German OEMs accelerate 90-second cure cycle compatibility. |
| Long-term Supply Agreement with Aerospace MRO | Modular pre-preg kit configurations fragment bulk contracts toward specialized distributors with technical service depth. |
| Green Manufacturing Transition for REACH Compliance | ECHA authorization timelines for bisphenol-A derivatives accelerate alternative epoxy building block qualification costs. |
Study Parameters
Multi-period observation of resin consumption patterns, formulation cycle times, and regulatory filing volumes anchored the trend analysis, supplemented by interviews with plant managers at European and Asian compounders, procurement leads at automotive Tier 1 suppliers, distribution channel partners handling pre-preg logistics, and technical R&D directors specializing in anhydride curing chemistry. Secondary validation drew from ECHA registration databases, EPA TSCA filings, Chinese MEE emissions disclosures, customs trade data for benzene and propylene derivatives, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down demand modeling from end-use industry consumption.
Input-output matrix frameworks connected feedstock price indices, cure technology adoption curves, and regional regulatory enforcement intensity to volume and value projections across the analysis window. Segmentation dimensions modeled included resin chemistry type, end-use industry vertical, physical form factor, and regional production hub qualification status. CAGRs were derived from slope analysis of fitted trend lines against historical consumption trajectories. Industry-specific forecast inputs incorporated electric vehicle battery housing program announcements and semiconductor packaging complexity indices.
Inputs from ECHA, EPA, and Chinese MEE regulatory filings were available through the study window; gaps in real-time OEM formulation qualification timelines introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding dual-cure technology penetration rates and REACH authorization enforcement schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Bio-Based Polymer Market