
 Temporary Power Generation & Power Rental Market | 2026-2036
Temporary Power Generation & Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Power Generation & Power Rental Market Insights
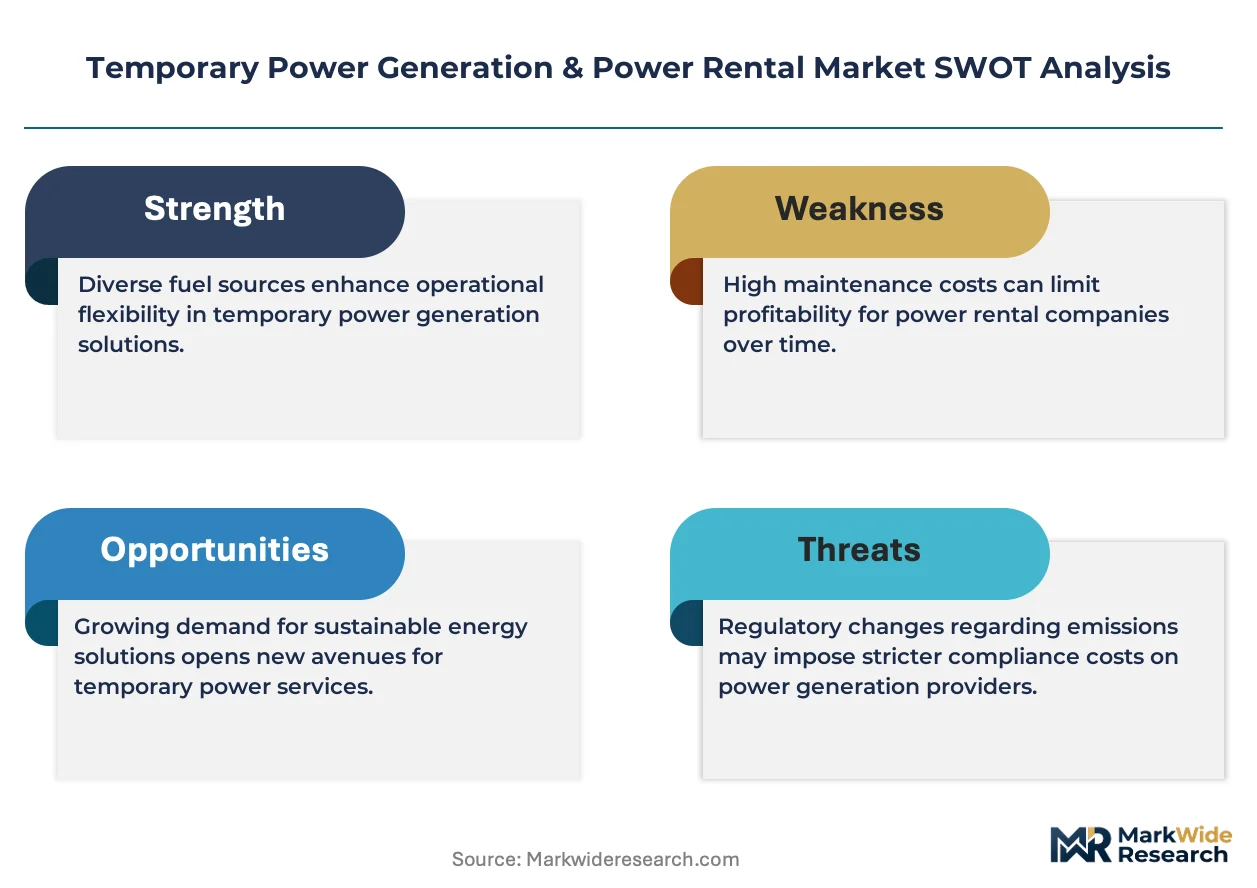
Tier 4 Final compliance specifications is collapsing the addressable market for legacy diesel generator rentals while simultaneously expanding premium-tier replacement demand. Cummins Inc. leverages its integrated engine-manufacturing footprint to anchor North American rental fleet renewals. Aggreko competes through hybrid-gas technology leadership in remote power deployments. Wärtsilä specializes in large-scale modular gas engine packages that dominate grid-stabilization contracts.
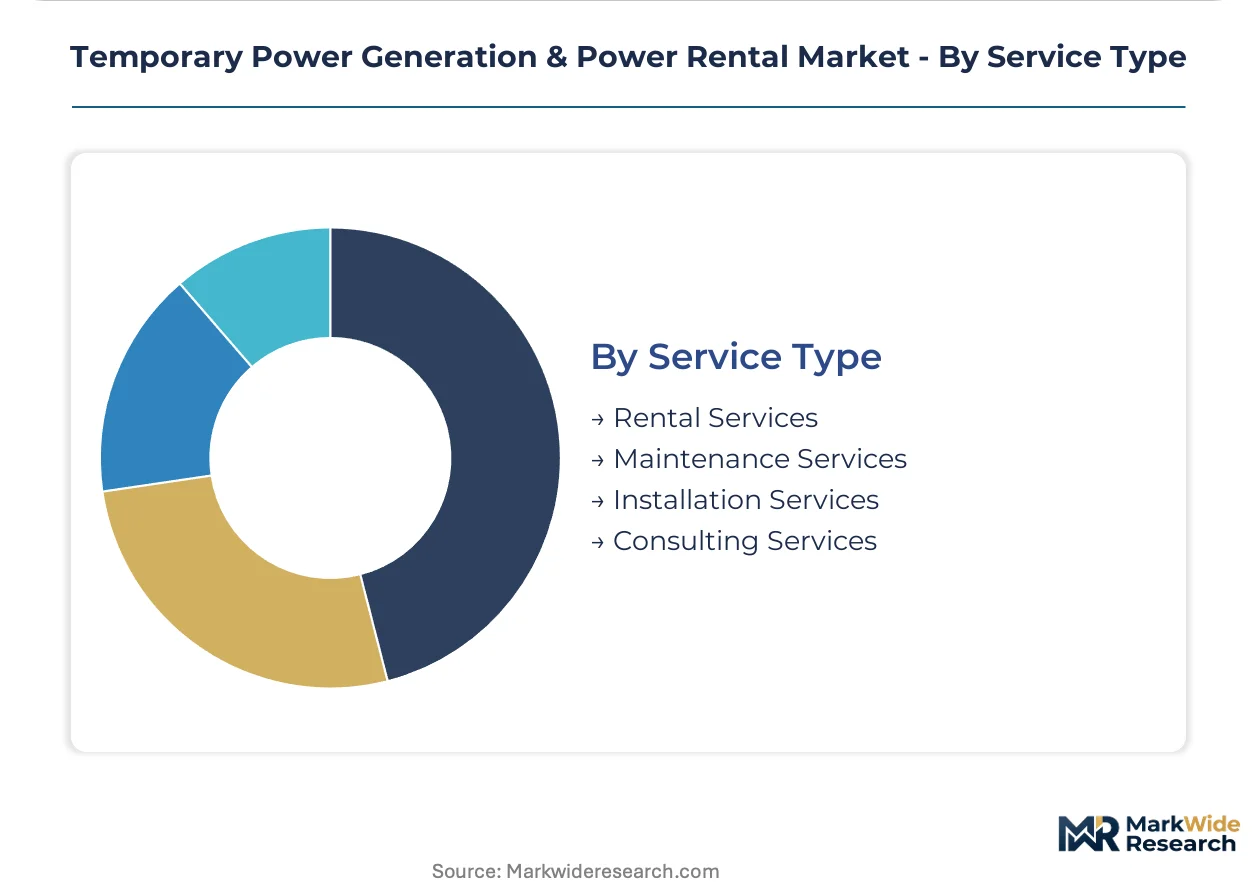
Temporary power generation and power rental encompasses the short-term provision of mobile or modular electricity-producing equipment, typically involving reciprocating engines, gas turbines, or photovoltaic arrays with outputs ranging from 20 kW to 100+ MW, deployed through lease or rental contracts rather than capital purchase. Diesel generators retain the largest installed rental base globally due to fuel availability and load-response reliability, though hybrid generators represent the fastest-expanding product category as fuel-cost volatility and emissions constraints intensify. Rental services capture the dominant revenue share within service-type segmentation, while maintenance services yield superior margins through long-term fleet-management contracts.
The EPA enforces Tier 4 Final particulate and NOx limits on non-road diesel engines in the United States, compelling rental providers to retire non-compliant assets or deploy costly after-treatment systems. India's Central Electricity Authority mandates grid-code compliance for backup power systems above specified thresholds, tightening product certification requirements for rental operators serving industrial clients. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local air-quality regulations that threaten to strand conventional diesel assets before technical end-of-life.
Market Dynamics
The EPA's Tier 4 Final emissions standards are compressing the operational lifespan of legacy diesel rental fleets while simultaneously accelerating capital redeployment toward gas-hybrid and battery-integrated systems. This regulatory pressure is restructuring competitive advantage around after-treatment expertise and alternative fuel infrastructure rather than pure engine scale.
Growth Catalysts
- Data center construction surge:Hyperscale facility builds across Northern Virginia, Frankfurt, and Singapore are generating sustained demand for multi-megawatt modular power packages during grid interconnection delays.
- Grid instability in emerging economies:India's Central Electricity Authority mandates for backup power compliance are forcing industrial clusters in Maharashtra and Gujarat to procure certified rental capacity during monsoon-related outages.
- Hybrid gas engine maturation:Dual-fuel reciprocating engines are capturing share in remote mining and oilfield applications where diesel logistics costs exceed fuel-switching conversion premiums.
Market Restraints
- After-treatment capex burden:Selective catalytic reduction and diesel particulate filter retrofits add 25-40 percent to legacy fleet refurbishment costs, eroding rental economics for sub-500 kW units.
- Engine manufacturing concentration:Critical high-horsepower diesel and gas engine blocks are sourced from a narrowing base of European and US suppliers, creating vulnerability for rental operators scaling above 50 MW deployments.
- Battery energy density ceiling:Lithium-ion systems remain economically unviable for continuous-load applications exceeding four-hour duration without diesel or gas backup integration.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:NEOM and Red Sea tourism developments are specifying temporary power as permanent grid infrastructure lags construction timelines by 18-36 months.
- Carbon border adjustment preparation:EU importers of rental services are pre-certifying equipment emissions profiles to avoid tariff exposure under the Carbon Border Adjustment Mechanism phase-in.
- Virtual power plant aggregation:Distributed rental assets are being enrolled in grid-balancing markets through automated dispatch platforms, creating incremental revenue streams beyond base rental rates.
Industry Challenges
- Tier 4 Final technician scarcity:After-treatment system diagnostics and urea infrastructure maintenance require specialized training that rental operators struggle to staff across dispersed deployment sites.
- Interconnection queue uncertainty:Utility timeline opacity for permanent power hookups complicates rental contract duration pricing and fleet rotation planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Power Generation & Power Rental Market |
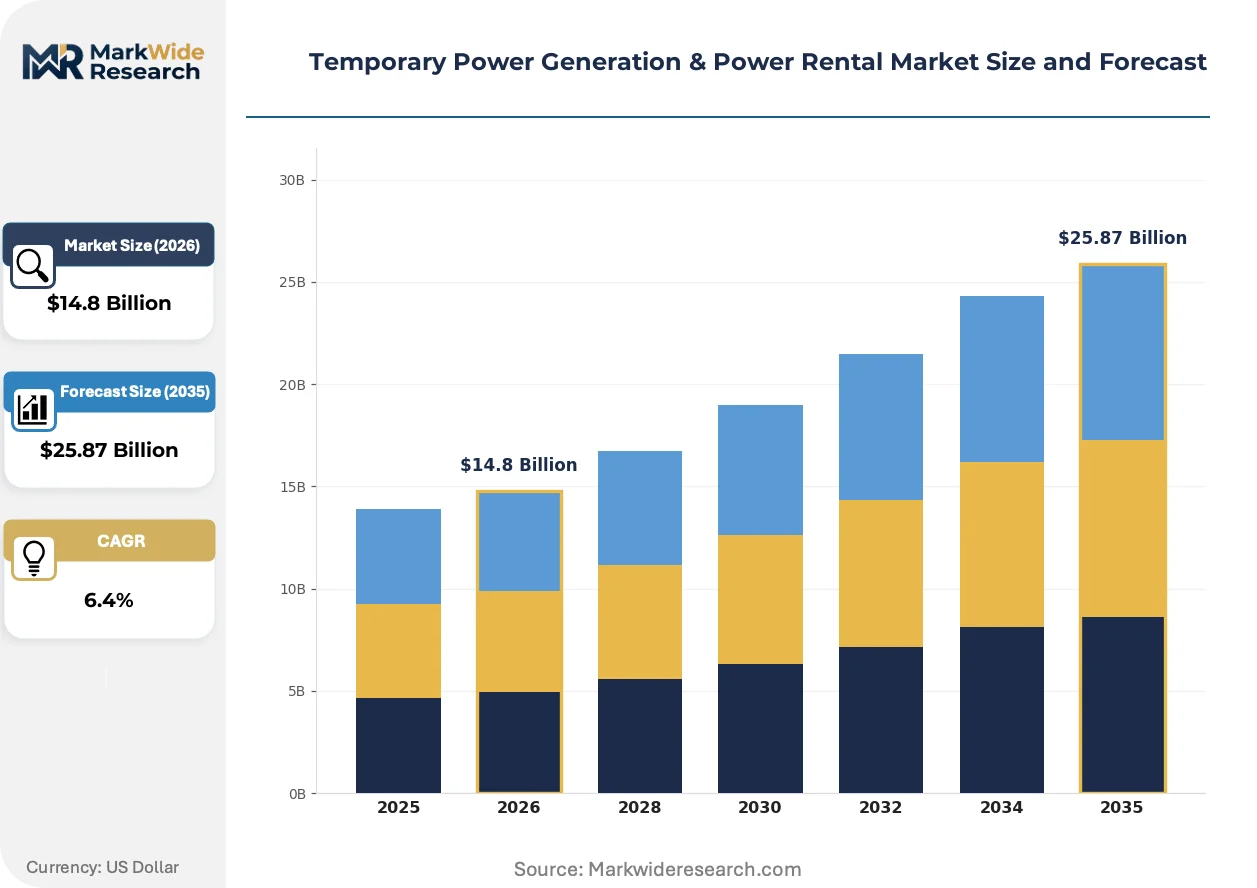
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Solar Generators Application: Event Management, Construction Sites, Emergency Backup, Industrial Operations End User: Construction Companies, Event Organizers, Data Centers, Industries Service Type: Rental Services, Maintenance Services, Installation Services, Consulting Services |
| Companies Covered | United Rentals, APR Energy, Aggreko, Generac Holdings, Atlas Copco, Caterpillar Inc., Ashtead Group, Wärtsilä, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Power Generation & Power Rental Market Trends and Innovations
Equipment form factors and fuel pathways are converging toward containerized, software-optimized systems that reduce site preparation requirements and enable faster redeployment between projects. This compression of mobilization timelines is reshaping how rental operators structure availability guarantees and pricing models.
Containerized battery energy storage systems paired with inverter packages are miniaturizing the footprint required for short-duration peak shaving and renewable firming applications. Data center developers in hyperscale clusters are adopting these systems for construction-phase power quality management. The technology is compressing traditional diesel generator procurement cycles for sub-10 MW temporary loads.
EPA enforcement of Tier 4 Final particulate and NOx limits on non-road diesel engines is forcing rental providers to accelerate fleet turnover or deploy costly exhaust after-treatment. Industrial customers in Texas and California are now specifying Tier 4 Final compliance as a contract prerequisite regardless of project duration. The regulation is concentrating procurement authority among rental operators with integrated engine manufacturing relationships.
Power-as-a-service contracting is displacing traditional dry-hire rental arrangements for extended-duration projects in mining and oilfield segments. Operators in Western Australia's Pilbara region are signing 24-36 month contracts that bundle fuel, maintenance, and carbon reporting rather than managing these inputs separately. This bundling is most visible in jurisdictions with stringent Scope 1 emissions disclosure requirements.
Temporary Power Generation & Power Rental Market Segmentation
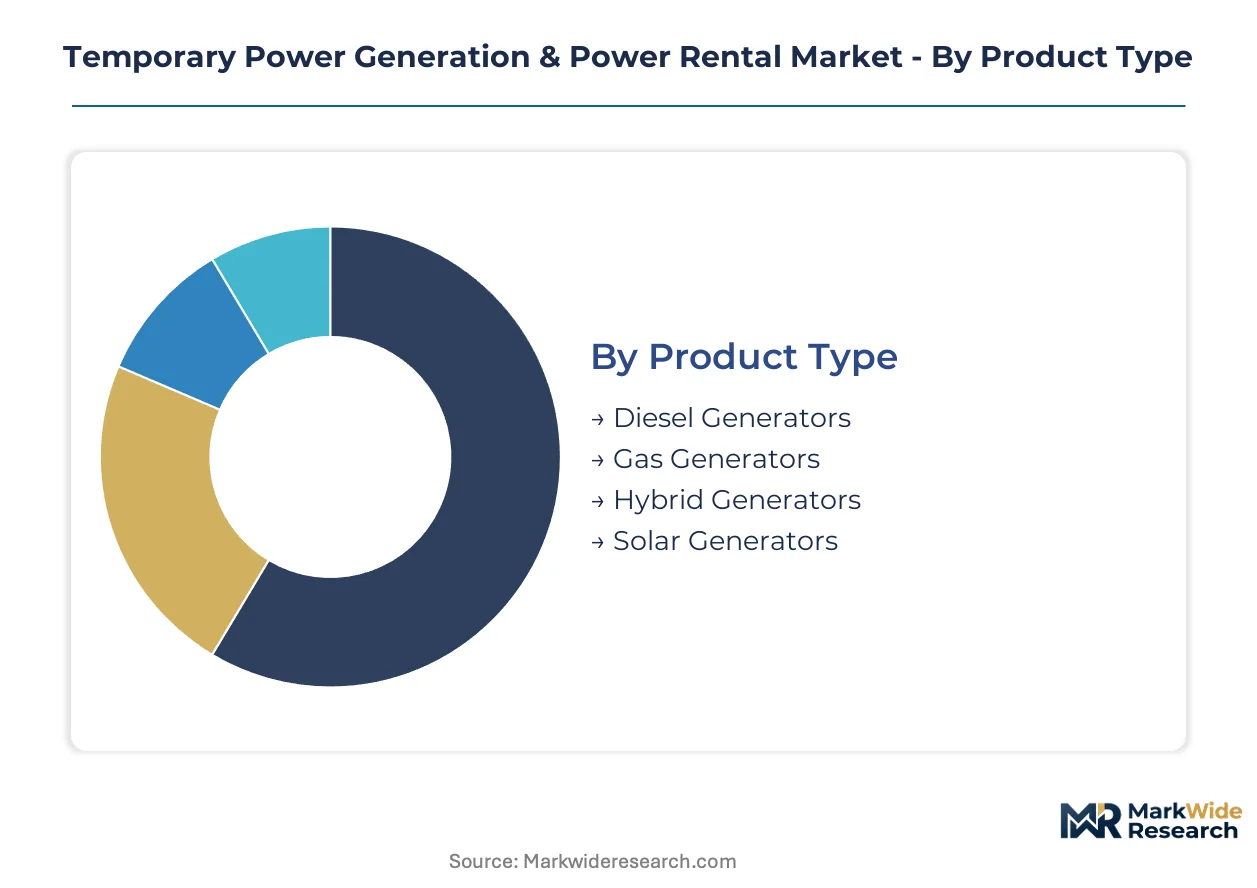
Equipment specifications and service bundling determine contract economics across temporary power deployments. Regulatory compliance tiers and fuel pathway choices create distinct customer acquisition costs and margin profiles for rental operators.
Product Type:
EPA Tier 4 Final particulate limits and India's CEA grid-code mandates are segmenting procurement by emissions certification grade rather than pure output capacity.
- Diesel Generators:Reciprocating engines running distillate fuel with outputs from 20 kW to 2 MW dominate installed rental fleet value. Demand concentrates in Texas and Maharashtra industrial corridors where fuel logistics infrastructure supports continuous-load operations and grid interconnection delays extend 12-24 months.
- Hybrid Generators:Battery-integrated systems with diesel or gas prime movers enable load-following with reduced runtime hours. Data center construction clusters in Northern Virginia and Frankfurt are specifying these units for construction-phase power quality management where emissions disclosure requirements apply.
- Gas Generators:Spark-ignited or dual-fuel reciprocating engines utilize pipeline natural gas or LNG virtual pipelines.
- Solar Generators:Photovoltaic arrays with integrated inverters and battery storage provide zero-direct-emission temporary power.
Established volume favors diesel generators; emerging adoption favors hybrid generators.
Application:
Duration and load predictability separate pricing models across use cases, with multi-year contracts commanding different service bundling than spot rentals.
- Industrial Operations:Continuous-load deployments exceeding 6,000 annual operating hours require Tier 4 Final compliance or equivalent certification. Petrochemical clusters in Gujarat and manufacturing zones near Houston sustain the longest average contract durations.
- Construction Sites:Variable-load applications with seasonal mobilization patterns favor containerized systems with rapid redeployment capability. Saudi giga-projects specify 18-36 month contracts as permanent grid infrastructure lags construction timelines.
- Emergency Backup:Standby power for grid instability or disaster response prioritizes fuel availability and black-start capability.
- Event Management:Short-duration deployments under 72 hours emphasize acoustic attenuation and rapid site preparation.
Contract duration separates industrial operations from event management; margin contribution inverts this pattern.
End User:
Capital intensity and in-house engineering capability determine whether customers procure dry-hire equipment or bundled power-as-a-service contracts.
- Data Centers:Hyperscale facility developers in Singapore and Frankfurt require multi-megawatt modular packages during utility interconnection queues. These customers specify Tier 4 Final compliance regardless of project duration and prioritize carbon reporting integration.
- Industries:Manufacturing and processing facilities with captive maintenance teams favor rental-only arrangements with fuel self-supply. Indian textile and pharmaceutical clusters drive demand for CEA-certified backup systems above 1 MW threshold.
- Construction Companies:Project-based contractors with dispersed sites favor fully serviced contracts including fuel logistics.
- Event Organizers:Seasonal demand with limited technical staff requires turnkey acoustic and electrical distribution packages.
Technical sophistication favors data centers; price sensitivity favors construction companies.
Service Type:
Revenue recognition timing and working capital requirements vary sharply between asset-heavy rental operations and labor-intensive maintenance contracts.
- Rental Services:Equipment lease revenue tied to availability guarantees and utilization rates captures the dominant share of industry revenue. Fleet rotation planning and residual value management determine operator profitability across 5-7 year asset lifecycles.
- Maintenance Services:Long-term fleet management contracts including preventive maintenance, after-treatment system servicing, and urea logistics yield superior margins. Western Australia's Pilbara mining region demonstrates 24-36 month bundled contracts displacing dry-hire arrangements.
- Installation Services:Site preparation, electrical distribution, and commissioning for temporary deployments.
- Consulting Services:Load profiling, emissions compliance strategy, and grid interconnection planning.
Asset intensity favors rental services; margin expansion favors maintenance services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine manufacturing and rental fleet operations concentrate among US, German, and Japanese suppliers, with demand fragmentation across infrastructure corridors in India, Saudi Arabia, and Australia. Rental procurement patterns diverge sharply between mature markets where emissions compliance dominates contract terms and emerging economies where grid instability sustains diesel-based deployments.
United States
Data center construction in Northern Virginia and Texas sustains multi-megawatt rental demand during utility interconnection delays. The EPA enforces Tier 4 Final particulate and NOx limits on non-road diesel engines, compelling fleet turnover or costly after-treatment retrofits. Petrochemical clusters near Houston operate the longest-duration rental contracts for continuous-load industrial power.
Germany
Manufacturing zones in Bavaria and North Rhine-Westphalia procure certified backup systems under grid-code stability mandates. The EU Carbon Border Adjustment Mechanism pressures rental operators to pre-certify equipment emissions profiles for cross-border project work. Frankfurt's hyperscale data center corridor generates sustained demand for modular gas-hybrid packages during construction phases.
India
Textile and pharmaceutical clusters in Maharashtra and Gujarat drive procurement of Central Electricity Authority-certified backup systems above 1 MW thresholds. The CEA mandates grid-code compliance for backup power systems, tightening product certification requirements for industrial clients. Monsoon-related outages in Mumbai and Ahmedabad sustain spot rental markets for emergency capacity.
Saudi Arabia
NEOM and Red Sea tourism developments specify temporary power as permanent grid infrastructure lags construction timelines by 18-36 months. The Saudi Standards, Metrology and Quality Organization enforces equipment certification for large-scale energy projects. Riyadh-based contractors dominate procurement for giga-project pipelines requiring containerized modular systems.
Australia
Mining operations in Western Australia's Pilbara region sign 24-36 month power-as-a-service contracts bundling fuel, maintenance, and carbon reporting. The Australian Energy Regulator oversees grid connection standards that delay permanent power hookups at remote extraction sites. Perth-based rental operators specialize in hybrid gas engine deployments for diesel logistics cost reduction.
Temporary Power Generation & Power Rental Market Competitive Landscape
Concentration sits with integrated engine manufacturers and specialized rental fleet operators rather than diversified industrial conglomerates. The market structures around three archetypes: vertically integrated engine producers with captive rental channels, pure-play rental specialists with multi-fuel technology portfolios, and regional equipment lessors with dense service networks. Competitive dynamics center on fleet emissions compliance upgrades and hybrid technology licensing arrangements rather than pure scale expansion.
Among integrated engine producers with rental exposure, Cummins Inc. and Caterpillar Inc. anchor the premium tier through manufacturing relationships that secure Tier 4 Final-compliant power blocks. Aggreko occupies a distinct position as a rental pure-play with documented hybrid-gas technology leadership in remote deployments. Wärtsilä exemplifies the large-scale modular gas engine specialist serving grid-stabilization contracts above 50 MW. United Rentals and Ashtead Group represent the capital-intensive equipment lessor archetype with dense North American and European service footprints.
| Leading Market Players |
|---|
| United Rentals |
| APR Energy |
| Aggreko |
| Generac Holdings |
| Atlas Copco |
| Caterpillar Inc. |
| Ashtead Group |
| Wärtsilä |
| Cummins Inc. |
| Others |
Pricing and Supply Chain Analysis
Fleet utilization rates above 70 percent in multi-megawatt diesel generator categories compress unit economics for Tier 4 Final-compliant assets while simultaneously elevating price floors for certified rental capacity. This scale threshold concentrates procurement leverage among operators with captive engine manufacturing relationships, forcing smaller lessors toward hybrid-gas technology partnerships or regional consolidation.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the temporary power rental landscape. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified units with integrated after-treatment from legacy diesel assets requiring retrofit or geographic restriction. Cost compression in the sub-500 kW segment is intensifying because selective catalytic reduction and diesel particulate filter retrofits add substantial refurbishment burden. Construction companies exhibit highest price sensitivity due to project-based budgeting, while data center developers prioritize emissions certification over rate negotiation.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for containerized generator sets and battery energy storage systems. Critical high-horsepower engine blocks draw from concentrated manufacturing footprints in the United States, Germany, and Japan, with cylinder heads and turbocharger assemblies resting on European supplier networks. Single-source vulnerability persists for gas engine control systems and power electronics modules. Distribution runs through regional equipment lessors with dense service footprints rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance services and long-term fleet management contracts represent a service-attach opportunity expanding faster than hardware rental revenue, as Western Australia's Pilbara mining region demonstrates with 24-36 month bundled arrangements displacing traditional dry-hire.
For Market Incumbents: Shield core rental margins by accelerating backward integration into after-treatment system servicing and urea logistics infrastructure. Consolidate regional lessors in Maharashtra and Gujarat to capture CEA-certified backup demand above 1 MW thresholds. Battery energy density limitations in continuous-load applications create a defensive moat for diesel-gas hybrid fleets through the mid-cycle phase. For New Entrants and Emerging Players: CEA grid-code certification fast-tracks market access for industrial backup contracts in Indian textile and pharmaceutical clusters. Target Saudi giga-project pipelines where permanent grid infrastructure lags construction timelines by 18-36 months, specifying containerized modular systems. Lead with power-as-a-service bundling that integrates fuel logistics and carbon reporting to differentiate from established dry-hire operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rental operators with documented hybrid-gas technology leadership and established EPA Tier 4 Final fleet compliance. Long-term viability centers on virtual power plant aggregation capabilities and automated dispatch platform integration. Monitor interconnection queue transparency improvements as the signal indicating permanent power timeline compression that would reduce extended-duration rental demand.| Strategic Initiative | Industry Significance |
|---|---|
| After-Treatment Service Network Expansion | Captures maintenance service margins from Tier 4 Final compliance requirements across Texas and California industrial corridors. |
| Hybrid-Gas Technology Licensing | Enables remote mining and oilfield deployments where diesel logistics costs exceed fuel-switching conversion premiums. |
| Virtual Power Plant Aggregation Platform | Creates incremental revenue streams beyond base rental rates through automated enrollment in grid-balancing markets. |
| CEA Certification Fast-Track Investment | Unlocks industrial backup contracts in Maharashtra and Gujarat above 1 MW thresholds under grid-code mandates. |
| Carbon Border Adjustment Pre-Certification | Protects EU cross-border project work from tariff exposure under Carbon Border Adjustment Mechanism phase-in. |
Research Methodology
Cross-validation between primary interviews with rental fleet managers, EPC contractors, and data center development executives and secondary sources including EIA power generation data, EPA enforcement records, and FERC interconnection queue filings anchors the qualitative findings. Utility planning officers, IPP project developers, and aftermarket service heads provided operational context on fleet rotation economics and maintenance contract structures. Bottom-up equipment deployment tracking and top-down regional demand estimation triangulate market sizing.
Sensitivity analysis across fuel price volatility scenarios and regulatory enforcement intensity variations informs the analytical framework. Modeled segmentation spans fuel source, generation capacity tier, project duration, emissions certification grade, and regional grid stability profile. CAGRs derive from installed base turnover rates and replacement demand elasticity rather than extrapolated shipment data. Interconnection queue depth and utility timeline opacity serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Tier 4 Final enforcement and continued hyperscale data center construction in Northern Virginia, Frankfurt, and Singapore; material deviation in regulatory stringency or infrastructure investment pacing would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
United Kingdom Power Market
Power Generation
Solar Generator Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Marine Power Plant Market
Power Generation
Oman Power Market
Power Generation
Global Gensets Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Microturbine Market
Power Generation
Mobile Power Plant Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Retail Electricity Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Captive Power Plant Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Southeast Asia Power Generation EPC Market