
 Malaysia Power Generation EPC Market | 2026-2036
Malaysia Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Power Generation EPC Market Foresight
Data center load growth is repositioning Malaysia's power generation EPC priorities as hyperscale facility developers seek dedicated clean energy supply. Cypark Resources Berhad leverages its landfill solar expertise to compete for utility-scale tenders in Peninsular Malaysia. General Electric Company sustains gas turbine technology leadership through combined cycle upgrades at existing TNB plants. Scatec ASA anchors its regional presence with floating solar EPC capabilities at hydroelectric reservoir sites.
Power generation engineering, procurement, and construction encompasses the integrated delivery of power plants from conceptual design through commissioning, typically spanning 24–48 months for utility-scale projects and requiring turbine-generator alignment tolerances within 0.05 mm for rotating equipment. The primary purpose centers on translating energy resource assessments into operational generation assets with guaranteed output and heat rate performance. Renewable energy solutions lead product type demand as Malaysia's Large Scale Solar program drives procurement volume, while combined cycle systems retain margin concentration through efficiency upgrade cycles at aging CCGT stations. Smart grids represent the fastest-growing technology segment as grid codes mandate enhanced frequency response from new interconnectors serving industrial zones.
Malaysia's Energy Commission (ST) enforces grid connection standards under the Electricity Supply Act, while the Sustainable Energy Development Authority (SEDA) administers feed-in tariff and net energy metering frameworks that shape project economics for EPC bidders. The Ministry of Investment, Trade and Industry (MITI) coordinates power sector licensing with national industrial master plan targets, creating compliance layers for foreign EPC contractors. Stakeholders must monitor the evolving balance between gas-fired baseload retention and renewable energy dispatch priority as Malaysia's grid code revisions approach finalization.
Market Dynamics
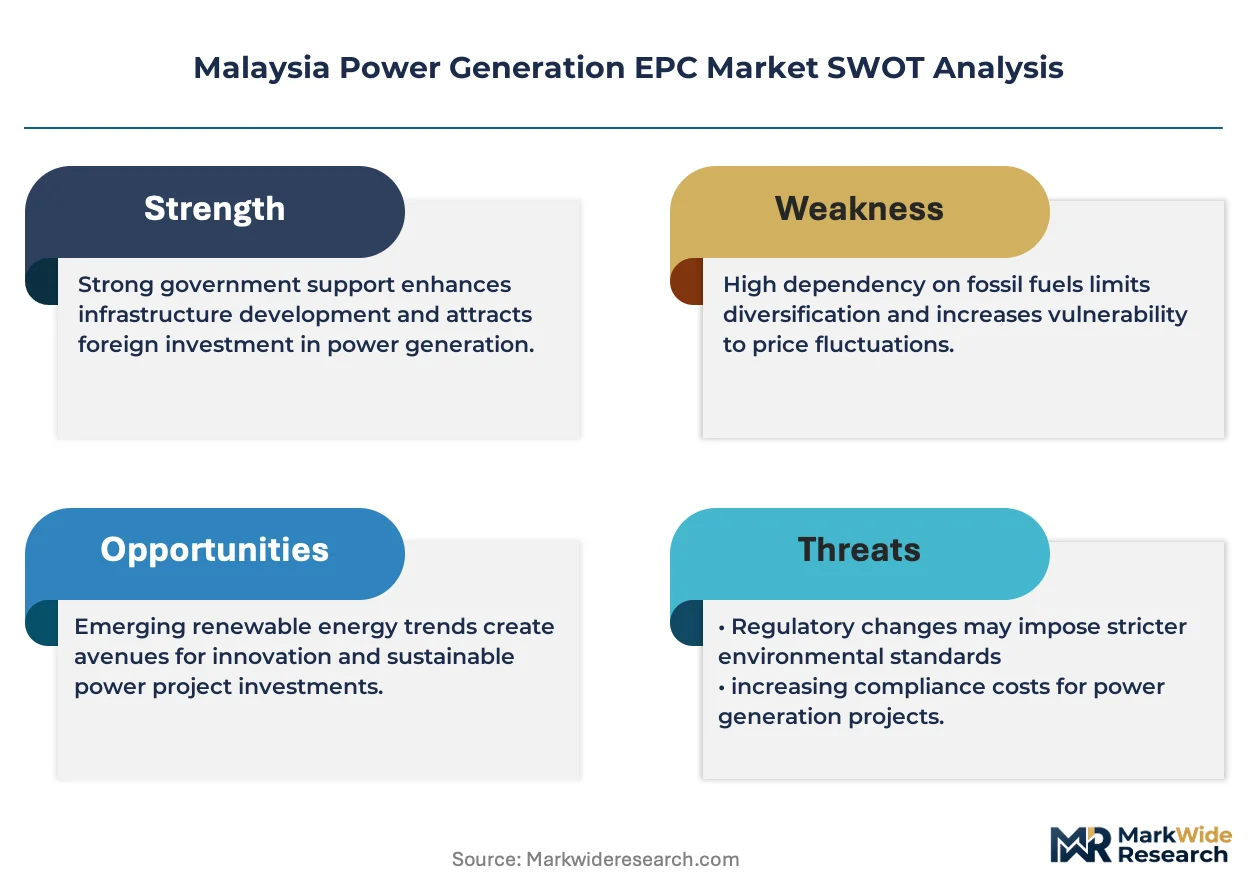
Malaysia's power generation EPC market is being fundamentally restructured by the Energy Commission's grid code revisions, which mandate enhanced frequency response capabilities from new interconnectors serving industrial zones and data center clusters.
Growth Catalysts
- Large Scale Solar Program:SEDA's procurement framework under the Malaysia Renewable Energy Roadmap creates guaranteed offtake volumes for utility-scale photovoltaic EPC contracts.
- Data center load expansion:Hyperscale facility developers in Johor and Selangor require dedicated clean energy supply agreements, driving demand for integrated generation and transmission EPC packages.
- Floating solar deployment:Reservoir sites at hydroelectric dams offer dual-use land advantages that reduce permitting timelines for EPC bidders with specialized marine construction capabilities.
Market Restraints
- Gas turbine supply concentration:Heavy rotating equipment for combined cycle upgrades depends on a limited set of European and Japanese original equipment manufacturers, creating procurement bottlenecks.
- Grid interconnection queuing:The Energy Commission's connection study backlog extends project commissioning schedules, compressing EPC contractor cash conversion cycles.
- Labor cost inflation:Specialist welding and high-voltage termination skills command premium rates in Peninsular Malaysia's tight construction labor market.
Strategic Opportunities
- East Malaysia penetration:Sarawak's hydroelectric surplus and Sabah's isolated grid create demand for transmission infrastructure EPC that Peninsular contractors have underdeveloped.
- Battery energy storage integration:Grid code revisions enabling ancillary services revenue streams allow EPC contractors to bundle BESS with solar generation assets.
- Net Energy Metering expansion:SEDA's commercial and industrial tariff reforms open distributed generation EPC opportunities outside utility-scale tender processes.
Industry Challenges
- Turbine-generator alignment precision:Rotating equipment installation demands tolerances within 0.05 mm that exceed standard civil construction workforce capabilities, requiring specialized subcontractor relationships.
- Legacy CCGT integration complexity:Efficiency upgrade projects at aging Tenaga Nasional Berhad plants must synchronize new digital control systems with existing analog protection schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Power Generation EPC Market |
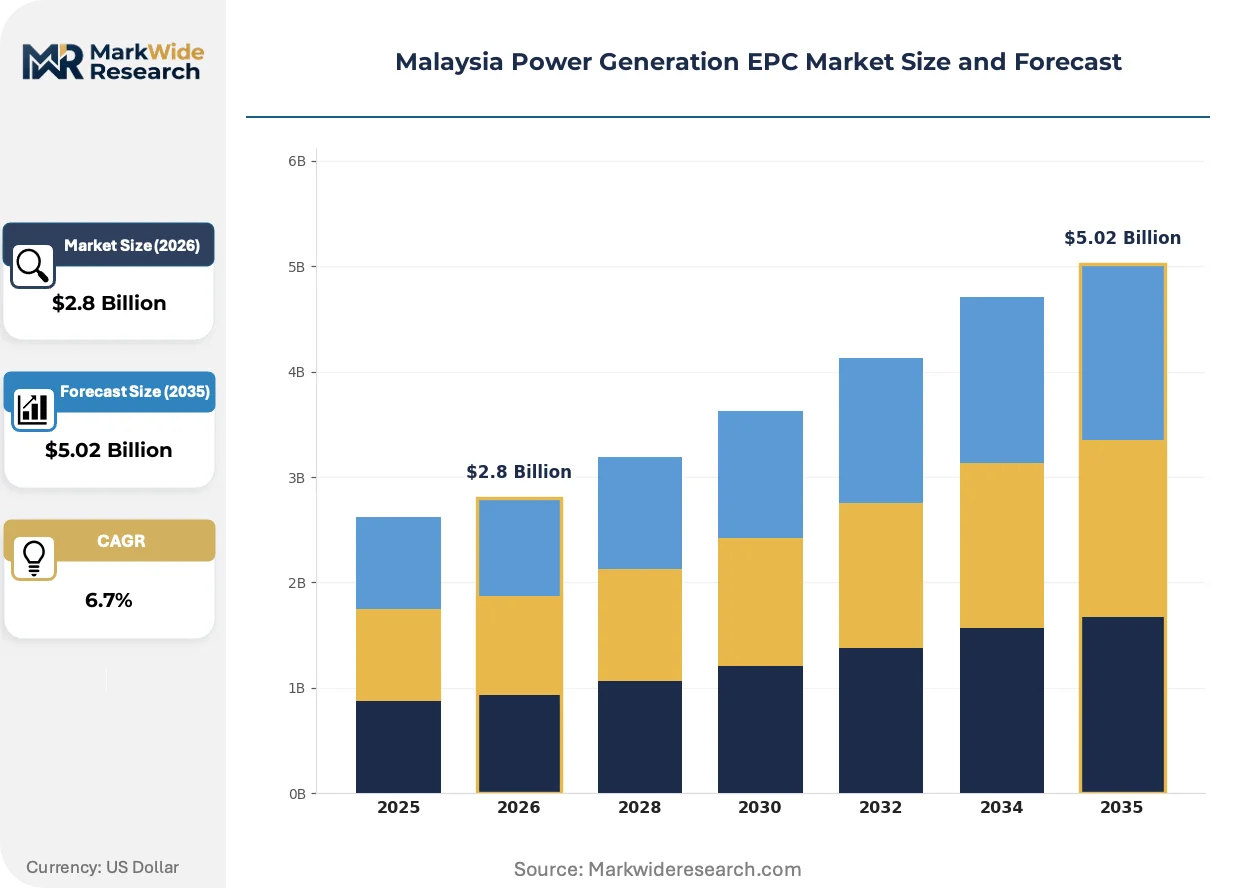
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Combined Cycle Systems, Renewable Energy Solutions Technology: Conventional Power, Renewable Energy, Hybrid Systems, Smart Grids End User: Utilities, Independent Power Producers, Industrial Users, Government Service Type: Design, Procurement, Construction, Maintenance |
| Companies Covered | Cypark Resources Berhad, General Electric Company, Scatec ASA, Toshiba Corporation, Sumitomo Corporation, Solarvest Holdings, Kpower Berhad, AFRY AB, Sunway Construction Group Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Power Generation EPC Market Shifts & Advancements
Digitization of plant control systems and modular construction methods are compressing EPC delivery timelines while raising performance guarantee thresholds for Malaysian power projects.
Hybrid inverter technology is unifying solar photovoltaic and battery energy storage power conversion into single hardware platforms. Industrial zone developers in Iskandar Malaysia are specifying these integrated systems to reduce footprint and balance-of-plant costs. This convergence is unifying procurement decisions that previously separated generation and storage EPC contracts into bundled single-source awards.
The Energy Commission's Enhanced Frequency Response mandate under pending grid code revisions requires new interconnectors above 30 MW to demonstrate synthetic inertia capabilities. Gas turbine and battery EPC contractors must now engineer plant-level control responses that were previously grid-operator responsibilities. Peninsular Malaysia's data center corridors face the steepest compliance curves as their load concentrations trigger the threshold requirements.
Power purchase agreement structures are migrating from capacity-based to availability-based remuneration, transferring operational risk to EPC contractors through extended warranty and performance guarantee clauses. Engineering firms are responding by embedding predictive maintenance systems into initial plant design rather than treating aftermarket services as separate revenue streams. This behavioral shift is most pronounced in solar EPC contracts for corporate offtakers in Selangor and Penang.
Malaysia Power Generation EPC Market Segmentation

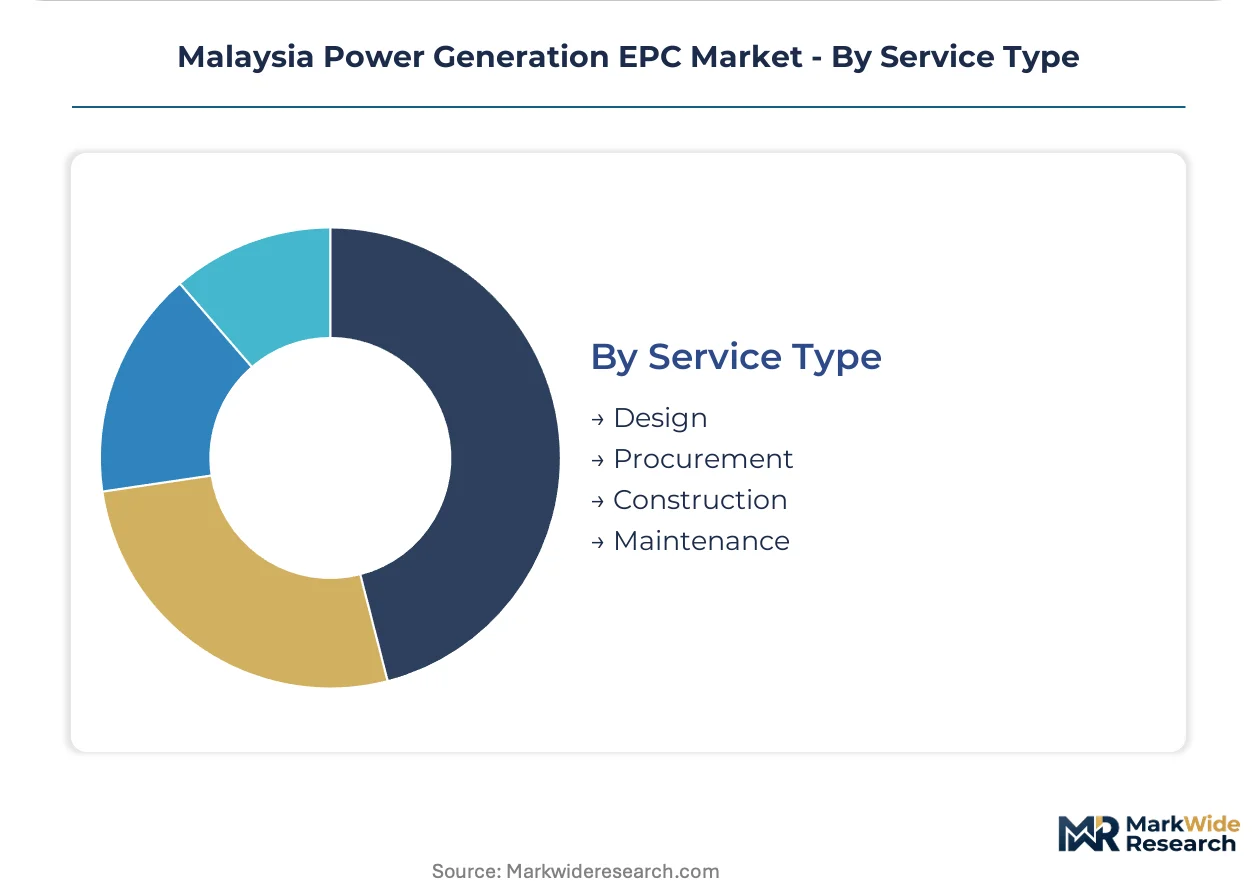
Malaysia's power generation EPC market segments along technology capability, procurement structure, and end-use concentration. Each axis reveals distinct competitive positioning requirements for contractors bidding under SEDA's procurement frameworks and TNB's upgrade cycles.
Product Type:
Technology specifications determine engineering workforce requirements and equipment sourcing strategies for EPC contractors operating in Peninsular Malaysia.
- Gas Turbines:Heavy rotating equipment installations demand alignment tolerances within 0.05 mm for generator coupling. Tenaga Nasional Berhad's aging CCGT fleet drives recurring upgrade demand at Sultan Iskandar and Pasir Gudang power stations.
- Renewable Energy Solutions:Photovoltaic and floating solar systems dominate new capacity procurement under Malaysia's Large Scale Solar program. EPC contractors with marine construction capabilities capture reservoir dual-use projects at hydroelectric dam sites.
- Steam Turbines:Coal and biomass plant retrofits require specialized welding protocols for high-pressure piping systems.
- Combined Cycle Systems:Efficiency upgrade cycles at existing stations bundle gas turbine, heat recovery steam generator, and steam turbine refurbishment into integrated contracts.
Renewable Energy Solutions leads on scale; Combined Cycle Systems leads on momentum.
Technology:
Plant control architectures separate legacy analog systems from digital platforms that enable grid code compliance.
- Smart Grids:Enhanced Frequency Response mandates under pending Energy Commission revisions require synthetic inertia capabilities above 30 MW interconnectors. Data center clusters in Johor and Selangor face the steepest compliance thresholds.
- Hybrid Systems:Unified solar-plus-storage power conversion platforms reduce balance-of-plant costs for industrial zone developers. Iskandar Malaysia specifications increasingly favor single-source EPC awards over separated generation and storage contracts.
- Conventional Power:Coal and gas-fired baseload retention depends on digital control retrofits synchronized with existing protection schemes.
- Renewable Energy:Large-scale solar and floating photovoltaic deployments concentrate demand for integrated EPC services across Peninsular Malaysia.
Smart Grids leads on scale; Hybrid Systems leads on momentum.
End User:
Procurement authority and offtake structure shape EPC contract terms and performance guarantee requirements.
- Independent Power Producers:Merchant and contracted generators drive new capacity additions under Malaysia's renewable energy transition policies. Corporate power purchase agreements transfer operational risk to EPC contractors through availability-based remuneration clauses.
- Utilities:Tenaga Nasional Berhad controls transmission interconnection queues and grid code enforcement. Upgrade projects at existing CCGT stations require synchronization with legacy analog protection systems.
- Industrial Users:Hyperscale data center developers in Johor and Selangor seek dedicated clean energy supply agreements with bundled generation and transmission EPC packages.
- Government:Federal and state entities procure distributed generation through SEDA's Net Energy Metering frameworks for public buildings.
Independent Power Producers leads on scale; Industrial Users leads on momentum.
Service Type:
Work scope bundling determines contractor margin structure and long-term revenue capture.
- Construction:Civil works, equipment installation, and commissioning span 24–48 months for utility-scale projects. Specialist welding and high-voltage termination skills command premium rates in Peninsular Malaysia's tight labor market.
- Procurement:Heavy equipment sourcing concentrates among European and Japanese original equipment manufacturers for gas turbine components. Supply bottlenecks extend project schedules and compress contractor cash conversion cycles.
- Design:Conceptual engineering and grid connection studies face backlog delays at the Energy Commission, extending front-end timelines.
- Maintenance:Predictive maintenance system embedding into initial plant design replaces separate aftermarket service contracts under extended warranty structures.
Construction leads on scale; Procurement leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peninsular Malaysia's industrial corridor from Johor to Selangor concentrates the nation's power generation EPC demand through data center load growth and utility-scale solar deployment.
Johor
Data center clusters in Iskandar Malaysia drive dedicated clean energy supply agreements for hyperscale facility developers. The Sustainable Energy Development Authority's Large Scale Solar program channels procurement toward integrated generation and transmission EPC packages. Pasir Gudang hosts combined cycle upgrade cycles at aging Tenaga Nasional Berhad stations requiring precision alignment capabilities.
Selangor
Corporate power purchase agreements in the Klang Valley transfer operational risk to contractors through availability-based remuneration clauses. The Energy Commission's grid code revisions mandate enhanced frequency response from new interconnectors above 30 MW. Cyberjaya and Putrajaya host floating solar EPC opportunities at hydroelectric reservoir sites with dual-use land advantages.
Penang
Industrial zone developers specify hybrid solar-plus-storage systems to reduce balance-of-plant costs for manufacturing facilities. The Ministry of Investment, Trade and Industry coordinates power sector licensing with national industrial master plan targets. Bayan Lepas and Batu Kawan concentrate demand for Net Energy Metering distributed generation EPC outside utility-scale tender processes.
Sarawak
Hydroelectric surplus creates transmission infrastructure EPC demand that Peninsular contractors have historically underdeveloped. The state's isolated grid structure requires specialized interconnection engineering distinct from peninsula standards. Kuching and Miri anchor renewable energy integration projects serving local industrial load centers.
Sabah
Grid stability challenges drive battery energy storage bundling opportunities with solar generation assets under pending ancillary services frameworks. The state's dispersed geography favors modular construction methods that compress EPC delivery timelines. Kota Kinabalu and Sandakan concentrate public building distributed generation through federal procurement channels.
Malaysia Power Generation EPC Market Competitive Landscape
Strategic partnerships dominate the current landscape as contractors bundle generation, storage, and transmission capabilities into single-source awards. The vendor base organizes around three tiers: integrated conglomerates with marine construction capabilities, specialized renewable energy developers with landfill solar expertise, and international equipment suppliers with gas turbine technology leadership. Two competitive vectors shape positioning: technology licensing arrangements for rotating equipment precision, and geographic expansion into East Malaysia's underpenetrated transmission infrastructure segment.
Within the integrated conglomerate tier, Sunway Construction Group Bhd and Kpower Berhad exemplify contractors pursuing bundled EPC packages across civil works, equipment installation, and commissioning. Among international technology providers, General Electric Company and Toshiba Corporation anchor the heavy rotating equipment segment through combined cycle upgrade relationships with national utility Tenaga Nasional Berhad. Scatec ASA occupies a position within the specialized renewable developer archetype, with floating solar capabilities at hydroelectric reservoir sites distinguishing its regional presence.
| Leading Market Players |
|---|
| Cypark Resources Berhad |
| General Electric Company |
| Scatec ASA |
| Toshiba Corporation |
| Sumitomo Corporation |
| Solarvest Holdings |
| Kpower Berhad |
| AFRY AB |
| Sunway Construction Group Bhd |
| Others |
Supply & Pricing Matrix
Data center developers' mandatory clean energy procurement specifications are forcing EPC contractors to absorb premium equipment costs for hybrid solar-plus-storage systems, compressing margins on bundled generation and transmission contracts while elevating price differentiation between marine-capable integrated providers and standard civil construction firms.
Pricing Analysis
Input-cost pass-through from heavy rotating equipment suppliers in Europe and Japan anchors EPC contract pricing, with alignment-precision capabilities and digital control integration driving tiered pricing structures across premium, standard, and economy service levels. Price differentiation stems from marine construction certification and synthetic inertia compliance engineering. Pricing pressure intensifies in utility-scale solar segments as SEDA's competitive tender processes compress developer margins and cascade downstream to EPC bidders. Independent power producers exhibit highest price sensitivity due to merchant exposure, while hyperscale data center operators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Direct-to-utility channels handle Tenaga Nasional Berhad's combined cycle upgrade demand, while project-specific procurement serves independent power producer tenders under SEDA frameworks. Manufacturing concentration for gas turbine components rests on Germany, Japan, and South Korea, with floating solar hardware sourcing from China and Taiwan. Critical dependencies include high-grade steel forgings, power electronics, and precision bearings. Single-source vulnerability around heavy rotating equipment OEMs creates procurement bottlenecks. Distribution runs through authorized equipment representatives and integrated EPC conglomerates with in-house marine construction divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's power generation EPC market functions as a stable compounder, with renewable energy transition policies under the Malaysia Renewable Energy Roadmap ensuring steady procurement volume through SEDA's guaranteed offtake frameworks.
For Market Incumbents: Deepen backward integration into marine construction capabilities to capture floating solar reservoir projects and defend against specialized renewable developers. Strengthen precision alignment subcontractor networks to maintain rotating equipment installation leadership as Tenaga Nasional Berhad's CCGT fleet ages. Prioritize grid code compliance engineering investments ahead of Energy Commission synthetic inertia mandates. For New Entrants and Emerging Players: Begin with East Malaysia transmission infrastructure specialization, where Sarawak's hydroelectric surplus and Sabah's isolated grid create white-space opportunities that Peninsular contractors have underdeveloped. Target battery energy storage integration as the most penetrable segment under pending ancillary services frameworks. Pursue joint-venture structures with local civil construction firms to overcome licensing barriers under MITI coordination. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap EPC contractors possessing marine construction certifications and existing SEDA framework relationships. Long-term viability centers on technology licensing arrangements for rotating equipment precision and geographic expansion capabilities. Monitor Energy Commission grid code finalization timing as the critical inflection indicator for BESS bundling revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Construction Certification | Unlocks floating solar EPC opportunities at hydroelectric reservoir sites with dual-use land advantages. |
| Grid Code Compliance Engineering | Enables synthetic inertia capability integration for data center corridor interconnectors above 30 MW threshold. |
| Backward Integration into BESS | Captures ancillary services revenue streams through bundled solar-plus-storage single-source awards. |
| East Malaysia Geographic Expansion | Addresses transmission infrastructure demand that Peninsular contractors have historically underdeveloped. |
| Predictive Maintenance System Embedding | Transforms extended warranty structures from cost centers into recurring revenue capture mechanisms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from Energy Commission regulatory filings, SEDA procurement databases, IEA power sector reports, and project development registries. Bottom-up capacity addition tracking and top-down macroeconomic scenario analysis enabled triangulation across modeling approaches.
Segment-weighting across the projection horizon applied technology capability, procurement structure, and end-use concentration dimensions, with fuel source, generation capacity tier, and regional grid type as industry-specific modeling layers. CAGRs were derived from installed capacity pipeline analysis and historical tender award patterns. Forecast inputs incorporated SEDA Large Scale Solar procurement schedules and data center load growth projections from industrial zone developers.
Several conditions sit outside the modeled scope, including unannounced grid code revision timing, sudden feed-in tariff suspension, and geopolitical disruption to heavy equipment supply chains. Forecasts reflect assumptions about regulatory continuity and equipment availability that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Global Gensets Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Mobile Power Plant Market
Power Generation
Global Turbines Market
Power Generation
Steam Turbine Market
Power Generation
East Africa Power Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
India Thermal Power Plant Market
Power Generation
Global Gas Turbines Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Thermal Power Market
Power Generation
Third Generation Energy Sources Market