
 India Gas Generator Market | 2026-2036
India Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
India Gas Generator Market Foresight
A capital-intensity divergence between domestic assemblers and multinational OEMs is unwinding competitive dynamics in India's gas generator sector. Cummins Inc leverages its integrated engine-generator manufacturing footprint to sustain price competitiveness across medium and high power segments. Kirloskar Electric Company Limited anchors its position through deep channel penetration into Maharashtra's industrial corridors and aftermarket service density. Caterpillar Inc competes on technology leadership in ultra high power installations for critical infrastructure buyers.
India gas generators are stationary internal combustion engine systems that convert gaseous fuel energy into electrical power through synchronous alternators, typically operating at 50 Hz with voltage outputs from 230V single-phase to 11kV three-phase for grid-parallel or island mode applications. Natural gas units dominate installed base economics where pipeline access exists, while biogas variants are gaining traction in agricultural and food processing clusters seeking waste-to-energy compliance. Low and medium power outputs occupy the volume-intensive commercial and residential backup segment, whereas high and ultra high power categories concentrate margin pools in industrial captive power and data center applications. Fixed installation types constitute the structural majority, though mobile configurations serve construction and event rental demand with faster depreciation cycles.
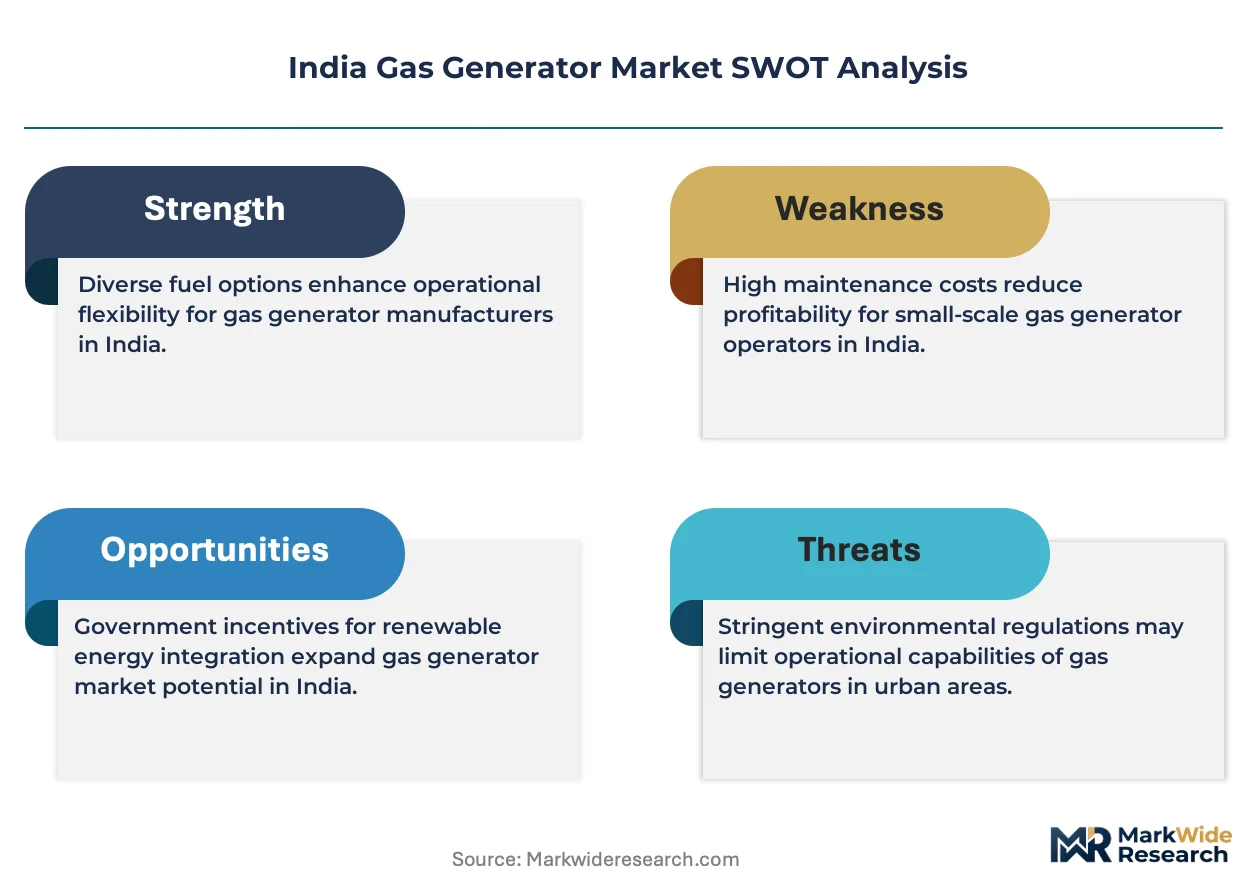
The Central Electricity Authority enforces grid interconnection standards and emission monitoring protocols for captive power plants above defined thresholds, while the Bureau of Indian Standards prescribes product safety and performance benchmarks under IS 4722 and related specifications. State-level electricity regulatory commissions in Gujarat, Karnataka, and Tamil Nadu administer open access regulations that influence the economic calculus of gas-based captive generation versus grid dependence. Stakeholders must monitor evolving carbon pricing mechanisms and renewable purchase obligation rules that could reframe gas generators as bridging assets or stranded investments depending on policy trajectory.
Market Dynamics
Grid reliability failures across Maharashtra and Tamil Nadu are accelerating captive power investments, while the Central Electricity Authority tightens emission monitoring protocols that favor gas over diesel alternatives.
Growth Catalysts
- Data center expansion:Hyperscale facilities in Mumbai and Hyderabad require redundant baseload capacity as utility outages disrupt operations. These installations favor high-output gas systems for continuous runtime economics.
- Bureau of Indian Standards certification:Updated IS 4722 specifications for synchronous alternator performance create quality barriers that favor established OEMs with testing infrastructure.
- Agricultural waste-to-energy clusters:Biogas digester installations in Punjab and Haryana food processing zones generate captive fuel supplies for distributed generation assets.
Market Restraints
- Pipeline access concentration:Natural gas distribution infrastructure clusters along the Hazira-Vijaipur-Jagdishpur network, leaving eastern and northeastern states dependent on costlier LNG trucking.
- Spark plug and catalyst supply:Precision ignition components and exhaust after-treatment systems rely on German and Japanese suppliers, exposing assemblers to currency volatility and extended lead times.
- Renewable purchase obligations:State electricity regulatory commissions in Karnataka and Gujarat mandate solar-wind quotas that compress the permitted operating hours for gas-based captive plants.
Strategic Opportunities
- Biogas purification upgrading:Membrane and pressure-swing adsorption systems that clean agricultural methane to pipeline quality open rural deployment without grid gas access.
- Containerized mobile units:Skid-mounted generator packages serve construction and event rental markets with faster capital recovery through depreciation acceleration.
- Production-linked incentive scheme:Domestic value-addition requirements for engine components create localization partnerships between multinational OEMs and Indian machine shops.
Industry Challenges
- Combustion tuning expertise:Calibrating fuel-air ratios across varying gas compositions requires specialized technicians scarce outside Mumbai and Delhi industrial corridors.
- CEA interconnect compliance:Captive plants above threshold capacities face extended approval timelines for grid-parallel operation, delaying commercial commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gas Generator Market |
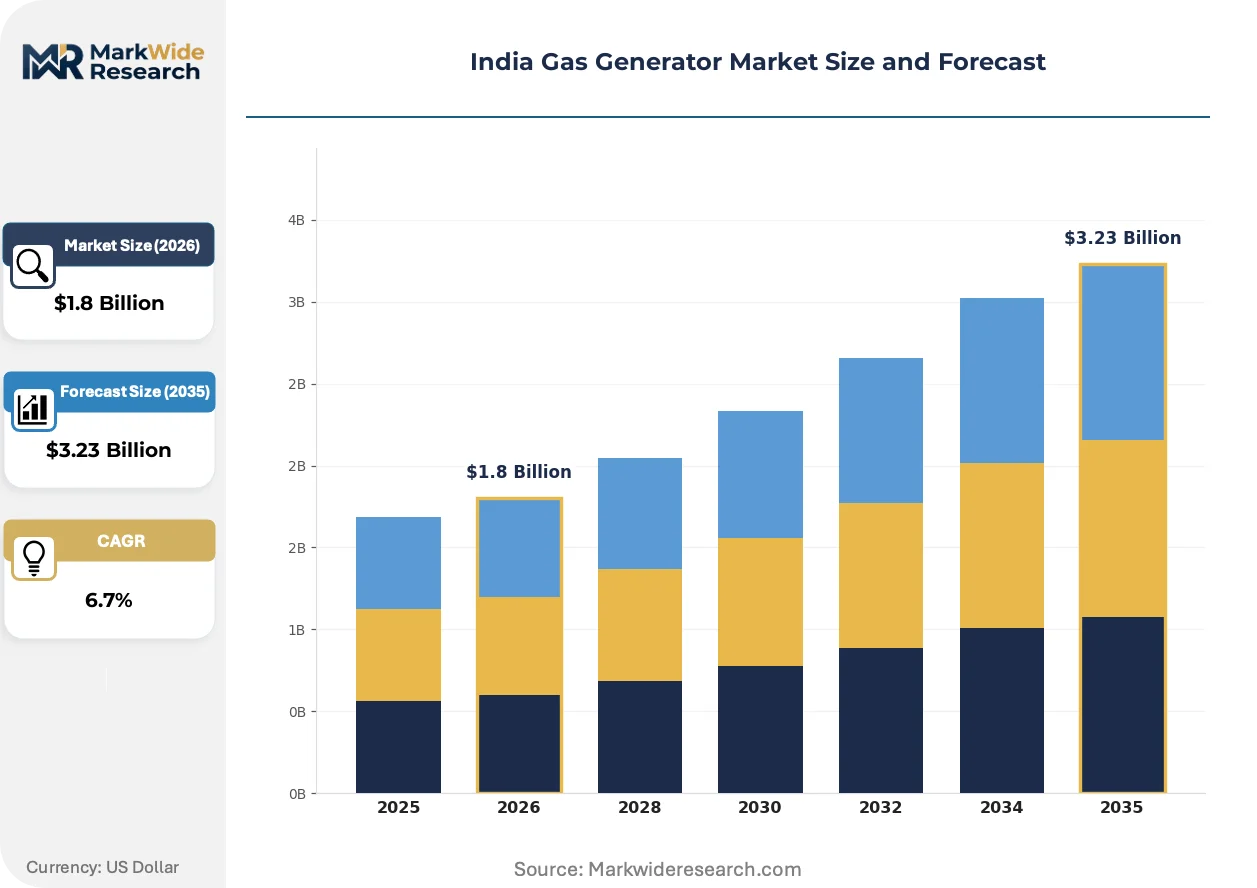
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Natural Gas, Biogas, Propane, Butane Power Output: Low Power, Medium Power, High Power, Ultra High Power End User: Residential, Commercial, Industrial, Agricultural Installation Type: Fixed, Portable, Mobile, Back-up |
| Companies Covered | Kirloskar Electric Company Limited, Cummins Inc, Caterpillar Inc, General Electric Company, Kohler Co, Mahindra Powerol Limited, Yanmar Co. Ltd, MTU Onsite Energy, AKSA Power Generation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gas Generator Market Shifts & Advancements
Digitization of asset performance monitoring and fuel flexibility engineering are compressing operating cost differentials between gas generator tiers while raising barriers for undifferentiated suppliers.
Lean-burn combustion architecture is supplanting stoichiometric designs in medium and high power segments. Data center operators in Hyderabad and Chennai specify these systems for their 10-15% fuel efficiency advantage during extended runtime scenarios. The technology is enabling smaller installed footprints per megawatt, reducing real estate costs in land-constrained urban clusters.
The Central Electricity Authority's amended Technical Standards for Connectivity mandate real-time emission reporting for captive plants above defined capacity thresholds. This regulatory friction is forcing industrial buyers toward OEMs with integrated telemetry and compliance documentation systems. Maharashtra and Gujarat manufacturing clusters face the steepest compliance ramps as state pollution control boards align with central protocols.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Large industrial buyers in Tamil Nadu and Karnataka now separate preventive maintenance, spare parts procurement, and remote monitoring into distinct vendor relationships. This behavioral shift is compressing margins for OEMs dependent on long-term service attach rates while creating openings for specialized diagnostics firms.
India Gas Generator Market Segmentation
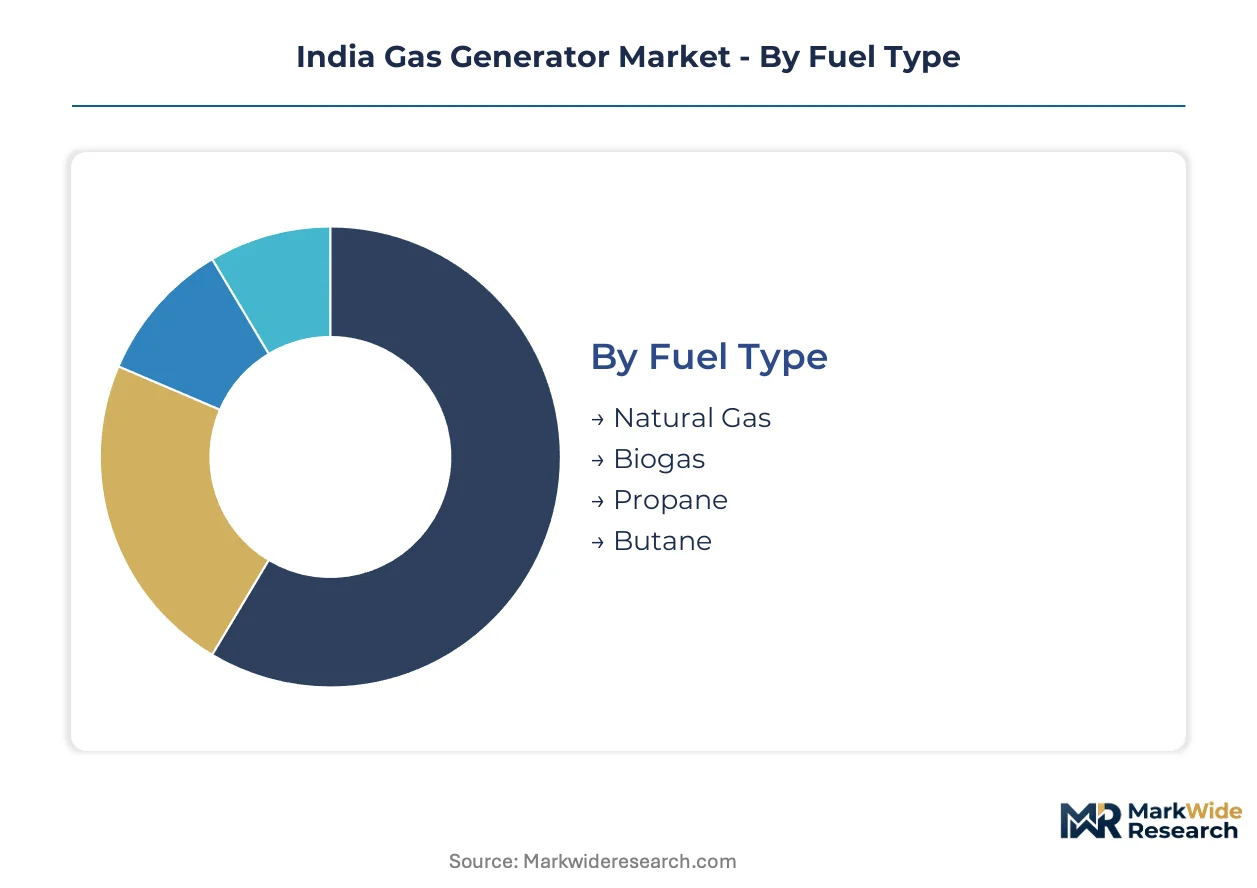
Segmentation in India's gas generator market reveals how fuel access, power density requirements, and installation constraints fragment procurement patterns across states. Buyers in Maharashtra and Gujarat face different economic trade-offs than those in biogas-rich Punjab or pipeline-starved eastern regions.
Fuel Type:
Natural gas dominates western and northern installations where the Hazira-Vijaipur-Jagdishpur pipeline network delivers grid-connected supply. Biogas and bottled alternatives concentrate in rural and distributed applications lacking pipeline infrastructure.
- Natural Gas:Pipeline-delivered methane powers continuous-duty installations in Mumbai and Ahmedabad manufacturing corridors. CEA emission monitoring protocols favor this fuel for captive plants above threshold capacities.
- Biogas:Agricultural digesters in Punjab and Haryana food processing clusters supply captive fuel for distributed generation. BIS certification requirements for gas quality create compliance barriers for unprocessed biogas.
- Propane:Bottled LPG serves backup installations in Tamil Nadu commercial hubs where pipeline gas remains unavailable.
- Butane:Blended with propane or used standalone in portable units for construction sites across Karnataka and Telangana.
Natural gas holds the largest share; momentum sits with biogas as agricultural waste-to-energy clusters expand digester capacity.
Power Output:
Cost tiers separate segments by capital intensity and runtime economics. Low and medium power units compete on acquisition price, while high and ultra high power categories justify premiums through fuel efficiency and reliability metrics.
- Low Power:Single-phase residential backup units below 15 kVA address outage protection in urban apartments. Maharashtra and Gujarat households drive volume through small commercial installations.
- Medium Power:Three-phase commercial systems between 15-100 kVA serve retail and office buildings. Hyderabad and Chennai IT parks specify these for redundancy during grid instability.
- High Power:Industrial captive plants above 100 kVA anchor manufacturing competitiveness in Tamil Nadu textile clusters. Lean-burn combustion architectures dominate this tier for fuel efficiency.
- Ultra High Power:Data center baseload installations above 1 MW require synchronous paralleling capability. Mumbai hyperscale facilities specify these for continuous runtime economics.
Medium power commands the broadest installed base; high power is climbing the fastest as industrial captive investments accelerate.
End User:
Customer type determines procurement sophistication and service contract structure. Industrial buyers unbundle maintenance and monitoring, while residential and agricultural segments favor bundled offerings.
- Residential:Apartment complexes and individual households prioritize acquisition cost over lifecycle efficiency. Tamil Nadu and Karnataka urban markets concentrate demand for silent canopy units.
- Commercial:Retail chains and hospitality groups standardize on medium power systems with remote monitoring. Mumbai and Delhi NCR operators drive specification for integrated telemetry.
- Industrial:Textile, pharmaceutical, and automotive manufacturers in Gujarat and Maharashtra deploy high-output captive plants. CEA grid interconnection compliance shapes vendor selection.
- Agricultural:Food processing cooperatives in Punjab and Haryana pair biogas digesters with low-to-medium power generators. BIS alternator standards under IS 4722 influence equipment sourcing.
Industrial users generate the highest revenue per installation; agricultural deployment is gaining share fastest as biogas infrastructure matures.
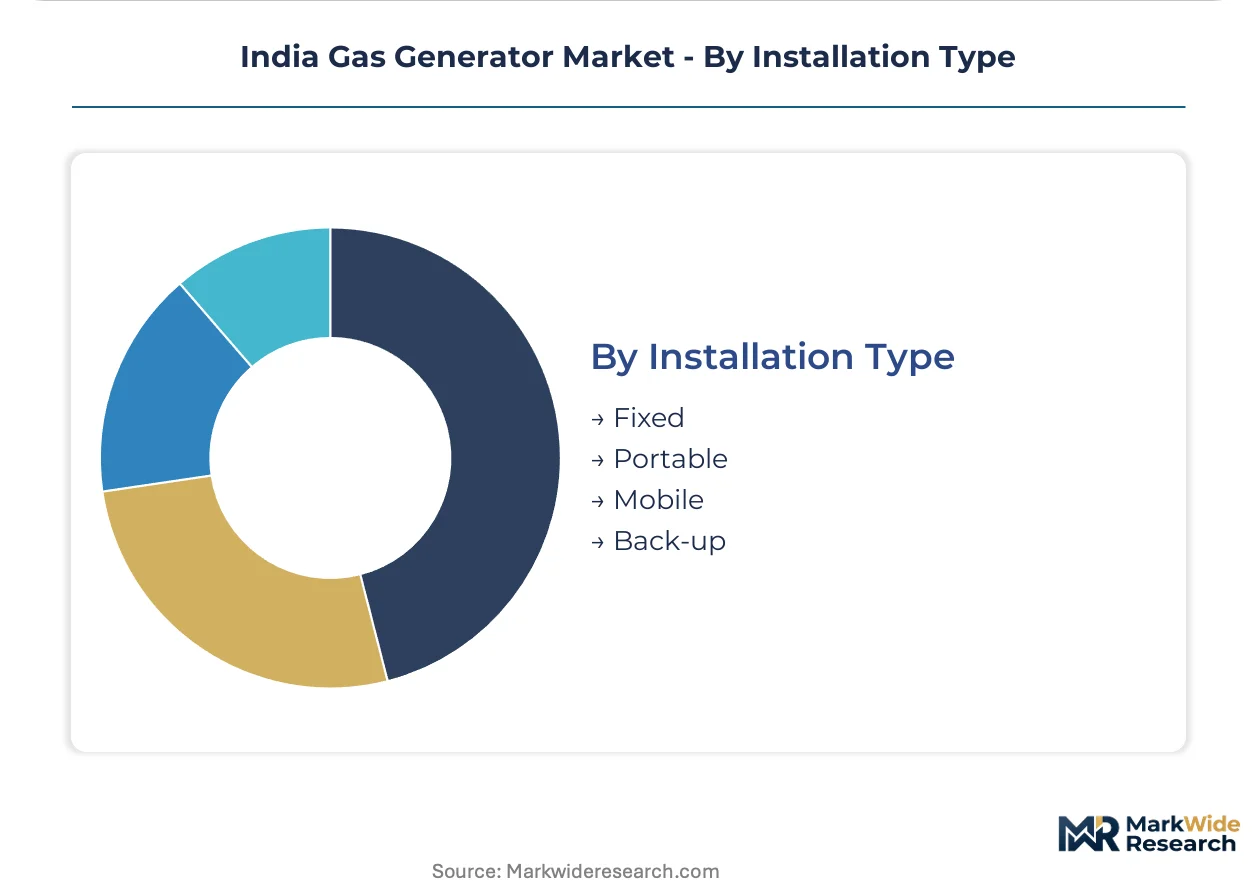
Installation Type:
Supply concentration favors fixed installations through domestic fabrication capacity, while mobile configurations depend on imported skid packages and faster depreciation accounting.
- Fixed:Permanent concrete-pad installations dominate industrial captive and data center applications. Maharashtra and Gujarat manufacturers prefer these for 15-20 year asset lifecycles.
- Portable:Wheeled units below 50 kVA serve construction sites and event rentals. Karnataka infrastructure projects drive rental fleet demand.
- Mobile:Trailer-mounted systems above 100 kVA address temporary power for mining and heavy industry. Telangana quarry operations specify these for rapid relocation.
- Back-up:Automatic transfer switch configurations prioritize start-time reliability for healthcare and financial services. Chennai and Hyderabad hospitals mandate sub-10-second response.
Fixed installation retains the dominant share; mobile configurations show the steepest expansion trajectory as rental markets professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across India varies sharply by pipeline proximity. Buyers in western states with Hazira-Vijaipur-Jagdishpur access prioritize fuel efficiency and runtime economics, while eastern and northeastern markets remain price-sensitive due to LNG trucking premiums.
Maharashtra
Mumbai's hyperscale data centers drive ultra high power gas generator procurement for redundant baseload capacity. The Central Electricity Authority mandates real-time emission reporting for captive plants above threshold capacities, tightening compliance requirements. Pune-Ahmednagar industrial corridors anchor manufacturing demand for continuous-duty installations.
Gujarat
Ahmedabad and Vadodara textile clusters deploy high-output captive plants to offset grid instability during peak manufacturing seasons. State electricity regulatory commission open access regulations influence economic calculus between gas-based generation and grid dependence. Mundra and Hazira port zones concentrate pipeline-delivered natural gas infrastructure for industrial buyers.
Tamil Nadu
Chennai IT parks specify medium power systems for redundancy during utility outages disrupting operations. The Bureau of Indian Standards enforces IS 4722 alternator performance benchmarks that create quality barriers for unestablished suppliers. Coimbatore textile and automotive manufacturing corridors drive high power segment growth.
Telangana
Hyderabad hyperscale facilities require synchronous paralleling capability for continuous runtime economics in data center applications. State pollution control boards align with central CEA protocols for captive plant emission monitoring. Secunderabad industrial zones concentrate procurement for lean-burn combustion architectures.
Punjab and Haryana
Food processing cooperatives pair biogas digesters with low-to-medium power generators for waste-to-energy compliance. BIS certification requirements for gas quality create barriers for unprocessed agricultural methane. Ludhiana and Ambala agricultural clusters expand digester capacity to supply captive fuel for distributed generation assets.
India Gas Generator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's gas generator sector. Multinational OEMs with captive engine manufacturing sustain price competitiveness through backward integration into powertrain components. Domestic assemblers anchor positions through channel density and aftermarket service networks. Two strategic archetypes dominate: technology leaders competing on fuel efficiency and emissions compliance, and service-intensive players competing on response time and spare parts availability. Competitive moves concentrate on localization partnerships under production-linked incentive schemes and unbundled service contract structures that fragment traditional bundled maintenance models.
Among the named participants, Kirloskar Electric Company Limited exemplifies the domestic service-intensive archetype through its Maharashtra industrial corridor penetration. Cummins Inc occupies a position representing integrated multinational manufacturing with engine-generator vertical control. Caterpillar Inc sits within the technology leadership tier for ultra high power critical infrastructure applications. These three anchors illustrate the competitive tension between localization depth and technology transfer in a market tightening emission and grid interconnection standards.
| Leading Market Players |
|---|
| Kirloskar Electric Company Limited |
| Cummins Inc |
| Caterpillar Inc |
| General Electric Company |
| Kohler Co |
| Mahindra Powerol Limited |
| Yanmar Co. Ltd |
| MTU Onsite Energy |
| AKSA Power Generation |
| Others |
Supply & Pricing Matrix
Spark plug and catalyst substitution toward domestic sourcing is redrawing procurement geography across India's gas generator sector while compressing margin structures for assemblers exposed to yen-euro currency volatility. This input transition simultaneously elevates working capital requirements for inventory buffers and intensifies price competition among OEMs with captive component testing infrastructure.
Pricing Analysis
Aftermarket service contracts and spare parts procurement now generate lifetime value exceeding original equipment margins for established OEMs. Pricing stratifies across premium certified tiers anchored by BIS IS 4722 compliance, standard offerings from domestic assemblers, and economy units targeting price-sensitive residential buyers in Tamil Nadu apartment complexes. Cost compression in the economy tier is intensifying as unbranded suppliers from eastern states exploit component arbitrage. Industrial captive buyers in Maharashtra and Gujarat demonstrate lowest price sensitivity, prioritizing emission compliance documentation and synchronous paralleling reliability over acquisition cost.
Supply Chain Analysis
Container availability constraints on the Hamburg-Mumbai and Yokohama-Chennai trade lanes are extending lead times for precision ignition components and exhaust after-treatment systems. Manufacturing concentration rests on Germany and Japan for spark plugs, catalyst substrates, and turbocharger assemblies, while domestic fabrication supplies alternator housings and cooling systems from Maharashtra and Gujarat machine shops. Single-source vulnerability concentrates in membrane-based biogas upgrading equipment sourced from European specialists. Distribution runs through authorized dealer networks in industrial corridors, with direct OEM relationships dominating data center and captive power procurement above 1 MW capacity thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with unbundled service contracts separating preventive maintenance, remote monitoring, and spare parts procurement into distinct vendor relationships. This demand-side shift creates specialist niches for diagnostics firms and regional service integrators outside traditional OEM channel structures.
For Market Incumbents: Fortify aftermarket service density through channel control investments in Maharashtra and Gujarat industrial corridors. Deepen backward integration into alternator winding and engine block machining to offset margin pressure from currency-exposed imported components. Prioritize BIS certification infrastructure as quality barriers under IS 4722 specifications favor established testing capabilities against emerging unbranded competitors. For New Entrants and Emerging Players: Remote monitoring and predictive diagnostics capabilities represent the most penetrable service-layer gap where incumbents under-serve agricultural biogas clusters in Punjab and Haryana. Target low-to-medium power biogas generator deployments with bundled fuel purification and maintenance packages. Pursue digester-to-generator integration partnerships with food processing cooperatives as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic assemblers holding Maharashtra channel positions but lacking technology transfer partnerships for lean-burn combustion architectures. Five-to-ten year viability hinges on localization compliance under production-linked incentive schemes and carbon pricing trajectory clarity. Monitor state electricity regulatory commission rulings on renewable purchase obligations as the critical inflection signal for gas-based captive power economics.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership Under PLI Scheme | Domestic value-addition requirements for engine components anchor multinational OEM manufacturing commitments in Gujarat. |
| Biogas Purification Technology Licensing | Membrane and pressure-swing adsorption systems unlock rural deployment without Hazira-Vijaipur-Jagdishpur pipeline access. |
| Containerized Mobile Unit Fleet Expansion | Skid-mounted packages accelerate capital recovery through depreciation advantages in Karnataka infrastructure rental markets. |
| Integrated Telemetry and Compliance Documentation | Real-time emission reporting capabilities align with CEA amended Technical Standards for Connectivity mandates. |
| Lean-Burn Combustion Architecture Investment | Fuel efficiency advantages of 10-15 percent justify premiums from Hyderabad and Chennai data center operators. |
Research Methodology
A spread of perspectives from plant engineers at textile and pharmaceutical manufacturers, aftermarket service heads at domestic OEMs, procurement leads at Mumbai hyperscale data centers, and regulatory affairs specialists at the Central Electricity Authority converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through BIS certification records, CEA technical standards filings, state electricity regulatory commission open access orders, and customs data on engine component imports. Bottom-up unit economics from individual installation specifications were triangulated against top-down demand projections from manufacturing capacity expansion announcements.
Segmentation dimensions modeled span fuel type, power output tier, end-user category, and installation configuration across the projection horizon. Analytical frameworks incorporated pipeline access density, grid reliability indices, and emission compliance cost curves. CAGRs were derived from regression analysis of historical captive power investments against manufacturing output and data center capacity additions. Industry-specific forecast inputs included biogas digester capacity buildout in Punjab and Haryana food processing zones and state-level renewable purchase obligation enforcement trajectories.
Material uncertainties — regulatory shifts in carbon pricing mechanisms, LNG trucking cost volatility for pipeline-starved eastern states, and currency fluctuation impacts on imported precision components — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding grid reliability deterioration rates and manufacturing cluster expansion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
India Gensets Market
Power Generation
South America Thermal Power Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Australia Thermal Power Market
Power Generation
Coal Fired Power Generation Market
Power Generation
South East Asia Power Market
Power Generation
Power Plant EPC Market
Power Generation
Global Power Generation Market
Power Generation
Oman Power Market
Power Generation
Hydrogenerators Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Distributed Power Generation Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Global Black Start Generator Market
Power Generation
Malaysia Power Generation EPC Market