
 Malaysia Oil and Gas Midstream Market | 2026-2036
Malaysia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Oil and Gas Midstream Market Foresight
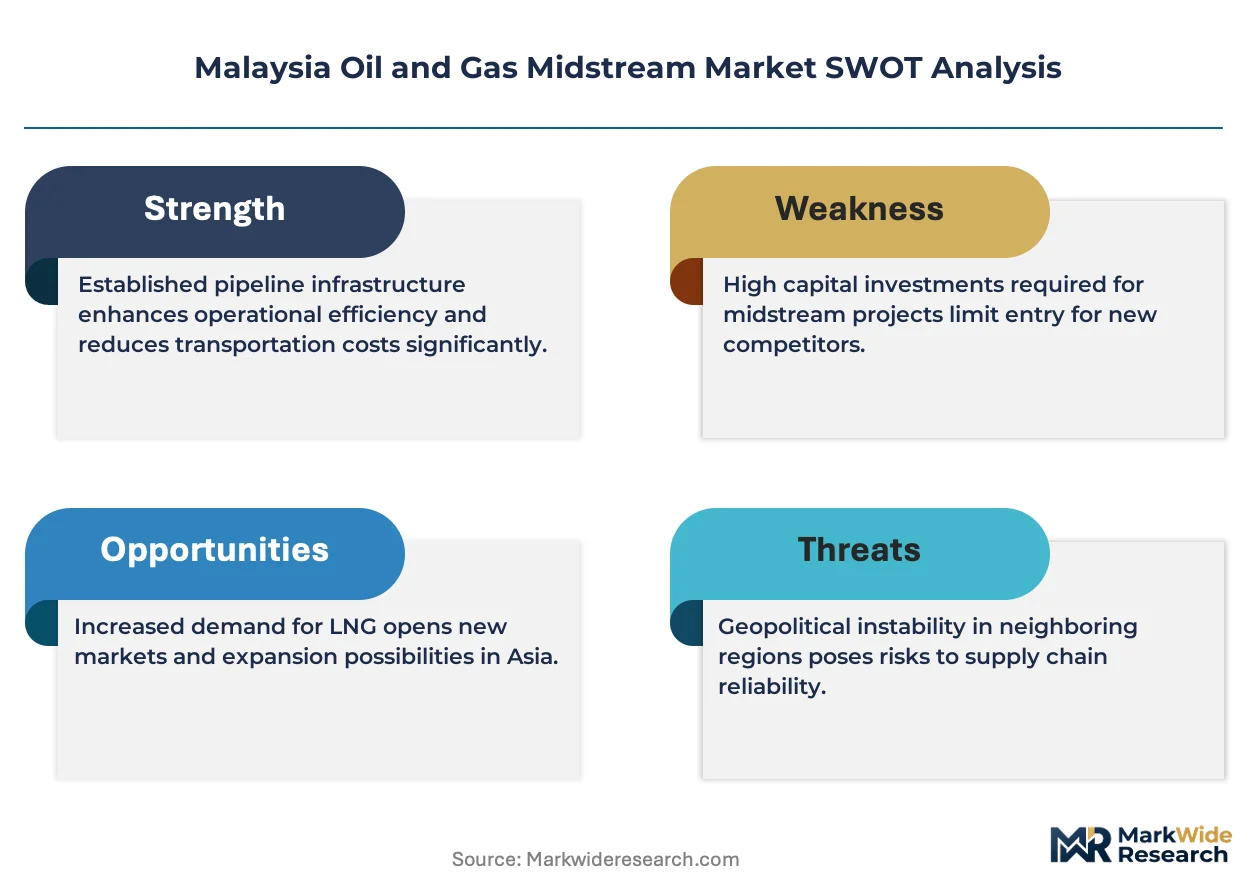
Project finance tied to long-term throughput agreements is narrowing the field of viable competitors in Malaysian midstream development. Petroliam Nasional Berhad (PETRONAS) leverages its integrated upstream-downstream position to anchor capital-intensive LNG terminal builds. Dialog Group Berhad sustains its competitive edge through specialized oil storage terminals at Tanjung Langsat and Pengerang. MISC Berhad dominates floating storage and offshore logistics, extending its reach across Malaysian waters.
Malaysia oil and gas midstream encompasses the transportation, storage, processing, and distribution of crude oil, natural gas, and refined products between extraction points and downstream facilities, typically involving pipeline networks exceeding 3,000 kilometers, cryogenic LNG storage at minus 162 degrees Celsius, and fractionation units separating raw gas into methane, ethane, and heavier hydrocarbons. Its primary purpose is to bridge temporal and spatial gaps between production volatility and steady refinery or export demand. Pipeline infrastructure by diameter classification shows large-diameter trunk lines carrying the bulk of Peninsular Malaysia's gas transmission burden, while small-diameter gathering systems at mature offshore fields face replacement cycles. LNG terminal technology leads capital deployment, with floating storage regasification units gaining preference over onshore greenfield builds due to land scarcity and faster permitting.
The Energy Commission enforces pipeline safety standards under the Gas Supply Act, while the Department of Environment mandates environmental impact assessments for coastal storage expansions, collectively raising compliance costs for new market entrants. PETRONAS licensing requirements for third-party access to transmission networks further shape competitive dynamics by specifying technical and financial qualification thresholds. Stakeholders must weigh stranded asset risk against the regulatory push for cleaner fuel infrastructure as Malaysia advances its national energy transition roadmap.
Market Dynamics
Pipeline integrity mandates from Malaysia's Energy Commission are compressing replacement cycles for aging offshore gathering systems while accelerating capital flows toward cryogenic LNG infrastructure.
Growth Catalysts
- Pengerang Complex Expansion:Petrochemical feedstock intake growth along Peninsular Malaysia's western coast is driving demand for specialized oil storage terminals and fractionation capacity additions.
- Gas Supply Act Enforcement:Stricter pipeline safety standards under Malaysian energy regulation are mandating integrity management systems that modernize transmission networks and create equipment upgrade cycles.
- Floating Storage Regasification:Land scarcity at coastal sites is accelerating preference for FSRU technology over onshore greenfield LNG terminal builds, compressing project timelines.
Market Restraints
- Specialized Fabrication Bottlenecks:Cryogenic storage tank construction for minus 162 degrees Celsius operations concentrates among a limited supplier base, extending delivery timelines.
- Third-Party Access Barriers:PETRONAS licensing requirements specify technical and financial qualification thresholds that restrict independent midstream developers from accessing transmission networks.
- Steel Input Volatility:Large-diameter trunk line projects face cost pressure from fluctuating high-grade steel plate prices, compressing project returns on pipeline replacements.
Strategic Opportunities
- Bintulu LNG Hub Modernization:Processing capacity expansitions at Sarawak's established export terminal create openings for offshore logistics and floating storage service providers.
- Energy Transition Infrastructure:Malaysia's national energy transition roadmap is redirecting midstream investment toward cleaner fuel handling systems and carbon capture integration.
- Tanjung Langsat Storage Growth:Dialog Group's established terminal complex demonstrates scalable model for independent oil storage development along Johor's southeastern coast.
Industry Challenges
- Cryogenic Welding Expertise Gap:FSRU and LNG terminal construction requires certified welders qualified for nickel-alloy work at extreme low temperatures, constraining project staffing.
- Legacy Pipeline Integration:New digital monitoring systems must interface with decades-old offshore gathering infrastructure, complicating integrity management deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Oil and Gas Midstream Market |
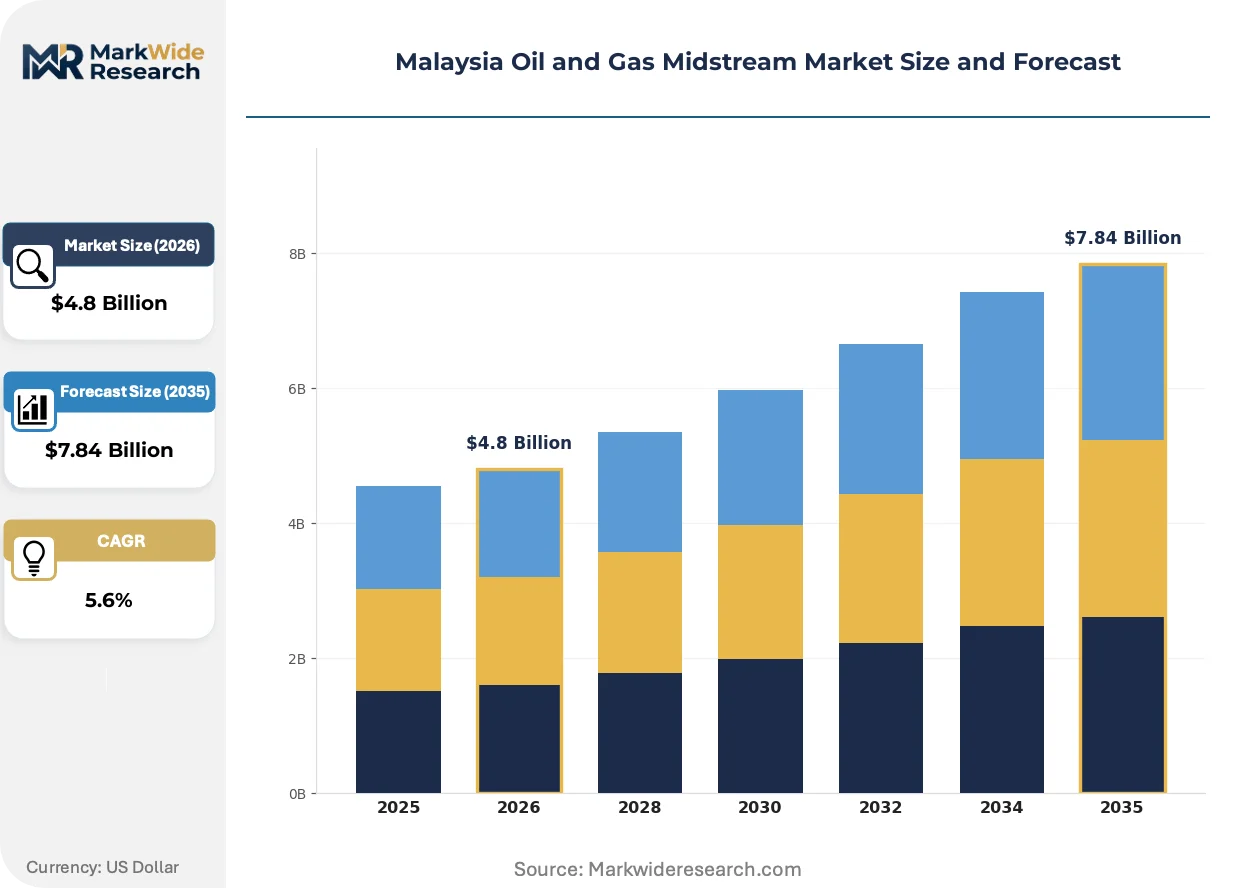
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Distribution Technology: Pipelines, LNG Terminals, Processing Plants, Pumping Stations End User: Refineries, Power Plants, Petrochemical Companies, Industrial Users Pipeline Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra-Large Diameter |
| Companies Covered | Petroliam Nasional Berhad (PETRONAS), Petronas Gas Berhad, Dialog Group Berhad, Gas Malaysia Berhad, MISC Berhad, Royal Vopak N.V., Fluor Corporation, Vitol Group, TechnipFMC plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Oil and Gas Midstream Market Shifts & Advancements
Digital twin technology and remote monitoring systems are virtualizing asset management across Malaysian midstream infrastructure, compressing inspection cycles while extending operational visibility offshore.
Digital twin platforms are replicating physical pipeline and terminal assets in real-time simulation environments. PETRONAS and Dialog Group are deploying these systems across Pengerang and Tanjung Langsat facilities to predict equipment degradation before failure. This capability is virtualizing maintenance scheduling, shifting from calendar-based interventions to condition-driven protocols that reduce unplanned downtime.
Malaysia's Department of Environment is tightening environmental impact assessment requirements for coastal storage expansions. The mandate is extending project approval timelines and raising documentation burdens for new terminal builds. Developers are responding by front-loading ecological baseline studies and engaging third-party certifiers earlier in planning cycles.
Long-term throughput agreements are displacing spot-market contracting as the dominant project finance structure. Independent storage operators at Bintulu and Pengerang are locking in 15-20 year offtake commitments with petrochemical buyers to secure construction debt. This shift is concentrating counterparty risk among a narrower buyer pool and favoring integrated players with captive upstream supply.
Malaysia Oil and Gas Midstream Market Segmentation
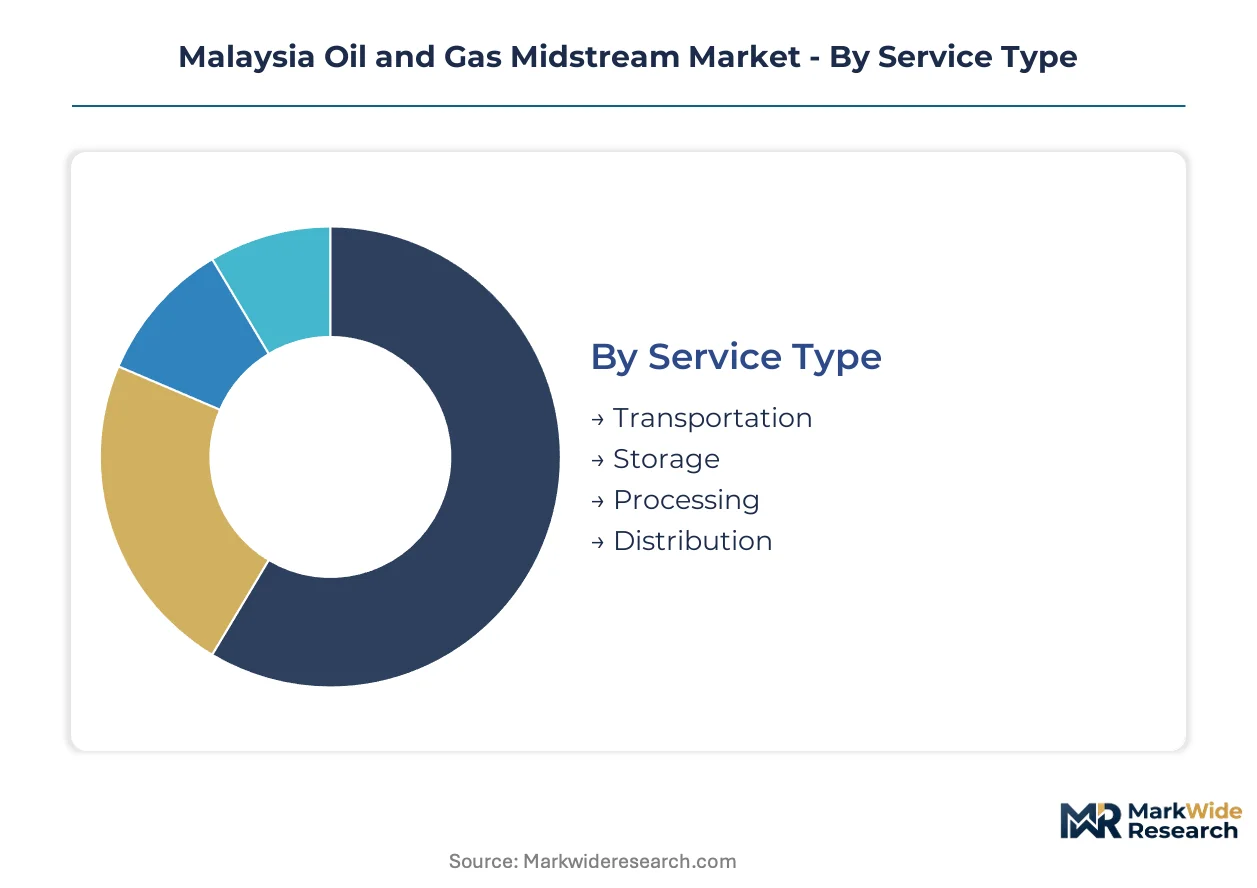
Malaysia's midstream infrastructure serves distinct operational profiles across service layers, technology platforms, and customer segments. Each dimension shapes capital deployment patterns and regulatory exposure differently across Peninsular Malaysia and East Malaysian developments.
Service Type:
Mature trunk transportation networks contrast with emerging processing capacity expansions across Malaysian midstream operations.
- Transportation:Pipeline networks exceeding 3,000 kilometers carry crude oil and natural gas between offshore production platforms and onshore facilities. PETRONAS-operated trunk lines across Peninsular Malaysia face integrity replacement cycles mandated by the Energy Commission's Gas Supply Act enforcement.
- Storage:Cryogenic LNG storage at minus 162 degrees Celsius and conventional oil terminals at Tanjung Langsat and Pengerang handle feedstock staging for petrochemical complexes. Land scarcity at coastal sites is accelerating floating storage regasification unit preference over greenfield builds.
- Processing:Fractionation units separate raw gas into methane, ethane, and heavier hydrocarbons for downstream chemical manufacturing.
- Distribution:Final-mile delivery networks connect transmission hubs to industrial off-takers across Johor and Sarawak.
Transportation retains volume leadership; processing holds the steepest expansion curve.
Technology:
Cost tiers separate legacy pipeline infrastructure from capital-intensive LNG terminal developments requiring specialized fabrication capabilities.
- Pipelines:Large-diameter trunk lines bear the bulk of Peninsular Malaysia's gas transmission burden, while small-diameter gathering systems at mature offshore fields require replacement. Steel input volatility pressures project returns on new trunk line construction.
- LNG Terminals:Floating storage regasification units compress permitting timelines versus onshore alternatives, though cryogenic welding expertise gaps constrain project staffing. Bintulu LNG hub modernization drives demand for terminal technology upgrades.
- Processing Plants:Gas treatment and fractionation facilities at Pengerang Integrated Complex handle expanding petrochemical feedstock requirements.
- Pumping Stations:Compression infrastructure maintains flow rates across Malaysia's extended pipeline geography.
Pipelines retain volume leadership; LNG terminals hold the steepest expansion curve.
End User:
Customer type determines contract duration and counterparty risk concentration across Malaysian midstream offtake agreements.
- Refineries:Downstream processing facilities require steady crude supply through dedicated pipeline connections and terminal access.
- Power Plants:Gas-fired generation assets depend on transmission network reliability for fuel security under Malaysia's energy transition roadmap.
- Petrochemical Companies:Feedstock intake growth along Peninsular Malaysia's western coast concentrates demand at Pengerang and Bintulu complexes, with operators locking 15-20 year throughput commitments to secure project finance.
- Industrial Users:Manufacturing and chemical processors access distribution networks for process energy and feedstock requirements.
Petrochemical companies retain volume leadership; power plants hold the steepest expansion curve.
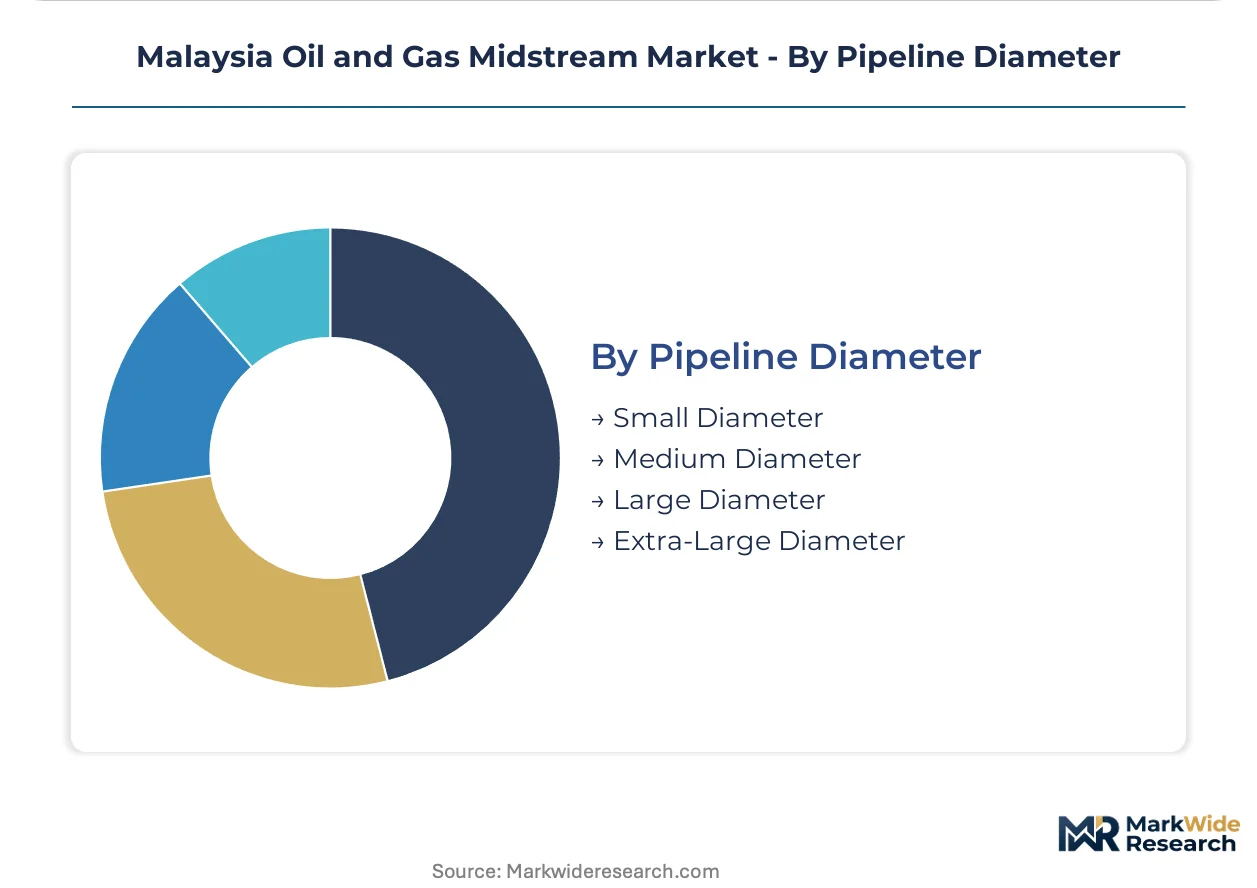
Pipeline Diameter:
Supply concentration favors large-diameter fabrication yards with limited global capacity for high-grade steel plate processing.
- Small Diameter:Gathering systems at mature offshore fields face compressed replacement cycles under pipeline integrity mandates.
- Medium Diameter:Branch lines distribute gas to regional industrial clusters across Peninsular Malaysia.
- Large Diameter:Trunk transmission infrastructure carries the majority of Malaysia's domestic gas movement, with diameter classification determining pressure ratings and throughput capacity.
- Extra-Large Diameter:Specialized high-capacity lines serve export corridors and major hub connections requiring maximum volume efficiency.
Large diameter retains volume leadership; extra-large diameter holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's national energy transition roadmap channels midstream investment toward cleaner fuel handling systems while pipeline integrity mandates from the Energy Commission modernize aging transmission networks. State-level development clusters concentrate capital deployment across Peninsular Malaysia and East Malaysian gas hubs.
Johor
Pengerang Integrated Complex drives specialized oil storage terminal demand and fractionation capacity additions for petrochemical feedstock intake. The Department of Environment mandates environmental impact assessments for coastal storage expansions, extending approval timelines. Tanjung Langsat hosts Dialog Group's scalable independent terminal model demonstrating storage growth potential.
Sarawak
Bintulu LNG hub modernization creates openings for offshore logistics and floating storage service providers as processing capacity expands. The Gas Supply Act enforcement shapes safety standards for regional pipeline networks. Bintulu's established export terminal concentrates LNG terminal technology deployment and cryogenic infrastructure investment.
Selangor
Gas-fired power generation assets depend on trunk line transmission reliability for fuel security under energy transition targets. The Energy Commission's pipeline safety standards mandate integrity management systems across Peninsular Malaysia's distribution networks. Klang Valley industrial corridors connect to medium-diameter branch lines serving regional manufacturing clusters.
Terengganu
Offshore production platforms supply mature gathering systems requiring replacement cycles under integrity mandates. PETRONAS licensing requirements for third-party access shape competitive dynamics for independent developers seeking transmission network entry. Kemaman supply base supports offshore logistics and maintenance operations for regional production assets.
Malaysia Oil and Gas Midstream Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's midstream infrastructure development. PETRONAS anchors capital-intensive LNG terminal builds through integrated upstream-downstream positioning, while independent storage operators secure project finance via long-term throughput agreements. Three archetypes dominate: national oil companies with captive supply chains, specialized terminal developers with scalable coastal assets, and offshore logistics providers with floating storage capabilities. Capacity expansion and strategic partnerships constitute the primary competitive moves as developers lock in 15-20 year offtake commitments.
Within the national oil company tier, Petroliam Nasional Berhad exemplifies channel control through integrated infrastructure positioning. Dialog Group Berhad and MISC Berhad occupy specialist positions—Dialog Group through coastal terminal development and MISC Berhad through offshore floating storage and logistics services. These three companies represent the dominant competitive archetypes shaping Malaysia's midstream investment patterns.
| Leading Market Players |
|---|
| Petroliam Nasional Berhad (PETRONAS) |
| Petronas Gas Berhad |
| Dialog Group Berhad |
| Gas Malaysia Berhad |
| MISC Berhad |
| Royal Vopak N.V. |
| Fluor Corporation |
| Vitol Group |
| TechnipFMC plc |
| Others |
Supply & Pricing Matrix
The Malacca Strait freight corridor connects Middle Eastern crude suppliers to Pengerang and Bintulu terminals, with voyage cost volatility compressing margins for independent storage operators while enabling PETRONAS to extract premium pricing through captive supply integration.
Pricing Analysis
Certification level under the Energy Commission's Gas Supply Act creates the primary spread between qualified and non-qualified pipeline operators. Long-term offtake agreements dominate project finance, with 15-20 year contracts locking in price floors for petrochemical buyers while spot-market exposure concentrates among floating storage providers. Cost compression in cryogenic fabrication is intensifying because nickel-alloy steel plate availability constrains FSRU construction timelines. Petrochemical companies demonstrate lowest price sensitivity due to feedstock security requirements, while industrial gas users exhibit highest sensitivity to transmission tariff fluctuations.
Supply Chain Analysis
Upstream high-grade steel plate feeds from South Korea, Japan, and China, with specialized cryogenic tank fabrication concentrating among yards in Singapore and South Korea. Nickel-alloy welding consumables, cryogenic insulation systems, and subsea pipeline coatings constitute critical input dependencies. Single-source vulnerability runs through the limited global base of certified cryogenic welders qualified for minus 162 degrees Celsius operations. Distribution runs through PETRONAS-controlled trunk networks, with third-party access licensing restricting independent terminal connections to coastal storage hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Malaysia's energy transition roadmap bifurcates demand between legacy hydrocarbon infrastructure and cleaner fuel handling systems, creating specialized niches for equipment retrofit and carbon capture integration.
For Market Incumbents: Build regulatory moats through early certification under tightening Department of Environment coastal storage standards. Anchor capital deployment in Pengerang and Bintulu capacity additions to preempt emerging terminal developers. Defensive consolidation should target independent storage operators at Tanjung Langsat before Dialog Group scales replication models. Vertical integration into cryogenic welding training programs addresses staffing bottlenecks constraining competitor project timelines.
For New Entrants and Emerging Players: Pursue FSRU logistics services at Bintulu LNG hub where MISC Berhad's dominance leaves gaps in offshore maintenance and floating storage operations. Target medium-diameter branch line integrity management contracts across Peninsular Malaysia's aging gathering systems, where PETRONAS licensing barriers are lowest for specialized service providers. Go-to-market positioning should emphasize digital twin deployment capabilities that reduce unplanned downtime for legacy pipeline assets.
For Investors and Strategic Acquirers: Specialist cryogenic fabrication shops with Energy Commission qualification pathways represent the most defensible acquisition profile. Long-term viability hinges on exposure to Malaysia's national energy transition roadmap execution rather than pure hydrocarbon volume growth. Watch for inflection signals in carbon capture integration mandates at Pengerang and Bintulu complexes, which would redirect midstream capital allocation toward cleaner fuel handling infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Capacity Buildout | Compresses permitting timelines at land-scarce coastal sites like Pengerang under Department of Environment assessments. |
| Backward Integration into Cryogenic Fabrication | Secures nickel-alloy welding capacity and reduces exposure to South Korean and Singaporean yard bottlenecks. |
| Long-term Throughput Agreement | Locks 15-20 year petrochemical offtake commitments to secure project finance for independent terminal developments. |
| Digital Twin Platform Deployment | Virtualizes maintenance scheduling across PETRONAS and Dialog Group facilities to shift from calendar-based to condition-driven protocols. |
| Carbon Capture Integration Partnership | Aligns with Malaysia's energy transition roadmap to redirect midstream investment toward cleaner fuel handling systems. |
Research Methodology
Operator-level perspectives from pipeline integrity managers, LNG terminal project developers, cryogenic fabrication yard supervisors, Energy Commission regulatory officers, and petrochemical procurement directors anchored the qualitative base. Secondary validation drew from Gas Supply Act enforcement records, Department of Environment environmental impact assessment filings, PETRONAS third-party access licensing databases, and regional trade data on high-grade steel plate imports. Bottom-up capacity assessments at Pengerang, Bintulu, and Tanjung Langsat facilities were triangulated against top-down energy transition roadmap expenditure projections.
Scenario-bracketing framed the analytical approach, with demand trajectories tested against varying paces of national energy transition roadmap implementation across the projection horizon. Segmentation dimensions modeled encompassed service type, technology platform, end-user category, and pipeline diameter classification. CAGRs were derived through regression analysis of historical throughput volumes against announced capacity expansion timelines, with cryogenic storage utilization rates and trunk line replacement cycles serving as key industry-specific forecast inputs.
Sensitivities concentrate around Energy Commission pipeline integrity mandate enforcement intensity and Department of Environment approval timeline extensions for coastal storage expansions. Forecasts embed assumptions regarding PETRONAS licensing threshold stability and nickel-alloy steel plate supply availability. Cross-checking against IEA Southeast Asia energy investment benchmarks and regional LNG terminal development databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Planned LNG Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Middle East and Africa Coiled Tubing Market