
 Indonesia Power Generation EPC Market | 2026-2036
Indonesia Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Power Generation EPC Market Foresight
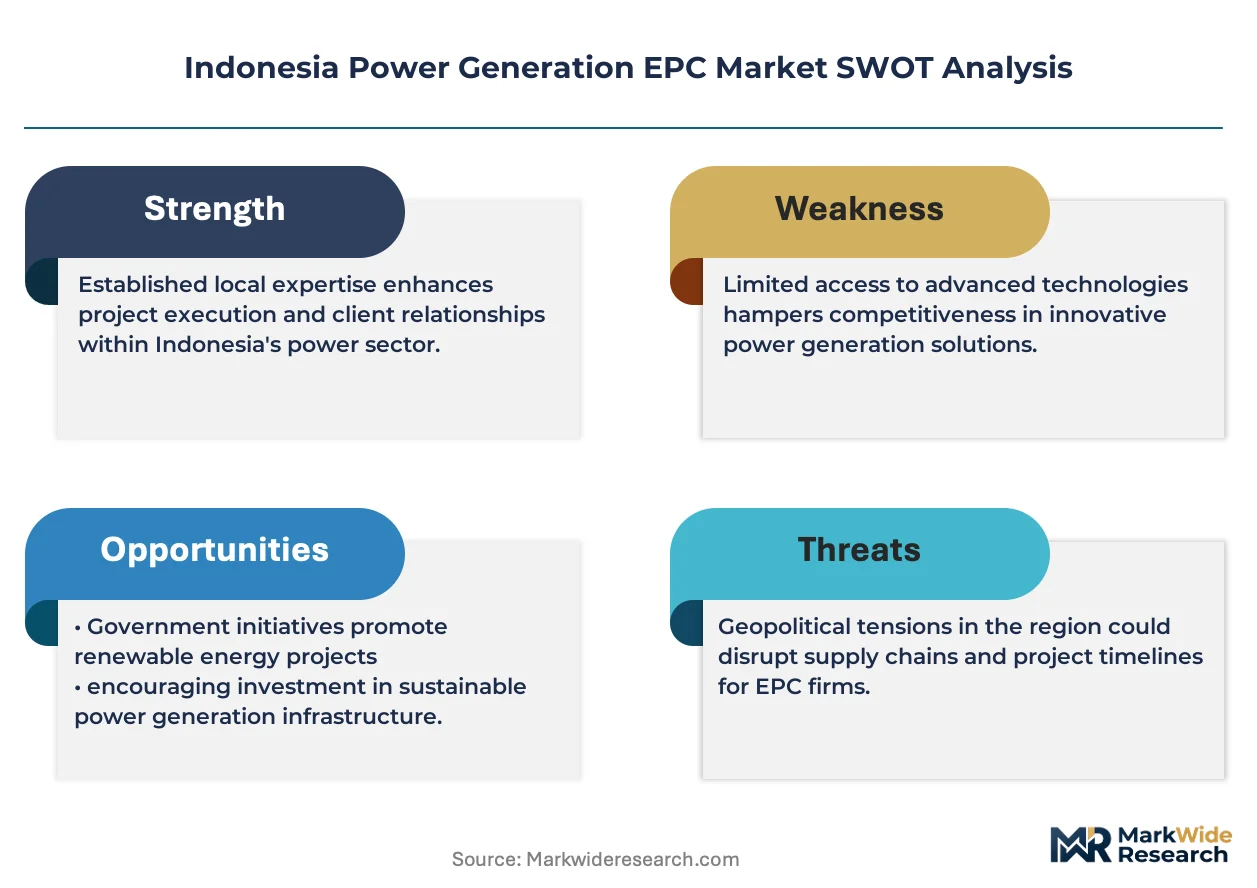
ISO 9001 certification is unwinding as a baseline gate for EPC qualification in Indonesia's power sector, forcing contractors to demonstrate quality management systems before tender participation. PT Wijaya Karya (Persero) Tbk anchors its position through integrated civil-structural capabilities across archipelago logistics. Hyundai Engineering Co. Ltd. leverages Korean financing ties to secure combined-cycle gas turbine projects. PT Pembangunan Perumahan (Persero) Tbk competes on government-backed project pipelines in remote island electrification.
Indonesia Power Generation EPC encompasses the integrated design, equipment sourcing, and turnkey construction of electricity generation facilities spanning thermal, renewable, and hybrid configurations, typically executed under lump-sum contracts with performance guarantees on output capacity and heat rate. Engineering services command premium margins due to front-loaded technical risk and proprietary turbine alignment protocols, while procurement functions absorb volatile commodity exposure through long-lead equipment scheduling. Solar installation segments accelerate fastest off low base penetration, though gas turbine construction sustains dominant value share underpinned by PLN's 35 GW program legacy and grid stability requirements.
MEMR local content regulations and BIS-equivalent equipment standards shape contractor sourcing obligations, mandating progressively higher domestic component ratios across project phases. PLN's procurement guidelines and the central bank's project finance prudential rules constrain foreign currency exposure and steer capital toward rupiah-denominated structures. Stakeholders must monitor regulatory recalibration of renewable energy tariffs against fossil fuel baseload economics to anticipate contract award velocity shifts.
Market Dynamics
PLN's 35 GW procurement program and MEMR's escalating local content mandates are restructuring contractor qualification hierarchies across Indonesia's power generation EPC landscape. Engineering firms must now front-load domestic partnership structures to meet progressively stringent domestic component ratios before tender submission.
Growth Catalysts
- Java-Bali Grid Interconnection:The archipelago's densest load centers drive concentrated investment in combined-cycle gas turbine capacity to stabilize frequency across the 500 kV backbone transmission network.
- MEMR Local Content Regulations:Tiered domestic sourcing mandates create protected market access for contractors with established Indonesian fabrication partnerships and certified local workforce development programs.
- Remote Island Electrification:Diesel-to-hybrid conversion programs in Eastern Indonesia generate distributed EPC demand for solar-diesel-battery integrated systems outside the main grid footprint.
Market Restraints
- Rupiah Currency Exposure:Bank Indonesia's prudential rules on foreign currency project finance constrain dollar-denominated equipment procurement for imported gas turbines and specialized control systems.
- Specialized Welding Certification Scarcity:ASME Section IX and BIS-equivalent pressure vessel qualifications face acute supply constraints across Indonesian technical institutes, extending project mobilization timelines.
- Long-Lead Equipment Scheduling:Steam turbine and generator manufacturing concentration in Northeast Asian supply bases creates vulnerability to maritime logistics bottlenecks through the Singapore Strait chokepoint.
Strategic Opportunities
- Sumatra-Bangka-Belitung Transmission Bridge:The 1,500 km submarine cable corridor requires offshore platform-based substation EPC capabilities currently underrepresented in domestic contractor portfolios.
- Green Hydrogen Co-Firing Pilots:MEMR's ammonia-hydrogen blending roadmaps for existing coal plants create retrofit EPC demand for combustion system modification and fuel handling infrastructure.
- Industrial Captive Power Liberalization:Revised electricity supply regulations permit direct power purchase agreements between renewable developers and smelter operators, bypassing PLN offtake intermediation.
Industry Challenges
- Geotechnical Survey Capacity:Volcanic soil characterization and seismic hazard assessment expertise concentrates in Bandung and Yogyakarta academic institutes, creating field mobilization bottlenecks for archipelago project execution.
- ISO 9001 Certification Backlogs:International accreditation body audit scheduling delays extend contractor pre-qualification timelines by six to nine months, freezing tender participation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Power Generation EPC Market |
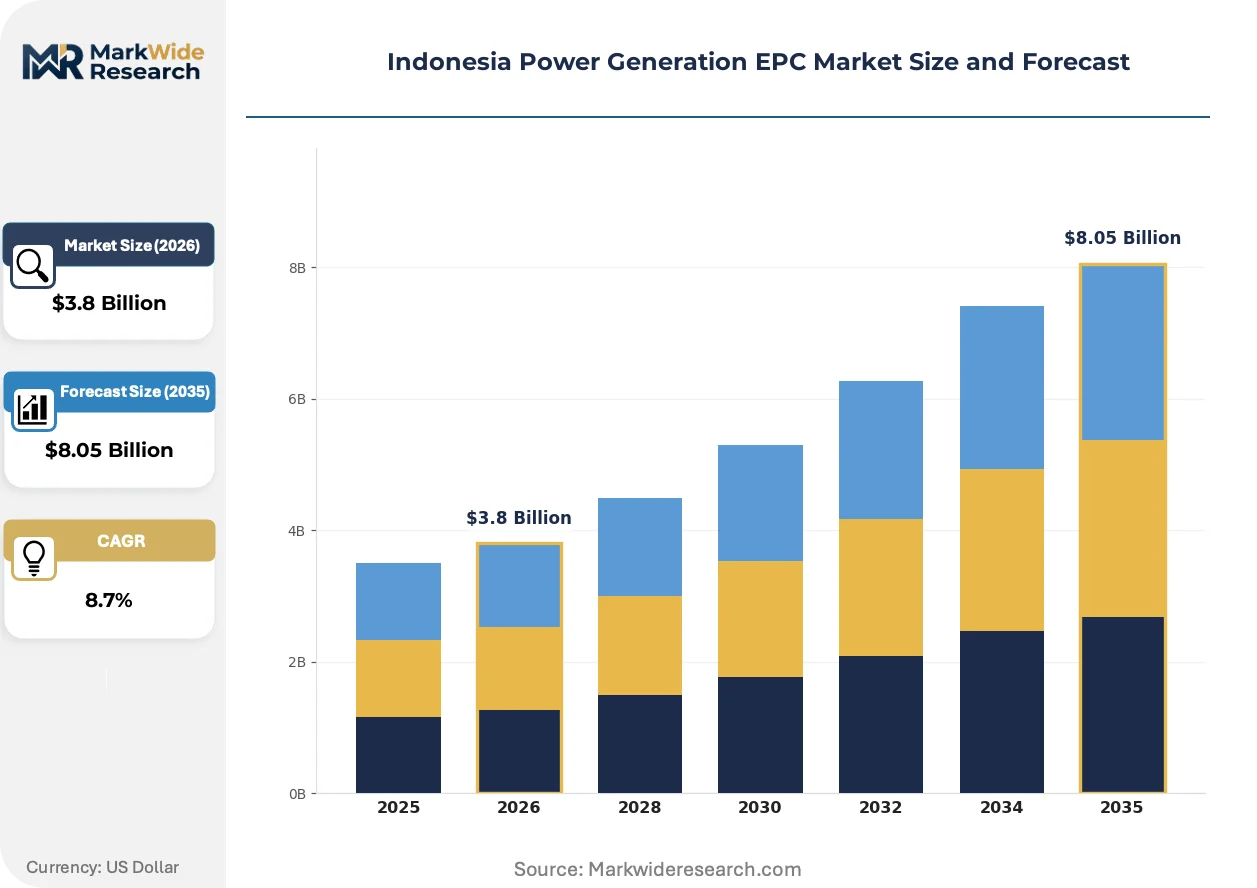
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Hydro, Solar Service Type: Engineering, Procurement, Construction, Project Management End User: Utilities, Independent Power Producers, Government, Industrial Users Installation: Onshore, Offshore, Urban, Rural |
| Companies Covered | General Electric Company, PT Adaro Energy Tbk, PT Wijaya Karya (Persero) Tbk, Samsung Engineering Co., Ltd., Hyundai Engineering Co. Ltd., PT Pembangunan Perumahan (Persero) Tbk, Marubeni Corp, Chiyoda Corporation, PT Rekayasa Industri (Persero), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Power Generation EPC Market Shifts & Advancements
Digitization of project controls and modular construction methodologies are compressing traditional EPC execution timelines across Indonesia's power infrastructure buildout. Contractor differentiation now hinges on integrated digital twin deployment rather than standalone civil-structural scale.
Containerized battery energy storage systems are miniaturizing grid-scale power quality solutions for distributed installation across Indonesia's islanded networks. PLN's distribution units are procuring 10-50 MWh modular units for frequency regulation in lieu of greenfield peaker plants. This technology is miniaturizing the capital commitment threshold for grid stability investments, enabling faster procurement cycles outside PLN's centralized generation planning.
MEMR's carbon capture utilization and storage readiness assessments for existing coal fleets are mandating reservoir characterization and pipeline routing studies in EPC scopes. Contractors must now integrate subsurface geology partnerships into traditional power island engineering. The regulation compresses project development timelines by front-loading permitting requirements that previously followed financial close.
Smelter operators in Morowali and Weda Bay are contracting directly with independent power producers under captive generation licenses, displacing PLN-mediated procurement for industrial load centers. This bilateral contracting model fragments the historical single-buyer market structure. The shift concentrates EPC demand in nickel processing corridors where energy intensity requirements exceed 500 MW per industrial park.
Indonesia Power Generation EPC Market Segmentation
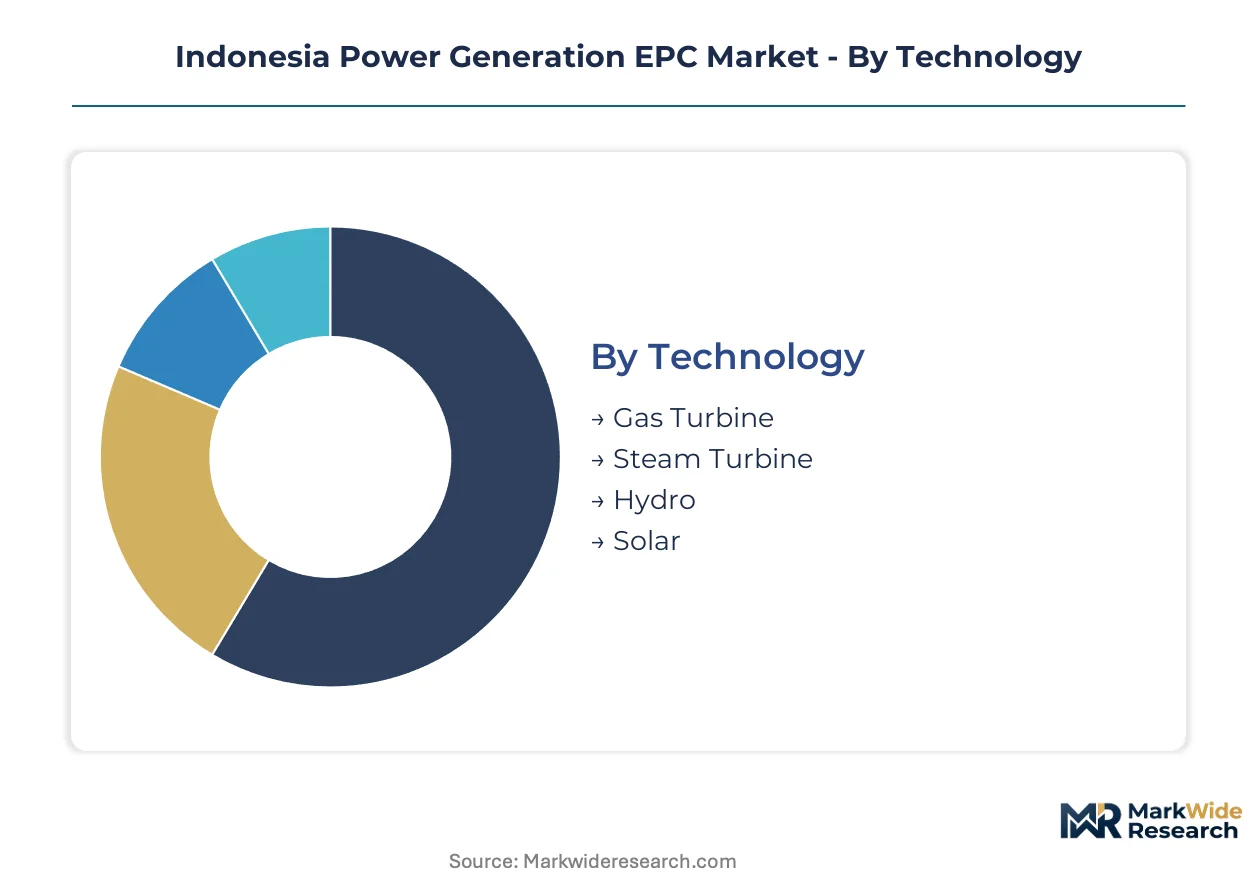
Segmentation in Indonesia's power generation EPC market reveals how MEMR local content mandates and PLN procurement hierarchies reshape contractor positioning across technology classes and service tiers. Understanding these divisions exposes where domestic partnership requirements create protected market access versus open competitive bidding.
Technology:
MEMR's tiered domestic content regulations impose progressively stricter local component ratios on imported turbine technologies, privileging contractors with established Indonesian fabrication partnerships.
- Gas Turbine:Combined-cycle configurations dominate PLN's 35 GW program procurement, with Korean and Japanese OEM partnerships essential for meeting efficiency guarantees on Java-Bali grid stability projects. MEMR mandates 40-50% local content thresholds for gas turbine packages, forcing EPCs to front-load domestic civil-structural and balance-of-plant sourcing.
- Solar:Photovoltaic installation segments accelerate from low base penetration as distributed generation regulations permit direct industrial offtake, with module mounting and DC cabling qualifying as domestic content under relaxed BIS-equivalent standards for renewable projects.
- Steam Turbine:Coal-fired baseload expansion has stalled under carbon neutrality commitments, concentrating remaining EPC demand on ultra-supercritical retrofits and biomass co-firing modifications.
- Hydro:Run-of-river and pumped storage development concentrates in Sumatra and Sulawesi watersheds, where geotechnical survey bottlenecks from Bandung and Yogyakarta academic institutes extend mobilization timelines.
Gas Turbine handles the majority of throughput; Solar is the fastest mover on share.
Service Type:
Cost tier differentiation separates front-loaded engineering risk from commodity-exposed procurement functions and capital-intensive construction mobilization.
- Engineering:Proprietary turbine alignment protocols and heat rate guarantee modeling command premium margins, with front-loaded technical risk concentrated in Jakarta-based design centers holding ISO 9001 certification.
- Construction:Archipelago logistics and specialized welding certification scarcity create execution bottlenecks, with ASME Section IX qualification backlogs extending mobilization timelines by six to nine months.
- Procurement:Long-lead equipment scheduling absorbs volatile commodity exposure through Northeast Asian supply base concentration, vulnerable to Singapore Strait maritime chokepoints.
- Project Management:Digital twin deployment and integrated controls commissioning now differentiate contractor bids, compressing traditional execution timelines through modular construction methodologies.
Engineering captures the margin concentration; Project Management is climbing the fastest as digitization restructures competitive positioning.
End User:
Customer type fragmentation is displacing PLN's historical single-buyer dominance, with industrial captive power liberalization creating bilateral contracting corridors outside centralized procurement.
- Utilities:PLN's generation procurement guidelines and rupiah-denominated finance prudential rules from Bank Indonesia constrain foreign currency exposure, steering capital toward domestic banking structures.
- Industrial Users:Smelter operators in Morowali and Weda Bay nickel processing corridors contract directly with independent power producers under captive generation licenses, bypassing PLN offtake intermediation for loads exceeding 500 MW per industrial park.
- Independent Power Producers:Merchant plant development faces tariff renegotiation risks as MEMR recalibrates renewable energy pricing against fossil fuel baseload economics.
- Government:Remote island electrification programs in Eastern Indonesia generate distributed demand for solar-diesel-battery hybrid systems outside the main grid footprint.
Utilities retain the dominant contract volume; Industrial Users are gaining share fastest as nickel processing corridors expand.
Installation:
Geography determines grid interconnection complexity and domestic content qualification pathways, with submarine cable corridors creating specialized offshore platform EPC demand.
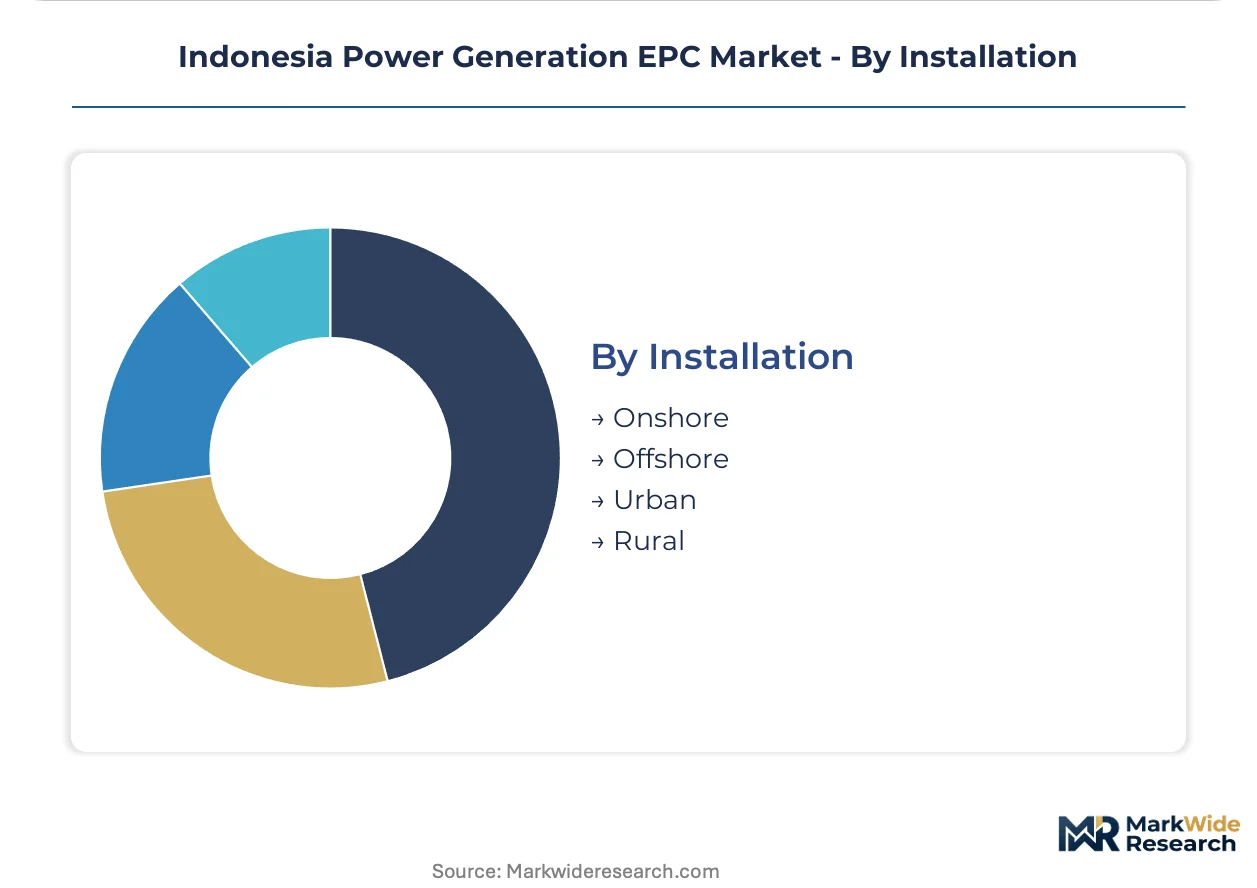
- Onshore:Java-Bali corridor concentrates execution where 500 kV backbone transmission interconnection needs are most acute, with volcanic soil characterization requirements creating geotechnical survey bottlenecks.
- Offshore:The 1,500 km Sumatra-Bangka-Belitung submarine cable corridor requires offshore platform-based substation capabilities currently underrepresented in domestic contractor portfolios.
- Urban:Land scarcity and environmental permitting compress project development timelines in Jakarta and Surabaya load centers, favoring modular gas turbine and containerized battery deployments.
- Rural:Eastern Indonesia diesel-to-hybrid conversion programs operate outside PLN's centralized generation planning, enabling faster procurement cycles for distributed 10-50 MWh modular units.
Onshore commands the execution volume; Offshore shows the steepest expansion trajectory as transmission bridge investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMR's escalating local content mandates and PLN's procurement guidelines are redistributing EPC contract flows across Indonesia's archipelago, privileging contractors with established domestic fabrication partnerships and certified workforce development programs.
Java-Bali Corridor
The densest load centers in Indonesia drive concentrated investment in combined-cycle gas turbine capacity to stabilize frequency across the 500 kV backbone transmission network. Bank Indonesia's prudential rules on foreign currency project finance steer capital toward rupiah-denominated structures for grid interconnection projects. Surabaya and Jakarta host the primary engineering design centers where ISO 9001 certification gates tender participation.
Sumatra
Run-of-river hydro development and coal-fired baseload retrofits concentrate in watersheds and existing plant corridors where geotechnical survey bottlenecks extend mobilization timelines. MEMR mandates progressively higher domestic component ratios for equipment sourcing, forcing EPCs to front-load local civil-structural partnerships. Medan and Palembang anchor procurement coordination for transmission bridge investments linking the island to Bangka-Belitung.
Sulawesi
Nickel processing corridors in Morowali and Weda Bay generate direct power purchase agreements between smelter operators and independent power producers, bypassing PLN offtake intermediation for loads exceeding 500 MW per industrial park. Revised electricity supply regulations permit captive generation licensing outside centralized procurement. Makassar serves as the logistics hub for Eastern Indonesia project execution.
Kalimantan
Remote mine-mouth power plants and barge-mounted generation solutions address grid isolation in coal and mineral extraction zones where transmission infrastructure remains underdeveloped. Diesel-to-hybrid conversion programs operate outside PLN's centralized generation planning, enabling faster procurement cycles for distributed solar-diesel-battery systems. Balikpapan concentrates marine logistics coordination for archipelago equipment mobilization.
Eastern Indonesia
Archipelago electrification programs generate distributed EPC demand for containerized battery energy storage and modular solar installations across islanded networks outside the main grid footprint. PLN's distribution units procure 10-50 MWh modular units for frequency regulation in lieu of greenfield peaker plants. Ambon and Jayapura anchor field mobilization for hybrid system deployment in the outer islands.
Indonesia Power Generation EPC Market Competitive Landscape
Listed leaders compete with private specialists across qualification hierarchies, with state-owned enterprises anchoring procurement volumes through PLN's generation program while international EPCs leverage financing ties for technology-intensive packages. The contractor base stratifies into three tiers: domestic civil-structural integrators with archipelago logistics capabilities, Korean and Japanese engineering firms with OEM partnerships, and state-backed developers with government pipeline access. Consolidation pressure is concentrating through domestic partnership mandates and ISO 9001 certification requirements that freeze out undercapitalized entrants.
Within the state-owned tier, PT Wijaya Karya (Persero) Tbk and PT Pembangunan Perumahan (Persero) Tbk represent integrated civil-structural capabilities across government-backed project pipelines. Hyundai Engineering Co. Ltd. occupies a position among Korean EPCs leveraging financing ties to secure combined-cycle gas turbine awards. These three exemplify how contractor differentiation now hinges on domestic content compliance and established PLN procurement relationships rather than standalone technical scale.
| Leading Market Players |
|---|
| General Electric Company |
| PT Adaro Energy Tbk |
| PT Wijaya Karya (Persero) Tbk |
| Samsung Engineering Co., Ltd. |
| Hyundai Engineering Co. Ltd. |
| PT Pembangunan Perumahan (Persero) Tbk |
| Marubeni Corp |
| Chiyoda Corporation |
| PT Rekayasa Industri (Persero) |
| Others |
Supply & Pricing Matrix
MEMR local content regulations gate both contractor qualification tiers and price differentiation simultaneously, with ISO 9001 certification backlogs freezing tender participation for undercapitalized EPCs while privileging established domestic partnerships with protected market access. PLN's rupiah-denominated procurement guidelines compress margins on imported gas turbine packages while inflating premiums for archipelago logistics capabilities.
Pricing Analysis
Certification level creates the primary spread between EPC tiers, with ISO 9001-accredited contractors commanding project-based lump-sum premiums against uncertified competitors frozen from PLN tender participation. Price differentiation hinges on domestic content compliance ratios and after-sales performance guarantee terms, with Bank Indonesia's foreign currency prudential rules intensifying cost compression on dollar-denominated equipment procurement. Industrial captive power buyers in Morowali and Weda Bay nickel corridors exhibit lowest price sensitivity due to energy intensity requirements exceeding 500 MW per park, while remote island electrification programs face acute budget constraints.
Supply Chain Analysis
Singapore Strait maritime chokepoints tether equipment mobilization timelines to Northeast Asian turbine manufacturing concentration, with Korean and Japanese OEM supply bases drawing from specialized forging and precision casting clusters. Long-lead steam turbine and generator components rest on nickel alloy and high-grade steel dependencies vulnerable to commodity price volatility. Distribution runs through Jakarta-based engineering design centers coordinating archipelago field mobilization, with Balikpapan anchoring marine logistics for Eastern Indonesia project execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's power generation EPC market is crossing a platform-economics inflection as MEMR's carbon capture readiness assessments and PLN's digital twin procurement criteria force interoperability between subsurface geology partnerships and traditional power island engineering.
For Market Incumbents: Compound defensive positioning through backward integration into certified welding training institutes, addressing ASME Section IX qualification scarcity that extends mobilization timelines by six to nine months. Deepen archipelago logistics capabilities via Makassar and Balikpapan hub consolidation to outflank Korean and Japanese EPCs on Eastern Indonesia remote island electrification programs.
For New Entrants and Emerging Players: Lead with containerized battery energy storage system deployment expertise targeting PLN distribution units procuring 10-50 MWh modular units for frequency regulation outside centralized generation planning. Penetrate the Sumatra-Bangka-Belitung submarine cable corridor where offshore platform-based substation capabilities remain underrepresented in domestic contractor portfolios.
For Investors and Strategic Acquirers: MEMR's escalating domestic content mandates reshape the acquisition landscape toward EPCs with established Indonesian fabrication partnerships and certified local workforce development programs. Target mid-tier civil-structural integrators with ISO 9001 accreditation and existing PLN procurement relationships as consolidation pressure concentrates through certification requirements. Monitor tariff renegotiation risks as MEMR recalibrates renewable energy pricing against fossil fuel baseload economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fabrication Partnership | MEMR local content mandates protect market access for EPCs with certified Indonesian workforce programs. |
| Digital Twin Deployment | Integrated project controls differentiate contractor bids as PLN prioritizes modular construction methodologies. |
| Subsurface Geology Integration | Carbon capture readiness assessments mandate reservoir characterization partnerships in traditional power scopes. |
| Captive Power Licensing | Direct smelter-IPP agreements in nickel corridors fragment PLN's historical single-buyer market structure. |
| Offshore Platform Capability | Sumatra-Bangka-Belitung transmission bridge creates specialized EPC demand currently underrepresented domestically. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MEMR regulatory filings, PLN procurement guidelines, and Bank Indonesia prudential circulars, with utility planning officers, IPP project developers, EPC contractors, and grid operators providing ground-truth validation. Secondary sources include IEA power sector reports, ASEAN energy statistics, and project development databases tracking Indonesia's 35 GW program execution. Bottom-up contract aggregation triangulates against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type throughout the forecast period. CAGRs derive from installed capacity buildout trajectories, local content compliance cost curves, and industrial captive power liberalization velocity. Forecast inputs incorporate MEMR ammonia-hydrogen blending roadmaps and nickel processing corridor energy intensity requirements.
Forecasts assume regulatory continuity in MEMR local content mandates and Bank Indonesia foreign currency rules; material policy shifts on renewable energy tariffs or carbon capture timelines would require re-modeling. Practitioners should keep alternative scenarios live as PLN procurement recalibration and industrial PPA standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Europe Distributed Power Generation Market
Power Generation
India Thermal Power Plant Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Steam Turbine Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Retail Electricity Market
Power Generation
Global Power to Gas Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Oilfield Power Generation Market
Power Generation
LAMEA Microturbine Market
Power Generation
Thermal Power Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
South East Asia Power Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Global Power Grid System Market
Power Generation
Marine Power Plant Market