
 Southeast Asia Power Generation EPC Market | 2026-2036
Southeast Asia Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Power Generation EPC Market Analytics
A widening capability gap between integrated conglomerates and specialized engineering firms is bifurcating the Southeast Asia Power Generation EPC competitive landscape. Mitsubishi Heavy Industries leverages its gas turbine manufacturing base to capture turnkey combined-cycle contracts across Indonesia and Vietnam. Larsen & Toubro Limited anchors its position through domestic fabrication capacity and cross-border project logistics from India into Myanmar and Bangladesh. Hyundai Engineering Co. competes aggressively on lump-sum turnkey pricing for mega-scale coal and gas replacements in Thailand and the Philippines.
Southeast Asia Power Generation EPC encompasses the engineering, procurement, and construction of electricity generation facilities spanning thermal, renewable, and hybrid technologies, typically involving turbine island installation, balance-of-plant systems, and grid interconnection infrastructure rated from 10 MW to over 1,000 MW. The discipline serves utilities and independent power producers seeking to expand baseload capacity, integrate variable renewable output, or replace aging fossil assets across archipelagic and mainland ASEAN grids. Solar and gas turbine segments attract the majority of new order intake, with solar EPC margins compressing due to module cost declines while gas turbine contracts retain premium pricing tied to long-term service agreements. Hydropower remains mature in Laos and Vietnam, where most viable large-scale sites are already developed, though small-scale run-of-river rehabilitation offers niche opportunities. Mega projects concentrate among a handful of consortia capable of arranging multilateral financing and navigating complex land acquisition across multiple jurisdictions.
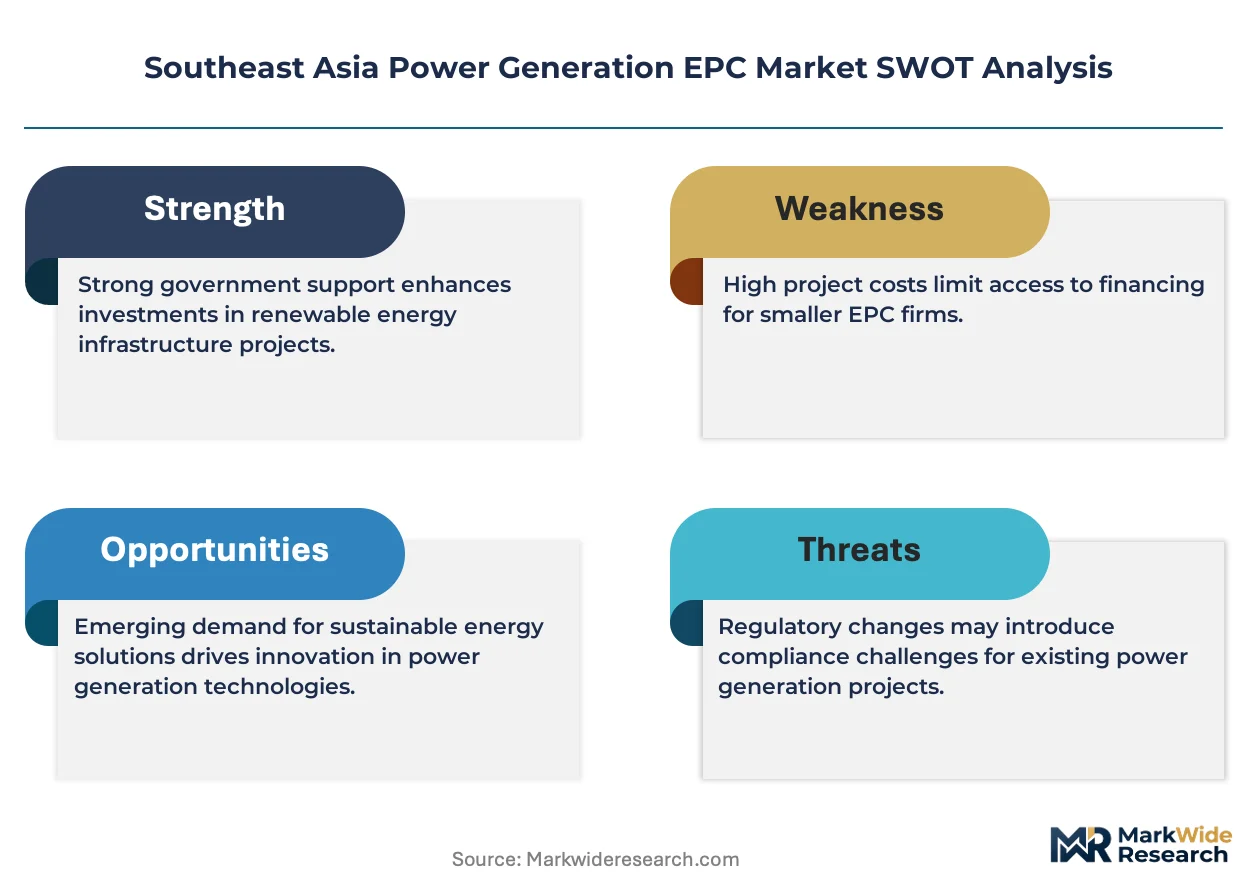
Indonesia's Ministry of Energy and Mineral Resources enforces local content requirements that reshape equipment sourcing and joint venture structures for foreign EPC contractors. Vietnam's Power Development Plan and circulars from the country's national utility regulator mandate competitive bidding for renewable projects, altering how developers select EPC partners and structure risk allocation. Thailand's ERC licensing framework and the Philippines' DOE permitting process add compliance layers that favor established players with in-house regulatory teams. Stakeholders must monitor how Indonesia's rooftop solar regulations and Vietnam's direct power purchase agreement pilots reshape project scale and offtake structures before committing capital to long-dated EPC contracts.
Market Dynamics
Indonesia's domestic content mandates and Vietnam's competitive bidding reforms are fragmenting procurement authority away from centralized utilities toward provincial regulators and industrial offtakers, forcing EPC contractors to rebuild pricing models around localized compliance costs rather than standardized turnkey rates.
Growth Catalysts
- Feed-in Tariff Reforms:Vietnam's revised solar and wind pricing mechanisms under EVN's latest circulars are unlocking stranded project pipelines that had stalled under previous rate uncertainty.
- Industrial Zone Expansion:Thailand's Eastern Economic Corridor Authority is accelerating power demand from petrochemical and automotive clusters seeking dedicated generation assets.
- Gas Turbine Technology:Advanced F-class and H-class units with 62%+ combined-cycle efficiency are displacing subcritical coal across Java-Bali procurement tenders.
Market Restraints
- LNG Price Volatility:Southeast Asian gas-fired project economics remain hostage to JKM-linked fuel costs that swing 40-60% within single fiscal years.
- Grid Interconnection Backlogs:PLN's transmission queue delays in Sumatra and Sulawesi strand completed generation assets for 18-36 months post-construction.
- Land Acquisition Complexity:Indonesia's agrarian reform processes and customary land rights create permitting timelines that exceed equipment delivery lead times by factors of two to three.
Strategic Opportunities
- Direct Power Purchase Agreements:Vietnam's pilot DPPA framework allows foreign manufacturers in Bac Ninh and Binh Duong to contract directly with renewable generators, bypassing EVN's monopoly.
- Solar-Plus-Storage Hybrids:Lithium-ion battery cost declines are enabling four-hour storage configurations that qualify for enhanced capacity payments under Thailand's ERC regulations.
- Small-Scale Run-of-River Rehabilitation:Laos and northern Vietnam host dozens of 10-50 MW hydropower assets requiring turbine and control system upgrades that fall below mega-project thresholds.
Industry Challenges
- Specialized Welding and Rotating Equipment Expertise:Shortages of ASME-certified pressure vessel welders and gas turbine commissioning engineers extend project schedules by 4-8 months across Indonesian and Philippine sites.
- Multilateral Financing Coordination:Arranging ADB, JICA, and AIIB co-financing structures requires navigating incompatible environmental safeguard standards that add 6-12 months to financial close timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Power Generation EPC Market |
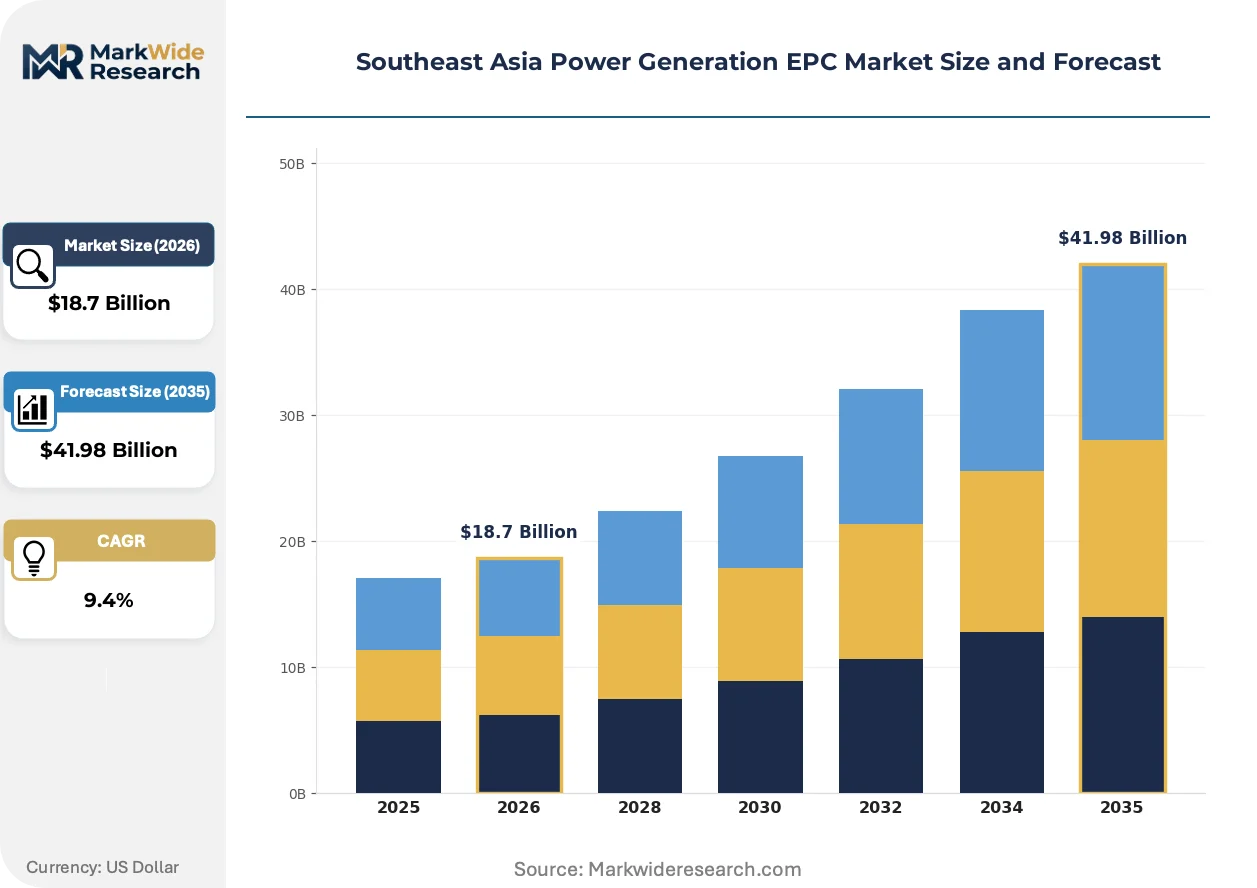
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Hydropower, Solar, Wind End User: Utilities, Independent Power Producers, Industrial Sector, Government Bodies Application: Urban Infrastructure, Rural Electrification, Industrial Applications, Commercial Use Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Poyry PLC, Larsen & Toubro Limited, Sumitomo Corporation, Kawasaki Heavy Industries, Toshiba Corp., Mitsubishi Heavy Industries, Indika Energy, Fluor Corporation, Hyundai Engineering Co., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Power Generation EPC Market Evolving Landscape
Modular construction methods and digital twin commissioning are compressing field execution schedules while regulatory pressure on carbon intensity is filtering technology choices upstream into EPC scope definitions.
Prefabricated electrical houses and skid-mounted balance-of-plant systems are decomposing traditional stick-built construction sequences. Indonesian IPPs in the Java-Bali corridor are adopting these modules to circumvent skilled labor shortages. Factory acceptance testing in supplier yards now replaces 30-40% of field commissioning hours, collapsing overall project duration by 8-14 months for 100-300 MW units.
Vietnam's Ministry of Industry and Trade circulars implementing competitive bidding for solar and wind projects are eliminating feed-in tariff certainty that previously underpinned EPC contract structures. Developers must now absorb merchant price risk or negotiate complex hedging instruments. Foreign contractors are responding by demanding higher contingency allowances and shorter construction windows to limit exposure to tariff regime changes.
Industrial offtakers in Thailand's Eastern Economic Corridor are unbundling long-term O&M agreements from initial EPC awards. Petrochemical and data center operators now prefer separate 5-7 year service contracts with penalty clauses tied to heat rate degradation. This procurement pattern is most visible in Rayong and Chonburi provinces, where Japanese and Korean EPC firms are establishing dedicated service subsidiaries to capture recurring revenue streams.
Southeast Asia Power Generation EPC Market Segmentation
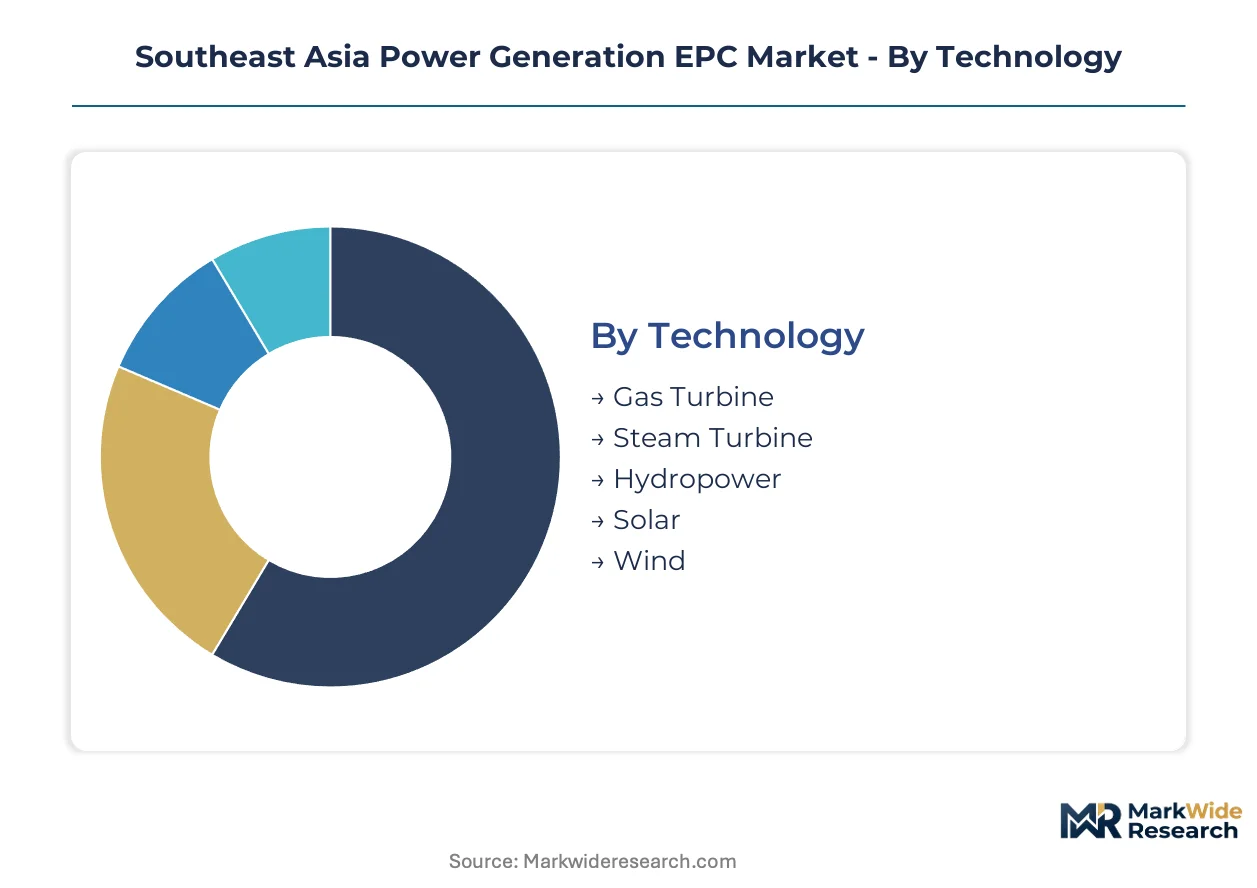
Technology choice dictates EPC contractor capability requirements, financing structures, and local content compliance across Southeast Asian procurement cycles. Segment boundaries are blurring as hybrid configurations and modular delivery methods reshape traditional technology categories.
Technology:
Gas turbine and solar segments face intensifying substitution pressure from battery-hybrid systems and advanced combined-cycle configurations that displace single-cycle thermal assets.
- Gas Turbine:Combined-cycle configurations rated 100-400 MW dominate Java-Bali corridor tenders, with PLN favoring F-class and H-class units for 62%+ efficiency. Procurement concentrates in Indonesia and Vietnam where LNG infrastructure expansion supports fuel-switching from coal.
- Solar:Utility-scale photovoltaic EPC contracts span 50-200 MW ground-mounted arrays, with Vietnam's competitive bidding reforms compressing developer margins. Module cost declines are forcing contractors toward fixed-tilt and tracking system differentiation rather than pure installation plays.
- Steam Turbine:Subcritical coal retrofits and biomass co-firing upgrades persist in Thailand and the Philippines where existing steam paths limit greenfield alternatives.
- Hydropower:Run-of-river rehabilitation below 50 MW offers niche opportunities in Laos and northern Vietnam, though most viable large-scale sites are already developed.
- Wind:Onshore projects face transmission interconnection constraints in Vietnam's central highlands, slowing EPC award velocity despite favorable resource profiles.
Gas turbine retains volume leadership across the region; solar holds the steepest expansion curve as module costs and financing structures improve.
End User:
Procurement authority is fragmenting toward industrial offtakers seeking captive generation outside traditional utility frameworks.
- Utilities:State-owned power companies in Indonesia, Vietnam, and Thailand anchor baseload procurement through competitive tenders and direct negotiations, with PLN and EVN driving combined-cycle and grid-scale solar awards.
- Independent Power Producers:Private developers navigate Vietnam's competitive bidding circulars and Indonesia's local content mandates, structuring EPC contracts around merchant price exposure and offtake security.
- Industrial Sector:Petrochemical and data center operators in Thailand's Eastern Economic Corridor are unbundling EPC from O&M agreements, demanding separate service contracts with heat rate guarantees.
- Government Bodies:Provincial regulators and rural electrification agencies in Indonesia and Myanmar procure small-scale distributed generation outside national utility frameworks.
Utilities dominate current contract value; industrial offtakers are climbing the fastest as direct power purchase agreement pilots expand.
Application:
Project scale and grid proximity determine EPC pricing models and technology selection across archipelagic and mainland ASEAN markets.
- Urban Infrastructure:Grid-connected generation serving metropolitan load centers in Jakarta, Ho Chi Minh City, and Bangkok favors gas turbine and solar hybrid configurations with existing transmission access.
- Industrial Applications:Captive power plants for manufacturing clusters in Vietnam's Bac Ninh and Binh Duong provinces leverage direct power purchase agreement frameworks to bypass utility intermediaries.
- Rural Electrification:Distributed diesel and small-scale solar-diesel hybrids address last-mile connectivity in Indonesia's outer islands and Myanmar's border regions where grid extension is uneconomic.
- Commercial Use:Rooftop solar and embedded generation for retail and office complexes faces regulatory fragmentation across Indonesian provincial implementations.
Industrial applications command premium EPC margins; urban infrastructure absorbs the highest absolute contract volume.
Project Size:
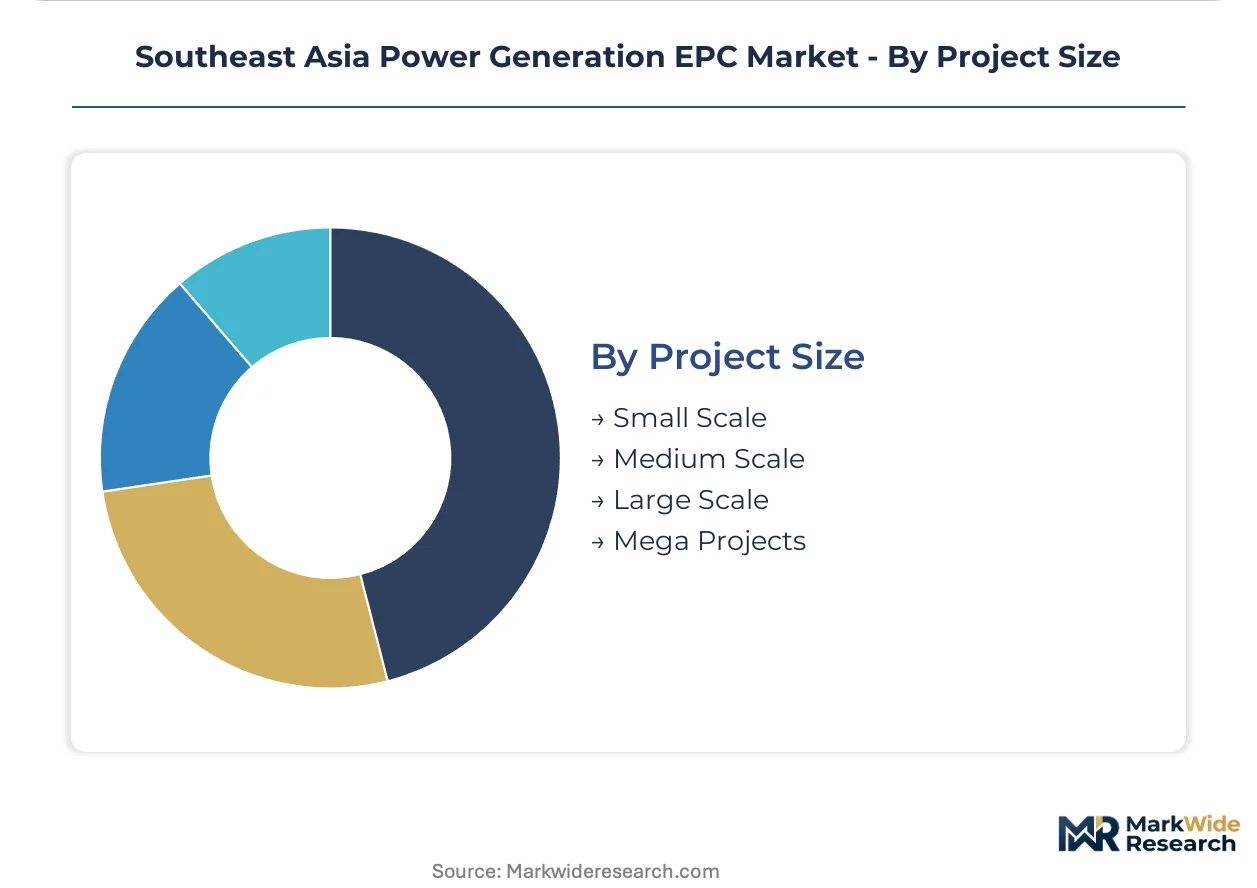
Financing complexity and contractor qualification thresholds create distinct competitive arenas across the size spectrum.
- Mega Projects:Installations exceeding 1,000 MW require consortia with multilateral financing access and cross-jurisdictional land acquisition expertise, concentrating among Japanese and Korean integrated conglomerates.
- Large Scale:300-1,000 MW combined-cycle and solar farms constitute the core revenue base for established EPC contractors with in-house regulatory teams.
- Medium Scale:50-300 MW projects attract specialized engineering firms and domestic contractors competing on localized compliance cost optimization.
- Small Scale:Below 50 MW run-of-river rehabilitation and distributed solar enable regional contractors to bypass mega-project qualification barriers.
Large scale projects generate the majority of current revenue; medium scale contracts are expanding most quickly as distributed generation procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia consumes EPC services differently from its neighbors by forcing local content compliance into every procurement layer, while Vietnam and Thailand prioritize competitive bidding efficiency and industrial captive generation respectively. This tripartite demand pattern shapes how contractors structure joint ventures, price risk, and sequence project execution across the region.
Indonesia
PLN's Java-Bali corridor tenders dominate order intake, with state utility procurement favoring combined-cycle gas plants above 200 MW. The Ministry of Energy and Mineral Resources enforces domestic content mandates that require foreign contractors to partner with local fabricators for balance-of-plant equipment. Industrial clusters in Cilegon and Gresik host steel and petrochemical facilities driving captive power demand outside PLN's centralized framework.
Vietnam
EVN's competitive bidding circulars have eliminated feed-in tariff certainty, forcing developers to absorb merchant price exposure or negotiate complex hedging instruments. The Ministry of Industry and Trade's direct power purchase agreement pilots allow foreign manufacturers in Bac Ninh and Binh Duong provinces to contract directly with renewable generators. Central highlands wind projects face transmission interconnection constraints that slow EPC award velocity despite favorable resource profiles.
Thailand
The Eastern Economic Corridor Authority accelerates power demand from petrochemical and automotive clusters seeking dedicated generation assets. ERC licensing frameworks add compliance layers that favor established players with in-house regulatory teams. Rayong and Chonburi provinces host unbundled procurement patterns where industrial offtakers separate long-term O&M agreements from initial EPC awards.
Philippines
The Department of Energy permitting process creates multilayered approval timelines that extend project development cycles by 12-18 months relative to regional peers. LNG terminal infrastructure expansion in Batangas province supports gas-fired project economics despite JKM-linked fuel cost volatility. Grid interconnection backlogs in Luzon strand completed generation assets for extended periods post-construction.
Southeast Asia Power Generation EPC Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Japanese and Korean conglomerates controlling mega-project financing access while Indian and Southeast Asian contractors capture medium-scale distributed generation awards. The market structure rewards players with captive gas turbine manufacturing, cross-border logistics capabilities, or domestic fabrication capacity. Three archetypes dominate: integrated technology-to-EPC conglomerates, regional specialists with local content compliance expertise, and global engineering firms with multilateral financing relationships. Competitive intensity concentrates on consortium formation for multilateral-backed projects and service subsidiary establishment to capture recurring O&M revenue.
Among Japanese integrated conglomerates, Mitsubishi Heavy Industries and Toshiba Corp. occupy positions that leverage captive gas turbine manufacturing into turnkey combined-cycle contract capture across Indonesia and Vietnam. Hyundai Engineering Co. represents the Korean lump-sum pricing archetype competing aggressively on turnkey rates for mega-scale replacements in Thailand and the Philippines. Larsen & Toubro Limited anchors the Indian cross-border specialist tier, deploying domestic fabrication capacity and project logistics into Myanmar and Bangladesh adjacent markets.
| Leading Market Players |
|---|
| Poyry PLC |
| Larsen & Toubro Limited |
| Sumitomo Corporation |
| Kawasaki Heavy Industries |
| Toshiba Corp. |
| Mitsubishi Heavy Industries |
| Indika Energy |
| Fluor Corporation |
| Hyundai Engineering Co. |
| Others |
Value Network & Pricing Analysis
Gas turbine manufacturing scale economies in Japan and Korea concentrate pricing power among integrated conglomerates, while module cost declines in solar EPC compress margins and force differentiation through after-sales service bundling. This asymmetry between thermal and renewable segments reshapes how contractors structure long-term revenue streams and source critical components across archipelagic ASEAN grids.
Pricing Analysis
Long-term service agreements and parts revenue now exceed 60% of lifetime contract value for combined-cycle gas turbine installations, shifting EPC pricing toward upfront equipment discounts with captive aftermarket lock-in. Three-tier pricing structure across premium, standard, and economy levels separates Mitsubishi and Toshiba turnkey offerings from Hyundai lump-sum bids and domestic Indonesian fabricator quotes. Cost compression in utility-scale solar EPC is intensifying because module price declines outpace balance-of-plant savings, squeezing contractor margins by half within three years. Industrial offtakers in Thailand's Eastern Economic Corridor demonstrate lowest price sensitivity due to heat-rate guarantee requirements, while provincial Indonesian IPPs negotiate aggressively on local content compliance costs.
Supply Chain Analysis
Malacca Strait transit congestion and port capacity constraints in Singapore and Tanjung Pelepas govern heavy gas turbine and generator set delivery schedules across the region. Manufacturing concentration in Japan, South Korea, and China for F-class and H-class turbines, combined with domestic Indonesian and Vietnamese steel fabrication for balance-of-plant structures, creates dual-source dependencies. Single-source vulnerability persists for advanced combustion turbine rotors and precision casting components sourced exclusively from Mitsubishi Heavy Industries and Siemens Energy parent facilities. Distribution runs through regional hub-and-spoke logistics networks anchored in Jakarta, Ho Chi Minh City, and Bangkok, with final-mile coordination handled by local EPC joint venture partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified welding capacity and gas turbine commissioning expertise constitute the binding constraint on project execution velocity, with shortages extending Indonesian and Philippine schedules by one-third. Contractors who solve this capability gap through apprenticeship pipelines or technology partnerships capture disproportionate share of PLN and EVN tender awards.
For Market Incumbents: Shield market position by acquiring specialized rotating equipment service firms in Vietnam and Indonesia before Korean competitors establish captive training centers. Deepen backward integration into balance-of-plant steel fabrication through joint ventures with Cilegon and Gresik industrial zone partners, neutralizing local content compliance cost penalties that erode turnkey margins. For New Entrants and Emerging Players: Lead with small-scale run-of-river rehabilitation below 50 MW in Laos and northern Vietnam, where mega-project qualification barriers exclude integrated conglomerates and provincial regulators accept simplified EPC structures. Target direct power purchase agreement pilots in Bac Ninh and Binh Duong provinces, positioning as independent engineering specialists who navigate EVN competitive bidding circulars without legacy feed-in tariff contract baggage. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EPC contractors who unbundle O&M agreements and establish dedicated service subsidiaries in Thailand's Eastern Economic Corridor. Long-term viability over the coming decade rests on capturing heat-rate guarantee contracts with penalty clauses that lock in petrochemical and data center operators. Acquisition screening should prioritize firms with in-house regulatory teams and multilateral financing relationships. The signal to watch is JKM-linked LNG price volatility breaching thresholds that trigger coal-to-gas switching acceleration in Indonesian procurement tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Joint Venture Formation | Indonesia's Ministry of Energy and Mineral Resources mandates domestic fabrication partnerships that reshape foreign contractor market access. |
| Service Subsiliary Establishment | Thailand's ERC licensing framework rewards EPC firms who separate long-term O&M agreements from initial construction awards. |
| Modular Construction Adoption | Prefabricated electrical houses and skid-mounted systems compress Indonesian project schedules by circumventing skilled labor shortages. |
| Direct Power Purchase Agreement Positioning | Vietnam's Ministry of Industry and Trade pilots allow foreign manufacturers to contract directly with renewable generators outside EVN monopoly. |
| Multilateral Financing Consortium Building | ADB, JICA, and AIIB co-financing structures require environmental safeguard navigation that favors established EPC players with dedicated compliance teams. |
Research Methodology
Desk research of EIA country analysis briefs, IEA Southeast Asia energy outlooks, and PLN procurement tender databases preceded structured interviews with utility planning officers, IPP project developers, EPC contract managers, and grid interconnection specialists. Primary fieldwork across Jakarta, Ho Chi Minh City, and Bangkok validated secondary assumptions on local content compliance costs and competitive bidding timeline compression. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated against regulatory filing disclosures.
Variance decomposition across technology segments, project scale tiers, and regulatory framework clusters shaped the analytical framework over the projection horizon. Modeled dimensions span fuel source, generation capacity tier, end-user procurement authority, and regional grid interconnection backlog severity. CAGRs were derived from unit economics modeling of representative project archetypes, incorporating feed-in tariff regime transitions, LNG price trajectory assumptions, and module cost decline curves specific to Southeast Asian procurement cycles.
Forecasts assume regulatory continuity in Indonesia's domestic content mandates, Vietnam's competitive bidding circulars, and Thailand's ERC licensing frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Brazil Power Plant EPC Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Residential Solar Generator Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Power Plant EPC Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Iraq Power EPC Market
Power Generation
United Kingdom Power Market
Power Generation
India Thermal Power Plant Market
Power Generation
Europe Thermal Power Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
South America Thermal Power Market
Power Generation
South East Asia Power Market
Power Generation
Australia Thermal Power Market
Power Generation
India Gas Generator Market