
 Wind Turbine Crane Market | 2026-2036
Wind Turbine Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Crane Market Insights
Modular crane configuration is pivoting buyer preference toward transport-optimized lifting systems that reduce mobilization costs between wind farm sites. Liebherr leverages its integrated manufacturing scale to supply self-erecting tower cranes purpose-built for nacelle placement. Konecranes anchors its position through electric-drive technology leadership in port-to-site logistics chains. Huisman Equipment BV specializes in bespoke offshore lifting solutions for next-generation turbine dimensions.
Wind turbine cranes are heavy-lifting machines engineered to handle nacelles, blades, and tower sections weighing hundreds of tonnes, with boom configurations reaching heights exceeding 150 meters to accommodate hub elevations on modern turbines. Their primary purpose is enabling safe, precision assembly and maintenance of onshore and offshore wind energy infrastructure. Mobile cranes dominate onshore deployment due to terrain adaptability and rapid site-to-site relocation, while crawler cranes capture the most structurally demanding offshore foundation lifts where ground-bearing pressure and stability under load are critical. Electric-drive technology is gaining share against hydraulic systems as operators target emission reductions during construction phases and grid-connected sites impose stricter environmental compliance.
European crane deployments fall under the EU Machinery Directive and CE marking requirements for lifting equipment safety certification, while offshore installations must satisfy national maritime regulators and the ILO's dock work conventions. China's SAMR enforces GB standards for crane structural integrity and operator certification, shaping export competitiveness of domestic manufacturers. The US OSHA and FAA coordinate on tower crane proximity to aviation corridors, constraining installation logistics in the Great Plains wind corridor. Stakeholders must monitor how evolving turbine scaling beyond 15 MW rated capacity forces crane OEMs to rethink load charts, counterweight strategies, and vessel-integration designs before committing to fleet renewal cycles.
Market Dynamics
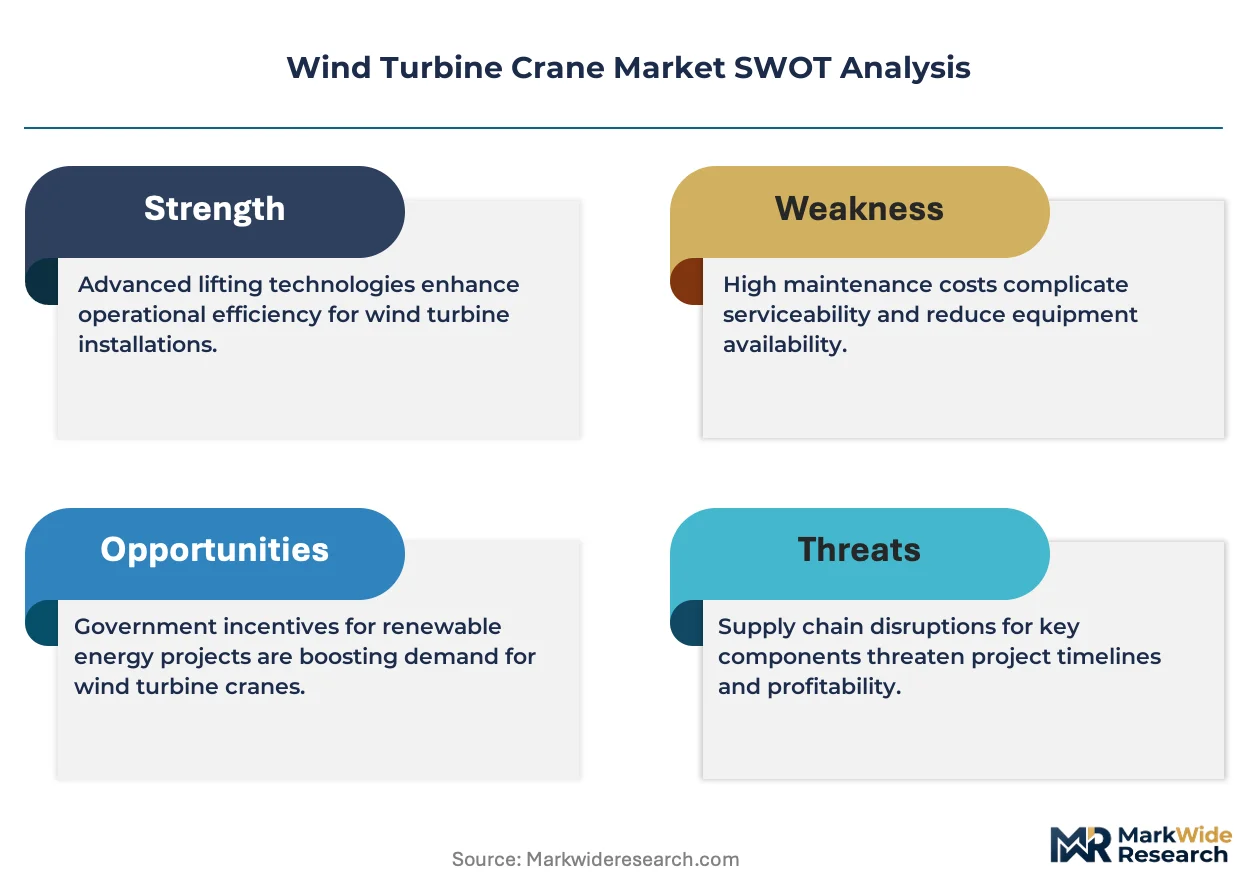
Turbine scaling beyond 15 MW rated capacity is compressing crane fleet replacement cycles and forcing load chart recalibration across installation contractors. This dimensional escalation favors electric-drive systems with precision control over legacy hydraulic configurations.
Growth Catalysts
- Offshore expansion in the North Sea:German port infrastructure investments at Bremerhaven and Cuxhaven are enabling heavier component staging for floating foundation installations.
- China's dual carbon goals:SAMR enforcement of updated GB standards for lifting equipment structural integrity is accelerating domestic crane manufacturing upgrades for nacelle placement.
- Electrification mandates:Grid-connected construction sites in Denmark and the Netherlands now require emission-free lifting equipment, pulling electric-drive crawler cranes into project specifications.
Market Restraints
- Specialized steel alloy scarcity:High-grade boom steel supply concentrates among a limited set of European and Japanese metallurgical suppliers, creating input cost volatility for crane OEMs.
- Maritime certification friction:Offshore crane systems must satisfy both EU Machinery Directive CE marking and national maritime regulator protocols, extending deployment timelines.
- Foundation installation bottlenecks:Monopile diameter growth beyond 12 meters exceeds current heavy-lift vessel crane capacity, constraining project sequencing.
Strategic Opportunities
- Floating wind emergence:Pre-assembly of turbine components on floating substructures at port creates demand for land-based heavy cranes with 3,000-tonne lifting capacity.
- US Great Plains corridor:FAA coordination requirements on tower crane proximity to aviation corridors have suppressed deployment density, creating latent demand for compliant self-erecting systems.
- Service life extension:Retrofit packages for hydraulic-to-electric drive conversion open aftermarket revenue streams for installed crawler crane fleets.
Industry Challenges
- Certified operator scarcity:GB standards-compliant crane operator certification programs in China and OSHA credentialing in the US cannot scale to match fleet expansion rates.
- Counterweight logistics:Transport of 500-tonne superlift counterweight packages between dispersed wind farm sites consumes mobilization budgets and extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Crane Market |
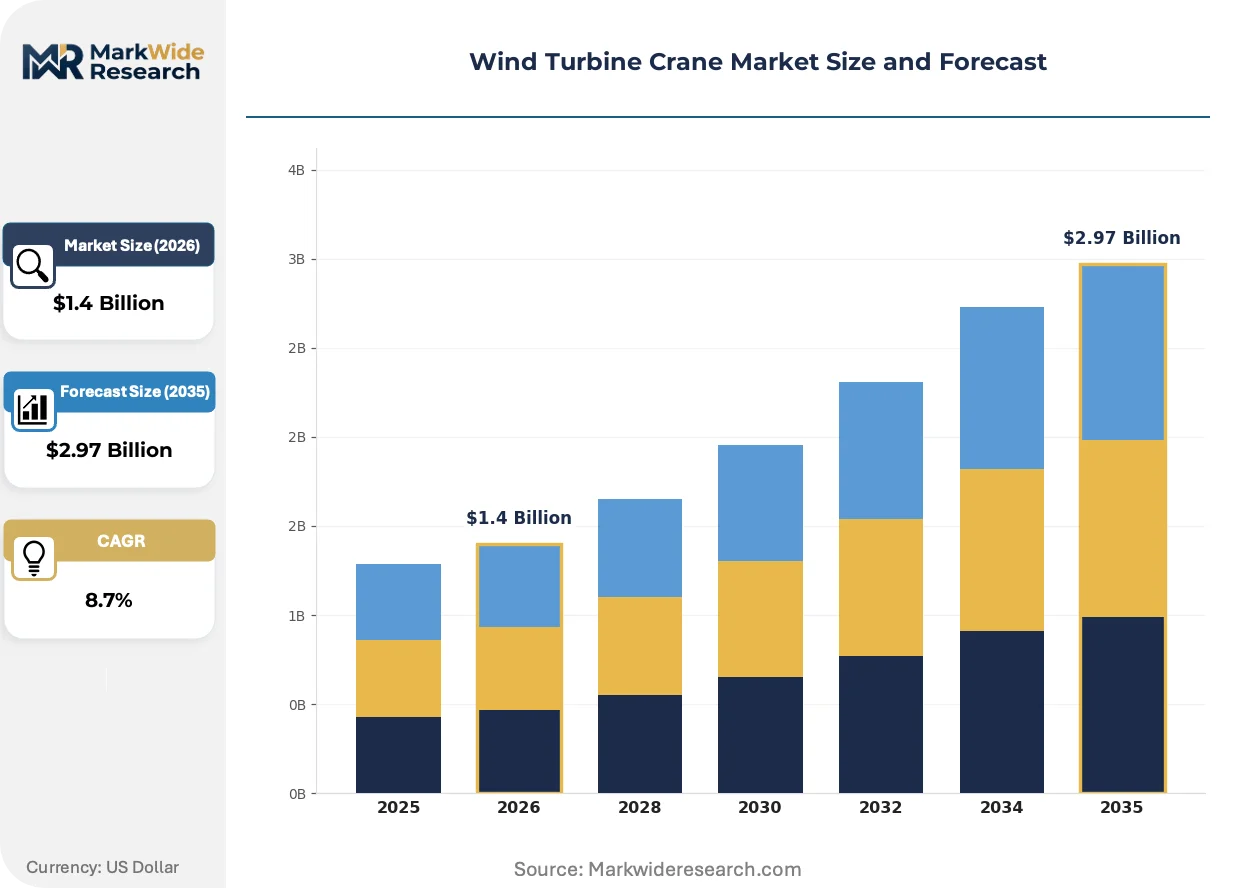
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Cranes, Tower Cranes, Crawler Cranes, Port Cranes End User: Utilities, Construction Firms, Renewable Energy Providers, Maintenance Services Deployment: Onshore, Offshore, Hybrid, Temporary Technology: Hydraulic, Electric, Pneumatic, Others |
| Companies Covered | Liebherr, Konecranes, Huisman Equipment BV, Mammoet, SANY, Sarens, Terex Corporation, Fred. Olsen Windcarrier AS, Liftra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Crane Market Trends and Innovations
Digital twin integration and autonomous load positioning are compressing installation windows while reducing weather dependency for offshore lifts. These capabilities are reshaping contractor procurement criteria toward integrated system suppliers.
Sensor-integrated boom monitoring is automating real-time structural stress assessment during nacelle lifts. Offshore contractors in the North Sea are specifying these systems on all new crawler crane acquisitions. The technology is automating go/no-go decisions that previously required manual engineering review, compressing weather window utilization.
The EU Machinery Directive's 2023 amendment on autonomous lifting equipment is forcing crane OEMs to redesign control architectures for functional safety compliance. Systems must now demonstrate fail-safe positioning without operator intervention. Electric-drive configurations with integrated PLCs are capturing specification share as contractors pre-empt certification requirements.
Equipment-as-a-service contracting is displacing outright crane purchases among mid-scale onshore developers. Danish and German wind farm operators now favor availability-guaranteed rental structures with bundled maintenance. This shift is most visible in the 800-1,200 tonne capacity segment where utilization rates fluctuate seasonally.
Wind Turbine Crane Market Segmentation
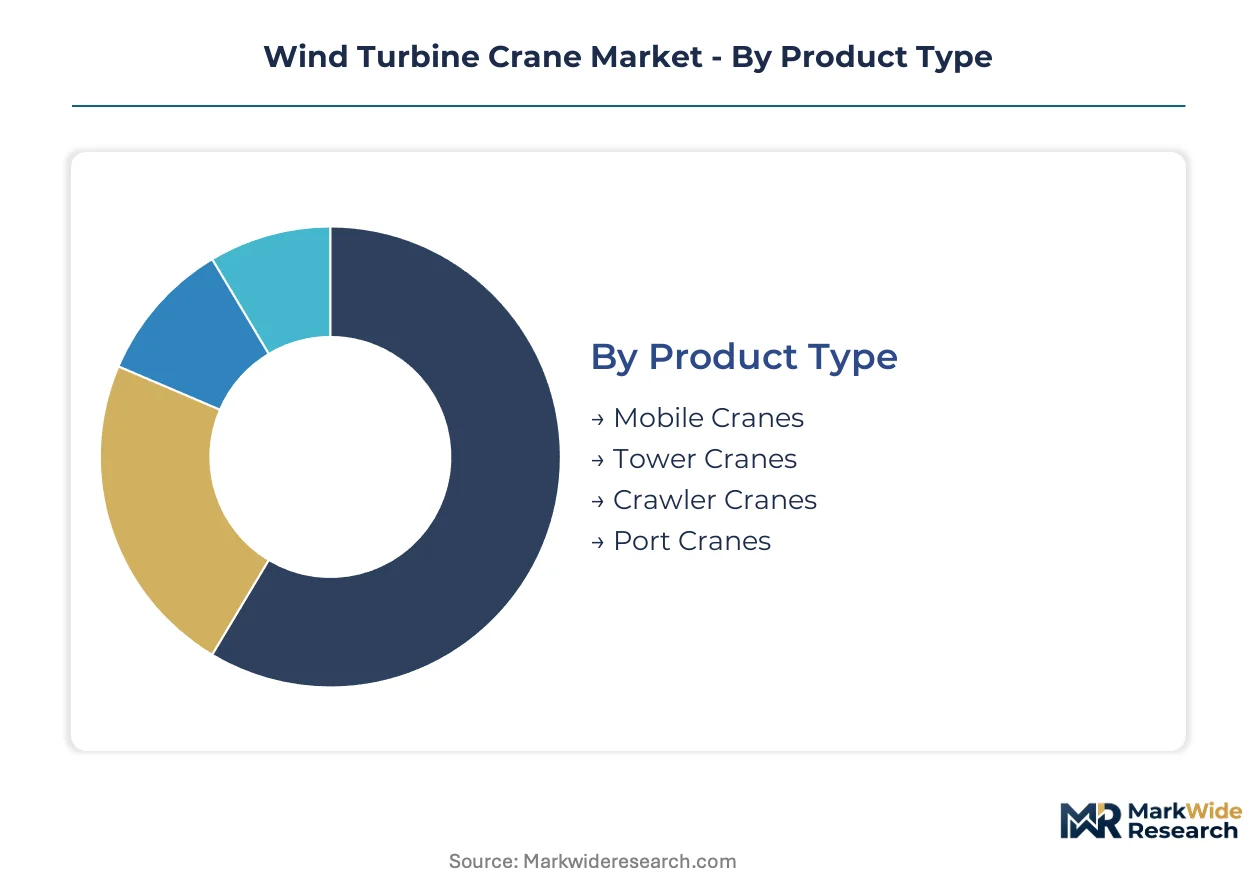
Crane specification choices cascade through project economics, mobilization logistics, and regulatory compliance across wind farm development cycles. Buyers segment procurement by terrain constraints, component dimensions, and grid-connection requirements rather than lifting capacity alone.
Product Type:
Site accessibility and foundation type dictate crane selection more than rated load, with terrain adaptability commanding premium pricing in remote installations.
- Mobile Cranes:All-terrain and rough-terrain configurations deploy hydraulic outrigger systems for rapid leveling on unprepared ground. Demand concentrates in the US Great Plains corridor where OSHA-coordinated aviation clearance constraints favor compact footprint systems that relocate between dispersed turbine pads daily.
- Crawler Cranes:Tracked undercarriages distribute ground-bearing pressure across soft coastal substrates during monopile foundation placement. German North Sea contractors specify these for 3,000-tonne capacity lifts at Bremerhaven staging yards where floating foundation pre-assembly requires stationary precision.
- Tower Cranes:Self-erecting designs with integrated climbing systems reduce mobilization crew requirements for nacelle placement at hub heights exceeding 150 meters. Chinese domestic manufacturers optimize these for GB standards compliance in high-altitude wind corridors.
- Port Cranes:Gantry and ship-to-shore configurations handle blade and tower section staging at installation ports. Cuxhaven and Rotterdam operators prioritize electric-drive variants to satisfy EU Green Deal emission mandates.
Mobile cranes lead on scale across installed fleet volumes; crawler cranes lead on momentum with fastest specification upgrades for 15 MW+ turbine dimensions.
End User:
Capital intensity and project duration separate procurement patterns between balance-sheet owners and contracted installation specialists.
- Utilities:Vertically integrated power generators favor long-term crane fleet ownership with captive maintenance capabilities. German offshore wind farm operators at EnBW and RWE anchor demand for 1,200-tonne+ crawler systems with availability-guaranteed service contracts.
- Construction Firms:General contractors bidding fixed-price EPC contracts prioritize rental structures with bundled operator certification. Danish installation contractors face certified operator scarcity that extends mobilization timelines beyond project schedules.
- Renewable Energy Providers:Independent power producers without captive construction arms specify equipment-as-a-service contracting. These developers concentrate in China's northern provinces where SAMR-enforced GB standards reshape supplier qualification requirements.
- Maintenance Services:Specialized O&M contractors require compact mobile units for blade repair and gearbox replacement. US Great Plains service providers navigate FAA coordination for temporary crane placement near aviation corridors.
Utilities dominate capital deployment; construction firms are expanding most quickly into rental-structured procurement.
Deployment:
Environmental exposure severity determines corrosion protection specifications and control system redundancy requirements.
- Onshore:Terrain-adaptable mobile and crawler configurations handle turbine assembly across variable ground conditions. Chinese onshore installations in Inner Mongolia and Gansu provinces drive demand for cold-weather hydraulic fluid systems.
- Offshore:Vessel-integrated crane systems must satisfy both EU Machinery Directive CE marking and national maritime regulator protocols. German North Sea projects face certification friction that extends deployment timelines.
- Hybrid:Dual-purpose cranes transition between port staging and near-shore foundation work. These systems concentrate at Bremerhaven where floating wind pre-assembly creates blended operational requirements.
- Temporary:Short-duration rental configurations serve grid emergency response and storm damage repair. Dutch and Danish operators specify these for seasonal maintenance windows.
Onshore deployments retain volume leadership; offshore configurations show steepest expansion trajectory with floating foundation emergence.
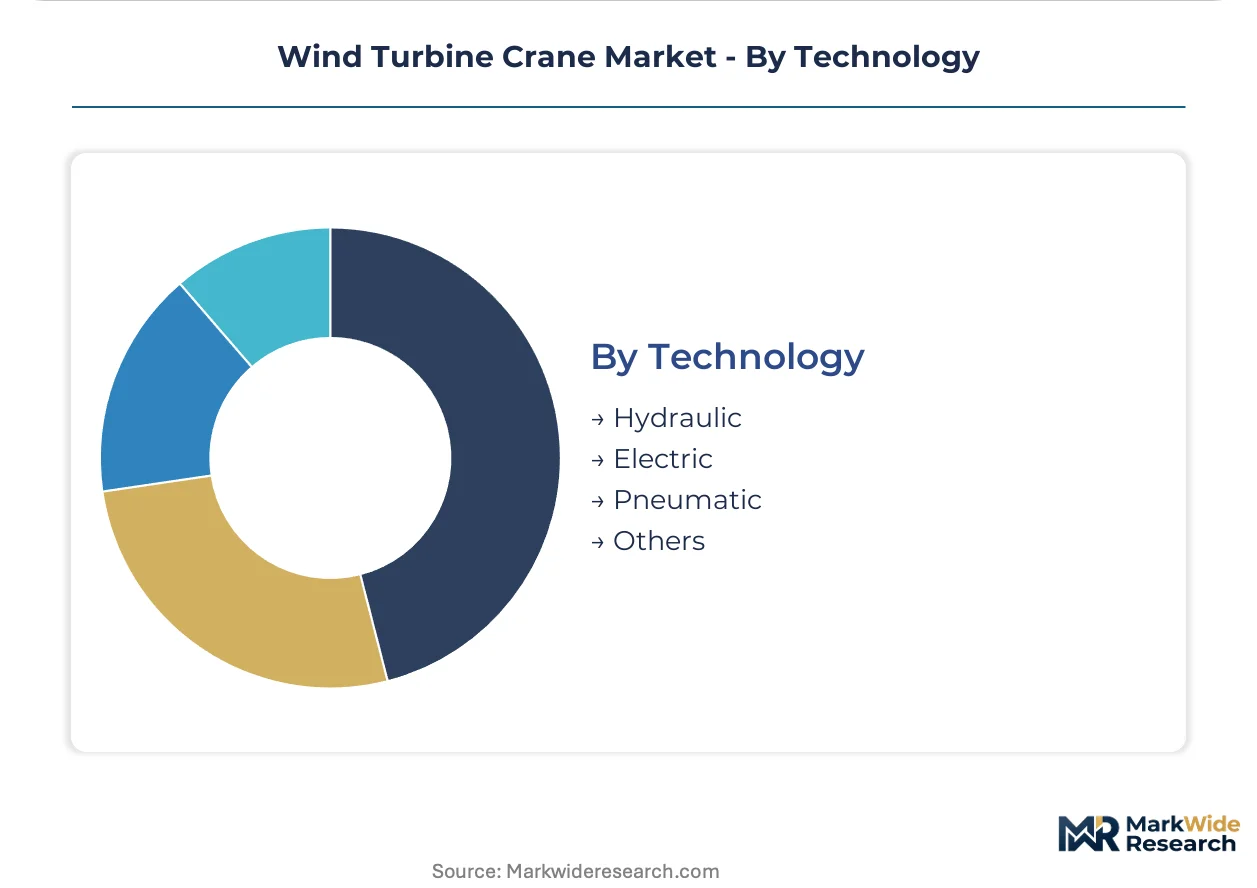
Technology:
Grid-connection status and construction-phase emission mandates increasingly filter hydraulic systems from project specifications.
- Hydraulic:Legacy power transmission systems dominate existing crawler crane fleets with proven reliability under shock loading. Retrofit packages for electric-drive conversion now open aftermarket revenue streams for these installed bases.
- Electric:Grid-tied or battery-electric configurations eliminate diesel combustion at sensitive sites. Denmark and the Netherlands now mandate emission-free lifting equipment for grid-connected construction, pulling electric-drive crawler cranes into project specifications.
- Pneumatic:Compressed air systems serve specialized explosive-atmosphere applications in offshore platform integration. These niche deployments concentrate at Norwegian North Sea facilities.
- Others:Hybrid and hydrogen fuel cell prototypes undergo field validation at German port demonstration sites. SAMR and EU Machinery Directive amendments on autonomous lifting equipment accelerate control architecture redesigns for these emerging systems.
Hydraulic systems anchor installed base volumes; electric configurations gain share fastest under tightening emission mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine crane manufacturing originated in Germany's industrial heartland during the 1990s offshore wind expansion, with Bremerhaven and Cuxhaven establishing the first dedicated heavy-lift staging infrastructure for North Sea installations.
Germany
Port infrastructure investments at Bremerhaven and Cuxhaven enable heavier component staging for floating foundation installations. EU Machinery Directive CE marking requirements shape equipment certification protocols for offshore deployment. North Sea contractors concentrate crawler crane fleets at Lower Saxony coastal yards where 3,000-tonne capacity systems pre-assemble turbine components.
China
SAMR enforcement of updated GB standards accelerates domestic crane manufacturing upgrades for nacelle placement. Dual carbon goals drive emission-free lifting equipment mandates at grid-connected construction sites. Inner Mongolia and Gansu provinces demand cold-weather hydraulic systems for high-altitude wind corridor installations.
United States
OSHA-coordinated aviation clearance constraints favor compact footprint mobile cranes in the Great Plains wind corridor. FAA regulations on tower crane proximity to aviation corridors suppress deployment density. Texas and Iowa installation contractors navigate seasonal mobilization windows between dispersed turbine pads.
Denmark
Grid-connected construction sites mandate emission-free lifting equipment, pulling electric-drive crawler cranes into project specifications. Equipment-as-a-service contracting displaces outright purchases among mid-scale developers. Esbjerg port operators prioritize electric-drive gantry configurations to satisfy EU Green Deal emission mandates.
Netherlands
Rotterdam and Eemshaven port infrastructure supports North Sea installation logistics with specialized blade staging capacity. National maritime regulators impose certification friction that extends offshore crane deployment timelines. Dutch installation contractors specify temporary rental configurations for seasonal maintenance windows.
Wind Turbine Crane Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with electric-drive system suppliers commanding pricing power over hydraulic legacy fleets. The vendor base concentrates among integrated industrial conglomerates and specialized offshore lifting fabricators. Three archetypes dominate: diversified heavy-machinery manufacturers with captive component supply, port-to-site logistics specialists with electric-drive technology leadership, and bespoke offshore solution providers for next-generation turbine dimensions. Competitive moves center on fleet electrification retrofit packages and availability-guaranteed rental structures with bundled maintenance.
Within the diversified industrial tier, Liebherr anchors German manufacturing scale across self-erecting tower crane configurations. Konecranes exemplifies electric-drive technology leadership in port-to-site logistics chains. Huisman Equipment BV occupies the bespoke offshore specialist position for floating wind foundation integration. These three represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| Liebherr |
| Konecranes |
| Huisman Equipment BV |
| Mammoet |
| SANY |
| Sarens |
| Terex Corporation |
| Fred. Olsen Windcarrier AS |
| Liftra |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing of high-grade boom steel in Germany and Japan anchors crane OEM pricing power through controlled alloy supply. This backward integration into specialized metallurgy insulates tier-one suppliers from raw material volatility while forcing tier-two assemblers toward spot-market exposure.
Pricing Analysis
Equipment-as-a-service contracting now dominates mid-capacity segments, with availability-guaranteed rental structures displacing outright purchases. Price differentiation hinges on CE marking compliance tier and bundled operator certification packages. Cost compression in standard mobile crane tiers intensifies as Chinese manufacturers scale GB-certified exports. Construction firms bidding fixed-price EPC contracts exhibit highest price sensitivity; utilities with captive fleet operations show lowest.
Supply Chain Analysis
Certified welder and crane operator scarcity in Lower Saxony and Jiangsu provinces constrains production ramp rates for specialized offshore systems. Manufacturing concentrates in Germany, China, and Finland, with high-grade steel plate sourcing from Japanese and European metallurgical suppliers. Single-source vulnerability in superlift counterweight casting creates bottleneck risk for 3,000-tonne capacity systems. Distribution runs through port-staging logistics chains at Bremerhaven, Rotterdam, and Cuxhaven.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where turbine scaling beyond 15 MW rated capacity pulls specification demand toward electric-drive precision systems with integrated sensor architectures.
For Market Incumbents: Anticipate certified operator scarcity compressing fleet utilization rates by accelerating autonomous load positioning R&D to reduce crew dependency. Defend margin position through captive boom steel supply agreements with ThyssenKrupp or Nippon Steel, insulating against alloy price volatility that erodes tier-two competitors.
For New Entrants and Emerging Players: Launch via equipment-as-a-service partnerships with Danish and German mid-scale developers who lack captive maintenance capabilities. White-space concentrates in FAA-compliant self-erecting tower cranes for the US Great Plains corridor, where aviation clearance constraints suppress incumbent deployment density.
For Investors and Strategic Acquirers: Roll-up economics work for regional crane rental specialists with certified operator pipelines because fragmented local fleets lack scale to meet utility availability-guaranteed contracting demands. Target acquisition archetype: 800-1,200 tonne capacity fleet operators in North Sea port zones with established maritime certification relationships. Monitor floating wind foundation contract awards as inflection signal for 3,000-tonne capacity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Drive Fleet Conversion | Denmark and Netherlands emission mandates pull battery-electric crawler cranes into project specifications. |
| Autonomous Load Positioning R&D | EU Machinery Directive 2023 amendments force fail-safe control architecture redesigns. |
| Port Infrastructure Partnership | Bremerhaven and Cuxhaven staging investments enable floating foundation pre-assembly capacity. |
| Certified Operator Pipeline Investment | GB standards and OSHA credentialing gaps constrain fleet expansion across installation contractors. |
| Retrofit Package Development | Hydraulic-to-electric conversion opens aftermarket revenue from installed crawler crane bases. |
Research Methodology
Coverage spans Germany, China, Denmark, the Netherlands, and the United States, with primary inputs from each. Interviews with EPC contractors, port logistics operators, crane OEM procurement directors, and utility fleet managers combined with secondary validation from EU Machinery Directive filings, SAMR GB standard updates, FAA coordination records, and IEA offshore wind project databases. Bottom-up unit deployment tracking triangulates against top-down capacity installation forecasts.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include crane product type, end-user capital intensity, deployment environment exposure, and drive technology configuration. CAGRs derive from logistic diffusion curves fitted to turbine scaling parameters and port infrastructure investment pipelines. Industry-specific inputs incorporate monopile diameter growth trajectories and floating foundation contract award velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under maritime certification friction delays or specialized steel alloy supply disruptions. Forecasts reflect documented assumptions on turbine scaling continuity and emission mandate enforcement timelines. Material deviation in floating wind foundation contract velocity or GB standards implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market