

Residential Solar Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Generator Market Insights
Off-grid residential demand is hardening as grid instability and wildfire-related public safety power shutoffs push homeowners toward self-sufficient energy architectures. Generac Power Systems leverages its standby generator dealer network to cross-sell solar-battery bundles across hurricane-prone coastal counties. EcoFlow anchors its position through modular expansion packs that let buyers scale capacity without replacing inverters. Jackery competes in the sub-2 kW portable segment where camping and RV owners prioritize weight over cycle life.
A residential solar generator converts photovoltaic energy into stored DC power through integrated lithium-ion or lithium iron phosphate battery packs, with pure sine wave inverters delivering 120V/240V AC output for household circuits; systems typically range from 500 Wh portable units to 20 kWh stationary installations with MPPT charge controllers and grid-forming inverters. Portable solar generators occupy the highest volume tier among product types but carry thinner margins than hybrid solar generators where battery-inverter integration commands price premiums. The 3-5 kW capacity range captures the bulk of whole-home backup installations, while above 5 kW systems concentrate in new construction projects with pre-wired solar readiness. Roof-mounted installation dominates in established suburbs, though ground-mounted arrays gain traction on larger rural properties where setback rules permit.
FERC Order 2222 enables aggregated residential storage to participate in wholesale markets, while California's SGIP incentive program and NEM 3.0 export rate structure directly shape battery sizing decisions for new installations. Germany's EEG 2023 reforms reduce feed-in tariffs while exempting battery-stored self-consumption from grid fees, redirecting installer focus toward storage attachment rates. Australia's CEC accreditation requirements and state-level home battery subsidies in Victoria and South Australia create a fragmented but high-growth compliance environment. Stakeholders must monitor how evolving interconnection standards and time-of-use rate designs alter the economic case for oversizing battery capacity versus generator-only backup.
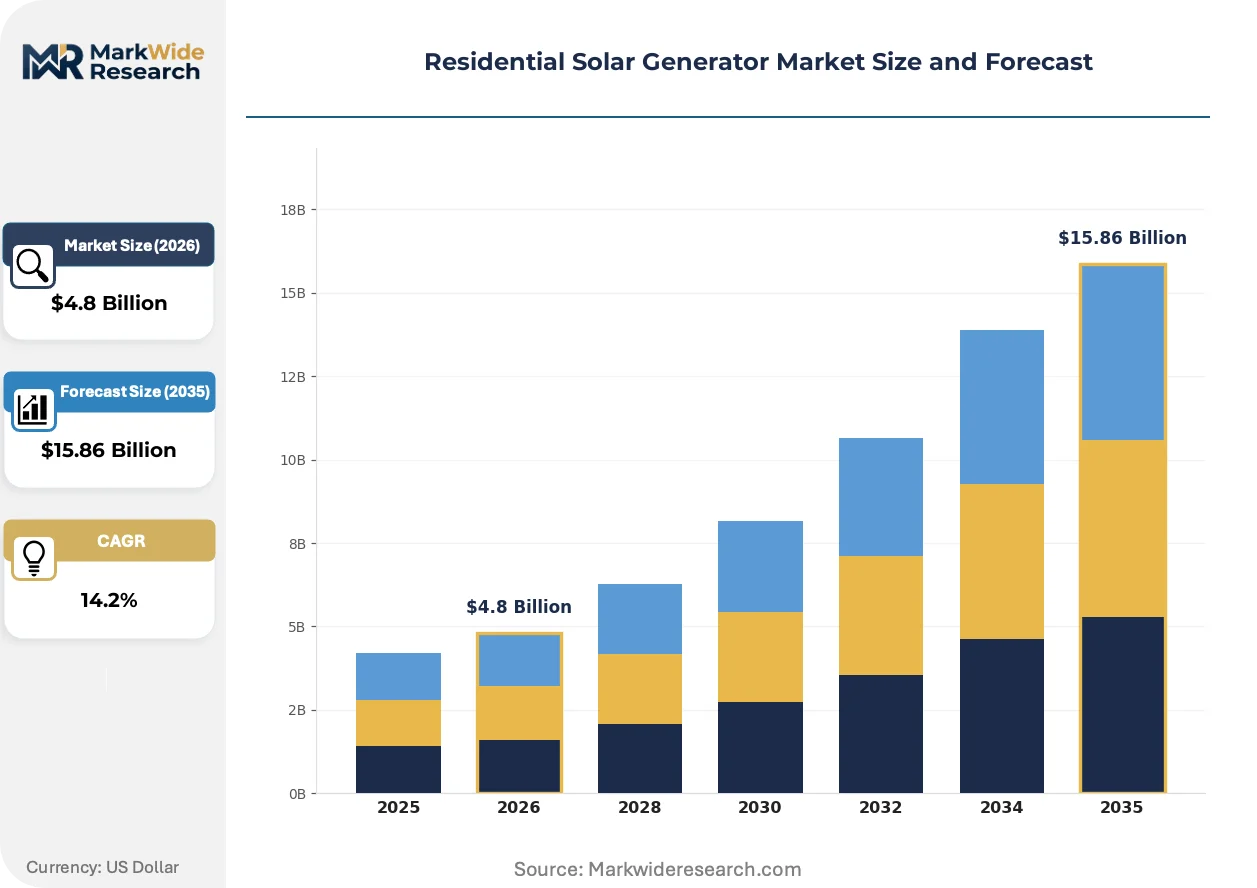
Market Dynamics
Net metering reforms across California and Germany are compressing solar export economics, forcing homeowners to oversize battery storage and accelerating the shift from grid-tied to hybrid solar-battery architectures.
Growth Catalysts
- Public Safety Power Shutoffs:Wildfire-driven grid de-energization protocols in California counties are hardening demand for whole-home backup systems with islanding inverters.
- FERC Order 2222:Aggregated residential storage participation in wholesale markets creates new revenue streams for battery-equipped households.
- Lithium Iron Phosphate Chemistry:Thermal stability and extended cycle life are displacing NMC batteries in stationary residential installations.
Market Restraints
- Raw Material Concentration:Lithium carbonate processing concentrates in China, exposing battery pack assemblers to supply rationing during quota periods.
- Interconnection Backlogs:Utility approval timelines for behind-the-meter storage stretch 6-18 months in high-penetration California districts.
- Natural Gas Generator Substitution:Propane and diesel standby units retain cost advantage for short-duration backup in hurricane-prone Gulf Coast counties.
Strategic Opportunities
- Victoria Home Battery Subsidy:Australia's state-level incentive programs reduce payback periods for 10+ kWh systems in suburban Melbourne electrification clusters.
- Modular Expansion Architectures:Stackable battery packs without inverter replacement enable incremental capacity scaling as household loads grow.
- RV and Camping Segment:Lightweight portable units under 2 kWh serve van-life and overlanding buyers who prioritize packability over cycle depth.
Industry Challenges
- Certification Timeline Compression:UL 9540A fire safety testing for residential battery systems creates 4-6 month product launch delays.
- Installer Skill Shortage:Grid-forming inverter commissioning requires electrical contractors trained in frequency-watt control protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Generator Market Trends and Innovations
Technology convergence between solar inverters and battery management systems is collapsing hardware margins while software-defined energy arbitrage creates new value capture layers for system integrators.
Lithium iron phosphate cell chemistry is consolidating its position as the dominant stationary storage format. Suburban electrification clusters in Australia and Germany are specifying LFP exclusively for 10-year warranty compliance. This chemistry shift is compressing NMC market share in residential applications where cycle life outweighs energy density priorities.
California's NEM 3.0 export rate structure is reducing compensation for rooftop solar feed-in. Homeowners are responding by right-sizing battery capacity to maximize self-consumption rather than grid export. Installer attachment rates for storage paired with new solar have climbed sharply in SCE and SDG&E territories.
Direct-to-consumer channel expansion is fragmenting traditional electrical contractor distribution. EcoFlow and Jackery are capturing sub-5 kW portable demand through e-commerce and outdoor retail partnerships. This bypasses the permit-driven sales cycle that slows stationary system deployment in established suburbs.
Residential Solar Generator Market Segmentation
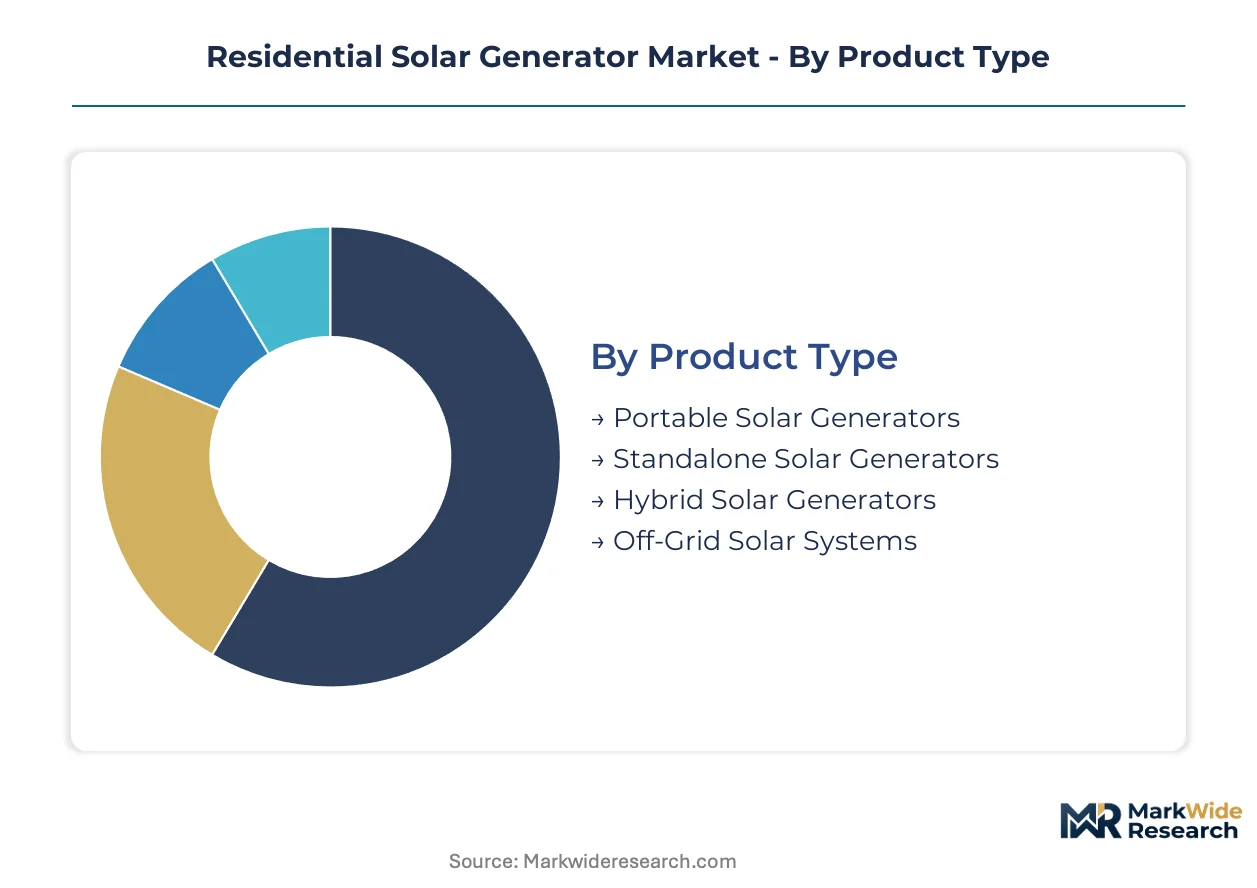
Segmentation in residential solar generators reveals how hardware integration depth shapes customer economics and installer workflows. Buyers self-select across standalone portable units, battery-inverter hybrids, and fully off-grid architectures based on grid reliability exposure and permitting appetite.
Product Type:
Standalone portable units operate without grid interconnection, while hybrid and off-grid systems embed battery management with inverter control—creating divergent certification and commissioning requirements.
- Portable Solar Generators:Self-contained lithium iron phosphate units under 2 kWh with integrated MPPT controllers and AC outlets. Demand clusters in California recreational counties and Australian coastal camping corridors where weight-constrained buyers prioritize packability over cycle depth. FERC Order 2222 excludes these sub-kilowatt units from wholesale market aggregation.
- Hybrid Solar Generators:Grid-tied battery-inverter combinations enabling self-consumption optimization and islanding capability. California NEM 3.0 export compression is accelerating attachment rates in SCE and SDG&E territories where homeowners oversize storage to avoid reduced feed-in compensation.
- Standalone Solar Generators:AC-coupled battery systems retrofitting existing solar arrays without inverter replacement. Germany's EEG 2023 battery storage exemptions from grid fees are redirecting installer focus toward this retrofit segment.
- Off-Grid Solar Systems:DC-coupled architectures with grid-forming inverters and oversized battery banks for permanent energy independence. Remote residences in Australian Victoria and South Australia electrification clusters specify these for properties beyond distribution line extension economics.
Portable solar generators lead volumes today; hybrid solar generators are gaining share fastest.
Capacity Range:
Cost tier stratification separates entry-level backup from whole-home resilience and new construction pre-wiring specifications.
- Up to 1 kW:Entry-level portable units serving camping and essential device charging. Jackery and EcoFlow dominate this sub-$2,000 tier through outdoor retail and direct-to-consumer channels.
- 1-3 kW:Partial home backup covering refrigeration and lighting circuits. California public safety power shutoff protocols are hardening demand in fire-prone counties.
- 3-5 kW:Whole-home backup capacity with 240V appliance support. This tier captures the bulk of suburban retrofit installations across United States, Australia, and Germany.
- Above 5 kW:New construction and large rural property specifications with pre-wired solar readiness and EV charging integration. Ground-mounted arrays in Australian rural properties and German agricultural conversions concentrate here.
3-5 kW systems anchor revenue concentration today; above 5 kW configurations show steepest expansion trajectory in new construction pipelines.
Installation Type:
Mounting geometry determines permitting complexity, structural engineering requirements, and setback rule applicability across suburban versus rural deployment contexts.
- Roof-Mounted:Dominant configuration in established United States suburbs with mature solar contractor networks. Interconnection backlogs in high-penetration California districts stretch utility approval timelines 6-18 months.
- Ground-Mounted:Preferred for larger Australian rural properties and German agricultural buildings where setback rules permit and shading optimization drives yield. Requires geotechnical assessment and trenching for battery housing.
- Wall-Mounted:Garage and exterior wall configurations for battery-inverter units in space-constrained urban properties. UL 9540A fire safety testing creates 4-6 month product launch delays for indoor-rated enclosures.
- Deck-Mounted:Elevated outdoor platforms for hybrid systems in flood-prone Gulf Coast counties where hurricane resilience demands above-grade battery placement.
Roof-mounted installations maintain volume leadership today; ground-mounted arrays are climbing the fastest in rural electrification clusters.
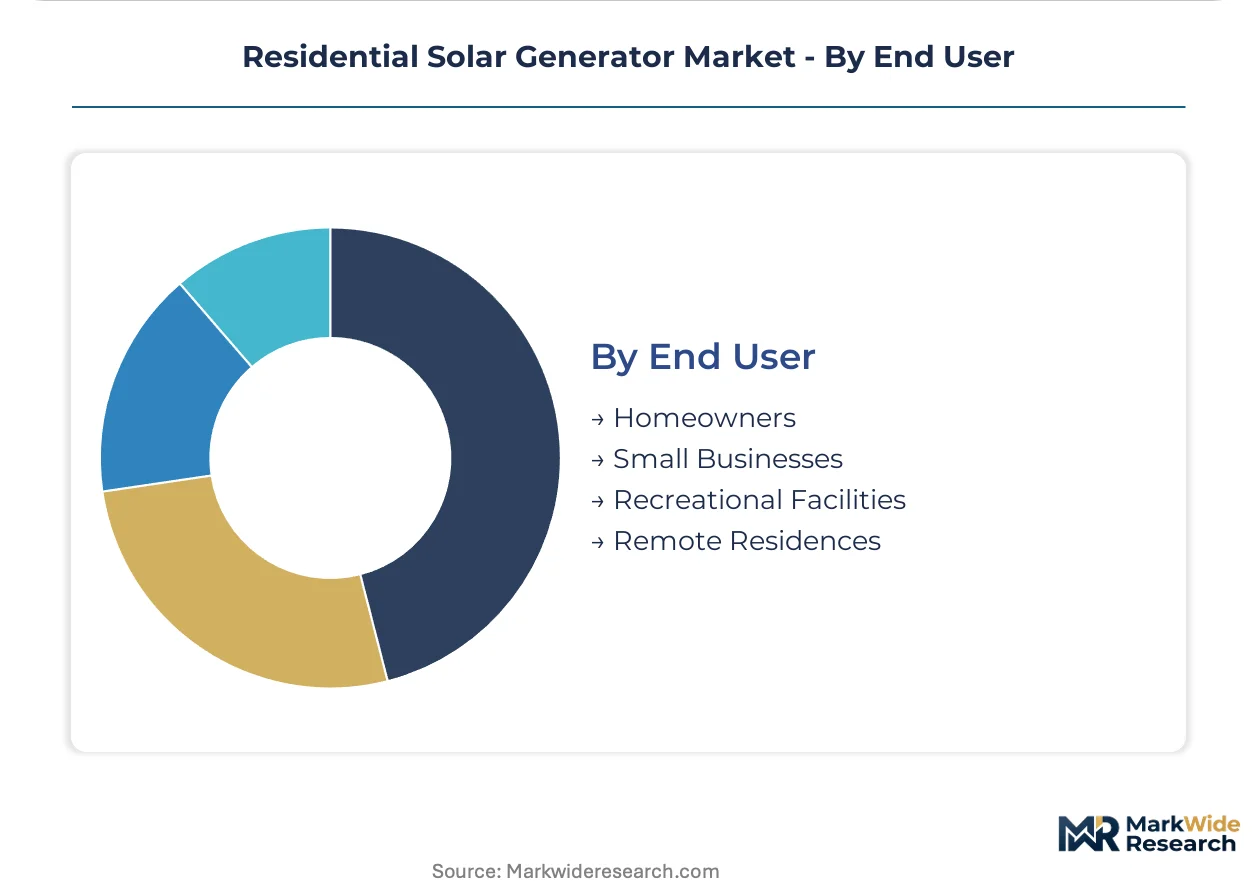
End User:
Customer type segmentation aligns procurement authority with load profile predictability and financing access.
- Homeowners:Primary demand source with split incentives between grid-tied savings and backup resilience. California NEM 3.0 and Germany's EEG reforms are reshaping payback calculations toward self-consumption maximization.
- Small Businesses:Home-based enterprises and rural commercial properties qualifying for accelerated depreciation. Australia's CEC accreditation requirements and Victoria state subsidies create compliance-driven procurement.
- Recreational Facilities:Campgrounds, RV parks, and eco-lodges specifying portable and sub-3 kW systems for guest amenities. Weight and noise constraints exclude fossil generator alternatives.
- Remote Residences:Off-grid homeowners beyond distribution infrastructure in Australian outback and German forest settlements. Lithium iron phosphate chemistry dominates for 10-year warranty compliance in these high-cycling applications.
Homeowners drive absolute volumes today; remote residences are expanding most quickly as grid extension economics deteriorate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as manufacturers migrate toward jurisdictions with streamlined battery safety certifications and favorable interconnection timelines. Cost-of-compliance gaps between California and Victoria, Australia, are accelerating contract manufacturing shifts.
United States
Public safety power shutoffs in California counties are hardening demand for whole-home backup systems with islanding capability. FERC Order 2222 enables aggregated residential storage participation in wholesale markets, creating new revenue streams for battery-equipped households. Suburban electrification clusters across Southern California Edison and San Diego Gas & Electric territories are driving installer attachment rates for storage paired with new solar.
Germany
EEG 2023 reforms reduce feed-in tariffs while exempting battery-stored self-consumption from grid fees, redirecting installer focus toward storage attachment rates. The country's national renewable energy regulator has reshaped payback calculations toward self-consumption maximization. Agricultural conversions in Lower Saxony and Bavaria are concentrating above-5 kW ground-mounted installations with pre-wired solar readiness.
Australia
Victoria and South Australia state-level home battery subsidies are reducing payback periods for 10+ kWh systems in suburban Melbourne electrification clusters. Clean Energy Council accreditation requirements create a fragmented but high-growth compliance environment for installer networks. Remote residences in Western Australia and Queensland outback are specifying lithium iron phosphate systems for properties beyond distribution line extension economics.
China
Domestic lithium carbonate processing concentration exposes battery pack assemblers to supply rationing during quota periods, creating procurement volatility for downstream manufacturers. The Ministry of Industry and Information Technology oversees dual carbon goals that shape cell chemistry transitions. Yangtze River Delta manufacturing hubs are consolidating lithium iron phosphate cell production for export-oriented residential storage OEMs.
Residential Solar Generator Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware manufacturers seek software-defined energy arbitrage capabilities through system integrator alliances. The vendor base stratifies across three tiers: legacy standby generator incumbents with dealer network leverage, pure-play lithium battery specialists with modular architectures, and direct-to-consumer portable brands with e-commerce scale. Archetypes include vertically integrated cell-to-system manufacturers, inverter-battery hybrid integrators, and lightweight portable specialists. M&A activity and geographic expansion through outdoor retail partnerships represent the dominant competitive vectors.
Among legacy power equipment manufacturers, Generac Power Systems exemplifies the standby-to-solar transition archetype through dealer network cross-selling. EcoFlow and Jackery anchor the direct-to-consumer portable tier, with the former representing modular expansion pack architectures and the latter occupying the sub-2 kW weight-optimized segment. These three companies illustrate how divergent channel strategies—electrical contractor networks versus e-commerce and outdoor retail—are fragmenting traditional distribution patterns in residential energy storage.
| Leading Market Players |
|---|
| Generac Power Systems |
| Jackery |
| EcoFlow |
| Goal Zero |
| Anker |
| Renogy |
| Growatt |
| Lion Energy |
| Bluetti |
| Others |
Pricing and Supply Chain Analysis
Suburban electrification clusters in California, Australia, and Germany concentrate procurement authority among electrical contractor networks and direct-to-consumer buyers, locking in divergent pricing models where installer-mediated sales command project-based premiums and e-commerce channels compete on per-unit transparency.
Pricing Analysis
Distributor margins for electrical contractor channels absorb 15-25 point markups over factory gate pricing, while direct-to-consumer brands bypass this layer entirely. Three-tier pricing structure across premium certified, standard utility-grade, and economy portable tiers differentiates UL 9540A fire-tested indoor enclosures from outdoor-rated commodity packs. Cost compression in the sub-2 kWh portable segment intensifies as Jackery and EcoFlow scale manufacturing volume. Recreational buyers exhibit highest price sensitivity, while remote residence owners prioritize cycle life specifications over upfront cost.
Supply Chain Analysis
Dual-sourcing requirements for lithium iron phosphate cells now mandate qualification of both Chinese Yangtze River Delta suppliers and South Korean cell manufacturers. Battery pack assembly draws from lithium carbonate processed in China, copper foil from Japan, and power electronics from Taiwan. Single-source vulnerability concentrates in Chinese lithium refining capacity, exposing downstream OEMs to quota-driven supply rationing. Distribution runs through electrical contractor networks for stationary systems and outdoor retail partnerships for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential solar generators constitute a late-cycle quality story as California NEM 3.0 and Germany EEG 2023 reforms shift buyer calculus toward decade-long warranty compliance and installer-certified commissioning over lowest-first-cost procurement.
For Market Incumbents: Deploy dealer network control as the primary defensive lever. Generac Power Systems exemplifies cross-selling solar-battery bundles through existing standby generator relationships in hurricane-prone counties. Incumbents should deepen backward integration into lithium iron phosphate cell supply and accelerate UL 9540A certification investment to extend product launch timelines that deter fast-follower competition. Natural gas generator substitution in Gulf Coast markets represents the persistent threat requiring islanding inverter capability as counter-positioning. For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for software-defined energy arbitrage specialists to capture wholesale market participation revenue streams. Victoria Home Battery Subsidy programs in Australia present the most penetrable white-space target for 10+ kWh system entrants. New players should pursue modular expansion architectures as the go-to-market angle, enabling incremental capacity scaling without inverter replacement that incumbent electrical contractors struggle to match. For Investors and Strategic Acquirers: Legacy standby generator manufacturers are the most active acquirer in this space, seeking solar-battery capabilities to offset fossil fuel revenue decline. Long-term viability centers on 10-year warranty service infrastructure and grid-forming inverter commissioning expertise rather than hardware margin capture. Acquisition targets should display CEC accreditation in Australia or SGIP program compliance in California as regulatory moats. The signal to watch is attachment rate divergence between storage-paired solar and generator-only backup in California SCE and SDG&E territories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Supply | Captive lithium iron phosphate supply insulates against Chinese quota rationing and secures 10-year warranty compliance. |
| Modular Expansion Architecture Development | Stackable battery packs without inverter replacement enable incremental revenue capture as household loads grow. |
| Grid-Forming Inverter Certification Investment | UL 1741 SA compliance unlocks California SGIP incentives and FERC Order 2222 wholesale market participation. |
| Direct-to-Consumer Channel Expansion | E-commerce and outdoor retail partnerships bypass 6-18 month utility interconnection timelines slowing contractor sales. |
| Software-Defined Energy Arbitrage Platform | Aggregation algorithms transform residential storage into wholesale market revenue streams beyond self-consumption savings. |
Research Methodology
Coverage spans the United States, Germany, Australia, and China, with primary inputs from each market combining interviews with electrical contractor network managers, battery system installers, utility interconnection officers, and direct-to-consumer brand marketing executives. Secondary validation draws from FERC filings, California Public Utilities Commission regulatory dockets, Clean Energy Council accreditation databases, and MIIT dual carbon policy disclosures. Bottom-up installation volume estimates triangulate against top-down battery cell shipment data.
Granularity-level modeling operates at product type, capacity range, installation geometry, and end-user archetype dimensions across the projection horizon. CAGRs derive from segmented growth rate reconciliation against macro renewable penetration assumptions. Forecast inputs incorporate NEM 3.0 export rate compression effects, EEG 2023 battery storage exemption uptake, and Victoria state subsidy program budget exhaustion trajectories.
Revisions become necessary when lithium carbonate processing quota restrictions intensify, interconnection backlog timelines extend beyond 18 months, or natural gas generator cost advantages erode in hurricane-prone counties. Deviation in California storage attachment rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.