
 Air Cooled Turbo Generators Market | 2026-2036
Air Cooled Turbo Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cooled Turbo Generators Market Analysis
The EU Green Deal is recalibrating the cost-of-entry calculus for air cooled turbo generator manufacturers across Europe. Siemens Energy leverages its technology leadership in direct drive systems to anchor premium positioning in utility-scale installations. General Electric sustains manufacturing scale advantages through integrated supply chains in North America. Mitsubishi Heavy Industries competes on thermal efficiency improvements in gas turbine generator sets.
Air cooled turbo generators are synchronous machines rated typically from 10 MVA to 300 MVA that use forced air circulation rather than hydrogen or water for rotor and stator cooling, enabling simpler maintenance and eliminating explosion risks in enclosed facilities. Their primary purpose is converting mechanical shaft power from prime movers into grid-synchronized electrical output for baseload and peaking power applications. Gas turbine generator sets command the largest revenue pool among product types due to distributed power growth, while data center end users represent the fastest-expanding demand segment driven by hyperscale facility construction. Combined cycle technology captures margin concentration through higher efficiency thresholds that justify premium equipment pricing.
The EPA enforces emissions standards that indirectly shape generator efficiency requirements in US power infrastructure. EMA and CE marking frameworks govern equipment safety and electromagnetic compatibility for European grid connection. China's MEE implements dual carbon goals that tighten thermal performance benchmarks for new generator installations. Stakeholders must monitor evolving efficiency mandates and cooling technology roadmaps to align capital allocation with regulatory trajectories.
Market Dynamics
The EU Green Deal is compressing thermal efficiency thresholds for air cooled turbo generators, forcing manufacturers to redesign rotor cooling architectures and thermal management systems to maintain grid connection eligibility across European markets.
Growth Catalysts
- Hyperscale Data Center Construction:Facility operators in Germany, China, and the United States are specifying air cooled units for on-site power redundancy, eliminating hydrogen explosion risks in enclosed server halls.
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation is accelerating abandonment of fluorinated coolant-dependent systems, redirecting capital toward forced-air synchronous machine platforms.
- Distributed Generation Mandates:China's MEE dual carbon goals are requiring thermal performance upgrades at industrial cogeneration sites, expanding addressable demand for gas turbine generator sets.
Market Restraints
- Copper and Electrical Steel Volatility:Stator core laminations and rotor windings depend on commodity metal inputs subject to supply concentration in Chilean copper and Chinese silicon steel.
- Technical Thermal Ceiling:Air cooling imposes hard limits on power density above 300 MVA, constraining unit scalability for utility-scale baseload applications.
- CE Marking Compliance Friction:Electromagnetic compatibility certification under EMA frameworks extends lead times for non-European manufacturers seeking European grid connection.
Strategic Opportunities
- Modular Data Center Microgrids:Edge computing facility operators in the United States are procuring containerized generator sets for rapid deployment at greenfield sites.
- Combined Cycle Efficiency Convergence:Integration of advanced blade coatings with air cooled generator platforms is opening premium pricing tiers for heat recovery applications.
- India PLI Scheme Alignment:Domestic manufacturing incentives for power equipment are creating localized assembly pathways for multinational generator suppliers.
Industry Challenges
- Specialized Winding Technician Scarcity:Rotor rewind and stator reconditioning require craft skills concentrated in aging workforce pools across Midwestern US and German industrial regions.
- IEC 60034 Certification Timelines:Type testing for efficiency class verification extends product launch cycles, compressing competitive response windows.
- Legacy Hydrogen-Cooled System Integration:Retrofit compatibility with existing turbine hall infrastructure demands custom engineering for each brownfield installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cooled Turbo Generators Market |
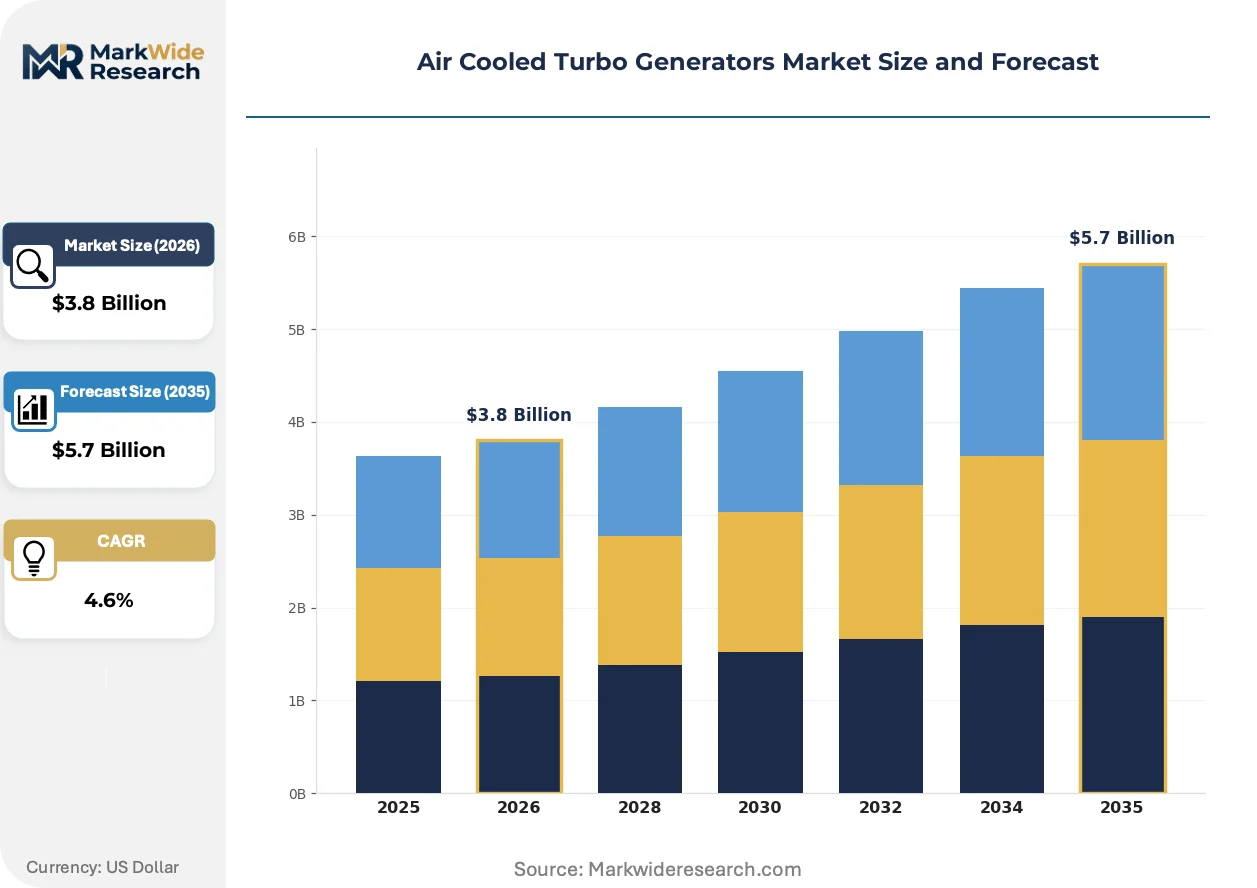
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbines, Gas Turbines, Hydro Turbines, Capstone Turbines End User: Power Plants, Industrial Facilities, Data Centers, Marine Applications Installation: Onshore, Offshore, Hybrid, Modular Technology: Direct Drive, Indirect Drive, Combined Cycle, Single Cycle |
| Companies Covered | ANDRITZ Group, Shanghai Electric Group, Siemens Energy, Fuji Electric, Harbin Electric International Company Limited, General Electric, Ansaldo Energia, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cooled Turbo Generators Market Emerging Trajectories
Forced-air thermal management architectures are displacing liquid and hydrogen cooling in enclosed industrial environments, while regulatory efficiency mandates and buyer procurement consolidation are restructuring competitive priorities across the supply base.
Direct drive permanent magnet generator technology is rewriting power conversion economics for distributed gas turbine applications. Data center operators are specifying these units for combined heat and power integration at hyperscale campuses. The elimination of gearbox maintenance intervals is compressing total cost of ownership calculations against conventional synchronous alternatives.
The EU Green Deal's efficiency benchmarks are mandating thermal performance disclosures for generator cooling systems above 10 MVA. Manufacturers must now submit verified loss calculations under standardized load profiles to maintain CE marking eligibility. German utility procurement teams are prioritizing suppliers with documented compliance trajectories ahead of 2030 tightening cycles.
Buyer consolidation among hyperscale cloud providers is concentrating specification authority with engineering teams at Amazon Web Services, Microsoft, and Google. These operators are unbundling aftermarket service contracts from initial equipment procurement, forcing generator OEMs to compete on unit price while surrendering long-term maintenance revenue streams. This pattern is most visible in Northern Virginia and Frankfurt data center clusters.
Air Cooled Turbo Generators Market Segmentation
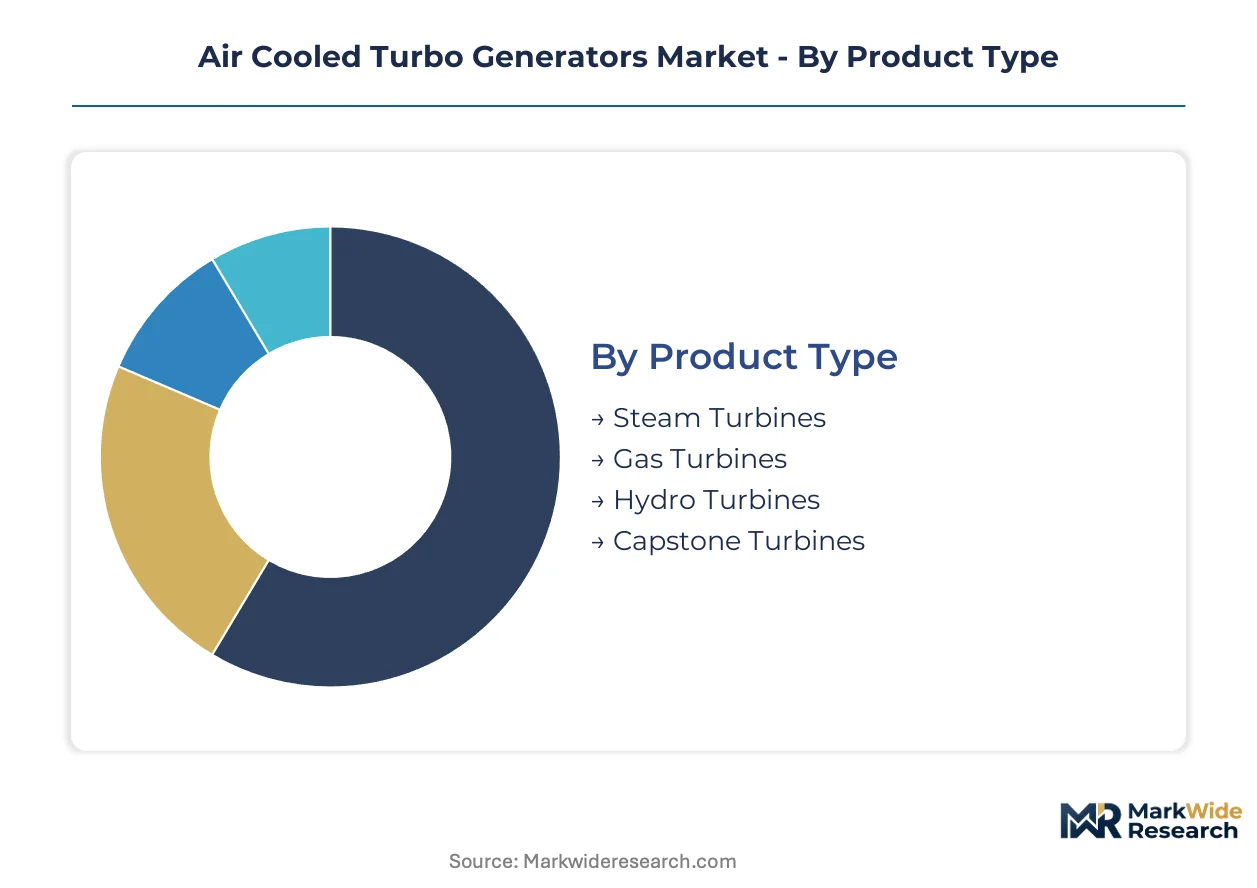
Segmentation in air cooled turbo generators determines procurement economics and thermal performance boundaries. Capital allocation, maintenance intervals, and regulatory compliance all vary sharply across product configurations and deployment contexts.
Product Type:
Capital intensity peaks with steam turbine generator sets requiring precision-machined casings and superalloy rotor forgings, while gas turbine platforms achieve faster payback through modular construction.
- Gas Turbines:These synchronous machines pair with aeroderivative or industrial gas turbines in distributed power and CHP configurations. Demand concentrates in German industrial cogeneration sites and Chinese MEE-mandated efficiency upgrades, driven by shorter installation timelines and lower civil works requirements than steam alternatives.
- Steam Turbines:High-inertia rotor designs with forged alloy steel components handle baseload duty cycles. Utility procurement in the United States focuses on these units for combined cycle repowering projects, constrained by extended lead times for specialized forging capacity.
- Hydro Turbines:Run-of-river and pumped storage applications in alpine regions.
- Capstone Turbines:Microturbine-scale units for commercial building CHP.
Most installed capacity flows through Gas Turbines. Expansion is steepest in Capstone Turbines.
End User:
Customer scale and redundancy requirements fragment pricing power across the value chain, with hyperscale operators extracting volume discounts unavailable to industrial buyers.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt clusters specify air cooled units for on-site generation, eliminating hydrogen safety protocols in enclosed server halls. AWS, Microsoft, and Google engineering teams unbundle service contracts from equipment procurement, compressing OEM margins.
- Power Plants:Grid-synchronized baseload and peaking installations dominate unit shipments by megawatt capacity. German utility procurement under EU Green Deal efficiency benchmarks prioritizes suppliers with verified loss calculations.
- Industrial Facilities:Cogeneration and process steam applications in chemical and refining sectors.
- Marine Applications:Naval and commercial vessel propulsion and auxiliary power.
Power Plants anchor current revenue. Data Centers are gaining share fastest.
Installation:
Site preparation and grid connection timelines vary by an order of magnitude between permanent onshore foundations and containerized modular deployments.
- Onshore:Permanent civil foundations with fixed transformer yards and switchgear enclosures. German grid code compliance and CE marking requirements extend commissioning schedules for brownfield turbine hall retrofits.
- Modular:Containerized generator sets with integrated cooling and control systems enable rapid deployment at greenfield data center sites in the United States. Edge computing operators procure these units for 90-day installation cycles.
- Offshore:Platform-mounted units for oil and gas and emerging wind integration.
- Hybrid:Dual-fuel or battery-integrated configurations for flexibility services.
Onshore foundations carry the greatest cumulative megawatts. Modular formats show the steepest expansion trajectory.
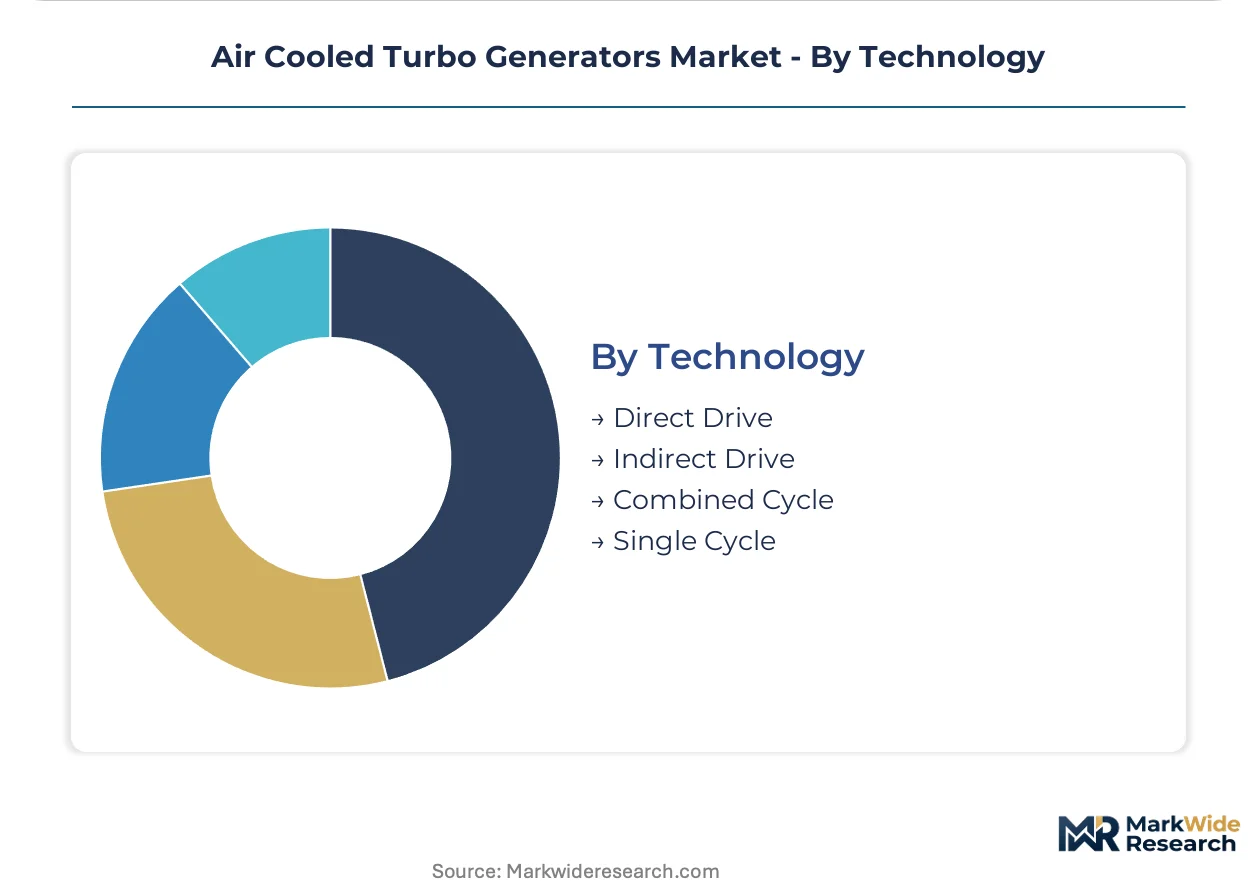
Technology:
Drive architecture and thermodynamic cycle selection determine efficiency ceilings, maintenance intervals, and integration complexity with prime movers.
- Combined Cycle:Heat recovery steam turbine integration with gas turbine exhaust captures margin concentration through premium pricing justified by efficiency thresholds above 60%. Advanced blade coatings paired with air cooled generators open new application tiers.
- Direct Drive:Permanent magnet generators eliminate gearbox maintenance and compress total cost of ownership calculations against conventional synchronous alternatives. Data center CHP integration in hyperscale campuses drives specification.
- Indirect Drive:Geared speed matching between turbine and generator maintains established maintenance protocols.
- Single Cycle:Simple gas turbine generator configurations for peaking and emergency power.
Combined Cycle commands premium pricing tiers. Direct Drive is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The air cooled turbo generator industry traces its commercial scaling to German engineering traditions in synchronous machine design, with subsequent capacity expansion across North American utility infrastructure and Chinese state-directed power equipment manufacturing.
Germany
Industrial cogeneration sites in the Ruhr and Bavaria drive replacement demand for gas turbine generator sets. The EU Green Deal tightens thermal efficiency disclosure requirements above 10 MVA, forcing verified loss calculations for CE marking retention. Frankfurt data center clusters specify air cooled units for on-site redundancy, eliminating hydrogen protocols in enclosed server halls.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth procure modular generator sets for 90-day deployment cycles. EPA emissions standards indirectly shape generator efficiency requirements for grid-synchronized installations. Midwestern industrial regions face specialized winding technician scarcity, compressing rotor rewind capacity for brownfield turbine hall retrofits.
China
MEE dual carbon goals mandate thermal performance upgrades at industrial cogeneration facilities, expanding addressable demand for efficiency-class generator sets. Yangtze River Delta manufacturing hubs concentrate silicon steel lamination capacity for stator core production. State-owned procurement channels prioritize domestic assembly pathways under equipment localization directives.
India
PLI scheme incentives for power equipment manufacturing create localized assembly pathways for multinational generator suppliers. CEA grid code compliance requirements shape specification standards for utility-scale installations. Gujarat and Maharashtra industrial corridors drive cogeneration demand from chemical and refining sector expansions.
Japan
Gas turbine generator integration with combined cycle configurations captures premium pricing in efficiency-sensitive utility procurement. METI energy security frameworks prioritize domestic grid infrastructure resilience. Kansai region manufacturing maintains precision forging capacity for high-inertia rotor components in baseload applications.
Air Cooled Turbo Generators Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive power equipment divisions. Siemens Energy and General Electric anchor consolidated positions through integrated supply chains and direct drive technology portfolios. Three archetypes dominate: European engineering conglomerates with utility-scale project execution capabilities, East Asian diversified industrials with thermal efficiency specialization, and state-affiliated Chinese manufacturers with cost-optimized production platforms. Capacity expansion and strategic technology licensing represent the primary competitive vectors, with OEMs repositioning around unbundled service contract economics.
Among European engineering conglomerates, Siemens Energy AG exemplifies the premium-tier positioning anchored in direct drive permanent magnet systems. General Electric Company occupies the scale-driven archetype with North American manufacturing integration. Mitsubishi Heavy Industries, Ltd. represents the thermal efficiency specialization vector within East Asian industrial diversification structures.
| Leading Market Players |
|---|
| ANDRITZ Group |
| Shanghai Electric Group |
| Siemens Energy |
| Fuji Electric |
| Harbin Electric International Company Limited |
| General Electric |
| Ansaldo Energia |
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper price volatility cascades through stator core lamination costs, compressing margins for mid-tier synchronous machine manufacturers while premium-tier suppliers pass through alloy surcharges to German utility and hyperscale data center buyers.
Pricing Analysis
Project-based contract pricing with indexed raw material adjustments dominates utility-scale procurement, separating Siemens Energy and General Electric's integrated cost structures from third-party winding shops facing spot copper exposure. Price differentiation hinges on IEC 60034 efficiency certification tier and bundled aftermarket service tenure. Cost compression in standard-efficiency classes intensifies as Chinese state-owned manufacturers expand export capacity. Industrial cogeneration buyers in Germany exhibit highest price sensitivity, while Frankfurt and Northern Virginia hyperscale operators prioritize rapid deployment over unit economics.
Supply Chain Analysis
Electrical steel supply rests on Yangtze River Delta silicon lamination capacity and Japanese precision rolling mills for high-permeability grades used in direct drive permanent magnet rotors. Copper rod drawing for stator windings draws from Chilean concentrate and Chinese smelter output. Single-source vulnerability concentrates in specialized forging capacity for high-inertia steam turbine rotors, concentrated in Kansai region and Midwestern US facilities. Distribution runs through OEM-direct channels for utility projects and EPC contractor integration for modular data center deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between Chinese state-subsidized silicon steel production and EU carbon border adjustment mechanisms creates geographic positioning incentives for generator OEMs restructuring supply footprints.
For Market Incumbents: Cement technology leadership in direct drive permanent magnet architectures through captive rare earth magnet supply agreements, defending against emerging Chinese manufacturers with state-backed vertical integration. Prioritize IEC 60034-2-3 efficiency test certification investment to maintain CE marking eligibility under EU Green Deal tightening cycles.
For New Entrants and Emerging Players: EPC contractors serving modular data center microgrid deployments represent the most accessible channel partnership for bypassing incumbent OEM service bundling. Target containerized generator set specifications for edge computing greenfield sites in secondary US markets, penetrating through 90-day deployment speed advantages against legacy onshore foundation timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap winding specialists possessing rotor rewind craft capabilities in German industrial regions, as specialized technician scarcity creates consolidation value. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for forced-air synchronous machine substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Captive neodymium procurement from Chinese state-owned miners secures direct drive generator cost position. |
| Modular Container Platform Launch | Integrated cooling and control systems enable 90-day deployment cycles for hyperscale data center operators. |
| IEC 60034-2-3 Certification Investment | Verified loss calculation capability maintains CE marking eligibility under EU Green Deal efficiency mandates. |
| Rotor Rewind Service Capability Acquisition | Specialized winding technician pools in German and Midwestern US regions address craft skill scarcity. |
| Combined Cycle Integration Partnership | Advanced blade coating pairing with air cooled generators opens premium pricing tiers for heat recovery applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with power plant engineering directors, data center facility operators, EPC procurement leads, and aftermarket service managers with secondary validation against EIA generation capacity data, IEA power equipment forecasts, FERC interconnection queue filings, and customs trade records for electrical steel and copper winding imports. Bottom-up unit shipment modeling and top-down utility capex allocation analysis were cross-referenced for triangulation.
Segment-weighting applied product type, end user, installation format, and technology architecture dimensions across the projection horizon. CAGRs were derived from regression analysis of historical utility procurement cycles and hyperscale facility construction pipelines. Forecast inputs incorporated EU Green Deal implementation timelines, MEE dual carbon goal enforcement trajectories, and EPA emissions standard revision schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export restriction policies, copper concentrate supply disruptions, and IEC efficiency class recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity price mean reversion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Subsea Power Grid System Market
Power Generation
Algeria Power Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Captive Power Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Distributed Generation Market
Power Generation
South East Asia Power Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Peaking Power Plant Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Stirling Engine Market
Power Generation
Distributed Power Generation Market
Power Generation
India Gas Generator Market
Power Generation
Global Gensets Market
Power Generation
Europe Distributed Power Generation Market