
 Algeria Power Market | 2026-2036
Algeria Power Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Power Market Outlook
Single-source procurement of gas turbine equipment is consolidating into multi-source frameworks as Algerian utilities diversify vendor relationships. Sonelgaz anchors domestic distribution through its monopoly over transmission and retail networks. Siemens Energy competes on large rotating equipment for combined-cycle expansions at Hassi R'Mel and Skikda. Eni Spa leverages its upstream gas position to secure long-term fuel supply agreements tied to power offtake.
Algeria power encompasses electricity generation, transmission, and distribution infrastructure spanning thermal plants exceeding 400 MW unit capacity and renewable installations from kilowatt-scale residential solar to utility photovoltaic arrays. The system serves industrial smelting, desalination, residential cooling, and rural irrigation across a territory where peak demand exceeds twelve gigawatts seasonally. Conventional thermal generation dominates installed capacity while solar technology captures the fastest expansion trajectory under Algeria's renewable energy program. Industrial application commands the largest margin pool due to interruptible tariff structures and direct bilateral contracting with Sonelgaz.
Algeria's Ministry of Energy and Mines sets capacity targets through five-year investment plans while the national electricity and gas regulatory commission oversees tariff methodology and independent power producer licensing. The country's renewable energy agency implements auction rounds and grid connection standards that determine project bankability for private developers. Stakeholders must monitor regulatory clarity on gas-to-power transition timelines and the pace of renewable auction allocation to align capital deployment with offtake certainty.
Market Dynamics
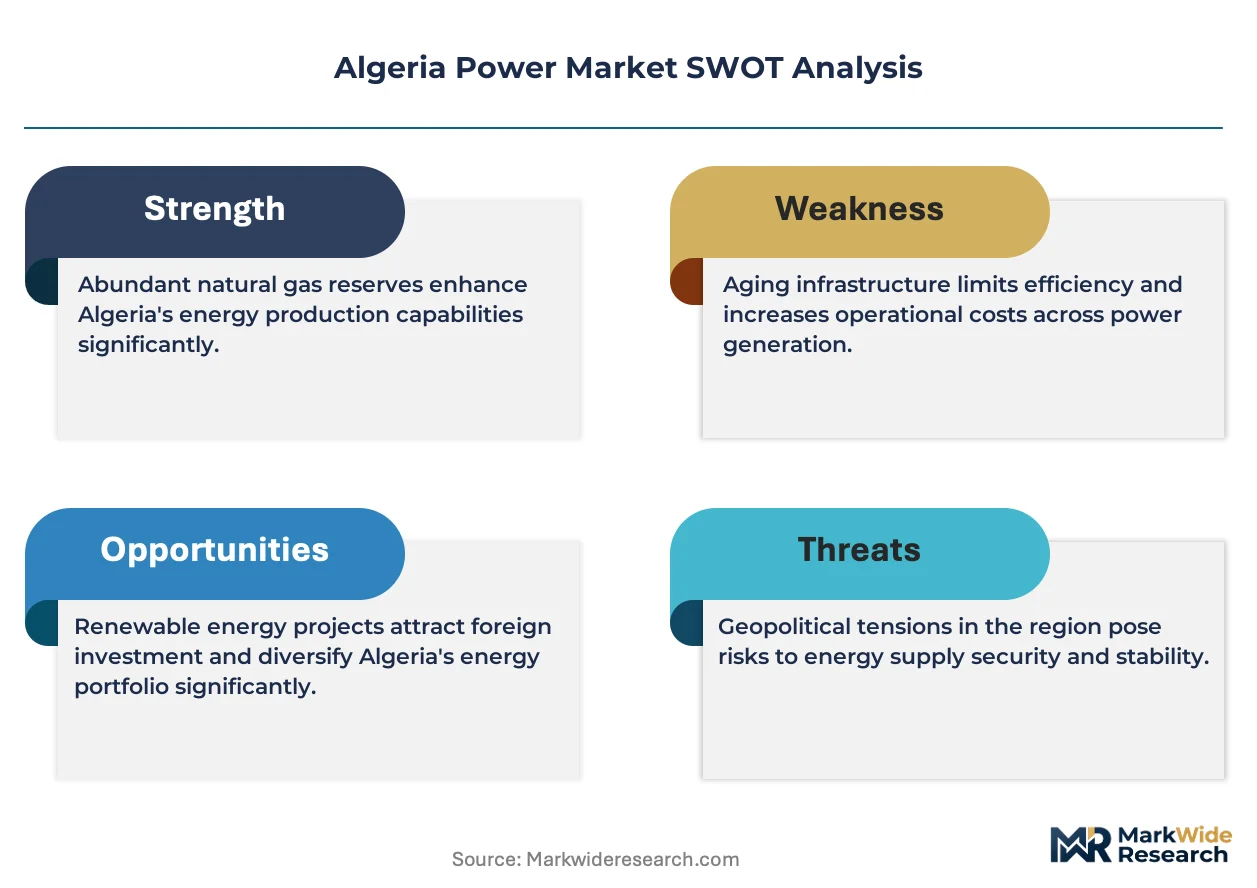
Sonelgaz's monopoly over transmission and retail networks concentrates dispatch authority while the Ministry of Energy and Mines redirects investment toward solar PV auctions under Algeria's renewable energy law.
Growth Catalysts
- Feed-in tariff revisions:Algeria's renewable energy agency implemented auction rounds that improve project bankability for private developers in Adrar and the High Plateaus.
- Industrial load expansion:Smelting and desalination facilities in Hassi Messaoud and Arzew absorb new combined-cycle capacity from Sonatrach-linked gas fields.
- Grid infrastructure:Existing transmission corridors along the northern coastal belt reduce connection costs for utility-scale solar installations.
Market Restraints
- Gas supply concentration:Dependence on Sonatrach-operated fields for combined-cycle fuel creates single-source vulnerability.
- Land access friction:Bureaucratic allocation procedures for desert solar sites delay project commissioning timelines.
- Currency convertibility:Dinar repatriation restrictions raise financing costs for international developers.
Strategic Opportunities
- Hybrid plant architectures:Solar-plus-storage configurations at Adrar offer frequency regulation services to the national grid.
- Rural electrification:Kilowatt-scale residential solar addresses irrigation loads in southern provinces beyond transmission reach.
- Green hydrogen export:Renewable power-to-gas projects leverage Algeria's pipeline infrastructure toward European offtake.
Industry Challenges
- Grid code compliance:Connection standards for inverter-based generation require specialized engineering capabilities scarce in local labor markets.
- Equipment procurement lead times:Multi-source frameworks for gas turbine parts extend spare parts availability windows.
- Legacy dispatch protocols:Thermal plant operating procedures conflict with variable renewable integration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Power Market |
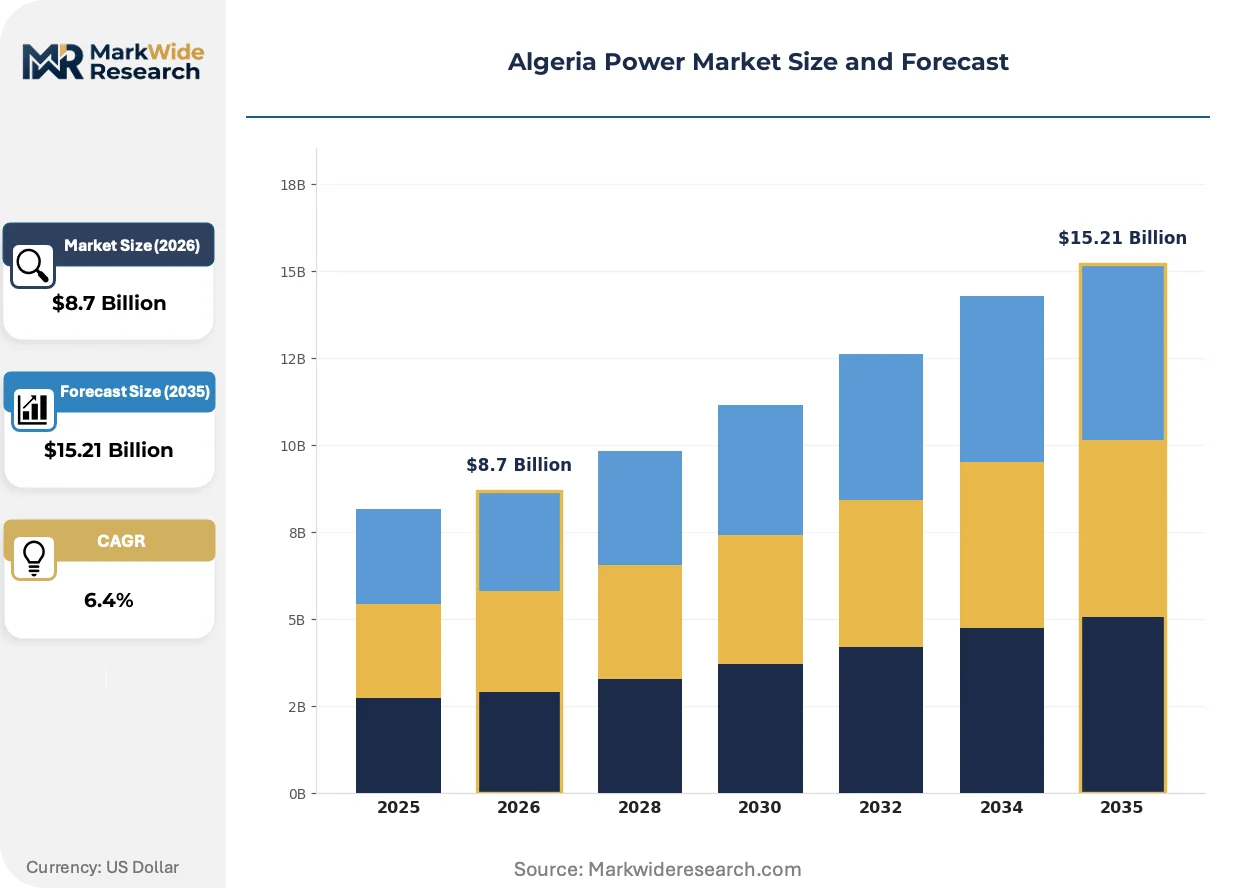
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Renewable, Hybrid, Distributed Application: Residential, Commercial, Industrial, Agricultural Technology: Solar, Wind, Gas Turbine, Hydropower End User: Utilities, Private Sector, Government, Non-Profit |
| Companies Covered | Eni Spa, Siemens Energy, Sonelgaz, SOLIWIND Algérie Sarl, Condor Electronics SPA, General Electric Company, TotalEnergies, Schneider Electric, Sonatrach, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Power Market Strategic Shifts
Digitalization of asset management and modular plant design are compressing development cycles while policy instruments redirect capital toward low-carbon generation.
Hybrid inverter technology is unifying solar PV and battery storage control into single hardware platforms. Industrial offtakers in Hassi Messaoud are adopting these integrated systems to manage interruptible tariff exposure. The technology is unifying procurement decisions that previously separated generation and flexibility assets.
Algeria's renewable energy law established auction mechanisms that replace administratively set tariffs with competitive price discovery. Independent power producers now bid capacity blocks against grid connection guarantees. Developers with existing land positions in Adrar capture preferential allocation under the new framework.
Direct bilateral contracting is displacing standardized Sonelgaz tariffs for large industrial loads. Smelters and desalination plants negotiate interruptible supply agreements with embedded price caps. This pattern concentrates in the northern coastal belt where manufacturing density supports volume commitments.
Algeria Power Market Segmentation
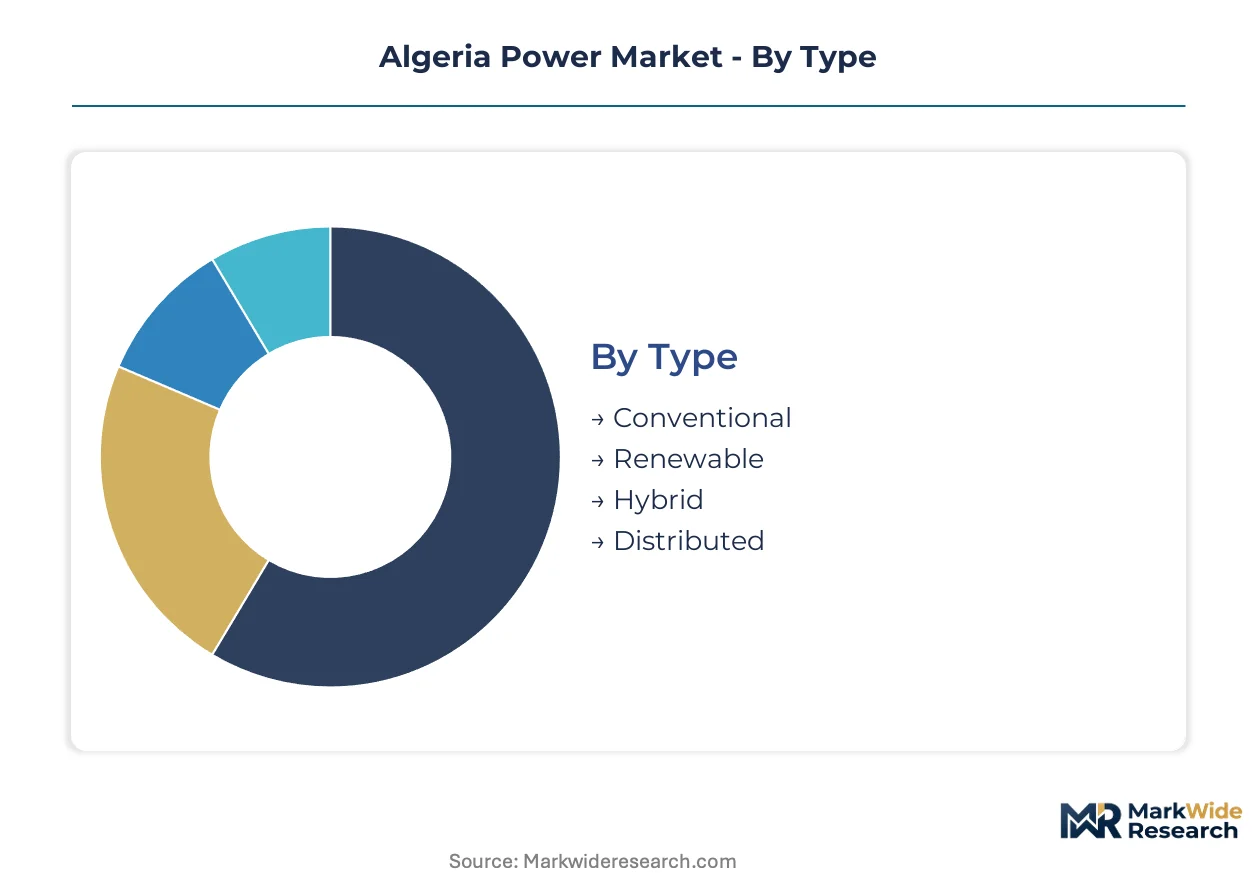
Segmentation reveals how Algeria's power infrastructure serves divergent load profiles across its coastal industrial belt and southern desert provinces. Technology choices and customer types determine capital intensity, fuel exposure, and regulatory treatment under the renewable energy law.
Type:
Asset replacement cycles favor technologies with shorter construction timelines and lower fuel price exposure.
- Conventional:Combined-cycle gas turbines exceeding 400 MW dominate baseload supply, drawing fuel from Sonatrach-linked fields at Hassi R'Mel. Hassi Messaoud and Arzew industrial zones absorb the bulk of this dispatch due to interruptible tariff structures and direct bilateral contracting.
- Renewable:Utility-scale solar PV arrays in Adrar and wind clusters along the High Plateaus capture the fastest capacity additions under revised feed-in tariffs. Grid connection guarantees and competitive auction rounds improve bankability for independent power producers.
- Hybrid:Solar-plus-storage configurations integrate generation and frequency regulation into single asset platforms. These systems address grid code compliance requirements for inverter-based resources while serving industrial offtakers seeking tariff stability.
- Distributed:Kilowatt-scale residential installations extend electrification to southern provinces beyond transmission reach. Rural irrigation loads and remote settlements drive deployment where centralized infrastructure proves uneconomical.
Volume placements concentrate in Conventional generation; the faster expansion belongs to Renewable installations.
Application:
Load characteristics determine tariff structures and dispatch priority within Sonelgaz's monopoly network.
- Residential:Northern coastal belt concentration aligns with existing transmission infrastructure and cooling-driven peak demand. Subsidized tariffs and universal service obligations shape investment returns for distribution upgrades.
- Commercial:Retail and service loads in urban centers exhibit daytime peak profiles that match solar generation curves. Building-integrated PV and demand response programs reduce exposure to Sonelgaz's standardized rates.
- Industrial:Smelting and desalination facilities command the largest margin pool through interruptible supply agreements. Direct bilateral contracting with embedded price caps displaces regulated tariffs for volume commitments.
- Agricultural:Irrigation pumping in southern provinces operates beyond grid reach, favoring distributed diesel-solar hybrid systems. Seasonal load patterns and remote location drive technology selection toward modular, rapidly deployable assets.
Industrial applications generate the highest revenue per megawatt-hour; Agricultural electrification is climbing the fastest as grid extension lags behind demand.
Technology:
Equipment procurement strategies diverge between mature thermal platforms and emerging renewable systems.
- Solar:Photovoltaic technology captures the steepest expansion trajectory under Algeria's renewable energy program. Adrar's high irradiance and available land positions attract auction allocation for utility-scale parks.
- Wind:High Plateaus wind resources support clustered development with capacity factors competitive with coastal thermal plants. Grid integration challenges and specialized engineering requirements constrain deployment pace.
- Gas Turbine:Large rotating equipment for combined-cycle expansions at Hassi R'Mel and Skikda anchors baseload reliability. Multi-source procurement frameworks replace single-vendor dependence for spare parts availability.
- Hydropower:Existing reservoir infrastructure in northern mountain zones provides peaking capacity and grid stability services. Limited undeveloped sites restrict growth potential relative to solar and wind alternatives.
Gas Turbine capacity retains the largest installed base; Solar technology is gaining share fastest under renewable auction mechanisms.
End User:
Customer type determines offtake structure, credit risk profile, and regulatory oversight intensity.
- Utilities:Sonelgaz's monopoly over transmission and retail networks concentrates dispatch authority and tariff-setting power. Five-year investment plans from the Ministry of Energy and Mines direct capital allocation across generation technologies.
- Private Sector:Independent power producers participate through auction rounds for renewable capacity blocks. Land access and grid connection guarantees determine project bankability under the new regulatory framework.
- Government:Public institutions and state-linked enterprises secure priority grid access and favorable payment terms. Military and administrative loads in remote locations drive distributed generation procurement.
- Non-Profit:Rural electrification cooperatives and development agencies deploy small-scale systems beyond commercial viability thresholds. Grant financing and concessional lending address affordability constraints in underserved provinces.
Utilities absorb the majority of generation output; Private Sector participation is expanding most quickly under independent power producer licensing reforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hassi R'Mel gas fields anchor Algeria's generation geography, feeding combined-cycle plants that dispatch across the northern coastal belt. Sonelgaz's transmission monopoly concentrates load centers in Algiers, Oran, and Annaba while southern provinces remain beyond grid reach. Sub-regional disparities in fuel access, irradiance, and industrial density shape divergent investment priorities.
Algiers-Tipaza Coastal Corridor
Cooling-driven peak demand and manufacturing density concentrate grid investment along this central littoral zone. The Ministry of Energy and Mines directs five-year capacity targets toward serving urban load growth. Hydropower peaking reservoirs in the Blidean Atlas provide frequency regulation for the capital region's industrial smelters.
Oran-Mostaganem Industrial Zone
Desalination facilities and petrochemical complexes absorb interruptible supply agreements with embedded price caps. Sonelgaz's transmission infrastructure here supports direct bilateral contracting that displaces standardized retail tariffs. Arzew's LNG export terminals create competing gas demand that tightens fuel allocation for local power generation.
Hassi Messaoud-Ourgla Oil Basin
Sonatrach-linked gas fields feed combined-cycle expansions serving upstream petroleum operations and sulfur recovery plants. The 2023 renewable energy law auction mechanisms allocate solar PV blocks to developers with established land positions in adjacent desert zones. Grid connection guarantees remain contingent on transmission buildout northward toward coastal load centers.
Adrar-Timimoun Solar Belt
High irradiance and available desert land positions attract utility-scale photovoltaic deployment under revised feed-in tariffs. Land access friction through bureaucratic allocation procedures delays commissioning timelines for independent power producers. Kilowatt-scale residential installations address irrigation loads beyond centralized infrastructure reach.
High Plateaus Wind Corridor
Consistent wind resources support clustered development with capacity factors competitive with coastal thermal plants. Specialized engineering capabilities for grid code compliance remain scarce in local labor markets, constraining deployment pace. Rural electrification cooperatives deploy small-scale hybrid systems for agricultural pumping in remote settlements.
Algeria Power Market Competitive Environment
Strategic partnerships dominate the current landscape as international equipment vendors align with state-linked fuel suppliers and domestic utilities. The market structure concentrates around Sonelgaz's monopoly over transmission and retail networks, with independent power producers contesting renewable auction rounds. Two archetypes prevail: integrated energy conglomerates leveraging upstream gas positions, and specialized technology providers competing on rotating equipment and grid infrastructure. Portfolio diversification and multi-source procurement frameworks represent the dominant competitive moves, displacing earlier single-vendor dependence.
Within the state-linked utility tier, Sonelgaz and Sonatrach occupy positions that concentrate dispatch authority and fuel supply control. Among international technology providers, Siemens Energy and General Electric Company exemplify the large rotating equipment archetype competing for combined-cycle expansions. Schneider Electric represents the grid infrastructure specialist segment, anchoring transmission and distribution technology supply. These named entities illustrate how vendor relationships are diversifying across multi-source frameworks rather than consolidating around exclusive partnerships.
| Leading Market Players |
|---|
| Eni Spa |
| Siemens Energy |
| Sonelgaz |
| SOLIWIND Algérie Sarl |
| Condor Electronics SPA |
| General Electric Company |
| TotalEnergies |
| Schneider Electric |
| Sonatrach |
| Others |
Value Chain & Pricing Dynamics
Industrial offtakers in Hassi Messaoud and Arzew anchor pricing power through direct bilateral contracting that displaces Sonelgaz's standardized retail tariffs. This buyer concentration forces equipment vendors to unbundle long-term service agreements from capital equipment sales.
Pricing Analysis
Extended warranty and spare parts availability are unbundled from gas turbine capital sales as Algerian utilities adopt multi-source procurement frameworks. Pricing stratifies across premium OEM service tiers, mid-tier regional contractors, and economy refurbishment options based on grid code compliance certification and fuel efficiency guarantees. Cost compression in the renewable EPC segment is intensifying because international developers face dinar repatriation restrictions that raise financing spreads. Agricultural electrification projects exhibit highest price sensitivity due to grant-dependent procurement, while industrial smelters demonstrate lowest sensitivity through interruptible supply agreements with embedded price caps.
Supply Chain Analysis
Regional distribution centers in Algiers and Oran operate hub-and-spoke patterns for rotating equipment parts, with satellite stocking points at Hassi R'Mel and Skikda. Manufacturing draws from Germany, Italy, and China for gas turbine components, while solar PV modules source from Chinese and Southeast Asian cell fabs. The supply chain rests on polysilicon and rare earth magnet dependencies for renewable and conventional generation respectively. Single-source vulnerability concentrates in Sonatrach-operated gas fields that feed combined-cycle plants. Distribution runs through Sonelgaz's monopoly transmission network to coastal load centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over fuel supply agreements and grid connection guarantees determines project bankability. Players are pursuing upstream fuel security and downstream dispatch authority as the decisive levers.
For Market Incumbents: Cement fuel supply dominance by securing long-term Sonatrach offtake contracts tied to power purchase agreements. Expand renewable EPC capabilities through captive engineering subsidiaries to defend against independent power producer entrants. The Ministry of Energy and Mines' auction allocation uncertainty threatens incumbent project pipelines.
For New Entrants and Emerging Players: Capture land access positions in Adrar and Timimoun ahead of grid connection guarantee awards under the renewable energy law. Target the rural electrification segment where kilowatt-scale residential solar operates beyond Sonelgaz's transmission reach. Partner with Algerian engineering firms to satisfy local content requirements in auction bidding.
For Investors and Strategic Acquirers: The window for entry favors hybrid plant developers with integrated storage capabilities. Long-term viability hinges on exposure to green hydrogen export infrastructure toward European offtake. Monitor regulatory clarity on gas-to-power transition timelines as the inflection signal for capital reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Combined-cycle expansions at Hassi R'Mel absorb Sonatrach-linked gas field output. |
| Power Purchase Agreement | Direct bilateral contracts with industrial smelters displace Sonelgaz standardized tariffs. |
| Technology Licensing | Hybrid inverter platforms unify solar PV and battery storage control for grid compliance. |
| Vertical Integration into Storage | Solar-plus-storage configurations at Adrar offer frequency regulation services to Sonelgaz. |
| Green Certification Program | Renewable energy law auction mechanisms reward projects with established land positions. |
Study Parameters
IEA electricity statistics, Sonelgaz regulatory filings, and Algeria's renewable energy agency auction records formed the secondary backbone. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators validated capacity addition timelines and tariff structures. Bottom-up project pipelines were triangulated against top-down Ministry of Energy and Mines five-year investment plans.
Historical trendline analysis of capacity additions and demand growth patterns anchored the analytical framework across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Forecast inputs included solar irradiance data for Adrar and wind resource assessments for the High Plateaus.
The model holds under continued Sonelgaz monopoly transmission authority and renewable auction allocation continuity; deviation in currency convertibility regulations or land access bureaucratic procedures would shift independent power producer participation rates. Forecasts reflect documented assumptions on fuel price trajectories and grid code compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Power Plant EPC Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Commercial Gensets Market
Power Generation
Wind Power EPC Market
Power Generation
Global Power to Gas Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Tunisia Power Market
Power Generation
Venezuela Power Market
Power Generation
Australia Thermal Power Market
Power Generation
Industrial Solar Generator Market
Power Generation
Thermal Power Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Canada Power EPC Market
Power Generation
India Gensets Market