
 Global Tin Market | 2026-2036
Global Tin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tin Market Intelligence
Traceability-as-a-service platforms, which verify conflict-free sourcing and ESG compliance, is expanding the value proposition beyond simple material sales. Yunnan Tin Company leverages its significant scale to supply China's vast electronics sector. Minsur differentiates its operations through a stated focus on sustainable mining practices in Peru, while state-owned PT Timah controls a substantial portion of Indonesia's output.
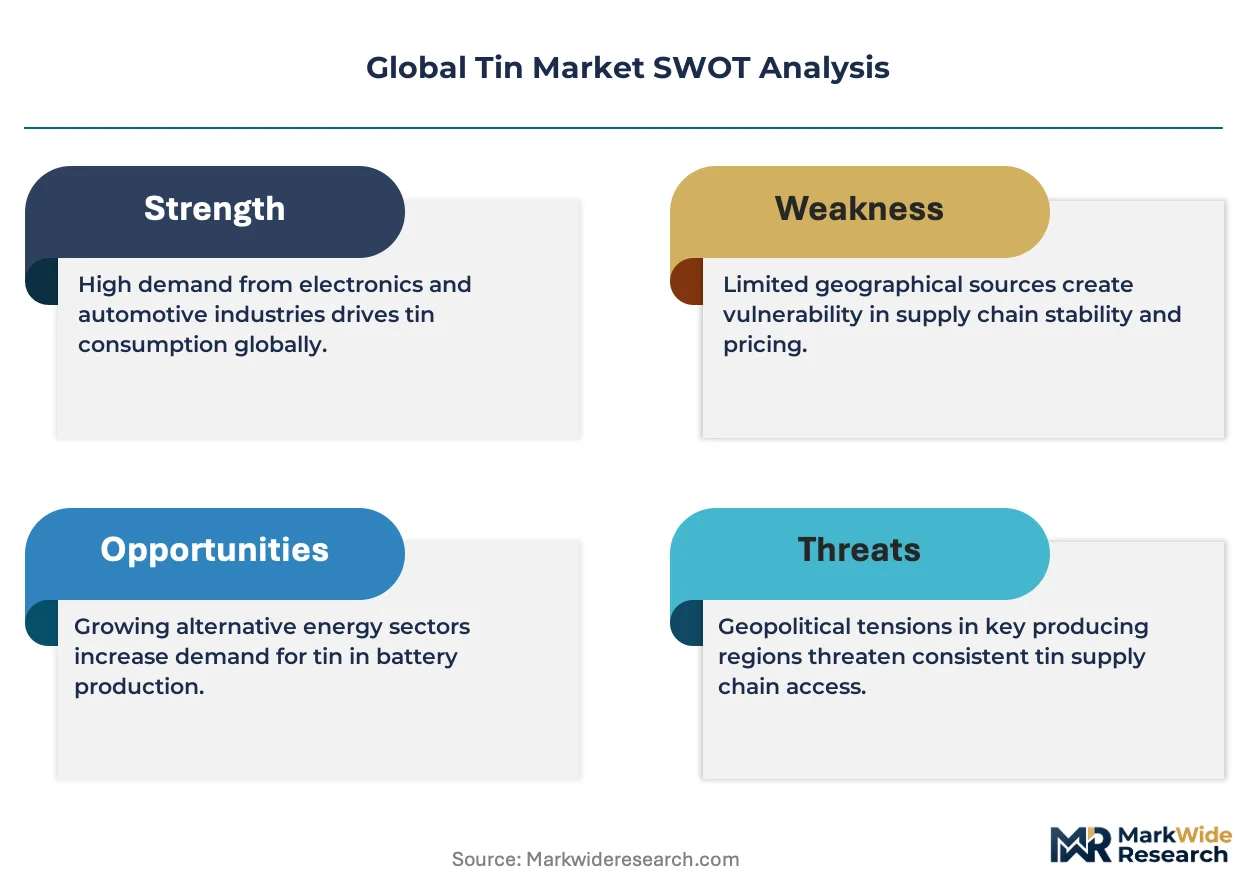
Tin is a soft, malleable, and corrosion-resistant post-transition metal with the atomic number 50. Its low toxicity and ability to bond with other metals make it essential for creating protective coatings and alloys. Soldering for the electronics industry remains the principal application driving overall volume. The refined tin product segment constitutes the bulk of traded material, while tin chemicals represent a higher-margin niche.
Supply chain diligence is fundamentally shaped by legal frameworks like the US Dodd-Frank Act and the EU Conflict Minerals Regulation. In parallel, environmental standards from China's MEE and the EU's RoHS directive govern smelter emissions and final product composition. Navigating these divergent international sourcing and purity standards is a critical strategic challenge for processors and electronics manufacturers.
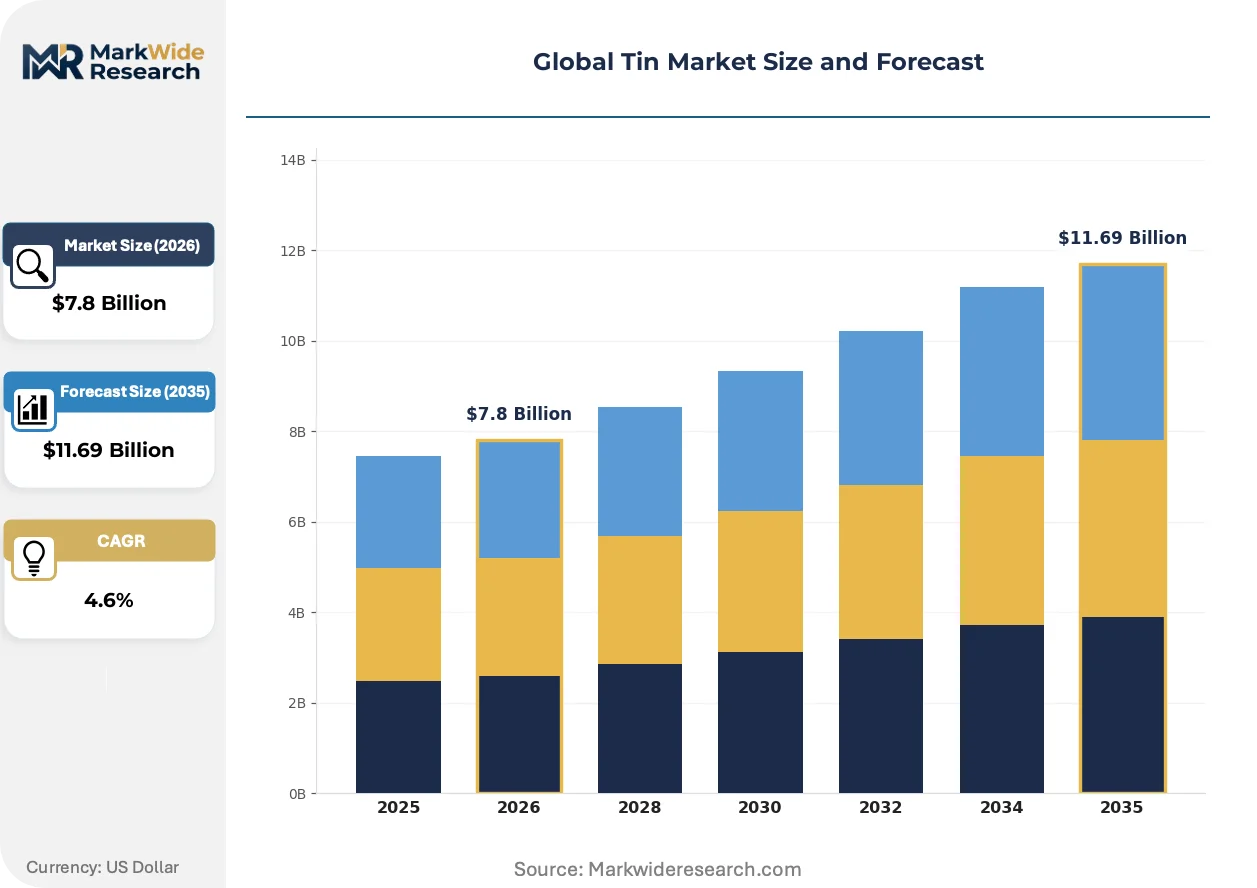
Market Dynamics
The tin market's structure is fundamentally defined by supply chain diligence mandates. Regulations like the US Dodd-Frank Act and the EU Conflict Minerals Regulation impose strict sourcing verification requirements, directly influencing procurement strategies from major producing nations like Indonesia and Peru.
Growth Catalysts
- Regulatory Mandates:The European Union's RoHS directive bans lead in electronics, securing tin's position as the primary component in lead-free solders used globally in printed circuit board assembly.
- Electronics Miniaturization:Continuous reduction in component size for smartphones and wearables necessitates higher-purity tin solders to ensure connection reliability and thermal performance.
- Electric Vehicle Production:China's focus on electric vehicle manufacturing creates substantial demand, as tin is critical for soldering in battery management systems, power inverters, and onboard chargers.
Market Restraints
- Geographic Supply Concentration:The global supply chain's heavy dependence on production from Indonesia and China creates significant price and availability risks tied to their domestic policies and operational stability.
- Smelting Energy Costs:The energy-intensive nature of refining tin ore into metal makes smelters highly exposed to volatile electricity and natural gas prices, directly impacting production costs.
- Substitution in Coatings:In certain packaging and industrial coating applications, alternative materials such as aluminum, zinc, and chromium can substitute for tinplate, limiting its use in price-sensitive segments.
Strategic Opportunities
- Advanced Battery Materials:Research into tin-based anodes for next-generation lithium-ion batteries presents a significant opportunity, potentially creating a new high-volume application in energy storage systems.
- Sourcing Verification Services:The expansion of blockchain-based traceability platforms allows producers to offer certified conflict-free tin, commanding a premium and meeting stringent OEM procurement requirements.
- Secondary Supply Development:Investing in advanced tin recovery and recycling infrastructure in Europe and North America can reduce reliance on primary imports and create a circular economy for electronics waste.
Industry Challenges
- Divergent Regulatory Compliance:Processors and manufacturers face significant administrative overhead in managing compliance with differing requirements from the US Dodd-Frank Act, EU Conflict Minerals Regulation, and China's MEE.
- Artisanal Sourcing Formalization:Integrating small-scale and artisanal mining output, particularly in Central Africa and Southeast Asia, into auditable, conflict-free supply chains remains a persistent operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tin Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Tin, Tin Scrap, Tin Alloys, Tin Chemicals, Tin Powder Application: Soldering, Chemicals Production, Tin Plating, Tin Foil, Glass Coating End User Industry: Electronics Manufacturers, Chemical Producers, Packaging Firms, Glass Makers, Coating Specialists Packaging Type: Bags, Drums, Bulk Containers, Tins, Palletized Units |
| Companies Covered | China Nonferrous Metal Mining Group, Yunnan Tin Company, Minsur, Mineração Taboca, PT Timah, Alphamin Resources, Metals X, First Tin, Malaysia Smelting Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tin Market Strategic Shifts & Innovations
Digital technologies are reshaping the verification of tin's origin and environmental impact. The focus is shifting from simple material provision to demonstrating a fully compliant and ethical supply chain through data-driven platforms that provide auditable proof of provenance.
Blockchain-based traceability platforms provide an immutable ledger for tracking tin from mine to smelter. Electronics and automotive OEMs are increasingly mandating their use to validate conflict-free claims from suppliers. This digital tracking capability is converging with corporate ESG reporting software, automating compliance verification for regulations like the EU's CSRD.
The European Union's Conflict Minerals Regulation imposes mandatory due diligence on importers to ensure minerals are sourced responsibly. This regulation effectively extends OECD sourcing standards to any global smelter wishing to sell into the EU market. The electronics sector feels the greatest impact, compelling manufacturers to overhaul supplier auditing processes to prove compliance.
A clear demand-side shift from price-centric purchasing to provenance-based sourcing is underway. Buyers now prioritize tin from smelters with active validation from the Responsible Minerals Initiative, disrupting uncertified commodity trading. This preference for certified material is most visible among consumer electronics brands in Europe and North America, where ESG metrics are scrutinized.
Global Tin Market Segmentation
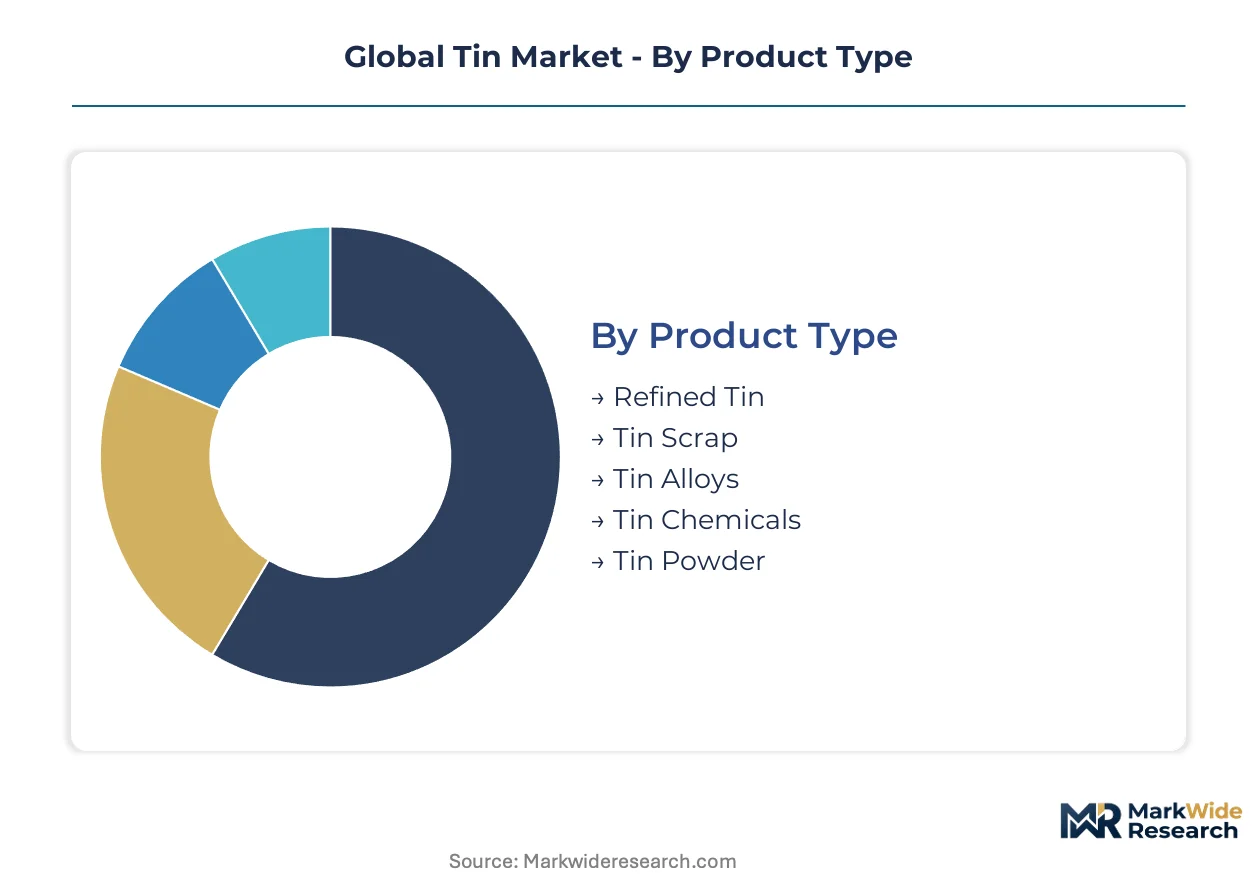
The Global Tin Market exhibits diverse segmentation across product forms, end-use applications, and industry verticals. Understanding these distinct segments allows for precise analysis of demand drivers and supply chain dynamics. Each category reveals specific market behaviors and competitive landscapes.
Product Type:
The tin market's product segmentation highlights how materials are integrated into standalone products or serve as intermediate components. This distinction influences processing requirements and market value. Raw and refined forms provide foundational inputs for diverse manufacturing processes.
- Refined Tin:This segment comprises high-purity metal, typically 99.85% or higher, produced from smelting tin concentrates. Demand concentrates in China's electronics sector, driven by its essential role in lead-free solder manufacturing.
- Tin Scrap:Recovered tin material from post-consumer or industrial waste streams serves as a secondary raw material source.
- Tin Alloys:These are metallic mixtures where tin is combined with other elements like lead, copper, or silver to enhance specific properties. The automotive industry utilizes tin alloys extensively for solders in electric vehicle components.
- Tin Chemicals:Compounds containing tin, such as tin oxides or organotin compounds, find specialized applications in various industrial processes.
- Tin Powder:Finely divided tin metal is used in powder metallurgy, friction materials, and certain specialized solder pastes.
Refined Tin leads volumes today; Tin Alloys are gaining share fastest.
Application:
Application segmentation reveals the primary functions tin performs across various industries, indicating usage intensity. Each application dictates specific purity requirements and material forms. The diversity of uses underscores tin's versatile properties.
- Soldering:This application involves joining metal components, primarily in electronics, utilizing tin's low melting point and excellent wetting characteristics. The miniaturization of electronics components necessitates high-purity tin solders for reliable connections.
- Chemicals Production:Tin compounds are synthesized for use as catalysts, stabilizers, and precursors in various chemical processes. These high-value applications often demand specific grades of tin, contributing to a higher-margin niche.
- Tin Plating:A thin layer of tin is electrodeposited onto other metals to provide corrosion resistance and improve solderability.
- Tin Foil:Thin sheets of tin metal are employed in specialized packaging and decorative applications requiring malleability.
- Glass Coating:Tin oxides are applied to glass surfaces to enhance electrical conductivity, anti-reflective properties, or scratch resistance.
Soldering dominates demand today; Chemicals Production shows significant expansion.
End User Industry:
End user industry segmentation highlights distinct procurement patterns and regulatory compliance needs within specific sectors. Each industry imposes unique performance specifications for tin materials. This categorization helps identify specialized market demands.
- Electronics Manufacturers:These companies integrate tin into lead-free solders for printed circuit boards, connectors, and semiconductor packaging. Stringent regulations like the EU's RoHS directive mandate tin's use, securing its market position.
- Chemical Producers:Firms in this sector utilize tin as a raw material for synthesizing various tin-based chemicals and catalysts. They often require specialized forms of tin for their high-purity production processes.
- Packaging Firms:These industries use tinplate for food and beverage containers, leveraging tin's corrosion resistance and non-toxic properties.
- Glass Makers:Manufacturers of flat glass and specialized glass products incorporate tin oxides for surface treatments and conductive coatings.
- Coating Specialists:Companies providing protective or decorative coatings use tin for plating applications and as an additive in paints.
Electronics Manufacturers drive the largest volume; Chemical Producers present a high-value segment.
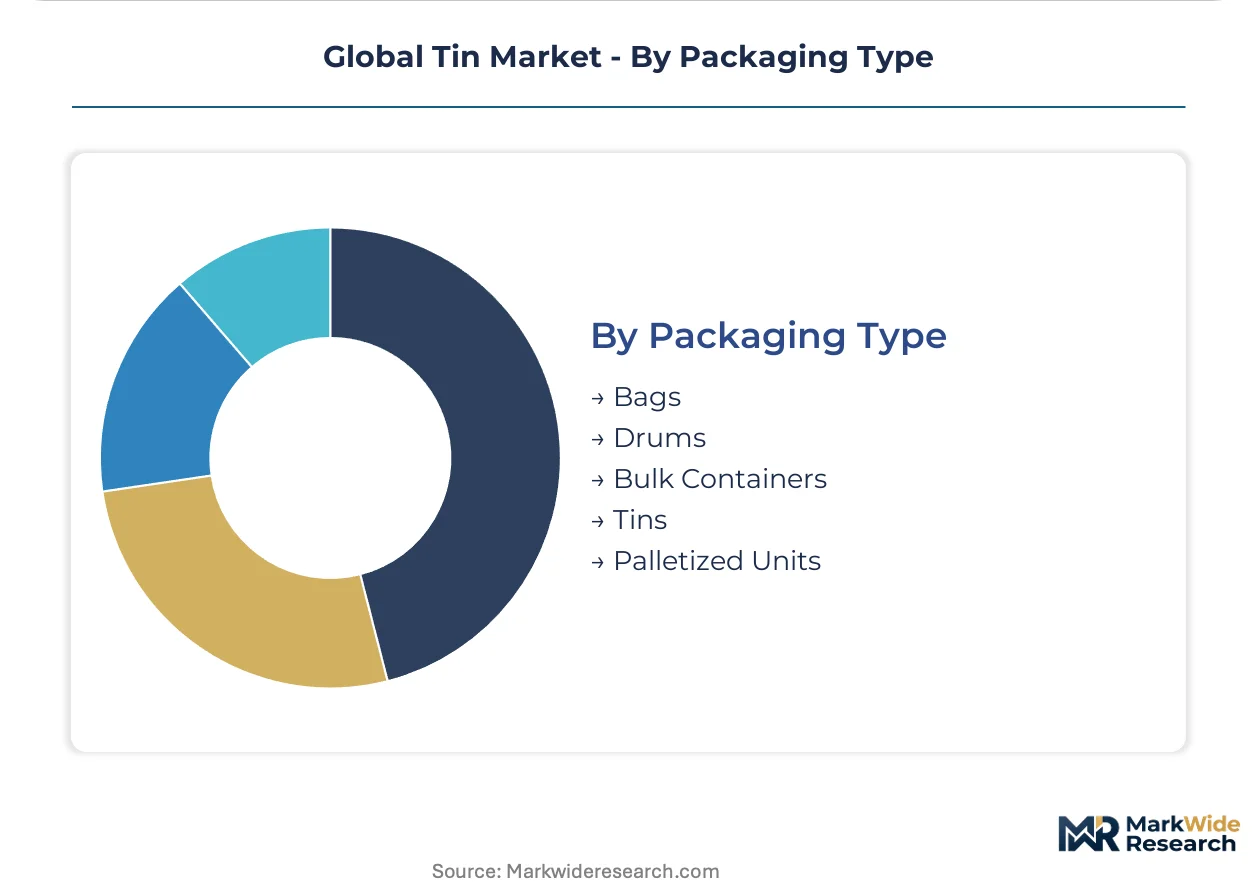
Packaging Type:
The packaging type segmentation reflects the logistical considerations and bulk handling requirements for tin products. Different packaging methods optimize for transport efficiency, material protection, and end-user convenience. This impacts storage and distribution costs across the supply chain.
- Bags:Smaller quantities of tin powder or chemicals are often supplied in multi-layered bags for ease of handling and storage.
- Drums:Intermediate volumes of tin products, including certain chemicals or alloys, are transported and stored in robust metal or plastic drums. These containers offer protection against contamination and facilitate stacking in warehouses.
- Bulk Containers:Large industrial quantities of refined tin or scrap are shipped in specialized bulk containers, such as ISO tanks or flexible intermediate bulk containers. This method optimizes for cost-effective, high-volume international transport.
- Tins:Finished tin products, like solder wire or small ingots, may be packaged in smaller metal tins for retail or specialized industrial use.
- Palletized Units:Various tin products, often in bags or drums, are consolidated onto pallets for efficient loading, unloading, and warehouse management.
Bulk Containers facilitate high-volume trade; Drums support specialized logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China dominates tin consumption and production, regulatory compliance and sustainable sourcing initiatives in Europe and South America are reshaping procurement priorities. The market's geographic distribution reflects both concentrated supply and dispersed demand across electronics and industrial applications.
China
Electronics manufacturing and electric vehicle production drive substantial tin demand within China. The Ministry of Ecology and Environment (MEE) imposes strict environmental standards on smelter emissions, influencing production costs. The Yangtze River Delta region, particularly around Shanghai and Shenzhen, represents a significant hub for electronics assembly requiring high-purity tin solders.
Indonesia
Indonesia remains a major global tin producer, with its output significantly influenced by export policies and environmental regulations. The US Dodd-Frank Act and the EU Conflict Minerals Regulation directly impact sourcing verification from Indonesian mines. The Bangka-Belitung islands are the primary tin mining and smelting center, facing ongoing challenges related to artisanal mining formalization.
Peru
Peru contributes significantly to global tin supply, with companies like Minsur emphasizing sustainable mining practices. The EU Conflict Minerals Regulation necessitates robust due diligence for Peruvian tin entering European markets. The Puno region hosts major tin mining operations, where efforts focus on integrating responsible sourcing standards into local communities.
United States
Electronics manufacturers and the growing electric vehicle sector in the United States create consistent demand for tin. The US Dodd-Frank Act requires supply chain transparency for conflict minerals, including tin, impacting procurement strategies. Silicon Valley and other tech hubs drive innovation in lead-free solder applications for advanced electronics.
Germany
Germany's advanced manufacturing base, particularly in automotive and electronics, relies on tin for various applications. The European Union's RoHS directive mandates lead-free solders, securing tin's essential role in electronics production. Industrial regions like Bavaria and Baden-Württemberg house key electronics and automotive component manufacturers.
Global Tin Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The global tin market exhibits a mix of large, integrated mining and smelting operations alongside smaller, specialized chemical producers. Key strategic archetypes include large-scale primary producers, niche chemical formulators, and recyclers. Technology licensing and capacity expansion represent dominant competitive moves in this industry.
Yunnan Tin Company, a prominent Chinese entity, exemplifies a vertically integrated producer with significant scale, supplying a substantial portion of China's electronics sector. Minsur, based in Peru, anchors the market's focus on sustainable mining practices, differentiating its operations through ESG commitments. State-owned PT Timah, from Indonesia, occupies a position as a major primary producer, controlling a substantial portion of its nation's tin output and influencing global supply dynamics.
| Leading Market Players |
|---|
| China Nonferrous Metal Mining Group |
| Yunnan Tin Company |
| Minsur |
| Mineração Taboca |
| PT Timah |
| Alphamin Resources |
| Metals X |
| First Tin |
| Malaysia Smelting Corporation |
| Others |
Cost & Logistics Intelligence
Energy costs, a critical component of tin refining, directly influence the final price points across the commodity spot market and long-term supply contracts. This cost component flows from upstream smelters through to downstream electronics manufacturers and chemical producers.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade tin, reflecting its dominant production volume. The market primarily operates on a hybrid model, combining commodity spot trading for standard grades with long-term contract-based offtake agreements for specialized, high-purity material. Price differentiation stems from two specific factors: the purity level required for electronics applications and the certification status for conflict-free sourcing. Pricing softness reflects an oversupply of uncertified, lower-grade material. Electronics manufacturers, requiring high-purity solders for miniaturized components, are the least price-sensitive buyers, while packaging firms often exhibit the highest price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of refined tin and alloys to manufacturing clusters. Geographic supply concentration remains acute, drawing heavily from Indonesia, China, and Peru. The supply chain relies on consistent access to tin ore and specialized chemical inputs for alloy production. A significant structural risk is the regulatory divergence between the US Dodd-Frank Act and the EU Conflict Minerals Regulation, creating compliance challenges for processors. The distribution model for high-volume refined tin primarily utilizes specialized bulk containers, while tin chemicals and alloys often require more specialized logistics for drums and palletized units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story, driven by the demand-shift towards high-purity, certified tin for advanced electronics and electric vehicle applications.
For Market Incumbents: Lock in long-term offtake agreements with leading electronics and automotive OEMs to secure demand for certified, high-purity tin. Invest in advanced recycling infrastructure in Europe and North America to diversify supply sources and mitigate geopolitical risks. The primary threat stems from volatile energy costs impacting smelting operations, necessitating efficiency improvements and renewable energy integration. ESG certification offers a powerful lever for market differentiation.
For New Entrants and Emerging Players: Blockchain-based traceability platforms represent a viable digital-channel route to market, offering auditable proof of provenance. Target the European and North American electronics sectors, where stringent ESG metrics and conflict minerals regulations create a premium for verified supply. The most penetrable segment is the niche for high-purity tin chemicals, leveraging specialized production processes. A compelling go-to-market angle involves offering certified conflict-free tin that meets evolving EU CSRD reporting requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where certified, sustainably sourced tin supply is constrained, particularly for high-purity grades. Long-term viability for tin hinges on its irreplaceable role in lead-free solders and potential for next-generation battery materials. The ideal acquisition target archetype is a vertically integrated producer with robust ESG practices and established traceability systems. The expansion of blockchain-based traceability platform adoption serves as a key signal to watch for market maturation and premium valuation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Certified Smelting | This move increases the supply of ethically sourced tin for global electronics manufacturers. |
| Advanced Recycling Infrastructure Development | This initiative reduces reliance on primary mining and strengthens circular economy principles for tin. |
| Blockchain-based Traceability System Adoption | This technology enhances supply chain transparency and verifies conflict-free sourcing for OEMs. |
| Long-term Offtake Agreements with EV Manufacturers | These contracts secure stable demand for tin in critical electric vehicle battery management systems. |
| Investment in Tin-based Battery Anode Research | This effort unlocks new high-volume applications for tin in next-generation energy storage solutions. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, ensuring a comprehensive view of the global tin market. Primary research included in-depth conversations with electronics R&D leads, smelter procurement managers, EV battery system engineers, and EU regulatory compliance officers. Secondary validation drew from EU RoHS directives, US Dodd-Frank Act filings, China's MEE environmental standards, and Responsible Minerals Initiative audit reports, triangulating data for robust market sizing and forecasting.
Comparable-period framing anchored the forecast window to established historical reference periods, allowing for consistent trend analysis across the modeling period. The analytical framework projected market growth across product type, application, end-user industry, packaging type, and regional market segments. Compound annual growth rates were derived from a blend of historical performance analysis and forward-looking economic indicators. Key industry-specific forecast inputs included electric vehicle production forecasts and electronics miniaturization rates.
The model assumes a particular technology adoption path, specifically the continued dominance of lead-free solder; alternative pathways for tin-based battery anodes would alter the outlook. Forecasts reflect a documented set of assumptions regarding regulatory stability and technological evolution. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging potential shifts from geopolitical events or energy price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Cobalt Market
Metals
Europe Metal Service Centers Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Bismuth Market
Metals
Copper Foil Market
Metals
North America Iron Casting Market
Metals
Europe Metal Casting Market
Metals
Magnesium Metal Market
Metals
Copper and Copper Alloy Market
Metals
Global Copper Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Rubidium Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Zinc Plating Market
Metals
Electrolytic Manganese Metal Market
Metals
Stainless Steel 400 Series Market