
 South Korea Protective Coatings Market | 2026-2036
South Korea Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Protective Coatings Market Analytics
Buyer concentration among South Korean shipbuilders and automotive OEMs is broadening as tier-two component suppliers and independent maintenance contractors enter the procurement pool. PPG Industries leverages its marine certification portfolio to serve Hyundai Heavy Industries and DSME yards in Ulsan. KCC Corporation anchors domestic supply through its integrated resin-to-coating manufacturing base in Gimcheon. Hempel A/S competes via specialized anti-fouling systems tailored to Korea's deep-draft vessel specifications.
South Korea protective coatings are engineered film-forming systems comprising binders, pigments, solvents, and functional additives that cure into adherent barriers against corrosion, chemical attack, and ultraviolet degradation, with film thickness typically ranging from 50 to 500 microns depending on exposure severity. Epoxy formulations dominate heavy industrial maintenance cycles due to their adhesion strength and chemical resistance in petrochemical environments. Waterborne technology is gaining formulation share as shipyards and automotive plants retrofit spray booths to meet emission thresholds, though solventborne systems retain share in offshore platform applications where cure speed and humidity tolerance remain critical.
MFDS oversight of chemical substance registration and KOSHA workplace exposure limits are tightening permissible solvent content in coating formulations, compelling reformulation investments across domestic manufacturers. The Green New Deal framework imposes carbon intensity benchmarks on industrial processes, pushing end users toward powder coating and UV-cured alternatives in appliance and electronics finishing. Stakeholders must monitor enforcement variance between metropolitan air-quality districts and provincial industrial zones to anticipate compliance cost differentials.
Market Dynamics
Shipyard operators in Ulsan and Geoje are consolidating procurement specifications around high-solids and solvent-free formulations, compressing supplier qualification timelines and fragmenting the vendor base across specialized marine coating categories.
Growth Catalysts
- Green New Deal carbon intensity benchmarks:Industrial process mandates are accelerating retrofit investments in powder coating and UV-cured systems across appliance and electronics finishing facilities.
- Deep-draft vessel specifications:Korean shipbuilders are expanding anti-fouling procurement for very large crude carriers and LNG carriers operating in high-fouling tropical routes.
- Gyeongsang coastal manufacturing belt concentration:Petrochemical complexes in Yeosu and Ulsan are driving cyclical maintenance demand for epoxy-based protective systems in aggressive chemical environments.
Market Restraints
- Epoxy resin price volatility:Feedstock fluctuations in bisphenol-A and epichlorohydrin are compressing formulation margins for domestic manufacturers without captive resin supply.
- MFDS chemical substance registration timelines:Extended approval cycles for new additive chemistries are delaying product launches by 18-24 months versus historical benchmarks.
- Humidity-cure incompatibility of waterborne systems:Technical performance gaps in offshore platform applications preserve solventborne share despite emission penalties.
Strategic Opportunities
- Independent maintenance contractor channel expansion:Tier-two ship repair facilities in Busan and Incheon are developing direct supplier relationships outside OEM-specified procurement.
- UV-cured technology convergence with robotics:Automotive OEMs are piloting automated spray lines for clearcoat applications in electric vehicle battery enclosure finishing.
- Provincial industrial zone enforcement variance:Compliance cost differentials between metropolitan air-quality districts and rural manufacturing zones create arbitrage opportunities for flexible production networks.
Industry Challenges
- Formulation chemist talent scarcity:Korean universities are producing insufficient graduates with hybrid polymer chemistry and regulatory compliance expertise to match industry hiring needs.
- Spray booth retrofit capex burdens:Waterborne conversion requires simultaneous investment in humidity control, flash-off zone extension, and wastewater treatment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Protective Coatings Market |
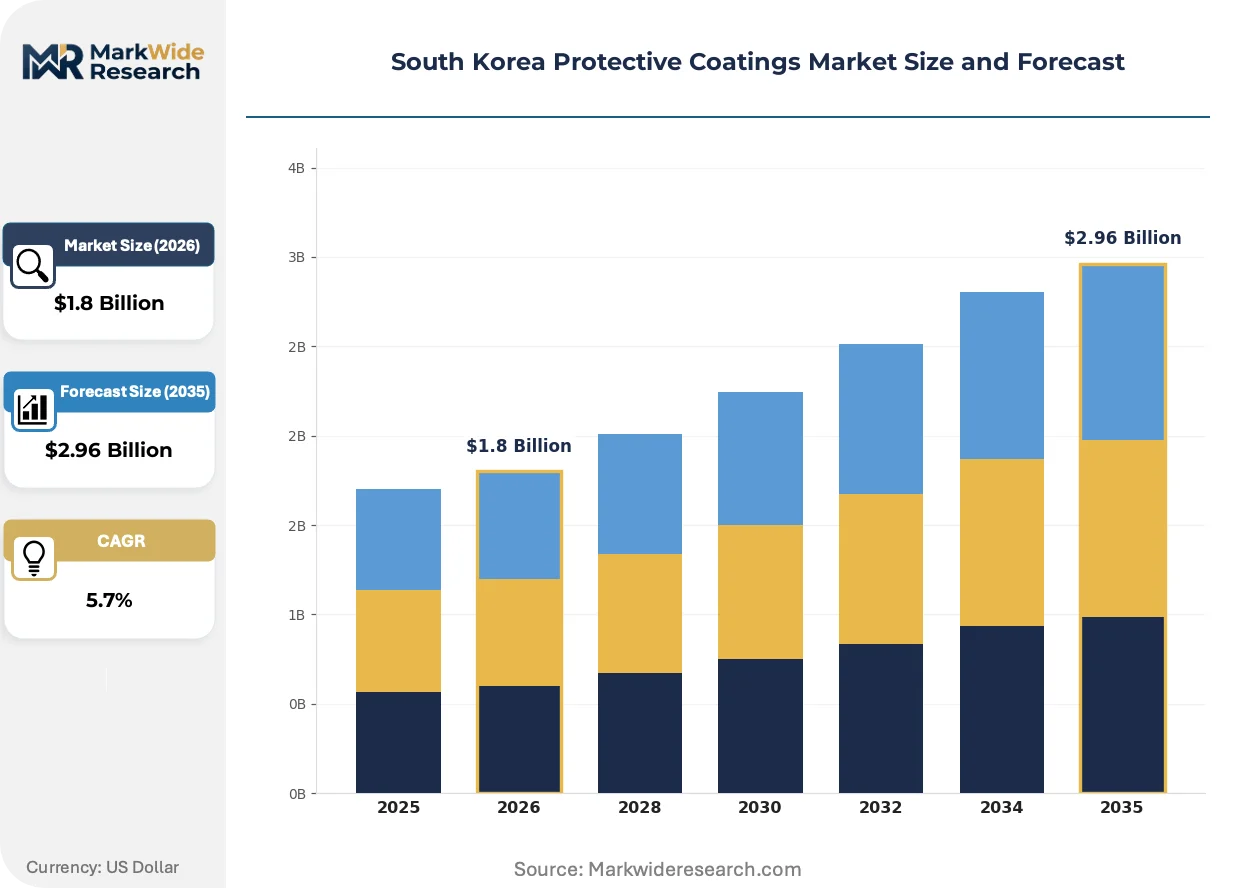
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, alkyd Application: Automotive, Aerospace, Marine, Industrial End User: Construction, Manufacturing, Oil & Gas, Consumer Goods Technology: Waterborne, Solventborne, Powder Coating, UV-Cured |
| Companies Covered | AkzoNobel N.V., PPG Industries, The Sherwin-Williams Company, Jotun, RPM International Inc., Hempel A/S, Axalta Coating Systems, Kansai Paint, KCC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Protective Coatings Market Evolving Landscape
Formulation science and application equipment are converging to enable thinner-film performance with reduced solvent burden, while procurement digitization is compressing specification-to-delivery cycles across the marine and industrial maintenance segments.
Self-healing microcapsule technology embedded in epoxy primers is electrifying corrosion protection strategies for subsea pipeline and offshore platform applications. Korean petrochemical operators are piloting these systems in the Yeosu industrial complex to extend maintenance intervals beyond conventional cathodic protection schedules. The technology is compressing total cost-of-ownership calculations for asset owners evaluating 25-year field life projections.
MFDS alignment with K-REACH substance notification thresholds is tightening pre-market data requirements for imported coating raw materials. Domestic blenders are responding by qualifying alternative bio-based hardener chemistries from local fermentation-derived feedstock suppliers. Marine coating formulators face the steepest compliance burden due to biocide registration requirements for anti-fouling actives.
Shipyard procurement teams are unbundling specification authority from central engineering departments, empowering individual vessel project managers to negotiate directly with certified coating applicators. This decentralization is fragmenting volume concentration previously captured by integrated OEM-service contracts. The pattern is most visible at DSME's Geoje yard, where project-specific coating packages now account for over one-third of marine procurement spend.
South Korea Protective Coatings Market Segmentation
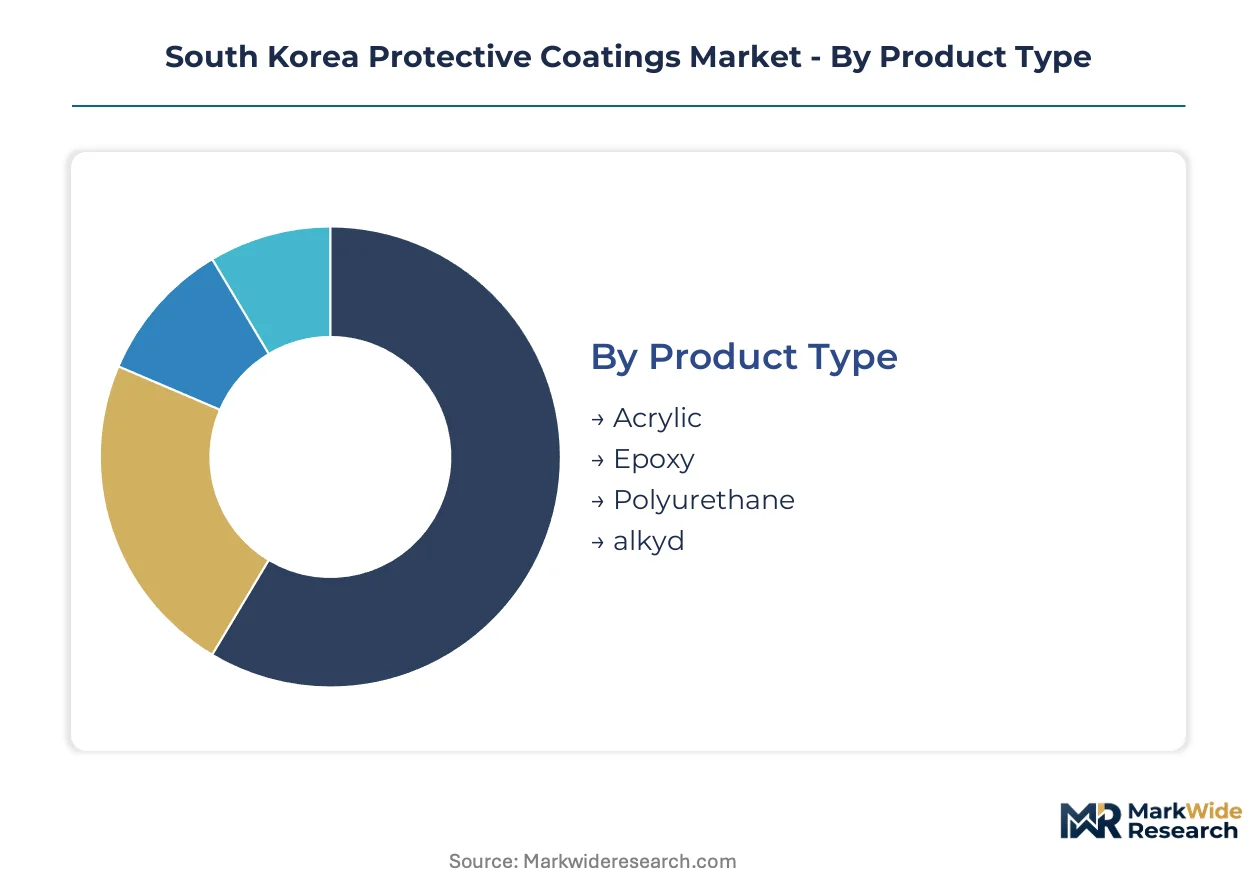
South Korea's protective coatings market fragments across technical specifications that determine MFDS registration pathways and KOSHA workplace exposure compliance. Segmentation choices directly shape reformulation investments and spray booth retrofit requirements for domestic manufacturers.
Product Type:
MFDS substance notification thresholds vary by resin chemistry, with biocide-bearing marine grades facing the steepest pre-market data requirements.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and epichlorohydrin deliver superior adhesion strength and chemical resistance. Petrochemical complexes in Yeosu and Ulsan specify these formulations for aggressive maintenance cycles, though feedstock price volatility compresses margins for blenders without captive resin supply.
- Polyurethane:Aliphatic and aromatic isocyanate-cured films provide abrasion resistance and UV stability for exterior durability. Automotive OEMs in Asan and Hwaseong are expanding procurement of polyurethane clearcoats for electric vehicle battery enclosure finishing, driven by Green New Deal carbon intensity benchmarks.
- Acrylic:Thermoplastic or thermosetting resin systems offering weatherability and color retention for architectural and transportation applications.
- Alkyd:Oil-modified polyester coatings delivering cost-effective corrosion protection for general industrial maintenance.
Leading the category by volume: Epoxy. Growing fastest: Polyurethane.
Application:
End-use sectors concentrate procurement authority differently, with marine and automotive channel structures diverging sharply.
- Marine:Anti-fouling and corrosion protection systems for newbuild and repair cycles. Shipyard operators in Ulsan and Geoje are unbundling specification authority from central engineering, empowering project managers to negotiate directly with certified applicators.
- Industrial:Heavy maintenance coatings for infrastructure and process equipment. Gyeongsang coastal manufacturing belt demand concentrates in chemical processing and power generation facilities.
- Automotive:OEM and refinish coatings for passenger and commercial vehicle production.
- Aerospace:High-performance films for commercial and military aircraft maintenance.
Marine commands the largest procurement volumes. Industrial maintenance exhibits the steepest expansion trajectory as infrastructure ages.
End User:
Customer scale determines contract structure, with national champions negotiating multi-year supply agreements while independent contractors purchase spot.
- Oil & Gas:Offshore platform and subsea pipeline protection requiring humidity-tolerant cure characteristics. Deep-draft vessel specifications drive anti-fouling procurement for very large crude carriers operating tropical routes.
- Manufacturing:Appliance and electronics finishing facilities retrofitting spray booths for powder coating and UV-cured alternatives under Green New Deal mandates.
- Construction:Infrastructure and commercial building protection systems.
- Consumer Goods:Decorative and functional coatings for household products.
Oil & Gas maintains the highest specification barriers. Manufacturing is gaining share fastest as appliance exporters expand capacity.
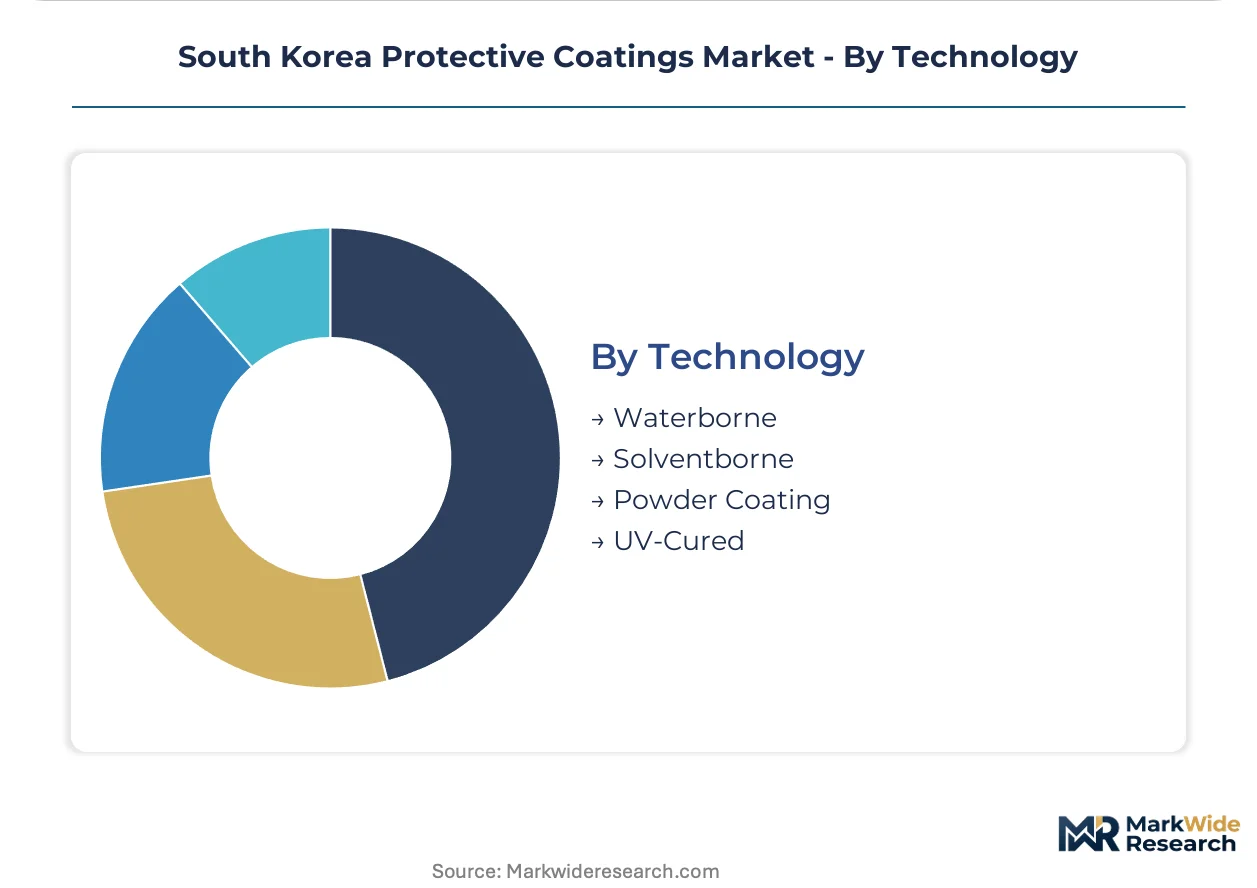
Technology:
Cure chemistry determines capital requirements, with waterborne conversion demanding simultaneous humidity control and wastewater treatment investments.
- Waterborne:Emulsion-based systems reducing VOC emissions for regulatory compliance. Technical performance gaps in offshore platform applications preserve solventborne share despite MFDS tightening permissible solvent content.
- Solventborne:Traditional high-solids and conventional systems retaining dominance where cure speed and humidity tolerance remain critical.
- Powder Coating:Thermosetting dry film systems eliminating liquid carrier requirements.
- UV-Cured:Photoinitiator-activated systems enabling rapid processing for high-throughput lines.
Solventborne still leads by installed base. Waterborne is climbing the fastest as shipyards and automotive plants retrofit spray booths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for protective coatings in South Korea concentrates along the Gyeongsang coastal manufacturing belt, where shipbuilding yards and petrochemical complexes generate concentrated procurement volumes. The Green New Deal carbon intensity benchmarks are reshaping investment patterns across metropolitan and provincial industrial zones.
Seoul Capital Area
Automotive OEMs in Asan and Hwaseong are expanding polyurethane clearcoat procurement for electric vehicle battery enclosure finishing. MFDS chemical substance registration timelines are extending approval cycles for new additive chemistries. Electronics finishing facilities in Suwon and Pyeongtaek are retrofitting spray booths for UV-cured alternatives under tightening VOC emission limits.
Busan-Ulsan
Shipyard operators at Hyundai Heavy Industries and DSME yards are consolidating procurement around high-solids marine formulations. KOSHA workplace exposure limits are compressing permissible solvent content in coating formulations. Anti-fouling system demand concentrates in Ulsan's deep-draft vessel construction for very large crude carriers operating tropical routes.
Daegu-Gyeongbuk
KCC Corporation anchors domestic supply through its integrated resin-to-coating manufacturing base in Gimcheon. The Green New Deal framework imposes carbon intensity benchmarks on industrial processes. Petrochemical maintenance cycles in Pohang are driving epoxy-based protective system demand for aggressive chemical environments.
Daejeon-Sejong
Government research institutes are piloting self-healing microcapsule technology for subsea pipeline applications. MFDS alignment with K-REACH substance notification thresholds is tightening pre-market data requirements. Technology transfer partnerships between national laboratories and domestic blenders are accelerating bio-based hardener development.
Gwangju-Honam
Yeosu industrial complex operators are extending maintenance intervals beyond conventional cathodic protection schedules through advanced corrosion protection strategies. Provincial industrial zone enforcement variance creates compliance cost differentials versus metropolitan air-quality districts. Independent maintenance contractors in Mokpo are developing direct supplier relationships outside OEM-specified procurement channels.
South Korea Protective Coatings Market Competitive Landscape
Domestic Korean producers anchor one tier through integrated resin-to-coating manufacturing; European and North American specialists hold premium marine and industrial certification portfolios. The vendor structure fragments across three qualification tiers: OEM-approved suppliers for newbuild ship construction, certified applicators for maintenance cycles, and independent distributors serving spot procurement. Two strategic archetypes dominate: vertically integrated chemical conglomerates controlling captive resin supply, and coating specialists leveraging marine certification authority. Competitive moves concentrate on spray booth retrofit partnerships and biocide registration compliance for anti-fouling actives.
Within the domestic integrated tier, KCC Corporation exemplifies backward control over upstream resin production. Among marine certification specialists, Hempel A/S and PPG Industries occupy positions tied to Korean shipbuilder procurement specifications. These three anchors represent the competitive geometry: one domestic conglomerate with supply chain integration, two international specialists with regulatory authority in deep-draft vessel applications.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries |
| The Sherwin-Williams Company |
| Jotun |
| RPM International Inc. |
| Hempel A/S |
| Axalta Coating Systems |
| Kansai Paint |
| KCC Corporation |
| Others |
Value Network & Pricing Analysis
Shipyard procurement consolidation around high-solids and solvent-free marine specifications is compressing supplier margins and forcing blenders to absorb feedstock volatility or lose OEM-approved status. This demand-side pressure reshapes supply responses, with domestic manufacturers prioritizing captive resin supply while international specialists lean on certification authority to defend premium positioning.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements for marine OEM procurement, while spot purchases by independent maintenance contractors capture thinner margins. Price differentiation hinges on certification grade — KOSHA-compliant low-VOC formulations command premium positioning — and volume scale, with national champions extracting tiered discounts. Pricing pressure stems from epoxy resin feedstock volatility in bisphenol-A and epichlorohydrin markets, compressing blender margins. Tier-two component suppliers exhibit highest price sensitivity, whereas offshore platform operators prioritize humidity-tolerant performance over cost.
Supply Chain Analysis
Domestic-content preferences in South Korea's Green New Deal procurement guidelines are elevating local blenders with integrated resin manufacturing. Raw material sourcing draws from China for epichlorohydrin, Japan for specialty isocyanates, and domestic petrochemical complexes for bisphenol-A derivatives. Single-source vulnerability concentrates in biocide actives for anti-fouling systems, where marine registration requirements limit qualified suppliers. Distribution runs through three tiers: direct OEM supply for newbuild construction, certified applicator networks for maintenance cycles, and independent distributors serving spot procurement in provincial industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's protective coatings sector is navigating a technology-transition phase, with waterborne and UV-cured systems displacing solventborne dominance in automotive and appliance finishing under tightening MFDS emission thresholds.
For Market Incumbents: Hedge against formulation margin compression by securing captive epichlorohydrin supply or qualifying alternative bio-based hardener chemistries from local fermentation-derived feedstock suppliers. KCC Corporation's integrated Gimcheon manufacturing base exemplifies this defensive posture. Counter the threat of procurement decentralization at DSME and Hyundai Heavy Industries yards by embedding technical service teams directly with vessel project managers to preserve specification influence. For New Entrants and Emerging Players: MFDS alignment with K-REACH substance notification thresholds in South Korea opens a window for bio-based hardener specialists to bypass incumbent biocide registration burdens in anti-fouling segments. Target the independent maintenance contractor channel in Busan and Incheon, where direct supplier relationships outside OEM-specified procurement are expanding fastest. A go-to-market angle anchored in spray booth retrofit partnerships — bundling waterborne formulation supply with humidity control infrastructure — addresses the capital burden blocking tier-two facility conversion. For Investors and Strategic Acquirers: The window for entry favors coating specialists with marine certification authority and UV-cured technology portfolios. Long-term viability over the next decade rests on positioning for appliance and electronics finishing automation, where robotics convergence with rapid-cure systems is accelerating. Watch for enforcement variance between Seoul Capital Area air-quality districts and provincial industrial zones as an inflection indicator — widening compliance cost differentials will reward flexible production networks with multi-site manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | KCC Corporation's captive bisphenol-A supply insulates margins from epichlorohydrin volatility. |
| Spray Booth Retrofit Partnership | Waterborne conversion bundling addresses tier-two facility capex barriers in Gyeongsang belt. |
| Marine Certification Investment | MFDS biocide registration for anti-fouling actives secures DSME and Hyundai Heavy Industries access. |
| UV-Cured Technology Licensing | Automotive OEMs in Asan pilot robotic clearcoat lines for electric vehicle battery enclosures. |
| Provincial Zone Production Expansion | Flexible networks exploit enforcement variance between Seoul metropolitan and rural industrial districts. |
Research Methodology
Document review covered customs and trade data, KOSHA workplace exposure filings, and MFDS chemical substance registration databases, complemented by interviews with plant managers at Ulsan and Yeosu petrochemical complexes, procurement leads at Hyundai Heavy Industries and DSME, distribution channel partners serving the Gyeongsang coastal belt, and technical R&D directors at domestic blenders. Secondary validation drew from K-REACH substance notification records, Green New Deal policy implementation reports, and shipyard production disclosures. Bottom-up demand modeling triangulated against top-down macroeconomic benchmarks across the analysis window.
Historical volume trajectories were cross-referenced against panel input from coating formulators and end-user procurement officers to construct the analytical framework. Segmentation dimensions modeled include resin chemistry tier, end-use application, cure technology, and regional production cluster. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and technology substitution curves. Forecast inputs incorporated shipyard order backlogs for very large crude carriers and LNG carriers, plus appliance exporter capacity expansion schedules under carbon intensity benchmarks.
The model assumes a particular technology adoption path; alternative pathways for waterborne system performance advancement in offshore platform humidity tolerance would alter the outlook. Forecasts reflect assumptions about MFDS enforcement consistency and KOSHA exposure limit trajectories. Epoxy resin feedstock volatility, extended additive chemistry approval cycles, and spray booth retrofit capex availability represent specific risk factors that could revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Bio-Based Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Yacht Coatings Market
Coatings
Coating Binders Market
Coatings
Europe Thermal Spray Market
Coatings
Solar Reflective Film Market
Coatings
Flexible Waterproof Coating Market
Coatings
Global Antiviral Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Dispersion Coating Market
Coatings
Global Solar Panel Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Fillers and Coating Market
Coatings
Heavy Duty Glass Coating Market