
 Tin Chemicals Market | 2026-2036
Tin Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Tin Chemicals Market Analysis
Lead-free solder requirements in electronics assembly is shifting tin chemical demand toward high-purity tin salts and specialized flux formulations. Yunnan Tin Company Group Limited anchors upstream concentrate supply through integrated mining and smelting operations in southwestern China. DowDuPont differentiates through application-specific organotin catalyst portfolios serving polymer and coatings customers. Element Solutions Inc. positions its specialty chemicals division to capture value from surface treatment and electroplating chemistry demand.
Tin chemicals encompass inorganic and organometallic compounds derived from tin metal, including tin oxides with 99%+ purity grades, organotin stabilizers containing dibutyltin or dioctyltin moieties, and tin halides produced via direct chlorination or dissolution processes; these materials function primarily as catalysts, stabilizers, and surface treatment agents across industrial manufacturing. Organotin compounds command the largest value share within product type segmentation due to their irreplaceable role in PVC thermal stabilization, while tin oxide powders lead growth trajectories driven by transparent conductive coating applications in display manufacturing. Application segmentation shows coatings and electronics as the dominant revenue pools, with pharmaceutical-grade tin salts representing a concentrated margin segment subject to stringent purity certification requirements.
REACH regulation through ECHA governs organotin compound authorization and restriction protocols across European manufacturing, while China's GB standards and MEE oversight enforce emission controls on tin chemical production facilities. FDA and EPA frameworks in the United States regulate tin-based additives in food-contact materials and industrial discharge limits respectively. Stakeholders must monitor evolving substitution dynamics between tin-based and calcium-zinc stabilizer systems while tracking purity specification escalations from downstream electronics customers.
Market Dynamics
REACH authorization protocols through ECHA are redirecting organotin formulation investment toward alternative catalyst systems while China's eastern coastal manufacturing clusters concentrate PVC stabilization and electronics plating demand.
Growth Catalysts
- Lead-free solder mandates:Electronics assembly standards across major manufacturing jurisdictions are elevating demand for high-purity tin salts and specialized flux formulations in surface-mount technology processes.
- Dual carbon targets:China's MEE emission controls on tin chemical production facilities are accelerating process efficiency upgrades and cleaner organotin synthesis pathways.
- Transparent conductive coatings:Display manufacturing expansion in East Asian industrial corridors is absorbing elevated volumes of 99%+ purity tin oxide powders for thin-film transistor applications.
Market Restraints
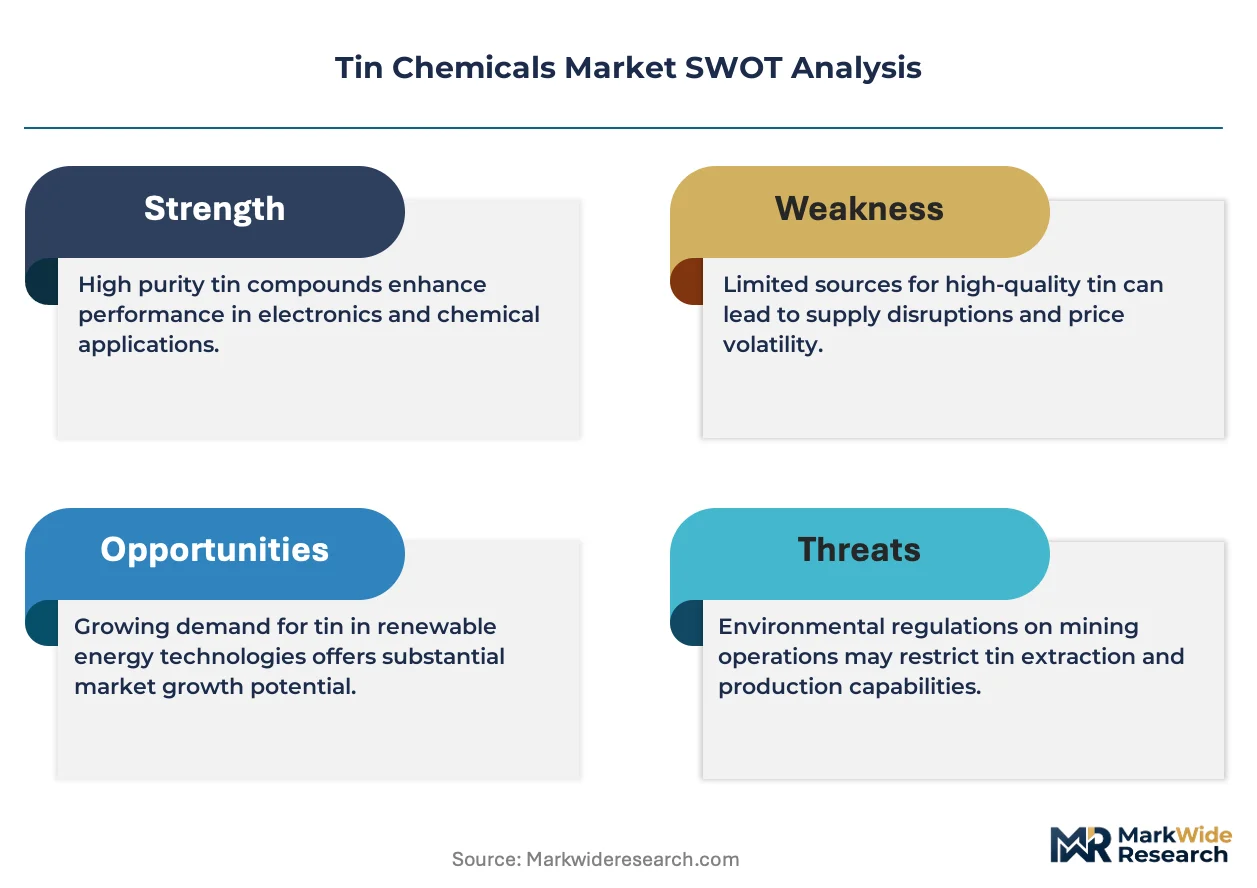
- Input cost volatility:Tin concentrate price fluctuations from upstream mining operations in southwestern China compress margin stability for downstream chemical processors.
- Substitution dynamics:Calcium-zinc stabilizer systems are capturing share in flexible PVC applications previously served by dibutyltin formulations, particularly in cost-sensitive construction segments.
- REACH authorization friction:ECHA restriction protocols on specific organotin moieties are forcing European formulators into costly re-registration and reformulation cycles.
Strategic Opportunities
- Pharmaceutical-grade tin salts:Stringent purity certification requirements for API manufacturing and diagnostic reagents command concentrated margin premiums from qualified suppliers.
- Surface treatment chemistry:Electronics plating operations in Vietnam and Indonesia present underpenetrated demand pools for specialized tin-based electroplating formulations.
- GB standard alignment:China's evolving national standards for tin chemical emissions create first-mover advantage for domestic producers with integrated environmental compliance infrastructure.
Industry Challenges
- Specialized synthesis expertise:Organotin catalyst production requires rare organometallic chemistry capabilities that concentrate among a limited pool of experienced technical personnel.
- Multi-jurisdiction certification timelines:Pharmaceutical and food-contact applications demand concurrent FDA, EMA, and NMPA approvals that extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tin Chemicals Market |
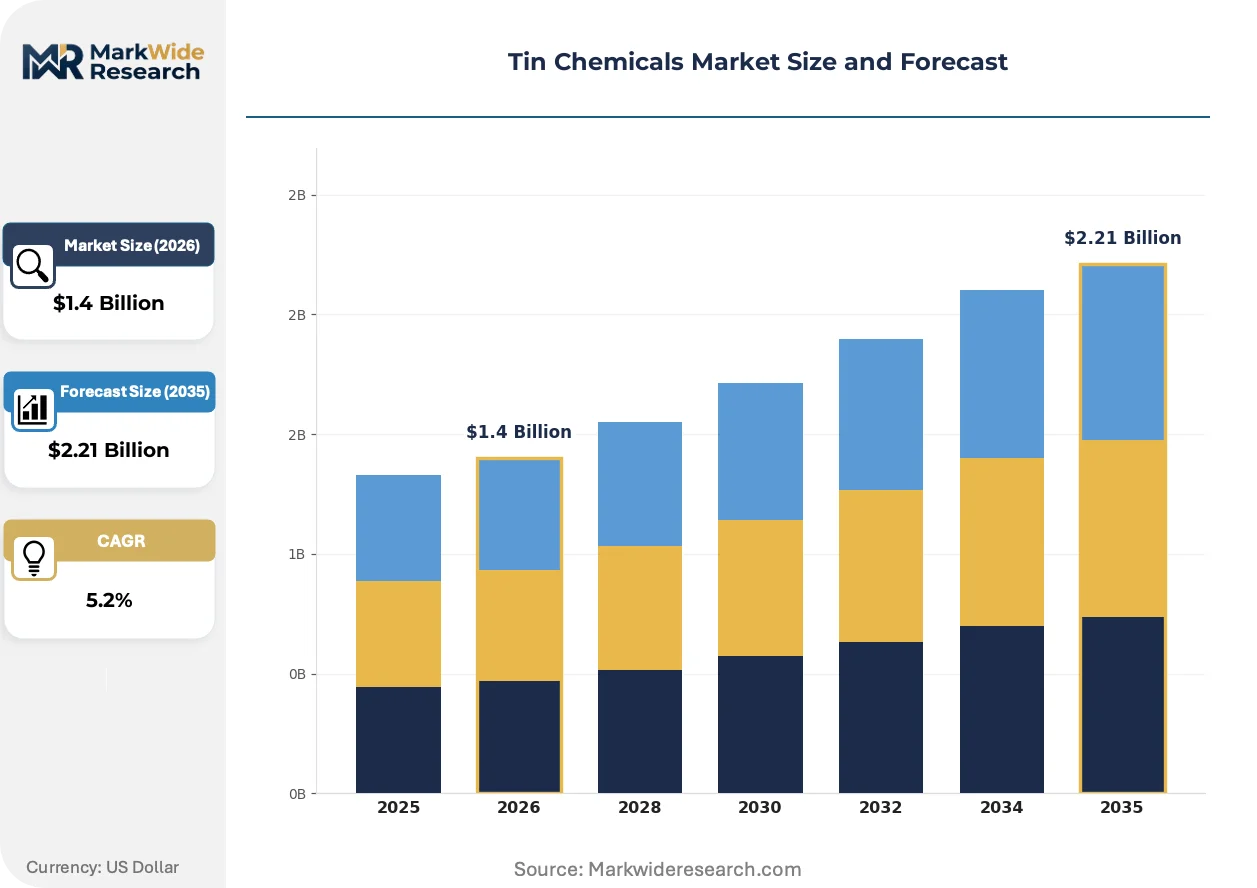
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tin Oxide, Organotin Compounds, Tin Chloride, Tin Sulfate Application: Electronics, Coatings, Plastics, Pharmaceuticals End User: Consumer Electronics, Automotive Manufacturers, Construction, Healthcare Form: Powder, Liquid, Granular, Paste |
| Companies Covered | William Blythe, Mason Corporation, Yunnan Tin Company Group Limited, DowDuPont, Lorad Chemical Corporation, Showa America, Keeling & Walker, Element Solutions Inc., TIB Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tin Chemicals Market Emerging Trajectories
Formulation chemistry is pivoting toward higher-purity grades and alternative catalytic systems as downstream electronics and pharmaceutical customers escalate specification requirements.
High-purity tin oxide powders with sub-micron particle distributions function as transparent conductive layers in display and photovoltaic applications. Panel manufacturers in South Korea and Japan are adopting these materials at accelerating rates for flexible OLED substrates. Vapor-phase synthesis methods is overtaking conventional precipitation processes for achieving the 99.9%+ purity thresholds demanded by semiconductor-grade applications.
REACH authorization protocols through ECHA are systematically restricting specific dibutyltin and dioctyltin formulations across European polymer processing. This regulatory compression is forcing stabilizer manufacturers toward mixed-metal and calcium-zinc alternatives that require reformulation investment. Western European PVC compounders are most affected, with many establishing dedicated regulatory compliance functions to manage substance authorization timelines.
Electronics assemblers are consolidating supplier relationships around qualified tin chemical providers capable of certifying conflict-free concentrate sourcing and batch-level traceability. Direct procurement from integrated mining-smelting-chemical operations is displacing distributor-mediated purchasing in high-volume solder paste and flux applications. This concentration pattern is most visible in China's Guangdong and Jiangsu provinces where contract manufacturers cluster.
Tin Chemicals Market Segmentation
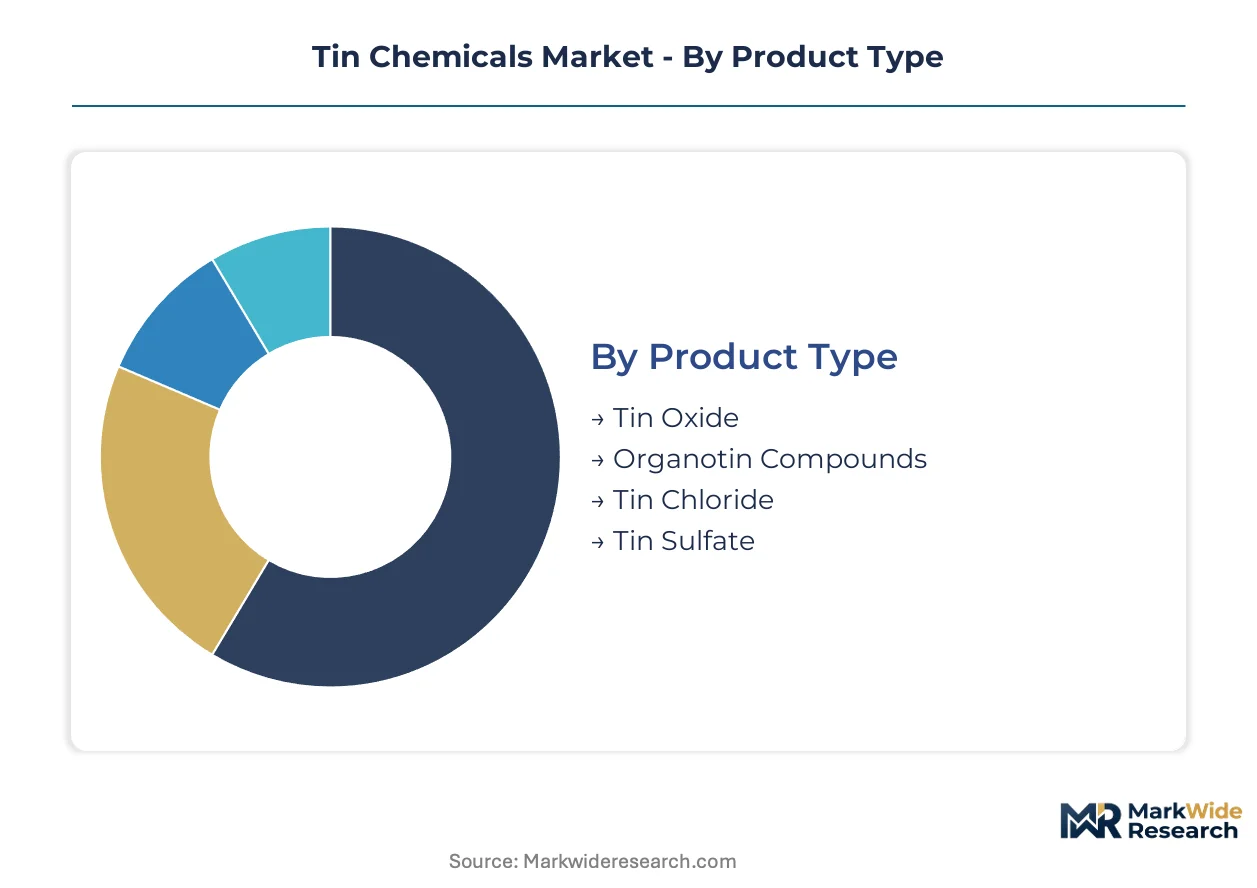
Tin chemical buyers prioritize distinct performance attributes across product categories—purity thresholds for electronics plating, thermal stability windows for PVC processing, and biocompatibility certifications for pharmaceutical applications. Segmentation clarity enables suppliers to align synthesis capabilities with margin concentration points.
Product Type:
Buyers in this category differentiate primarily by specification stringency and regulatory burden—electronics customers demand 99.9%+ purity with full batch traceability, while polymer processors prioritize cost-adjusted stabilization efficiency.
- Organotin Compounds:Dibutyltin and dioctyltin moieties serve as thermal stabilizers in PVC processing, with dibutyltin formulations dominating rigid applications. Demand concentrates in China's eastern coastal provinces where PVC compounding clusters face MEE emission compliance deadlines.
- Tin Oxide:Sub-micron powders with 99%+ purity function as transparent conductive layers in display manufacturing. South Korean and Japanese panel manufacturers absorb elevated volumes for flexible OLED substrates, with vapor-phase synthesis displacing precipitation methods for semiconductor-grade specifications.
- Tin Chloride:Produced via direct chlorination or dissolution processes, these halides serve as electroplating bath constituents and polymerization catalysts. Surface treatment operations in Vietnam and Indonesia present underpenetrated demand pools.
- Tin Sulfate:Specialized grades support electroplating chemistry and pigment manufacturing, with pharmaceutical-grade variants subject to concurrent FDA and NMPA certification timelines.
Volume sits with organotin stabilizers; growth tilts toward tin oxide powders for transparent conductive applications.
Application:
Application selection tracks end-use margin structure—electronics commands premium pricing for conflict-free certified supply, while construction-facing plastics compete on reformulation cost.
- Electronics:Lead-free solder mandates across major manufacturing jurisdictions elevate demand for high-purity tin salts and specialized flux formulations. Procurement is consolidating around qualified providers with integrated mining-smelting-chemical operations in China's Guangdong and Jiangsu provinces.
- Coatings:Surface treatment chemistry spans electroplating, anti-corrosion, and functional thin films. REACH authorization protocols through ECHA are redirecting European formulators toward alternative catalyst systems.
- Plastics:PVC thermal stabilization absorbs the majority of organotin volume, with calcium-zinc systems capturing share in flexible applications previously served by dibutyltin formulations.
- Pharmaceuticals:API manufacturing and diagnostic reagents require stringent purity certification, with qualified suppliers commanding concentrated margin premiums subject to 18-36 month multi-jurisdiction approval cycles.
Revenue concentrates in electronics; expansion is accelerating fastest in pharmaceutical-grade salts.
End User:
End user selection reflects supply chain proximity to concentrate sources and certification infrastructure depth.
- Consumer Electronics:Contract manufacturers cluster in China's eastern coastal provinces, driving direct procurement from integrated suppliers capable of certifying conflict-free concentrate sourcing.
- Automotive Manufacturers:Electronics plating and coating applications demand consistent specification adherence across multi-site production networks.
- Construction:PVC piping and profile extrusion in cost-sensitive segments faces substitution pressure from calcium-zinc stabilizer systems.
- Healthcare:Pharmaceutical and diagnostic applications impose the most stringent purity and traceability requirements.
Procurement scale favors consumer electronics; margin capture tilts toward healthcare.
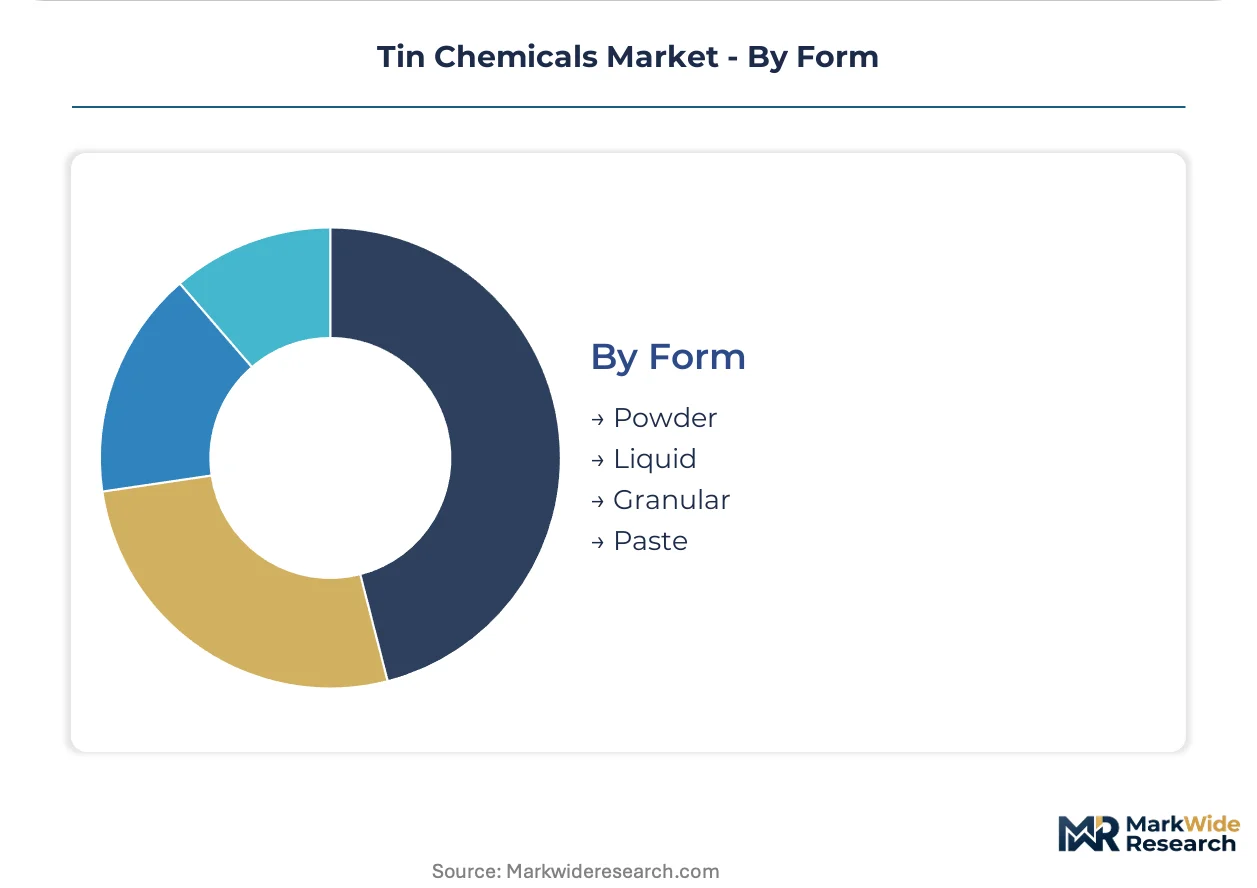
Form:
Form selection balances handling efficiency, dispersion requirements, and synthesis pathway compatibility.
- Powder:Sub-micron distributions dominate transparent conductive and semiconductor-grade applications, with particle size distribution directly determining coating uniformity.
- Liquid:Organotin stabilizers and catalysts ship predominantly as liquids or concentrated solutions for direct metered addition in polymer processing.
- Granular:Free-flowing grades simplify bulk handling in high-volume PVC compounding operations.
- Paste:Solder paste formulations combine tin powder with flux vehicles for surface-mount technology deposition.
Volume flows through liquid and powder forms; paste formats are climbing fastest alongside electronics assembly expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta Economic Zone concentrates the highest density of tin chemical consumption, with bonded zones in Shanghai and Jiangsu offering preferential tax treatment for electroplating and polymer processing operations.
China
MEE emission controls on tin chemical production facilities are accelerating cleaner synthesis pathways in Jiangsu and Zhejiang provinces. The dual carbon targets mandate process efficiency upgrades across eastern coastal manufacturing clusters. Guangdong province hosts contract electronics manufacturers consolidating procurement around conflict-free certified suppliers.
United States
FDA and EPA frameworks regulate tin-based additives in food-contact materials and industrial discharge limits respectively. Lead-free solder mandates across electronics assembly standards elevate demand for high-purity tin salts. Texas and Arizona host surface treatment operations serving semiconductor fabrication demand.
Germany
ECHA REACH authorization protocols systematically restrict specific dibutyltin and dioctyltin formulations across polymer processing. Western European PVC compounders establish dedicated regulatory compliance functions to manage substance authorization timelines. The Ruhr industrial corridor maintains specialty chemical production despite reformulation pressures.
South Korea
Panel manufacturers absorb elevated volumes of 99%+ purity tin oxide powders for flexible OLED substrates under METI-aligned quality standards. Vapor-phase synthesis methods displace conventional precipitation processes for semiconductor-grade specifications. Gyeonggi-do province concentrates display manufacturing supply chain integration.
Japan
JIS standards govern tin chemical specifications for electronics plating and surface treatment applications. Pharmaceutical-grade tin salts for API manufacturing require PMDA certification extending commercialization cycles. The Kansai region maintains precision chemical synthesis capabilities for high-purity grades.
Tin Chemicals Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mining-smelting-chemical operations commanding procurement relationships in high-volume electronics applications. The vendor base organizes around three archetypes: upstream-integrated concentrate suppliers, application-specific catalyst formulators, and specialty electroplating chemistry providers. M&A activity concentrates on backward integration into tin concentrate sourcing and geographic expansion into Vietnamese and Indonesian surface treatment markets.
Within the upstream-integrated tier, Yunnan Tin Company Group Limited exemplifies captive mining-smelting-chemical operations anchoring concentrate supply. DowDuPont occupies a position among diversified chemical conglomerates with polymer and coatings catalyst portfolios. Element Solutions Inc. sits within the specialty chemicals segment serving surface treatment and electroplating demand.
| Leading Market Players |
|---|
| William Blythe |
| Mason Corporation |
| Yunnan Tin Company Group Limited |
| DowDuPont |
| Lorad Chemical Corporation |
| Showa America |
| Keeling & Walker |
| Element Solutions Inc. |
| TIB Chemicals |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in China's eastern coastal provinces anchor tin chemical supply, translating captive concentrate access into pricing discipline against volatile LME tin benchmarks. Their integrated mining-smelting-chemical operations compress working capital cycles and buffer margin erosion when concentrate costs spike.
Pricing Analysis
Short lead-time premiums of fifteen to thirty percent separate spot pharmaceutical-grade tin sulfate orders from scheduled contract volumes in API manufacturing. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and industrial-grade certifications dominates the market, with FDA-NMPA dual-certified salts commanding the widest spreads. Cost compression in flexible PVC stabilizers is intensifying because calcium-zinc substitution erodes dibutyltin volume in cost-sensitive construction segments. Construction-facing compounders exhibit the highest price sensitivity, while healthcare procurement teams prioritize batch traceability over unit economics.
Supply Chain Analysis
Reverse-logistics flows for spent electroplating bath solutions remain underdeveloped, though Jiangsu province pilots closed-loop tin recovery from semiconductor fabrication waste. Concentrate supply concentrates in China, Indonesia, and Myanmar, with Yunnan Tin Company Group Limited anchoring upstream captive production. Downstream chemical synthesis draws from tin metal, chlorine gas, and organometallic precursors as core inputs. Single-source vulnerability around Myanmar concentrate exports during monsoon disruptions presents structural exposure. Distribution runs through direct procurement relationships with integrated producers displacing distributor channels in high-volume electronics applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization protocols through ECHA have erected a cost-of-compliance moat that rewards incumbent European formulators with dedicated regulatory affairs infrastructure while straining smaller competitors.
For Market Incumbents: Deepen backward integration into conflict-free concentrate sourcing to defend against qualification requirements from electronics assemblers consolidating supplier lists. Fortify regulatory compliance capabilities across ECHA, FDA, and NMPA jurisdictions to extend authorization timelines that block mid-tier competitors. Calcium-zinc substitution in flexible PVC represents the most pressing volume threat to organotin stabilizer positions. For New Entrants and Emerging Players: Vietnamese electroplating service bureaus present the most penetrable white-space target, with surface treatment chemistry demand outpacing qualified local supply. Indonesia's emerging electronics manufacturing zones offer parallel entry corridors with lower incumbent density than China's saturated coastal clusters. Partner with regional distributors possessing existing MEE compliance relationships to accelerate market access without building captive regulatory infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap tin oxide specialists with vapor-phase synthesis capabilities in South Korea's Gyeonggi-do corridor, where display manufacturing consolidation is squeezing subscale producers. Long-term viability hinges on positioning for semiconductor-grade purity escalation rather than commodity transparent conductive oxide volumes. Watch for METI-aligned quality standard revisions as the inflection signal for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Sourcing | Captive tin concentrate supply from Yunnan or Myanmar operations secures conflict-free certification for electronics procurement. |
| Vapor-Phase Synthesis Capacity Expansion | Semiconductor-grade tin oxide production displaces precipitation methods for 99.9%+ purity OLED substrate applications. |
| Multi-Jurisdiction Regulatory Certification | Concurrent FDA, EMA, and NMPA approvals for pharmaceutical-grade salts extend commercialization moats by 18-36 months. |
| Joint Venture in Vietnamese Surface Treatment | Electroplating chemistry partnerships in Binh Duong province capture underpenetrated demand from relocating electronics assemblers. |
| Green Manufacturing Transition | MEE-aligned emission controls in Jiangsu and Zhejiang provinces create first-mover advantage for domestic producers with integrated compliance infrastructure. |
Methodological Framework
Independent corroboration across customs trade data, SEC filings from specialty chemical conglomerates, and ECHA substance authorization registries underwrites the qualitative findings in this study. Primary interviews with plant managers at Jiangsu and Zhejiang tin chemical facilities, procurement leads at Guangdong contract electronics manufacturers, and distribution channel partners across Southeast Asia combined with secondary validation from ACC industry reports, Chinese customs records, and FDA drug master file databases. Bottom-up volume estimates from individual production facility disclosures triangulate against top-down demand aggregation from end-use industry consumption patterns.
Comparable-period anchoring to historical production and trade flows across the analysis window established baseline calibration for forward projections. Segmentation dimensions modeled include product purity grade, end-use industry vertical, packaging format, and regional production hub clustering. CAGRs derive from weighted-average growth assumptions applied to segment-level volume baselines, with tin concentrate price volatility and REACH authorization timelines as chemical-specific forecast inputs.
Caveats apply where ECHA restriction list expansions or Myanmar supply disruptions could materially shift the outlook for organotin stabilizer volumes and concentrate cost structures. Practitioners should monitor MEE enforcement intensity in China's eastern coastal provinces and METI quality standard revisions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Antiozonant Market
Chemicals
Ferric Oxide Market
Chemicals
Pyrogallol Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Elemental Fluorine Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
1, 4 Butanediol Market
Chemicals
Potassium Fluoride Market
Chemicals
Inorganic Chemicals Market
Chemicals
Potassium Alum Market
Chemicals
India Ethoxylates Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Germany Methanol Market
Chemicals
Sodium Aluminum Hydride Market