
 Copper Foil Market | 2026-2036
Copper Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Foil Market Intelligence
The IATF 16949 automotive quality management standard is bifurcating the competitive landscape, separating suppliers qualified for electric vehicle battery applications from those serving general electronics. South Korea's SKC Inc. specializes in ultra-thin foils for next-generation batteries. Competitor ILJIN Materials leverages its extensive production capacity to serve high-volume gigafactory clients. Meanwhile, JX Nippon Mining & Metals positions its treated foils for high-frequency printed circuit board applications.
Copper foil is a thin sheet of high-purity copper produced via electrodeposition to achieve thicknesses as low as 9µm for battery applications. Its primary function is to act as a current collector in lithium-ion battery anodes or as a conductive layer in printed circuit boards. Demand from the lithium-ion batteries application is rapidly eclipsing the historically dominant printed circuit boards segment. Electrodeposited foil maintains the largest share due to its suitability for battery manufacturing, while rolled foil serves niche, high-performance electronics.
Material composition and market access are governed by regulations like the EU's RoHS and REACH directives, which restrict hazardous substances in electronics. In parallel, China's GB standards dictate performance requirements for foils used in domestic battery production. Supplier success now depends on securing long-term offtake agreements with battery and EV manufacturers to justify capital-intensive capacity expansions.
Market Dynamics
The bifurcation of the market between automotive-grade battery foils and standard electronics foils is the central dynamic. This separation, driven by stringent quality standards like IATF 16949, is creating distinct competitive arenas and supply chain requirements for producers.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act and EU Green Deal stimulate domestic battery production, directly increasing regional demand for anode-grade copper foil.
- Gigafactory Expansion:Massive investment in battery gigafactories in China creates concentrated, high-volume demand requiring dedicated foil production capacity.
- Technology Advancement:The push for higher battery energy density drives development of ultra-thin foils, creating a premium segment for next-generation anode performance.
Market Restraints
- Capital Intensity:High capital expenditure for electrodeposition lines and cleanroom facilities acts as a significant barrier to entry for new competitors.
- Energy Consumption:The energy-intensive electrodeposition process exposes manufacturers to electricity price volatility and carbon regulations in regions like the European Union.
- Input Cost Volatility:Production costs are tied to high-purity copper feedstock prices, which fluctuate on global commodity markets and create margin pressure.
Strategic Opportunities
- High-Frequency Electronics:Demand for treated rolled copper foil in 5G infrastructure and ADAS applications creates a high-margin niche separate from the battery sector.
- Battery Circularity:Recovering high-purity copper from end-of-life batteries aligns with EU battery passport regulations and creates a secondary supply source.
- Solid-State Batteries:Research into copper foil's role in emerging solid-state battery architectures presents a long-term growth pathway for specialized foil products.
Industry Challenges
- Quality Control Complexity:Maintaining uniform thickness and purity at sub-10 micron levels for battery-grade foil requires sophisticated process controls and extensive quality assurance systems.
- Automotive Qualification:The IATF 16949 automotive quality standard imposes lengthy and rigorous qualification processes for suppliers seeking to enter the EV battery supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Foil Market |
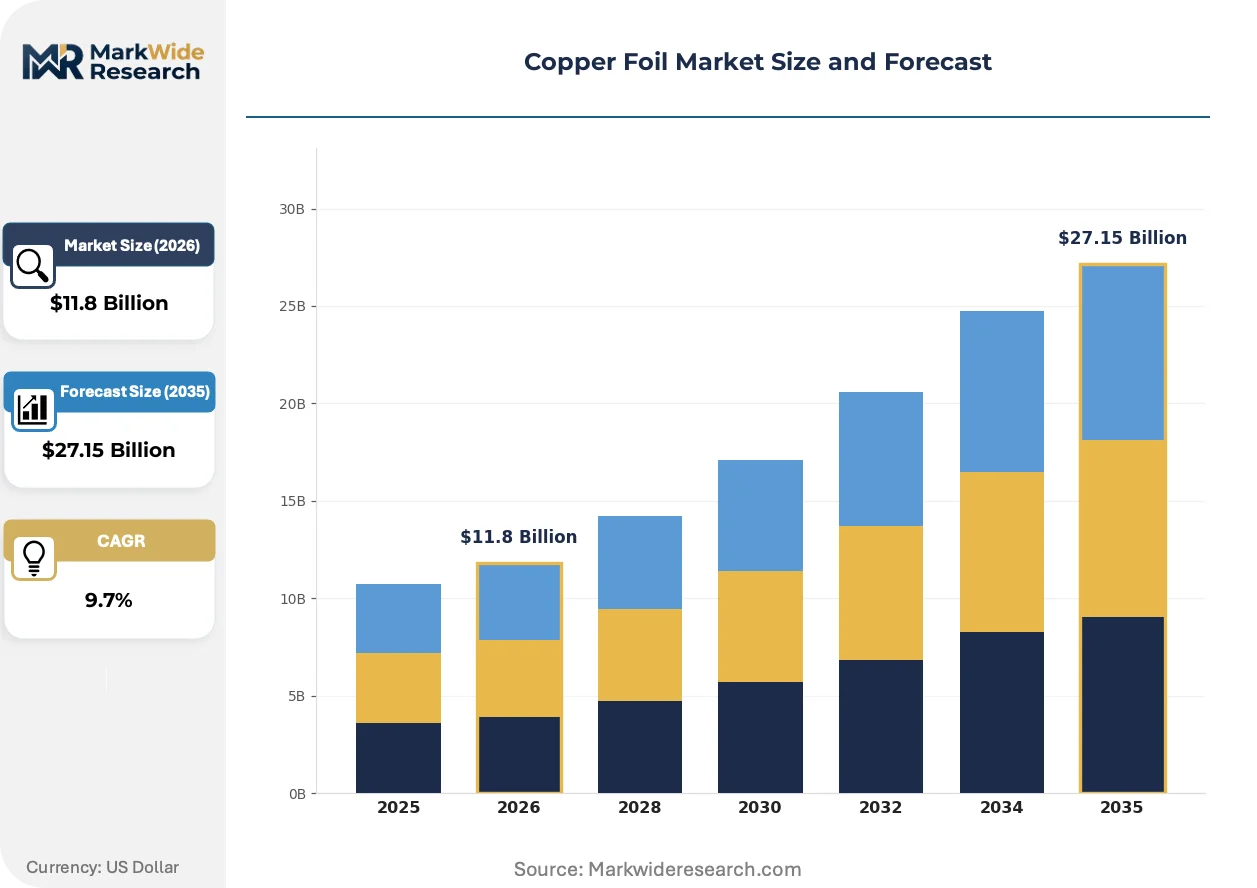
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $27.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodeposited, Rolled, High-Strength, Chemically Treated, Others Application: Printed Circuit Boards, Lithium-Ion Batteries, Capacitors, EMI/RFI Shielding, Transformers Thickness: 9µm, 12µm, 18µm, 35µm, 70µm End User: Consumer Electronics Manufacturers, Electrical Equipment Firms, Battery Makers, Telecommunication Companies |
| Companies Covered | Chang Chun Group, ILJIN Materials Co. Ltd., Mitsui Mining & Smelting Co. Ltd., Circuit Foil Luxembourg, SKC Inc., Furukawa Electric Co. Ltd., LS Mtron Ltd., Nan Ya Plastics Corporation, JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Foil Market Strategic Shifts & Innovations
The copper foil market is bifurcating into two distinct pathways. One path involves massive-scale, standardized production for lithium-ion batteries, while the other focuses on high-performance, specialized foils for advanced electronics and next-generation energy storage.
Ultra-thin copper foils, with thicknesses below 9µm, are engineered to increase the energy density of lithium-ion batteries. Electric vehicle battery manufacturers are rapidly adopting these thinner foils to achieve longer vehicle ranges and faster charging capabilities. This advanced material is supplanting thicker, conventional foils in next-generation anode designs for high-performance battery cells.
European Union directives like REACH and RoHS regulate hazardous substances in electronic components, including chemicals for treating copper foil. This forces PCB foil makers to ensure compliance through documentation and testing for market access. The high-frequency PCB segment is most affected, with suppliers reformulating surface treatments to meet these standards.
A shift toward long-term offtake agreements defines supplier relationships in the battery sector. EV manufacturers are securing multi-year supply contracts instead of using spot markets, justifying supplier capacity expansions. This model is most prominent in North America and Europe where new gigafactories are built upon these committed volumes.
Copper Foil Market Segmentation
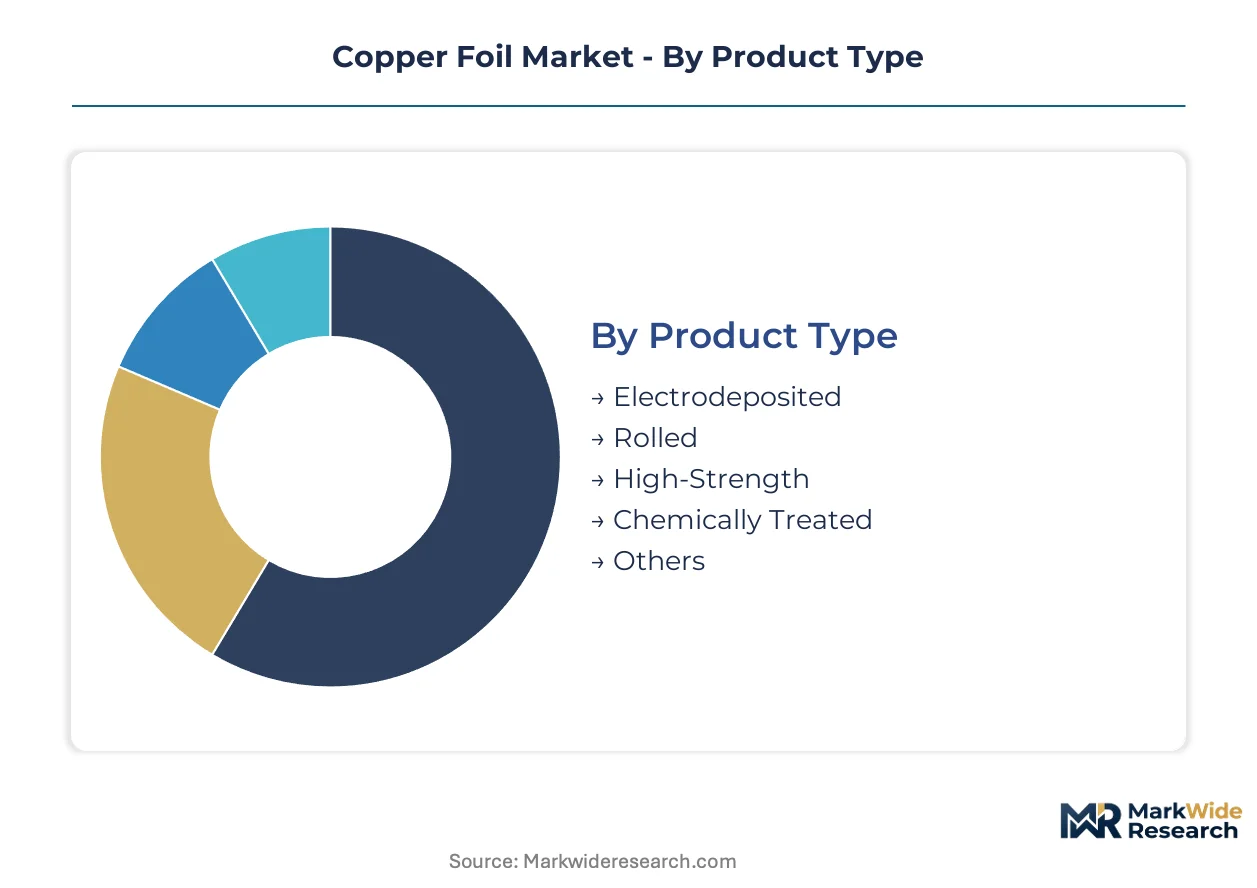
The copper foil market segmentation reflects the diverse technical requirements and end-use applications driving demand across various industries. Each segment presents unique challenges and opportunities for manufacturers, influencing material specifications, production processes, and market access strategies. Understanding these distinct segments is crucial for navigating the evolving competitive landscape.
Product Type:
Margin pools within the product type category reflect the specialized manufacturing processes and performance characteristics each foil variant offers.
- Electrodeposited:This foil is produced via electrodeposition, achieving thicknesses as low as 9µm for battery applications. Demand concentrates in China and South Korea for lithium-ion battery anodes, driven by electric vehicle production.
- Chemically Treated:This process involves surface modification to enhance adhesion and corrosion resistance for specific applications. Demand is strong in high-frequency printed circuit boards in Japan and Taiwan, where signal integrity is critical.
- Rolled:Rolled copper foil serves niche, high-performance electronics and certain flexible circuit applications due to its superior mechanical properties.
- High-Strength:High-strength foil is engineered for applications requiring enhanced durability and fatigue resistance, often found in demanding industrial electronics.
- Others:This category includes various specialty foils tailored for unique electrical or thermal management requirements in advanced systems.
Electrodeposited foil holds significant installed capacity. Chemically Treated foil is rotating up the share rankings.
Application:
Cost tiers across application segments are influenced by material purity requirements and processing complexity.
- Lithium-Ion Batteries:Copper foil functions as the anode current collector, requiring ultra-thin foils with high purity and uniform thickness. Demand is concentrated in North America and Europe, stimulated by the IRA and EU Green Deal for EV battery production.
- Printed Circuit Boards:This application provides a conductive layer for electronic components, with varying thickness and surface treatment needs. Demand is strong in consumer electronics manufacturing in Southeast Asia, driven by smartphone and computing device production.
- Capacitors:Capacitors employ thin copper foils as electrodes in certain capacitor types, contributing to energy storage and discharge functions.
- EMI/RFI Shielding:This segment utilizes copper foil for electromagnetic interference suppression in sensitive electronic devices, protecting signal integrity.
- Transformers:Transformers use copper foil in windings for compact and efficient power conversion, particularly in high-frequency designs.
Lithium-Ion Batteries are gaining share fastest, while Printed Circuit Boards maintain a substantial volume base.
Thickness:
Volume consumption in the thickness category directly correlates with specific end-use requirements and performance targets.
- 9µm:This represents ultra-thin foils crucial for maximizing energy density in next-generation lithium-ion batteries. Demand is surging from EV battery gigafactories in Germany and the United States, pushing for longer range capabilities.
- 18µm:This is a standard thickness widely adopted for general-purpose printed circuit board manufacturing and various electronic components. Demand is consistent across global electronics production hubs, including Vietnam and Mexico, for diverse applications.
- 12µm:This thickness offers a balance between performance and material usage, finding application in advanced PCBs and some battery designs.
- 35µm:This thickness is typically used for higher current applications or where greater mechanical strength is required, such as power electronics.
- 70µm:This represents thicker foils, often employed in high-power distribution, busbars, or specialized industrial equipment.
9µm foils are experiencing the steepest expansion trajectory. 70µm foils serve established, specialized industrial demands.
End User:
Customer types within the end-user category exhibit distinct procurement strategies and quality assurance standards.
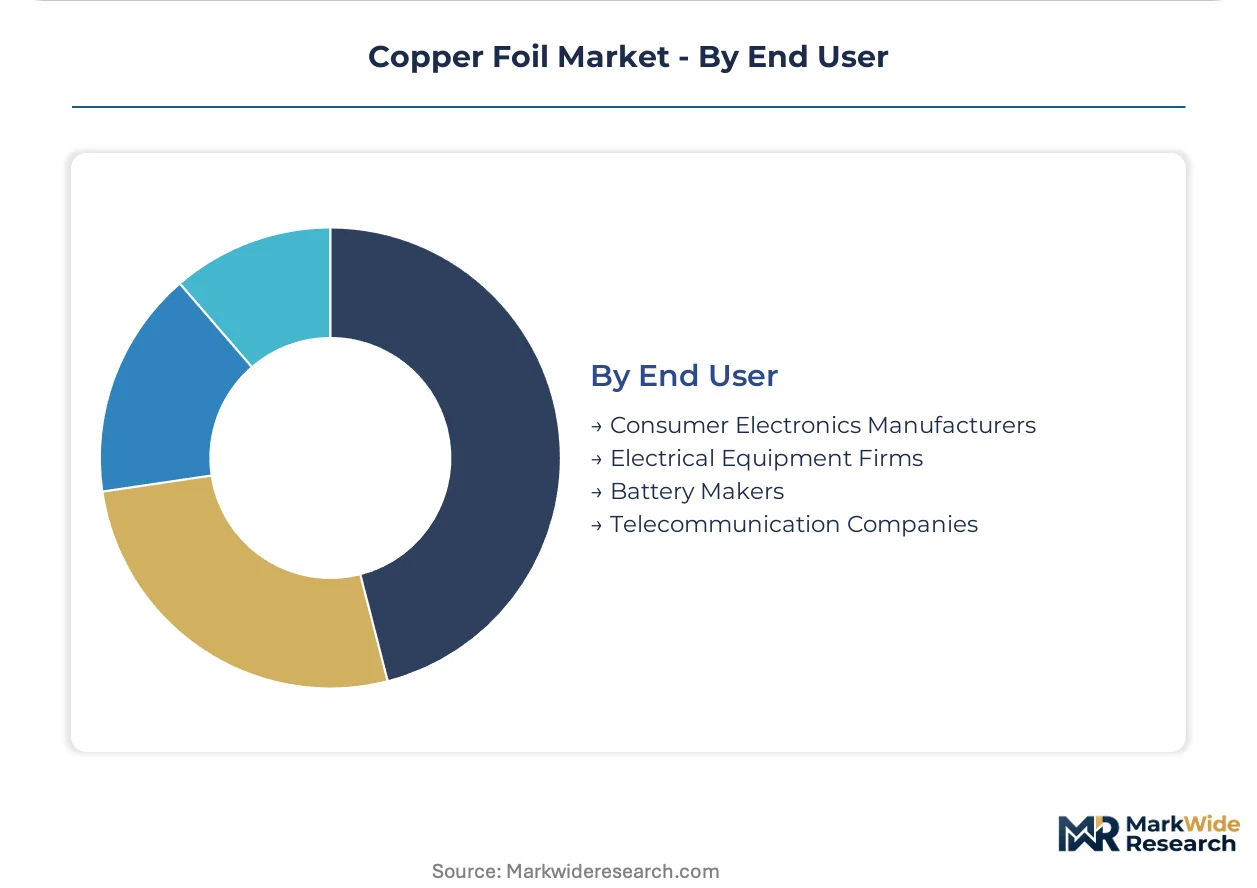
- Battery Makers:These firms require IATF 16949 certified foils with stringent purity and dimensional stability for lithium-ion cell production. Demand is driven by EV production in South Korea and China, necessitating long-term offtake agreements.
- Consumer Electronics Manufacturers:These companies utilize copper foil for PCBs in smartphones, laptops, and tablets, balancing cost-effectiveness with performance. Demand is high in India and Brazil, fueled by a growing middle class and increasing device penetration.
- Electrical Equipment Firms:These companies procure copper foil for power distribution, transformers, and industrial control systems, prioritizing reliability and conductivity.
- Telecommunication Companies:These companies employ copper foil in network infrastructure, including 5G base stations and data centers, for high-frequency signal integrity.
Battery Makers are driving significant capacity expansions. Consumer Electronics Manufacturers represent a broad and consistent demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act and the EU Green Deal are stimulating domestic battery production, directly increasing regional demand for anode-grade copper foil. This policy-driven growth is reshaping investment flows and manufacturing footprints across key global regions. Significant capacity expansions are underway to meet the escalating requirements of the electric vehicle sector.
China
Demand for electrodeposited foil is concentrated in China for lithium-ion battery anodes. China's GB standards dictate performance requirements for foils used in domestic battery production, ensuring quality. Massive investment in battery gigafactories in cities like Ningde and Guangzhou creates concentrated, high-volume demand.
United States
The US Inflation Reduction Act directly increases regional demand for anode-grade copper foil. This policy incentivizes domestic battery manufacturing, driving new factory construction. EV battery gigafactories in states like Georgia and Michigan are pushing for longer vehicle ranges with ultra-thin foils.
South Korea
South Korea's battery makers require IATF 16949 certified foils with stringent purity for lithium-ion cell production. The country's industrial policies support advanced materials development for electric vehicle components. Companies like SKC Inc. in Suwon specialize in ultra-thin foils for next-generation battery applications.
Germany
European Union directives like REACH and RoHS regulate hazardous substances in electronic components, including copper foil. The EU Green Deal stimulates domestic battery production within the region. EV battery gigafactories in areas like Brandenburg and Lower Saxony are driving demand for 9µm foils.
Japan
High-frequency printed circuit boards in Japan drive demand for chemically treated foil where signal integrity is critical. METI's industrial policies encourage innovation in advanced materials for electronics. JX Nippon Mining & Metals in Tokyo positions its treated foils for high-frequency PCB applications.
Copper Foil Market Key Industry Players
Player mix skews toward established electrodeposition specialists and diversified materials conglomerates. The market structure exhibits a tiered consolidation, with a few large-scale producers dominating the battery-grade segment due to stringent qualification requirements. Strategic archetypes include high-volume battery foil suppliers and niche providers of specialized foils for high-frequency electronics, each with distinct market access strategies. Competitive moves center on capital-intensive capacity expansion, securing long-term offtake agreements with major battery manufacturers, and continuous process innovation.
Within the specialized materials tier, South Korean-based SKC Inc. exemplifies producers focusing on ultra-thin foils for next-generation batteries. ILJIN Materials Co. Ltd., also from South Korea, represents the high-volume capacity providers serving gigafactory clients. JX Nippon Mining & Metals Corporation, a Japanese entity, occupies a position among suppliers of treated foils for high-frequency printed circuit board applications. These firms anchor distinct segments of the copper foil market, from advanced battery components to specialized electronics.
| Leading Market Players |
|---|
| Chang Chun Group |
| ILJIN Materials Co. Ltd. |
| Mitsui Mining & Smelting Co. Ltd. |
| Circuit Foil Luxembourg |
| SKC Inc. |
| Furukawa Electric Co. Ltd. |
| LS Mtron Ltd. |
| Nan Ya Plastics Corporation |
| JX Nippon Mining & Metals Corporation |
| Others |
Cost & Logistics Intelligence
Ultra-thin copper foil adoption for battery applications simultaneously reshapes supply geography towards Asian and North American production hubs and elevates pricing economics for specialized, high-performance grades.
Pricing Analysis
Certification level, specifically IATF 16949, creates the primary spread in copper foil pricing. The dominant pricing model for battery-grade foil is contract-based long-term offtake agreements. Price differentiation stems from material purity requirements and the stringency of quality assurance systems. Pricing pressure stems from input cost volatility, particularly for high-purity copper feedstock, impacting standard foil margins. Consumer electronics manufacturers exhibit the highest price sensitivity, whereas EV battery makers prioritize performance and certification over marginal cost savings.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized chemicals and high-purity copper, influence regional supply chain configurations. Geographic supply concentration for electrodeposited foil centers on China and South Korea, with emerging capacity in the United States and Germany. The market draws from critical dependencies on high-purity copper feedstock and specialized chemicals for surface treatment. A structural risk involves commodity price volatility for copper, creating margin pressure for manufacturers. Distribution runs through direct sales channels for battery makers and specialized distributors for diverse electronics applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The copper foil market presents an early-cycle expansion story, driven by the accelerating penetration of electric vehicles and the associated global buildout of battery gigafactories.
For Market Incumbents: Fortify long-term offtake agreements with major battery and EV manufacturers to de-risk capital-intensive capacity expansions. Invest strategically in IATF 16949 certification processes to counter the threat from new regional competitors spurred by policy incentives. Expand production capacity for ultra-thin foils in North America and Europe, leveraging R&D to meet next-generation battery performance requirements.
For New Entrants and Emerging Players: Differentiate on specialized product performance for high-frequency electronics or emerging battery chemistries. Target niche, high-margin segments such as treated rolled copper foil for 5G infrastructure and ADAS applications. A penetrable segment exists in specific regional battery markets with strong policy support, allowing for a focused go-to-market strategy through partnerships with specialized battery startups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established electrodeposition specialists possessing advanced process controls and IATF 16949 certification. The market demonstrates long-term viability, underpinned by sustained demand from the electric vehicle sector and advanced electronics. Identify acquisition targets with strong intellectual property in ultra-thin foil manufacturing or unique surface treatment technologies. The signal to watch is the accelerated adoption rate of 9µm foils in new gigafactory production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | Secures long-term supply for gigafactories, mitigating regional demand spikes. |
| R&D in Ultra-Thin Foils | Drives higher energy density in lithium-ion batteries, enhancing EV performance. |
| IATF 16949 Certification | Unlocks access to stringent automotive battery supply chains in key markets. |
| Long-Term Offtake Agreements | Justifies capital-intensive capacity investments for foil manufacturers. |
| Battery Circularity Investment | Aligns with EU regulations, creating a secondary copper supply source. |
Research Approach
A standing panel of battery production executives, PCB design engineers, material scientists, and EV manufacturers provided ongoing calibration and validation for market insights. The research methodology combined extensive primary interviews with detailed secondary research from regulatory filings, trade association reports, government energy reports, and patent databases. This approach ensured a robust bottom-up and top-down triangulation of market data.
Market volume and value outputs underwent consistency checks against external benchmarks across the analysis window. The analytical framework modeled market segmentation across product type, application, thickness, end-user, and regional battery production capacity. Compound annual growth rates were derived from historical trends, projected demand drivers, and specific forecast inputs like EV production forecasts and battery gigafactory buildout schedules.
The analysis sits within stated boundaries; outcomes outside specific conditions would require recalibration. Forecasts reflect assumptions regarding technological stability and regulatory frameworks. Specific risk factors, including sudden shifts in battery chemistry, unexpected changes in raw material supply, or geopolitical trade policy, could revise these forecasts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Titanium Sponge Market
Metals
Iron Ore Market
Metals
Global Flat Steel Market
Metals
Copper Clad Aluminum Wire Market
Metals
Steel Drums and Ibcs Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Silver Enamel Market
Metals
Aluminum Flat-Rolled Products Market
Metals
India Steel Market
Metals
Saudi Arabia Aluminum Market
Metals
Osmium Market
Metals
Global Brass Rods Market
Metals
Anodized Titanium Market
Metals
Welding Materials Market
Metals
Smelting Chemicals Market
Metals
Global Stainless Steel Lashing Wire Market