
 Electrolytic Manganese Metal Market | 2026-2036
Electrolytic Manganese Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolytic Manganese Metal Market Analysis
Solid-state battery R&D is reconfiguring manganese cathode chemistry requirements, pushing purity thresholds beyond conventional specifications. Tianyuan Manganese Industry Group dominates electrolytic manganese capacity in China's Ningxia corridor. Tosoh Corporation specializes in ultra-high-purity grades for Japanese electronics customers. Mesa Minerals Limited anchors supply from Western Australia's emerging manganese belt.
Electrolytic manganese metal is a 99.7%+ pure manganese product refined through electrolysis of manganese sulfate solutions, valued for its low iron and phosphorus content in demanding metallurgical and chemical applications. Battery grade manganese commands premium pricing as cathode makers enforce stricter particle size and trace metal specifications for lithium-ion cells. High purity manganese sustains margins in aerospace alloy applications where contamination tolerance approaches single-digit parts per million. The alloys segment retains volume leadership through stainless steel desulfurization demand, though its growth lags battery applications.
China's SAMR enforces GB standards on electrolytic manganese purity and workplace emissions, while the EU Battery Regulation mandates recycled content quotas and supply chain due diligence for manganese entering European battery supply chains. EPA oversight of manganese particulate emissions shapes US smelter operating permits and equipment investment cycles. Stakeholders must track evolving cathode chemistry roadmaps from Korean and Japanese battery makers to anticipate grade-specific demand shifts before capacity commitments lock in.
Market Dynamics
Solid-state battery chemistry roadmaps are compressing purity specifications for electrolytic manganese metal, forcing suppliers to retool electrowinning circuits ahead of cathode qualification timelines.
Growth Catalysts
- Lithium-ion cathode densification:Energy density targets above 300 Wh/kg in Korean battery manufacturing are mandating battery-grade manganese with sub-50ppm iron thresholds.
- EU Battery Regulation recycled content mandates:The regulation's due diligence requirements for manganese entering European supply chains are accelerating investment in closed-loop refining infrastructure.
- China's dual carbon goals:SAMR enforcement of GB standards on electrolytic manganese emissions is consolidating capacity toward Ningxia's integrated industrial corridors.
Market Restraints
- Feedstock concentration risk:High-grade manganese ore dependency on South Africa's Kalahari basin and Gabon's Moanda belt creates single-source vulnerability for sulfate precursor production.
- Power cost volatility:Electrowinning's 4,500-6,000 kWh per ton electricity intensity exposes margins to regional grid pricing swings, particularly in China's industrial heartland.
- Technical ceiling on particle morphology:Conventional electrolytic deposition cannot achieve the spherical morphology required for high-loading cathode designs without downstream micronization capex.
Strategic Opportunities
- Western Australia supply corridor:Mesa Minerals' emerging manganese belt offers alternative sulfate feedstock for battery makers diversifying beyond African ore.
- Solid-state cathode chemistry convergence:Sulfide and oxide solid electrolyte interfaces are creating specifications for ultra-high-purity manganese that command 40-60% price premiums over standard battery grade.
- Direct shipping ore bypass:New port infrastructure at Port Hedland and Geraldton enables integrated mine-to-sulfate operations that compress logistics costs for Asian cathode clusters.
Industry Challenges
- Electrochemist talent scarcity:Deep expertise in manganese sulfate electrowinning resides with retiring cohorts at Chinese state-owned refiners, complicating technology transfer to new capacity builds.
- Cathode qualification timeline compression:Korean and Japanese cell makers are compressing supplier validation cycles from 24 months to 12 months, straining quality documentation systems.
- Legacy furnace asset stranding:Sub-99.5% purity electrolytic metal capacity in China's older industrial zones faces accelerated obsolescence under tightening SAMR workplace emission standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolytic Manganese Metal Market |
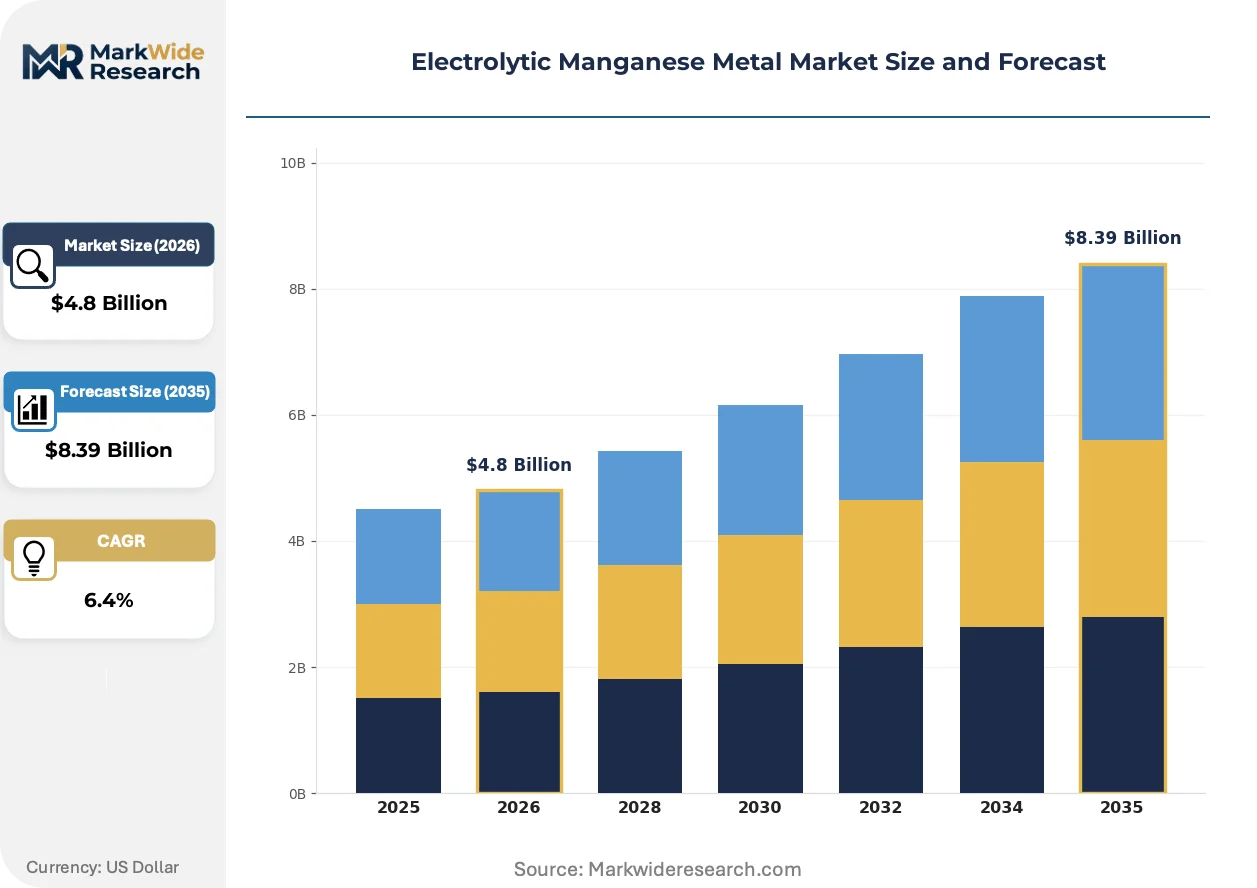
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity Manganese, Battery Grade Manganese, Electrolytic Manganese, Manganese Dioxide Application: Batteries, Alloys, Chemical Manufacturing, Electroplating End User: Automotive, Electronics, Metallurgy, Renewable Energy Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Mesa Minerals Limited, Tianyuan Manganese Industry Group, Tosoh Corporation, Umicore, Guangxi Dameng Manganese Industry Group, Manganese Metal Company, Nippon Denko, MOIL Limited, Euro Manganese Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolytic Manganese Metal Market Emerging Trajectories
Cathode chemistry evolution and carbon disclosure mandates are restructuring how electrolytic manganese metal is specified, priced, and sourced across battery supply chains.
Purification technology is migrating from conventional two-stage electrowinning to continuous ion-exchange polishing systems that strip residual calcium and magnesium to sub-10ppm levels. Tosoh Corporation's Japanese electronics customers pioneered these specifications, and Korean cathode material producers near Gwangyang are now mandating equivalent purity for high-nickel manganese cobalt formulations. The structural consequence is a bifurcation between commodity-grade metal for steel desulfurization and premium-grade product captive to battery supply agreements.
REACH's extended scoping for battery-critical raw materials is forcing manganese suppliers to deploy mass-balance accounting for carbon intensity disclosure across the electrowinning value chain. The EU Battery Regulation's recycled content quotas are particularly stringent for manganese entering cells manufactured in European gigafactories. German and French cathode precursor plants are responding by qualifying sulfate suppliers with verified Scope 3 emissions below 8 kg CO2 per kg metal.
Buyer concentration around South Korea's Gwangyang-Ulsan cathode cluster is compressing contract structures from annual tenders to quarterly price-volume negotiations indexed to London Metal Exchange manganese ore benchmarks. Long-term offtake agreements with fixed purity premiums are displacing spot procurement for battery-grade material. This behavioral shift is most pronounced among Korean conglomerates integrating backward into precursor manufacturing.
Electrolytic Manganese Metal Market Segmentation
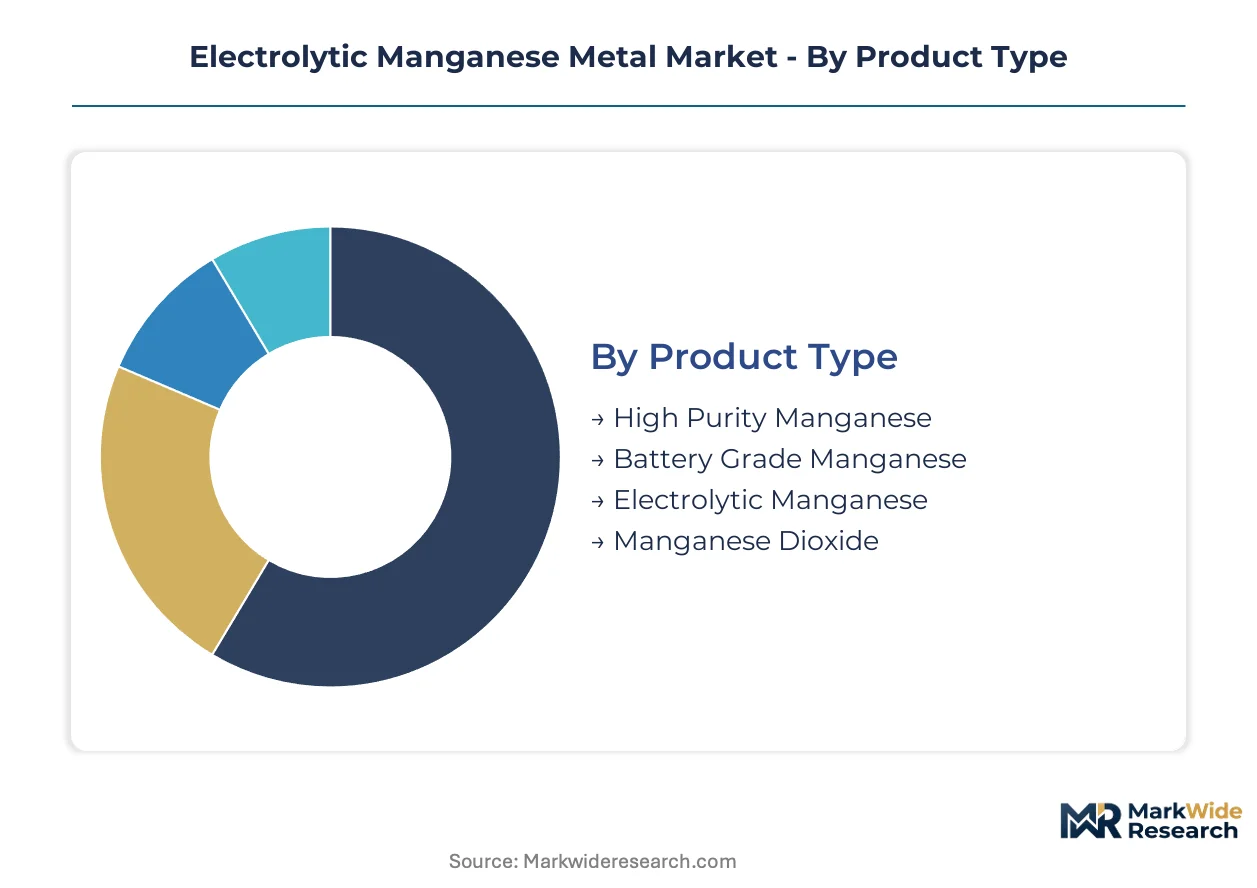
Electrolytic manganese metal specifications diverge sharply across end-use requirements, with battery cathode makers imposing purity thresholds that legacy steel desulfurization customers never demanded. Technical service intensity escalates with grade complexity, as ultra-high-purity shipments require certificate-of-analysis documentation and lot-traceability systems that commodity grades bypass entirely.
Product Type:
After-sales service intensity scales directly with purity tier, as battery-grade and high-purity segments demand technical troubleshooting, cathode qualification support, and regulatory documentation that commodity electrolytic metal never requires.
- High Purity Manganese:99.9%+ manganese content with sub-10ppm calcium and magnesium specifications serves Japanese electronics manufacturers and aerospace alloy producers. Korean cathode material plants near Gwangyang now mandate equivalent purity for high-nickel manganese cobalt formulations, compressing supplier validation timelines.
- Battery Grade Manganese:99.7-99.9% purity with sub-50ppm iron thresholds and controlled particle morphology for lithium-ion cathode loading. Energy density targets above 300 Wh/kg in Korean battery manufacturing are tightening trace metal specifications faster than electrowinning circuits can adapt.
- Electrolytic Manganese:Standard 99.7% purity metal for steel desulfurization and general metallurgical applications.
- Manganese Dioxide:Primary battery cathode material and chemical oxidation agent with lower purity requirements than electrolytic metal grades.
By volume, Electrolytic Manganese leads. By growth pace, Battery Grade Manganese is gaining share fastest.
Application:
Cost tier stratification separates premium battery applications from commodity metallurgical uses, with cathode-grade material commanding 40-60% price premiums over standard specifications.
- Batteries:Lithium-ion cathode precursors and primary cell manufacturing drive the steepest demand expansion. Solid-state battery R&D is reconfiguring manganese chemistry requirements, pushing purity thresholds beyond conventional electrowinning capabilities.
- Alloys:Stainless steel desulfurization and specialty metallurgical additives retain volume leadership. China's Ningxia corridor dominates this segment through integrated mine-to-metal operations with lower technical service overhead.
- Chemical Manufacturing:Manganese sulfate and other derivative production for agricultural and industrial chemicals.
- Electroplating:Decorative and functional coating applications with moderate purity requirements.
Alloys generate the highest shipment volumes. Batteries exhibit the most rapid demand acceleration.
End User:
Customer type concentration around integrated battery conglomerates is compressing procurement structures from annual tenders to quarterly negotiations with stringent qualification documentation.
- Automotive:Electric vehicle battery supply chains dominate premium-grade procurement. EU Battery Regulation due diligence requirements are forcing manganese suppliers to deploy mass-balance accounting for carbon intensity disclosure.
- Electronics:Tosoh Corporation's Japanese customer base pioneered ultra-high-purity specifications now migrating to Korean cathode producers.
- Metallurgy:Stainless steel mills and specialty alloy foundries represent stable, price-sensitive demand with lower service intensity.
- Renewable Energy:Grid-scale battery storage systems emerging as a specification bridge between automotive and industrial grades.
Metallurgy absorbs the most tonnage. Automotive is climbing the fastest.
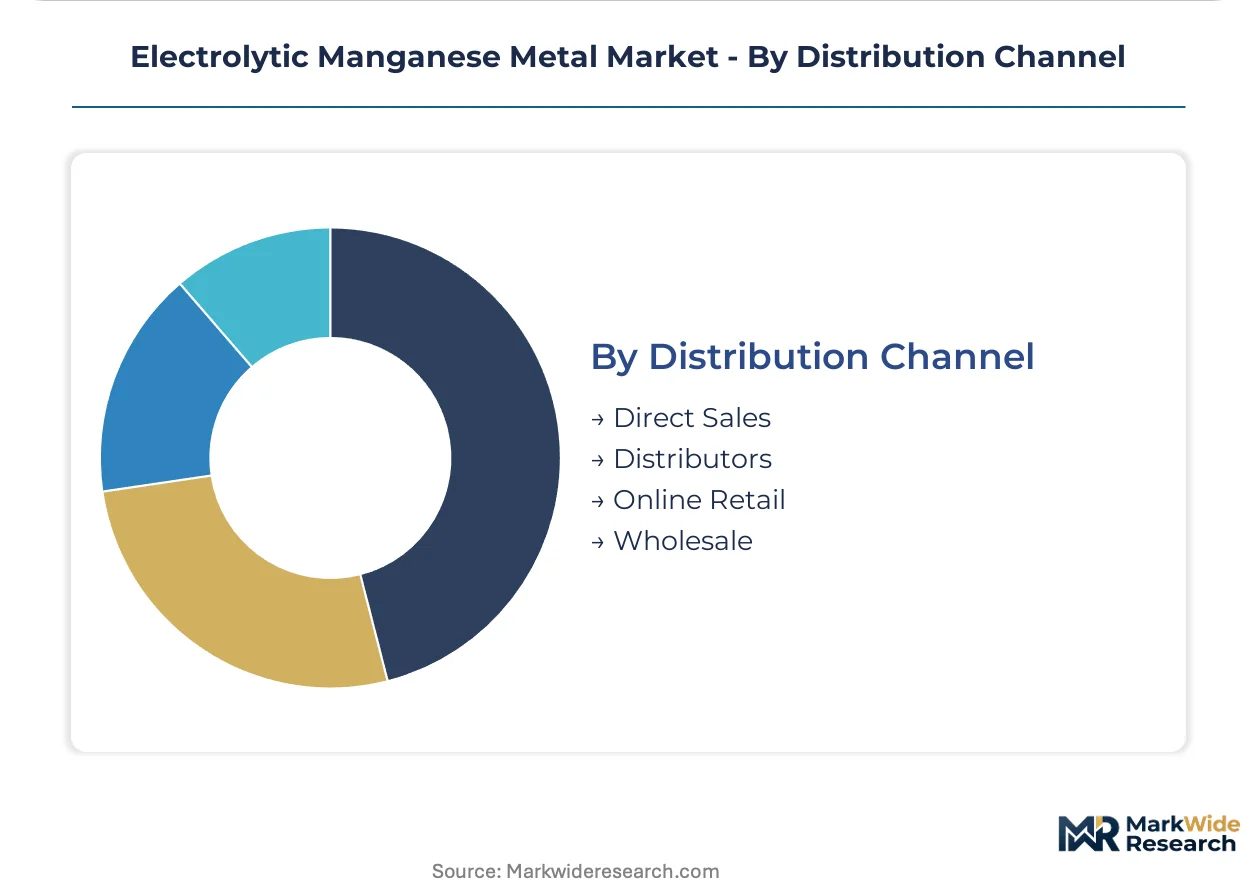
Distribution Channel:
Supply concentration in China's Ningxia corridor and emerging Western Australia operations shapes channel economics, with direct sales dominating high-volume battery supply agreements.
- Direct Sales:Long-term offtake agreements with fixed purity premiums displace spot procurement for battery-grade material. Korean conglomerates integrating backward into precursor manufacturing favor this channel.
- Distributors:Regional stocking operations serve fragmented steel desulfurization customers with lower technical requirements.
- Online Retail:Limited to laboratory and small-batch industrial chemical procurement.
- Wholesale:Bulk commodity-grade shipments to trading houses for resale to unspecified end-users.
Direct Sales command the highest value flow. Distributors handle the broadest customer count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningxia corridor exports battery-grade electrolytic manganese metal to South Korean cathode clusters near Gwangyang and Ulsan, establishing the dominant trade-flow corridor in this market.
China
SAMR enforcement of GB standards on electrolytic manganese emissions is consolidating capacity toward Ningxia's integrated industrial corridors. The dual carbon goals are accelerating closure of sub-99.5% purity furnace assets in older industrial zones. Tianyuan Manganese Industry Group anchors supply from this corridor, serving both domestic battery makers and export contracts.
South Korea
Energy density targets above 300 Wh/kg are mandating battery-grade manganese with sub-50ppm iron thresholds from cathode material producers. MFDS oversight of battery material safety standards shapes import qualification protocols for manganese sulfate precursors. The Gwangyang-Ulsan cluster is compressing supplier validation cycles from 24 months to 12 months.
Japan
Ultra-high-purity specifications pioneered by electronics manufacturers are migrating to solid-state battery R&D programs. METI technology roadmaps for next-generation cells are reconfiguring manganese chemistry requirements beyond conventional electrowinning capabilities. Tosoh Corporation's customer base in this market commands sub-10ppm calcium and magnesium thresholds.
Australia
Mesa Minerals Limited anchors emerging sulfate feedstock supply from Western Australia's manganese belt for battery makers diversifying beyond African ore. New port infrastructure at Port Hedland and Geraldton enables integrated mine-to-sulfate operations that compress logistics costs. This corridor offers alternative procurement for Asian cathode clusters seeking supply chain resilience.
Belgium
Umicore's precursor manufacturing operations face stringent EU Battery Regulation due diligence requirements for manganese entering European gigafactories. REACH extended scoping for battery-critical raw materials is forcing mass-balance accounting for carbon intensity disclosure across the electrowinning value chain. Recycled content quotas are accelerating investment in closed-loop refining infrastructure serving German and French cathode plants.
Electrolytic Manganese Metal Market Vendor Landscape
On the supply side, the industry is consolidating around integrated mine-to-metal operators and specialized electrowinning refiners with cathode qualification capabilities. Capacity ownership fragments between Chinese state-affiliated groups controlling Ningxia corridor output and Western developers securing alternative sulfate feedstock. Three archetypes dominate: purity-tier specialists serving electronics and aerospace, battery-grade scale operators feeding Korean cathode clusters, and commodity-grade producers supplying stainless steel desulfurization. Competitive moves center on backward integration into manganese sulfate precursor production and geographic diversification away from South African ore dependency.
Among Australian-based developers, Mesa Minerals Limited occupies a position exemplifying the Western supply corridor archetype. Chinese state-affiliated groups represented by Tianyuan Manganese Industry Group and Guangxi Dameng Manganese Industry Group anchor the integrated mine-to-metal tier serving volume battery demand. Japanese specialists including Tosoh Corporation exemplify the ultra-high-purity archetype, with specifications now migrating to Korean cathode material producers near Gwangyang.
| Leading Market Players |
|---|
| Mesa Minerals Limited |
| Tianyuan Manganese Industry Group |
| Tosoh Corporation |
| Umicore |
| Guangxi Dameng Manganese Industry Group |
| Manganese Metal Company |
| Nippon Denko |
| MOIL Limited |
| Euro Manganese Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's legacy furnace zones is squeezing margins for sub-99.5% purity producers while tightening SAMR emission standards accelerate capacity consolidation toward Ningxia's integrated corridors. This utilization divergence hands pricing power to battery-grade specialists serving Korean cathode clusters, who capture fixed purity premiums through long-term offtake structures indexed to London Metal Exchange ore benchmarks.
Pricing Analysis
Conventional electrowinning circuits face widening price pressure against next-generation ion-exchange polishing systems that command 40-60% premiums for sub-10ppm calcium and magnesium specifications. Three-tier pricing structure across ultra-high-purity, battery-grade, and commodity metallurgical levels separates Japanese electronics customers from Korean cathode makers and stainless steel desulfurization buyers. Cost compression in commodity tiers stems from power cost volatility and furnace asset stranding under tightening GB standards. Steel mills exhibit highest price sensitivity, while solid-state battery developers accept premium positioning for qualification-grade material.
Supply Chain Analysis
Export-control scrutiny on battery-critical raw materials is reshaping qualification protocols for manganese sulfate entering European gigafactories under EU Battery Regulation due diligence mandates. Supply concentrates in China's Ningxia corridor, South Korea's Gwangyang-Ulsan cluster, and Western Australia's emerging manganese belt. Electrowinning operations draw from high-grade ore feedstock anchored in South Africa's Kalahari basin and Gabon's Moanda belt. Single-source vulnerability for sulfate precursor production creates structural exposure to African supply disruptions. Distribution runs through direct sales channels for battery-grade offtake agreements, with distributors serving fragmented metallurgical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery chemistry roadmaps are disrupting purity specifications faster than conventional electrowinning circuits can adapt, creating asymmetric opportunity for suppliers with ion-exchange polishing capabilities.
For Market Incumbents: Entrench battery-grade positioning by accelerating backward integration into manganese sulfate precursor production and securing Western Australia feedstock alternatives before Mesa Minerals' corridor reaches full capacity. Threats from Korean conglomerates integrating backward into precursor manufacturing demand captive supply control. Certification investment in EU Battery Regulation compliance and Scope 3 emissions documentation represents the critical defensive lever. For New Entrants and Emerging Players: Build out ion-exchange polishing capacity targeting the specification gap between Tosoh Corporation's ultra-high-purity electronics grades and standard battery-grade output. Western Australia offers the most penetrable geography given new port infrastructure at Port Hedland and Geraldton enabling integrated mine-to-sulfate operations. Go-to-market execution should anchor on cathode qualification support services that compress Korean and Japanese cell makers' validation timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ion-exchange purification infrastructure as solid-state battery programs mandate sub-10ppm thresholds. Long-term viability over the next decade favors operators with dual capability in electrowinning and downstream sulfate precursor production. Acquisition targets should display verified cathode qualification relationships with Korean or Japanese battery makers. The signal to watch is compressed supplier validation cycles accelerating from 24 months toward 12 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfate Precursor Production | Captive supply control defends margin position against Korean conglomerate verticalization. |
| Ion-Exchange Polishing Capacity Expansion | Sub-10ppm calcium and magnesium capability unlocks solid-state battery qualification premiums. |
| Western Australia Feedstock Diversification | Mesa Minerals' corridor reduces African ore dependency for Asian cathode clusters. |
| EU Battery Regulation Compliance Certification | Mass-balance accounting for Scope 3 emissions enables European gigafactory access. |
| Cathode Qualification Support Services | Technical documentation acceleration addresses Korean cell makers' compressed validation timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SAMR regulatory filings, SEC 10-K disclosures from listed materials companies, and London Metal Exchange manganese ore benchmarks. Primary interviews engaged electrowinning plant managers, cathode material procurement leads at Korean battery makers, distribution channel partners in metallurgical supply chains, and technical R&D directors at Japanese electronics manufacturers. Bottom-up capacity modeling triangulated against top-down demand segmentation across purity tiers and end-use applications.
Forecast inputs span electrowinning capacity utilization rates, cathode chemistry roadmaps from Korean and Japanese battery makers, SAMR emission standard enforcement trajectories, and EU Battery Regulation recycled content quota implementation. Segmentation dimensions modeled include purity grade tier, end-use industry split between batteries and metallurgy, regional production hub concentration, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion timelines across the analysis window.
Stress conditions across African ore supply disruptions, Chinese power grid pricing volatility, and solid-state battery chemistry convergence timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cathode qualification cycle compression and SAMR enforcement intensity. Material shifts in EU Battery Regulation due diligence requirements or Korean energy density target acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zinc Plating Market
Metals
Liquid Metal Thermal Pad Market
Metals
Powder Metallurgy Market
Metals
Chrome Metal Powder Market
Metals
Ore Metals Market
Metals
Ferro Aluminum Market
Metals
Scandium Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Steel Ingots Market
Metals
Beryllium Copper Billet Market
Metals
Global Chromium Market
Metals
Brazil Aluminum Market
Metals
Pump Casing Materials Market
Metals
North America Aluminum Casting Market
Metals
Aluminum Wire Market
Metals
Aluminum Hot Rolling Mill Market