
 Zinc Plating Market | 2026-2036
Zinc Plating Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Plating Market Outlook
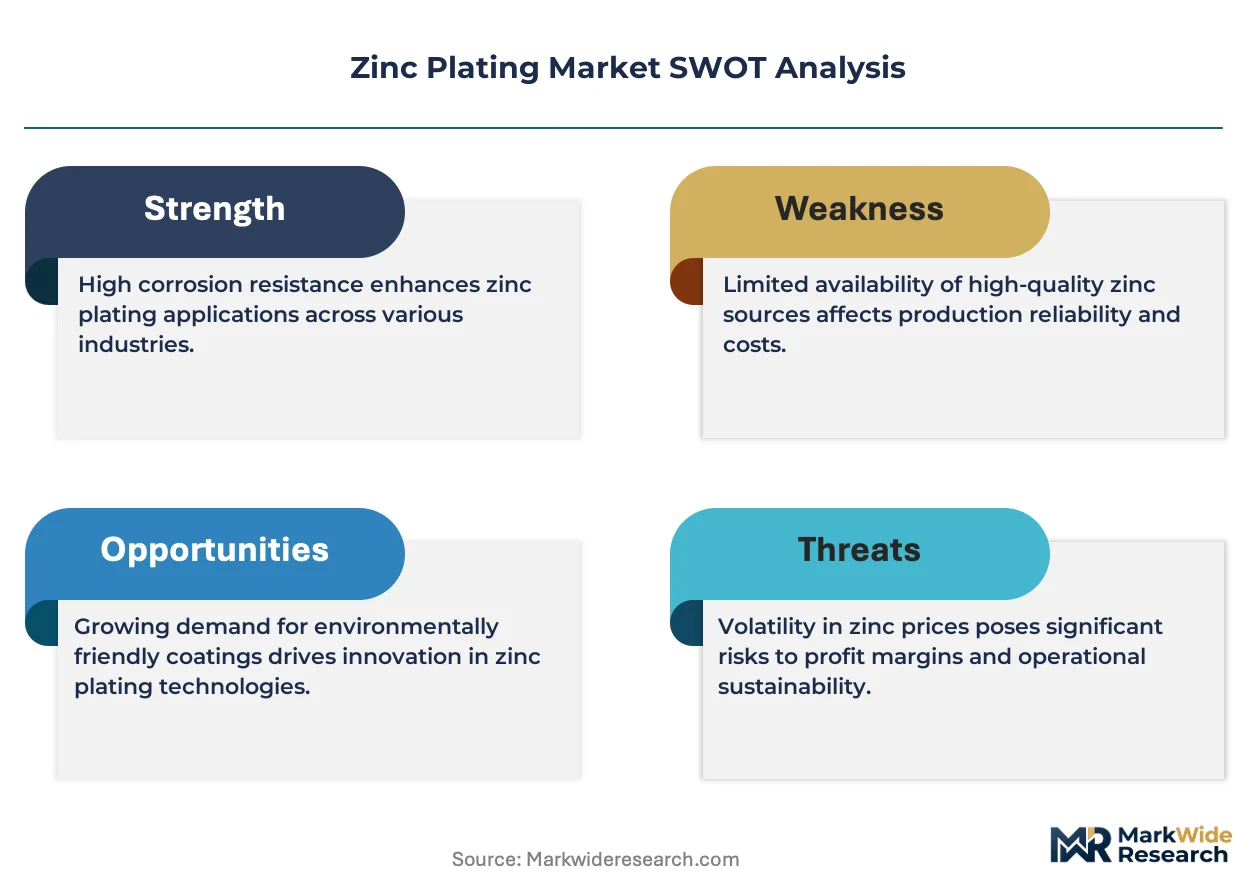
ISO 14001 environmental management certification is bifurcating the supplier base into qualified tier-1 finishers and unaccredited local shops. Sharretts Plating Company leverages its AS9100 and NADCAP credentials to anchor aerospace and defense contracts across the northeastern United States. Chem Processing sustains a dense network of OEM approvals from Deere, Caterpillar, and Boeing, which locks in multi-year finishing agreements with penalty clauses for qualification lapses.
Zinc plating deposits a sacrificial metallic layer, typically 5–25 microns thick, onto steel or iron substrates through electrolytic reduction of zinc salts in alkaline or acid baths, primarily to prevent oxidative corrosion in atmospheric and marine environments. Corrosion-Resistant Coating and Zinc-Nickel Alloy segments command premium pricing due to salt-spray requirements exceeding 1,000 hours in automotive underbody applications. Electrolysis Process technology dominates volume production, though Plating Bath innovations in ionic liquid formulations are displacing conventional cyanide and chloride chemistries in European facilities facing ECHA scrutiny.
EPA effluent guidelines under the Clean Water Act, REACH Annex XVII restrictions on carcinogenic passivates, and China's MEE emission standards for electroplating workshops collectively raise compliance capital requirements by forcing facility upgrades or exit. The EU F-Gas Regulation and forthcoming CSRD disclosure rules will further tighten traceability demands on coating supply chains serving exported machinery. Stakeholders must monitor which national regulators next mandate hexavalent chromium phase-outs, as this determines where captive plating investments relocate and which process technologies achieve scalable certification.
Market Dynamics
REACH Annex XVII restrictions on hexavalent chromium passivates and China's GB standards on heavy-metal emissions are forcing plating facilities to retool toward trivalent chemistries and alkaline zinc-nickel systems, bifurcating the supplier base into accredited tier-1 finishers and unqualified local shops.
Growth Catalysts
- Automotive OEM procurement:German, Japanese, and US automakers are expanding orders for corrosion-resistant fasteners and chassis components requiring salt-spray performance exceeding 1,000 hours.
- REACH regulatory pressure:The EU's phasedown of carcinogenic passivates is accelerating facility upgrades and creating first-mover advantages for compliant finishers.
- India's PLI-linked manufacturing:Production-linked incentive schemes in Pune and Chennai industrial corridors are drawing plating capacity toward automotive and electronics export hubs.
Market Restraints
- Zinc ingot price volatility:London Metal Exchange price swings for primary zinc directly compress margins for job-shop finishers lacking long-term supply contracts.
- Captive plating concentration:Large automotive Tier-1 suppliers in Germany and Japan have internalized high-volume lines, shrinking the addressable merchant market.
- Alkaline zinc-nickel technical barriers:Bath chemistry control and anode dissolution management require specialized expertise absent in generalist plating operations.
Strategic Opportunities
- Underpenetrated US aerospace finishing:AS9100 and NADCAP-certified capacity remains scarce in the northeastern United States, creating white space for qualified entrants.
- EU F-Gas Regulation compliance services:Traceability and disclosure mandates under forthcoming CSRD rules will generate recurring revenue from coating supply chain auditing.
- Ionic liquid chemistry convergence:Non-aqueous electrolyte formulations are opening pathways to eliminate cyanide and chloride chemistries in European facilities facing ECHA scrutiny.
Industry Challenges
- Environmental compliance capex intensity:EPA effluent guideline upgrades under the Clean Water Act and MEE emission standards in China require six-figure wastewater treatment investments.
- ISO 14001 certification timeline:The 12-18 month accreditation process for environmental management systems delays qualification for OEM approved-vendor lists.
- Legacy bath conversion complexity:Retooling from hexavalent to trivalent passivation lines disrupts production continuity and risks customer qualification lapses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Plating Market |
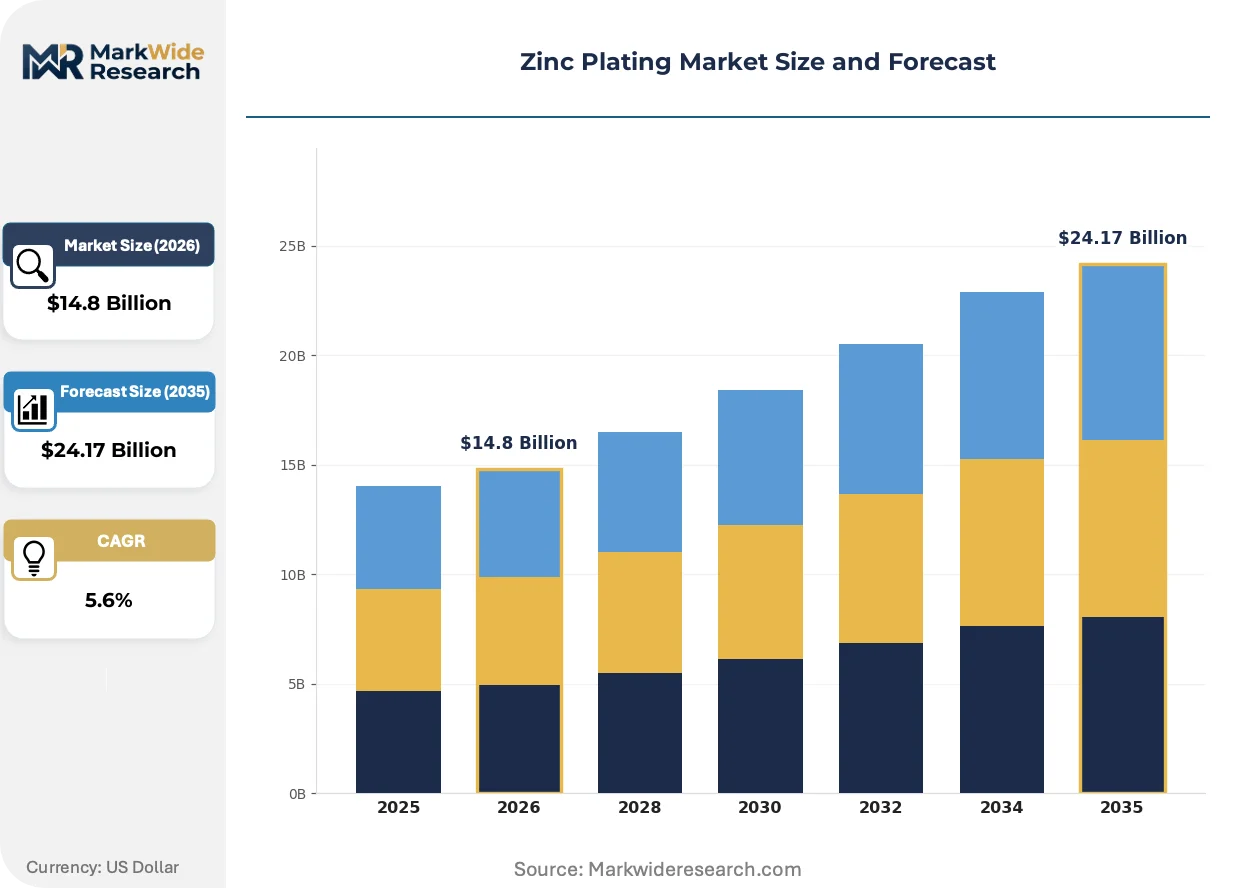
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion-Resistant Coating, Electroplated Zinc, Hot-Dip Zinc, Zinc-Nickel Alloy Application: Automotive Parts, Industrial Equipment, Construction Hardware, Electrical Components End User: Manufacturing, Construction, Aerospace, Electronics Technology: Electrolysis Process, Anodizing, Thermal Spraying, Plating Bath |
| Companies Covered | Sharretts Plating Company, KC Jones, EC Williams, Chem Processing, Hohman Plating, Northeast Metal Works, Alternate Finishing, Allegheny Coatings, Gatto Industrial Platers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Plating Market Strategic Shifts
Process chemistry innovation and procurement model evolution are compressing technology cycles and reshaping competitive positioning in surface finishing. Three developments merit close attention.
Ionic liquid electrolyte formulations are miniaturizing the environmental footprint of zinc plating operations while maintaining deposit uniformity. European job shops facing ECHA substance scrutiny are piloting these non-aqueous systems to eliminate cyanide and chloride waste streams entirely. The technology is compressing permitting timelines and enabling relocation closer to urban manufacturing clusters previously restricted by emission controls.
China's MEE emission standards for electroplating workshops are tightening effluent monitoring and reporting obligations nationwide. The regulations are forcing facility consolidation as smaller operators exit rather than absorb compliance capital requirements. Automotive and electronics export manufacturers are responding by qualifying fewer, larger finishers with integrated wastewater treatment capabilities.
Long-term finishing agreements with penalty clauses for qualification lapses are displacing spot-market transactions in heavy machinery and aerospace supply chains. Deere, Caterpillar, and Boeing have locked in multi-year coating contracts with approved suppliers, compressing switching flexibility for competing finishers. This pattern is most visible in the US Midwest and Germany, where OEM vendor reduction programs concentrate volume among accredited tier-1 partners.
Zinc Plating Market Segmentation
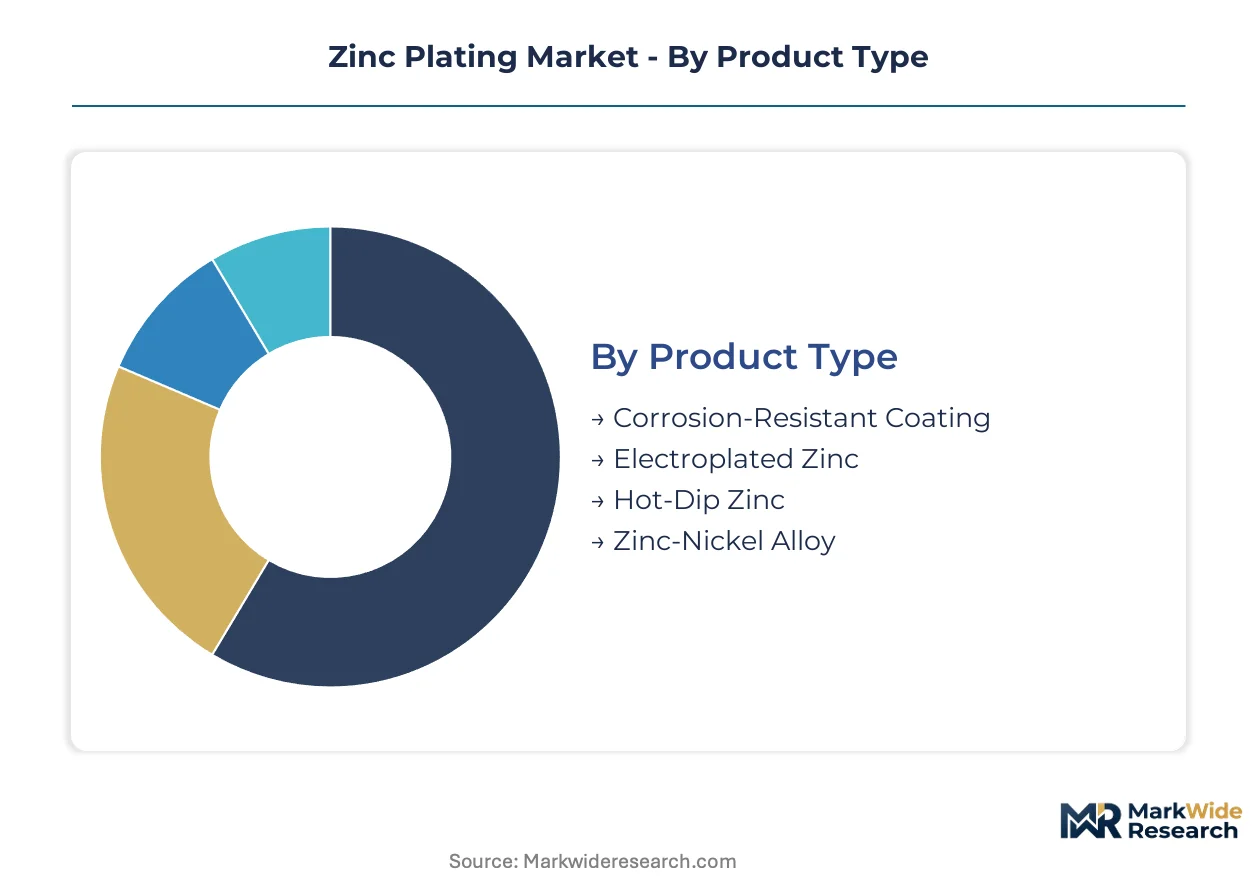
Zinc plating technologies serve divergent performance requirements across automotive underbodies, aerospace fasteners, and electronics housings. Segmentation reveals how specification tiers align with OEM qualification barriers and regional regulatory stringency.
Product Type:
Export-oriented automotive OEMs in Germany and Japan favor high-performance alloys, while domestic construction markets absorb commodity coatings.
- Corrosion-Resistant Coating:Engineered for salt-spray endurance exceeding 1,000 hours through trivalent passivation layers. German and US automakers specify these coatings for chassis components exposed to road salt and marine atmospheres, with REACH Annex XVII compliance now mandatory for EU-bound exports.
- Zinc-Nickel Alloy:Deposits containing 12-15% nickel by weight deliver sacrificial protection at elevated temperatures for brake calipers and engine hardware. Alkaline bath chemistry dominates Japanese and Korean supplier qualifications, though bath control complexity limits adoption among generalist finishers.
- Electroplated Zinc:Acid and alkaline electrolytic deposits 5-25 microns thick serve general industrial fasteners and electrical enclosures.
- Hot-Dip Zinc:Immersion coating for structural steel beams and transmission towers prioritizes coating thickness over surface finish.
Corrosion-Resistant Coating holds the largest share; momentum sits with Zinc-Nickel Alloy.
Application:
Volume concentrates in automotive and construction, though margin premiums accrue to aerospace-qualified segments.
- Automotive Parts:Underbody fasteners, fuel lines, and brake components require salt-spray performance certification to OEM-specific test protocols. Tier-1 suppliers in Stuttgart, Detroit, and Toyota City have internalized high-volume lines, compressing the merchant addressable market for job shops.
- Industrial Equipment:Agricultural and construction machinery manufacturers including Deere and Caterpillar lock in multi-year finishing agreements with penalty clauses for qualification lapses.
- Construction Hardware:Structural bolts and facade fasteners for commercial buildings specify hot-dip or electroplated zinc per ASTM standards.
- Electrical Components:Bus bars, connectors, and enclosures require uniform deposit thickness for conductivity and solderability.
Automotive Parts generates the highest absolute volume; Industrial Equipment commands the steepest expansion trajectory as machinery OEMs consolidate approved-vendor lists.
End User:
Customer sophistication bifurcates between specification-driven OEMs and price-sensitive distributors.
- Manufacturing:Automotive, appliance, and machinery OEMs drive specification intensity through AS9100, IATF 16949, and ISO 14001 certification requirements. Captive plating investments by large Tier-1 suppliers in Germany and Japan have reduced merchant market access for independent finishers.
- Aerospace:AS9100 and NADCAP credentials anchor defense and commercial aviation contracts, with certified capacity scarce in the northeastern United States.
- Construction:Project-based procurement through distributors emphasizes coating thickness compliance over process certification.
- Electronics:Miniaturized connectors and shielding housings demand precise thickness control for RF performance.
Manufacturing absorbs the dominant volume; Aerospace offers the highest margin expansion potential.
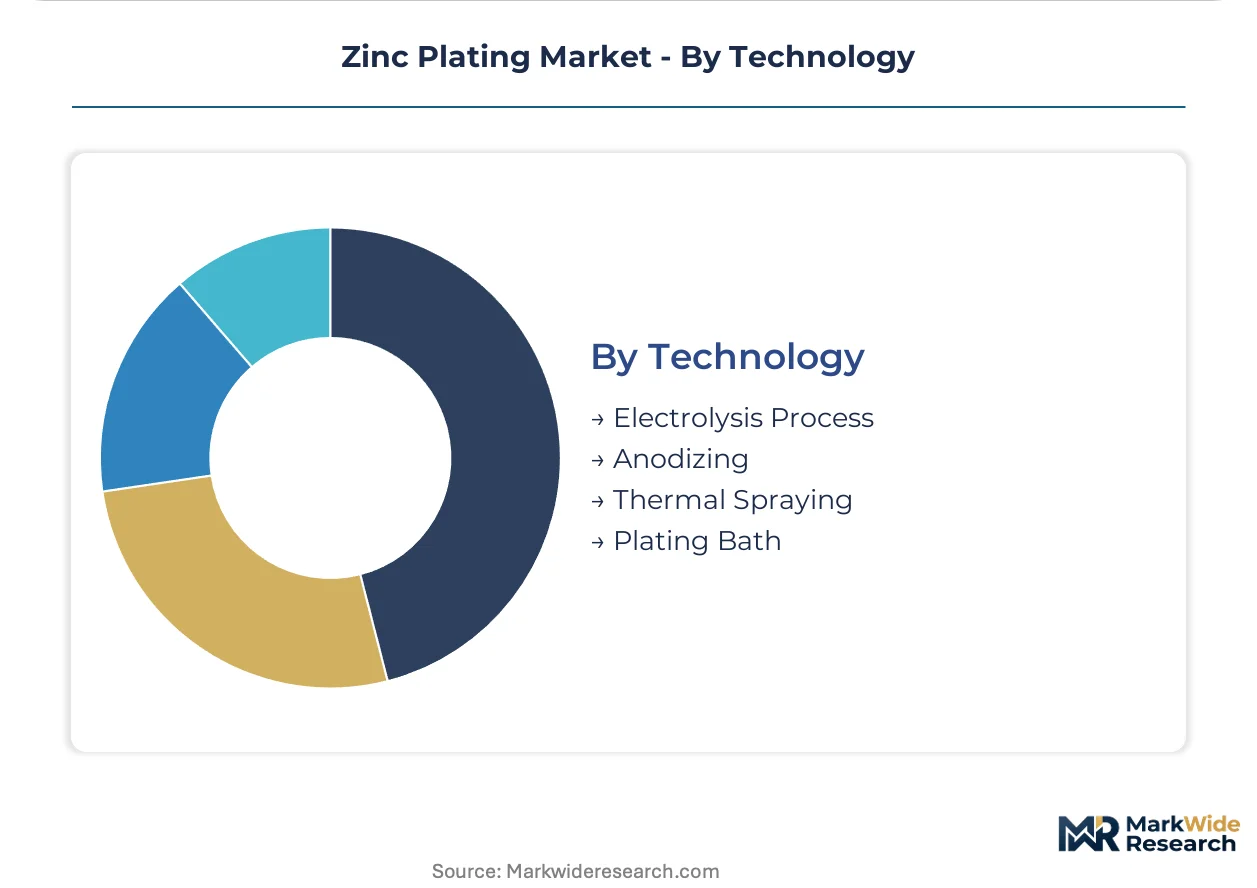
Technology:
Environmental compliance capex is displacing legacy chemistries in European and Chinese facilities.
- Electrolysis Process:Acid chloride and alkaline non-cyanide baths dominate high-volume production for automotive fasteners. ECHA scrutiny of cyanide and chloride waste streams is accelerating ionic liquid pilot programs in European job shops seeking urban relocation permits.
- Plating Bath:Bath chemistry innovations in ionic liquid formulations eliminate aqueous effluent entirely. Non-aqueous systems compress permitting timelines and enable proximity to manufacturing clusters previously restricted by emission controls.
- Anodizing:Conversion coating for aluminum substrates prior to zinc plating for multi-material assemblies.
- Thermal Spraying:Arc and flame spray deposition for large structural components where tank dimensions preclude immersion processes.
Electrolysis Process retains installed base dominance; Plating Bath gains share fastest among environmentally constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German plating specialists to Baltic and North Sea automotive supply chains, anchoring European distribution networks for corrosion-resistant fasteners.
United States
Detroit's automotive OEMs drive specification intensity for salt-spray certified chassis components. EPA effluent guidelines under the Clean Water Act force six-figure wastewater treatment upgrades at Midwest job shops. Certified capacity concentrates in Pennsylvania and Ohio, where AS9100 finishers anchor aerospace and defense contracts.
Germany
Stuttgart's Tier-1 suppliers have internalized high-volume zinc-nickel lines for brake calipers and engine hardware. REACH Annex XVII restrictions on hexavalent chromium passivates accelerate trivalent chemistry adoption across Baden-Württemberg facilities. The country's national electroplating association coordinates compliance timelines for SME finishers.
China
Shanghai's electronics export manufacturers specify uniform deposit thickness for RF connectors and shielding housings. MEE emission standards for electroplating workshops consolidate capacity toward larger operators with integrated treatment systems. Yangtze River Delta plating clusters face GB standards enforcement that eliminates smaller unaccredited shops.
India
Pune's PLI-linked automotive investments draw merchant plating capacity toward corrosion-resistant fastener production. The country's Bureau of Indian Standards mandates heavy-metal emission disclosures for electroplating facilities. Chennai's industrial corridor concentrates new alkaline zinc-nickel capacity serving electronics export hubs.
Japan
Toyota City's captive plating operations reduce merchant market access for independent finishers. METI industrial standards specify alkaline bath chemistry control for high-temperature engine applications. Nagoya's automotive supply chain maintains strict JIS qualification protocols that lock in multi-year finishing agreements.
Zinc Plating Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where ISO 14001-accredited finishers capture OEM contracts while unqualified shops compete on price for construction hardware. The supplier base concentrates around three strategic archetypes: aerospace-certified specialists holding AS9100 and NADCAP credentials, automotive-aligned finishers with IATF 16949 qualifications, and regional job shops serving distributors. Dominant competitive moves include facility consolidation to absorb environmental compliance capex and technology licensing for ionic liquid bath formulations.
Among US-based coating specialists, Sharretts Plating Company and Chem Processing occupy positions within the premium certification tier, while EC Williams represents European finishers navigating REACH-driven chemistry transitions. These companies exemplify how accreditation density determines contract access in specification-driven end uses.
| Leading Market Players |
|---|
| Sharretts Plating Company |
| KC Jones |
| EC Williams |
| Chem Processing |
| Hohman Plating |
| Northeast Metal Works |
| Alternate Finishing |
| Allegheny Coatings |
| Gatto Industrial Platers |
| Others |
Value Chain & Pricing Dynamics
Trivalent passivation chemistry substitution for hexavalent chromium systems simultaneously redraws supplier geography toward REACH-compliant zones and compresses margin structures for finishers absorbing retooling costs. Buyers in Germany and Japan now pay certification premiums while spot-market construction hardware absorbs zinc ingot volatility directly.
Pricing Analysis
Volume-discount tiering separates AS9100-certified aerospace finishers from IATF 16949 automotive suppliers and unaccredited regional job shops. Certification grade and long-term contract scale drive price differentiation, with penalty-clause agreements locking in multi-year premiums. Cost compression in commodity electroplated zinc intensifies as London Metal Exchange volatility feeds through to spot buyers. Distributors serving construction hardware remain most price-sensitive; aerospace OEMs with NADCAP mandates show least elasticity.
Supply Chain Analysis
China, Germany, and India anchor global plating capacity, with Yangtze River Delta clusters supplying electronics exports and Stuttgart's Tier-1 networks feeding automotive OEMs. Zinc ingot sourcing, trivalent chemistry formulations, and wastewater treatment equipment constitute critical input dependencies. Single-source vulnerability concentrates in specialty alloy anode supply from Japanese and Korean producers. Distribution runs through OEM-approved vendor lists with qualification barriers, bypassing spot-market channels for specification-driven end uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zinc plating functions as a platform economy where REACH-driven chemistry interoperability and OEM qualification databases create winner-take-most dynamics. Ecosystem lock-in through approved-vendor lists now determines contract access more than unit cost.
For Market Incumbents: Consolidate captive plating assets in Germany and Japan through acquisition of distressed REACH-compliant facilities. Lock in multi-year chemistry supply agreements with trivalent passivation formulators to defend against ionic liquid disruptors. Deepen backward integration into zinc-nickel anode production to offset ingot price volatility. For New Entrants and Emerging Players: Anchor in underpenetrated US aerospace finishing corridors where AS9100 and NADCAP scarcity creates qualification white space. Target northeastern US defense subcontractors lacking certified local capacity. Deploy mobile ionic liquid pilot units to bypass aqueous effluent permitting delays near urban manufacturing clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive finishing platforms in the US Midwest facing OEM vendor consolidation pressure. Five-to-ten year viability hinges on chemistry transition execution rather than volume scale. Monitor ECHA substance review timelines as the inflection signal for captive plating relocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Upgrade | Trivalent passivation conversion unlocks EU automotive contract eligibility for Tier-2 finishers. |
| Ionic Liquid Chemistry Licensing | Non-aqueous formulations eliminate cyanide waste streams and compress urban permitting timelines. |
| AS9100 Capacity Expansion | Northeastern US aerospace certification scarcity supports premium pricing for qualified entrants. |
| Long-term OEM Finishing Agreement | Penalty-clause contracts with Deere and Caterpillar lock in volume against spot-market volatility. |
| India PLI Corridor Positioning | Pune and Chennai manufacturing incentives concentrate export-oriented plating investments. |
Study Parameters
Initial hypotheses were tested against primary input from plating plant managers, automotive OEM procurement leads, aerospace quality directors, and chemical supply technical specialists and refined through secondary validation. Customs trade data, EPA enforcement records, REACH registration dossiers, and electroplating association membership directories anchored supply-side triangulation. Bottom-up facility capacity estimates and top-down end-use consumption models were reconciled across the analysis window.
Variance-decomposition across product type, application, end user, and technology segments structured the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by value-per-unit differentials. Zinc ingot price elasticity, REACH compliance capex absorption rates, and OEM qualification timeline distributions informed industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under sustained REACH enforcement and stable automotive production assumptions; material deviation in regulatory timelines or OEM insourcing patterns would warrant model refresh. Recalibration cycles align with substance restriction announcements and major OEM vendor consolidation programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Superconducting Wire Market
Metals
Titanium Mill Products Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Global Chromium Market
Metals
Niobium Market
Metals
Finished Steel Products Market
Metals
Medical Metal Tubing Market
Metals
Cerium Market
Metals
Copper Clad Aluminum Wire Market
Metals
Aluminum Casting Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Silver Cyanide Market
Metals
Global Flat Steel Market
Metals
Aluminum Flat Products Market
Metals
Steel Drums and Ibcs Market
Metals
Russia Metal Fabrication Market