
 Magnesium Metal Market | 2026-2036
Magnesium Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Metal Market Intelligence
ISO 9001 and IATF 16949 certification is collapsing as a baseline qualifier for automotive and aerospace supply contracts, forcing smaller refiners out of tier-one vendor pools. US Magnesium LLC leverages captive brine reserves in Utah to sustain fully integrated production from extraction to ingot. Rima Industrial anchors Brazilian supply through its Minas Gerais electrolytic facility, while Dead Sea Magnesium Ltd. competes on the back of Israel Chemicals' integrated Dead Sea bromine-magnesium complex.
Magnesium metal is a silvery-white alkaline earth metal with density of 1.74 g/cm³, produced chiefly via the Pidgeon process or electrolytic reduction, valued for its exceptional strength-to-weight ratio and castability in structural applications. Magnesium alloys dominate value capture due to their penetration in powertrain housings and transmission cases where AZ91D and AM60B specifications govern performance. Pure magnesium ingot remains a mature, high-volume category serving aluminum alloying and desulfurization in steelmaking. Powder and granule forms are gaining traction in chemical processing and pyrotechnic applications where particle size distribution determines reactivity.
EPA air quality standards and OSHA workplace exposure limits shape US smelter economics, while REACH registration and the EU Green Deal carbon border adjustments constrain European import sourcing. China's MEE enforces emission intensity caps on Pidgeon process operations in Ningxia and Shaanxi, redirecting investment toward electrolytic capacity. Stakeholders must monitor which process route—thermal reduction or electrolysis—secures preferential treatment under emerging national carbon accounting frameworks.
Market Dynamics
China's MEE emission intensity caps on Pidgeon process operations in Shaanxi and Ningxia are forcing thermal reduction capacity toward electrolytic conversion or closure, compressing global primary supply availability while redirecting investment toward low-carbon process routes.
Growth Catalysts
- Airframe lightweighting mandates:Boeing and Airbus procurement specifications for AZ91D and AM60B alloy castings in powertrain housings and transmission cases are pulling magnesium into structural aerospace programs.
- REACH registration and EU Green Deal carbon border adjustments:European import sourcing constraints are creating preferential market access for electrolytic-origin metal with verifiable carbon intensity documentation.
- Dead Sea bromine-magnesium complex integration:Israel's captive brine-to-ingot production yields fully traceable supply chains for desulfurization and aluminum alloying applications.
Market Restraints
- Ferrosilicon input cost volatility:Pidgeon process economics hinge on ferrosilicon pricing, which fluctuates with Chinese steelmaking demand and electricity tariffs in Ningxia smelter clusters.
- Shaanxi Province supply concentration:Over half of China's primary magnesium output originates from a single provincial cluster, exposing buyers to localized environmental enforcement actions and forced shutdowns.
- Aluminum-lithium substitution in aerospace:Al-Li alloys from Alcoa and Constellium compete for wing and fuselage applications where magnesium once held cost advantages.
Strategic Opportunities
- Brazilian electrolytic capacity expansion:Minas Gerais-based production anchored by Rima Industrial offers Atlantic-basin supply diversification away from Chinese thermal reduction dominance.
- Pyrotechnic and chemical processing powder grades:Granule and powder forms with tight particle size distribution specifications are penetrating specialty reagent markets beyond traditional structural applications.
- US Inflation Reduction Act clean manufacturing credits:Domestic content incentives for low-carbon industrial materials are stimulating Utah brine-based electrolytic project development.
Industry Challenges
- IATF 16949 and ISO 9001 certification collapse:Automotive and aerospace tier-one vendor pools are excluding smaller refiners unable to sustain audit costs and documentation systems.
- Pidgeon-to-electrolytic process reconfiguration capex:Converting thermal reduction capacity requires furnace replacement, chlorine handling infrastructure, and grid interconnection investments that strain refiner balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Metal Market |
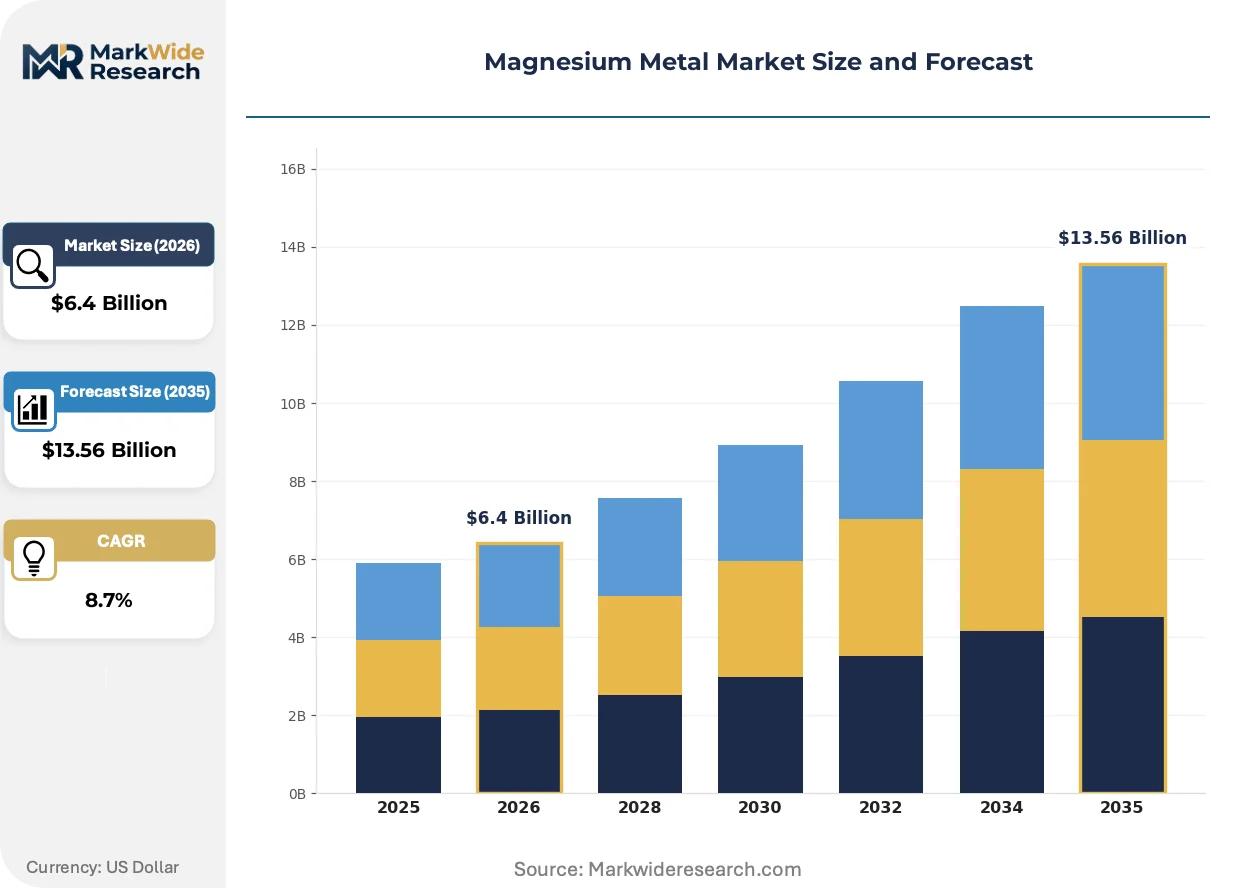
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Magnesium, Magnesium Alloys, Powder, Granules, Rods Application: Aerospace Components, Electronics Casings, Automotive Parts, Chemical Industry, Fireworks Manufacturing End User Industry: Airframe Manufacturers, Consumer Electronics Producers, Vehicle Assemblers, Chemical Processing Plants, Pyrotechnic Manufacturers Form: Ingot, Sheet, Wire, Foil, Blocks |
| Companies Covered | Rima Industrial, Solikamsk Magnesium Works, China Magnesium Corporation, Henan Jingu Magnesium Industry Co., Ltd., Dead Sea Magnesium Ltd., US Magnesium LLC, ICL Group, Yinguang Magnesium, Baowu Magnesium Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Metal Market Strategic Shifts & Innovations
Process technology divergence between thermal reduction and electrolytic routes is splitting supplier competitive profiles, while regulatory carbon accounting frameworks are beginning to price process-origin differentiation into contract terms.
Solid-state electrolysis research is fragmenting the incumbent technology landscape. Alumina and rare-earth metal producers are piloting molten salt cell designs that bypass chlorine-based electrolysis entirely. European aerospace tier-one suppliers are qualifying solid-state origin metal for 2027 contract vintages. This technology is fragmenting procurement specifications into parallel thermal, electrolytic, and solid-state qualification tracks.
China's GB standards on industrial emissions and dual carbon goals are tightening Pidgeon process compliance requirements. Shaanxi smelters face retrofit deadlines or closure orders under MEE provincial enforcement. Ningxia operations are accelerating electrolytic joint ventures with SOE partners to secure grid access and carbon quota allocations.
Buyer consolidation among aluminum alloyers and desulfurization users is compressing spot market liquidity. Large steelmakers and secondary aluminum producers are negotiating direct offtake agreements with Shaanxi and Israeli producers, bypassing merchant traders. This concentration is most visible in German and Japanese automotive supply chains where long-term contract coverage now exceeds eighty percent of annual requirements.
Magnesium Metal Market Segmentation
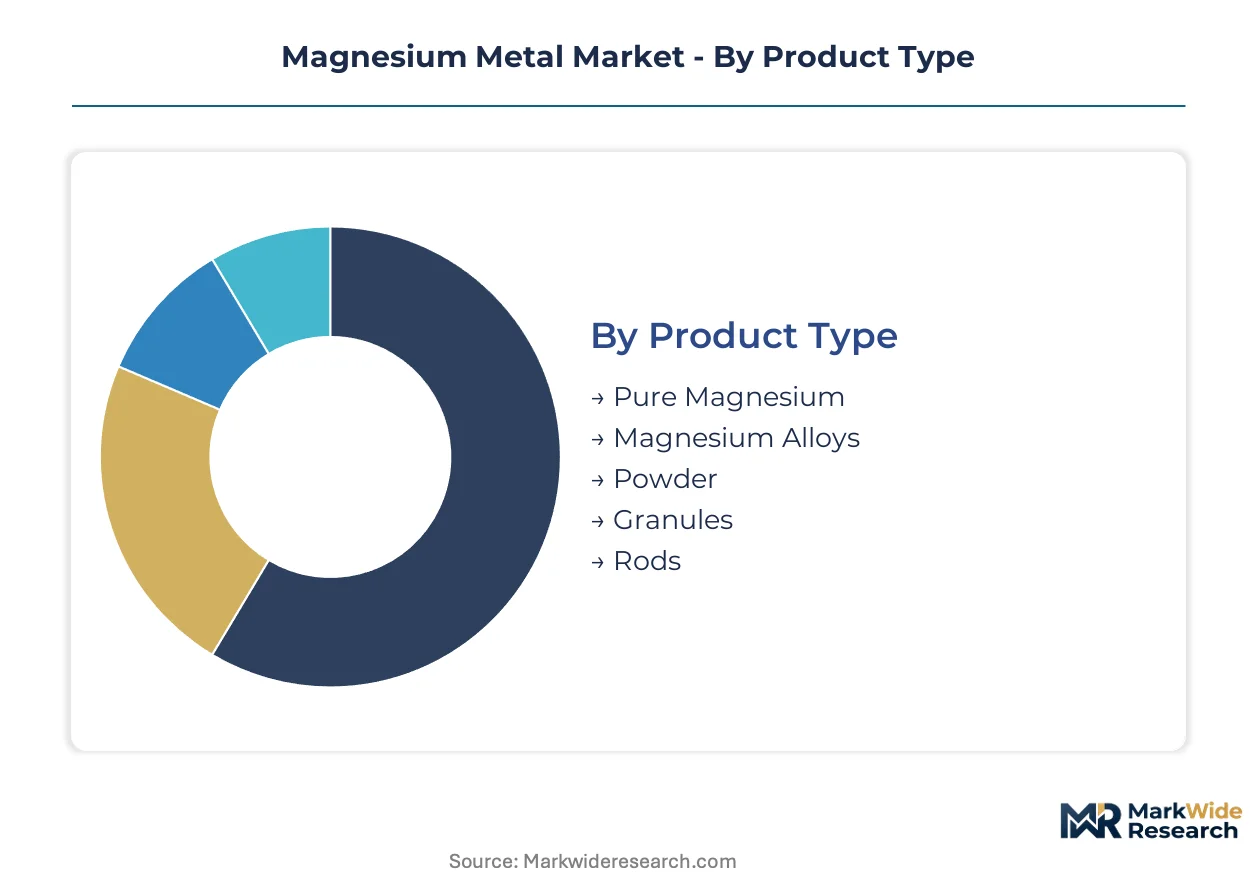
Magnesium metal segmentation reflects divergent process economics and qualification requirements across supply chains. Regulatory carbon accounting frameworks are beginning to price process-origin differentiation into contract terms, reshaping how buyers evaluate product categories.
Product Type:
REACH registration and EU Green Deal carbon border adjustments favor electrolytic-origin metal with verifiable carbon intensity documentation, while Pidgeon-process output faces sourcing constraints in European markets.
- Magnesium Alloys:AZ91D and AM60B specifications govern performance in powertrain housings and transmission cases where strength-to-weight ratio determines selection. Boeing and Airbus procurement programs for lightweight airframe components are pulling alloy castings into structural aerospace applications, with tier-one suppliers qualifying solid-state origin metal for future contract vintages.
- Pure Magnesium:High-volume ingot production serves aluminum alloying and desulfurization in steelmaking as a mature, specification-driven category. Large steelmakers negotiate direct offtake agreements with Shaanxi and Israeli producers, bypassing merchant traders and compressing spot market liquidity for this grade.
- Powder:Tight particle size distribution specifications determine reactivity in specialty reagent markets beyond traditional structural applications.
- Granules:Penetrating pyrotechnic applications where controlled burn rates require consistent morphology.
- Rods:Serving specialized machining and welding feedstock requirements in industrial fabrication.
Magnesium alloys handle the majority of throughput; powder is the fastest mover on share.
Application:
Cost tier stratification separates premium-qualified aerospace grades from commodity desulfurization volumes, with certification requirements acting as the primary price differentiator.
- Aerospace Components:Airframe lightweighting mandates from Boeing and Airbus procurement specifications demand AZ91D and AM60B alloy castings with full traceability documentation. Solid-state electrolysis research is fragmenting procurement specifications into parallel thermal, electrolytic, and solid-state qualification tracks for 2027 contract vintages.
- Automotive Parts:Powertrain housings and transmission cases consume alloy volumes where IATF 16949 certification operates as a baseline qualifier, forcing smaller refiners out of tier-one vendor pools. German and Japanese automotive supply chains now cover over eighty percent of annual requirements through long-term contracts.
- Chemical Industry:Reagent-grade consumption depends on consistent purity specifications for specialty synthesis applications.
- Electronics Casings:EMI shielding and lightweight enclosure applications in consumer devices.
- Fireworks Manufacturing:Brightness and burn-rate specifications drive granule and powder demand in pyrotechnic formulations.
Automotive parts command the largest volume position; aerospace components are expanding most quickly.
End User Industry:
Customer concentration among aluminum alloyers and desulfurization users is redirecting procurement toward direct producer relationships and away from spot market intermediation.
- Vehicle Assemblers:Tier-one automotive supply chains in Germany and Japan have consolidated procurement through long-term contract coverage exceeding eighty percent of annual magnesium requirements. IATF 16949 and ISO 9001 certification collapse is excluding smaller refiners unable to sustain audit costs and documentation systems.
- Airframe Manufacturers:Boeing and Airbus lightweight material programs are strengthening demand for qualified alloy castings with full carbon intensity documentation under emerging national carbon accounting frameworks.
- Chemical Processing Plants:Reagent-grade specifications govern procurement for specialty synthesis and catalyst applications.
- Consumer Electronics Producers:EMI shielding and thermal management requirements in portable device enclosures.
- Pyrotechnic Manufacturers:Particle size distribution specifications determine reactivity in controlled burn applications.
Vehicle assemblers represent the dominant demand sink; airframe manufacturers are climbing the fastest on share.
Form:
Supply concentration in Shaanxi Province ingot production shapes availability of downstream fabricated forms, with conversion capacity determining regional access to sheet, wire, and foil products.
- Ingot:Primary output form from both Pidgeon process clusters in Shaanxi and electrolytic facilities in Utah and Minas Gerais. China's MEE emission intensity caps are forcing thermal reduction capacity toward electrolytic conversion or closure, compressing global primary supply availability.
- Sheet:Rolled product serving aerospace skin panels and automotive body applications where formability requirements specify thickness tolerances.
- Wire:Welding feedstock and electrical conductor applications in specialized industrial fabrication.
- Foil:EMI shielding and battery current collector applications in electronics and energy storage.
- Blocks:Foundry feedstock for sand casting and permanent mold applications in general industrial use.
Ingot handles the majority of throughput; foil is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum alloyers and desulfurization buyers concentrate procurement through direct producer relationships, bypassing spot markets. Large steelmakers and secondary aluminum producers negotiate long-term offtake agreements that now cover over eighty percent of annual requirements in key automotive supply chains.
China
Shaanxi Province hosts over half of national primary magnesium output through Pidgeon process clusters concentrated around Yulin and Shenmu. The MEE enforces emission intensity caps that force thermal reduction capacity toward electrolytic conversion or closure. Ningxia smelters face parallel compliance deadlines, accelerating joint ventures with SOE partners to secure grid access and carbon quota allocations under dual carbon goals.
United States
US Magnesium LLC operates captive brine reserves in Utah sustaining fully integrated production from extraction to ingot for aluminum alloying and desulfurization buyers. The EPA air quality standards and OSHA workplace exposure limits shape smelter economics. Domestic content incentives under the Inflation Reduction Act are stimulating Utah brine-based electrolytic project development for low-carbon industrial materials.
Brazil
Rima Industrial anchors Atlantic-basin supply through its Minas Gerais electrolytic facility, offering diversification from Chinese thermal reduction dominance. The ANVISA regulatory framework governs chemical-grade specifications for specialty reagent applications. Minas Gerais-based production serves desulfurization and aluminum alloying markets with electrolytic-origin metal.
Germany
German automotive tier-one supply chains have consolidated procurement through long-term contract coverage exceeding eighty percent of annual magnesium requirements. REACH registration and EU Green Deal carbon border adjustments constrain import sourcing to electrolytic-origin metal with verifiable carbon intensity documentation. IATF 16949 certification operates as a baseline qualifier, forcing smaller refiners out of vendor pools.
Israel
Dead Sea Magnesium Ltd. competes through Israel Chemicals' integrated Dead Sea bromine-magnesium complex yielding fully traceable supply chains. The captive brine-to-ingot production serves desulfurization and aluminum alloying applications with documented carbon intensity. Israeli output penetrates European markets constrained by EU Green Deal sourcing requirements.
Magnesium Metal Market Key Industry Players
Player mix skews toward integrated brine-to-ingot operators and captive Pidgeon process clusters. Thermal reduction capacity concentrates in Shaanxi Province while electrolytic production anchors supply in Utah, Minas Gerais, and the Dead Sea. Two strategic archetypes dominate: fully integrated resource holders with captive feedstock and regional processors dependent on merchant ferrosilicon and grid electricity. Competitive moves center on process route conversion capex and certification system investments for tier-one vendor qualification.
Among integrated resource holders, US Magnesium LLC and Dead Sea Magnesium Ltd. exemplify the captive brine archetype with in-house control over extraction through ingot production. Rima Industrial occupies a position within the Atlantic-basin electrolytic tier, representing Brazilian supply diversification. These three companies anchor competitive positioning around process-origin differentiation as carbon accounting frameworks price thermal reduction against electrolytic routes in contract terms.
| Leading Market Players |
|---|
| Rima Industrial |
| Solikamsk Magnesium Works |
| China Magnesium Corporation |
| Henan Jingu Magnesium Industry Co., Ltd. |
| Dead Sea Magnesium Ltd. |
| US Magnesium LLC |
| ICL Group |
| Yinguang Magnesium |
| Baowu Magnesium Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
REACH registration and EU Green Deal carbon border adjustments gate both supply qualification and price differentiation simultaneously, forcing electrolytic-origin metal into premium contract tiers while Pidgeon-process output faces sourcing constraints and compressed margins in European markets. IATF 16949 certification operates as a parallel qualifier in automotive supply chains, excluding uncertified refiners from tier-one vendor pools regardless of price competitiveness.
Pricing Analysis
Cost-plus contracts with ferrosilicon indexation dominate Pidgeon-process transactions, while electrolytic-origin metal commands fixed-price premiums tied to carbon intensity documentation. Price differentiation separates IATF 16949-certified aerospace grades from commodity desulfurization ingot, with German and Japanese automotive buyers showing lowest price sensitivity due to long-term contract coverage exceeding eighty percent of requirements. Pricing pressure stems from Shaanxi Province environmental enforcement actions that trigger spot supply disruptions and force buyers into premium sourcing alternatives.
Supply Chain Analysis
Ferrosilicon supply from Ningxia and Shaanxi smelter clusters underwrites Pidgeon-process economics, creating input cost vulnerability when Chinese steelmaking demand spikes. Geographic supply concentration centers on China, Israel, and Brazil, with captive brine-to-ingot operations in Utah and the Dead Sea offering diversification. Raw material dependencies include ferrosilicon reductant, dolomite ore, and chlorine for electrolytic conversion. Single-source vulnerability in Shaanxi Province exposes buyers to localized MEE enforcement actions. Distribution runs through direct offtake agreements between large steelmakers and primary producers, bypassing merchant traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnesium metal market operates as a substitution defense against aluminum-lithium alloys from Alcoa and Constellium, which compete for wing and fuselage applications where magnesium once held cost advantages. Incumbents must navigate this threat while process-origin differentiation reshapes competitive positioning.
For Market Incumbents: Compound captive brine resource positions through electrolytic capacity expansion in Utah and Minas Gerais, insulating against Shaanxi supply disruptions. Deepen backward integration into ferrosilicon production or secure long-term reductant offtakes to stabilize Pidgeon-process input costs. Prioritize IATF 16949 and ISO 9001 certification maintenance to defend tier-one vendor status against audit-excluded competitors.
For New Entrants and Emerging Players: Anchor in pyrotechnic powder and granule specialty grades where tight particle size distribution specifications create qualification barriers for incumbent commodity producers. Target chemical processing reagent markets with consistent purity offerings that bypass aerospace and automotive certification requirements. Pursue direct sales to pyrotechnic manufacturers and specialty chemical synthesis operations as the most penetrable entry channel.
For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape toward electrolytic-origin assets with verifiable carbon intensity documentation. Frame long-term viability around process route conversion capex requirements and grid access positioning across the next decade. Target captive brine-to-ingot operators with integrated supply chains as the preferred acquisition archetype. Monitor solid-state electrolysis pilot progress as the critical signal for technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolytic Capacity Conversion | MEE emission caps in Shaanxi force thermal reduction retrofit or closure decisions. |
| Carbon Intensity Certification | REACH documentation requirements gate European market access for electrolytic metal. |
| Long-term Supply Agreement | German automotive chains now cover over eighty percent through direct producer offtakes. |
| Backward Integration | Captive ferrosilicon production stabilizes Pidgeon-process margins against steelmaking demand spikes. |
| Specialty Powder Grade Development | Pyrotechnic applications with tight particle size specifications bypass commodity pricing pressure. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with magnesium refinery operations managers, automotive Tier 1 procurement leads, aerospace materials qualification engineers, and steelmaking desulfurization buyers; alongside secondary validation through customs trade data, EPA and MEE enforcement disclosures, SEC filings from integrated chemical producers, and IATF certification registry records. Bottom-up capacity and production estimates triangulated against top-down demand modeling from aluminum alloying and automotive casting consumption.
Across the projection horizon, the analytical framework segmented volume and value outputs by process route, product form, certification tier, and end-use industry concentration. CAGRs derived from regression analysis of historical capacity utilization, regulatory compliance cost trajectories, and substitution elasticity between magnesium and aluminum-lithium alloys. Forecast inputs incorporated MEE provincial enforcement schedules, IRA domestic content incentive qualification criteria, and solid-state electrolysis technology readiness assessments.
Material uncertainties — Shaanxi environmental enforcement intensity, ferrosilicon price volatility, and solid-state electrolysis commercialization timing — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory implementation pace and process route conversion investment flows. Practitioners should keep alternative scenarios live as EU carbon border adjustment mechanisms and Chinese dual carbon goal enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Stainless Steel 400 Series Market
Metals
Nickel Sulfate Market
Metals
North America Metal Casting Market
Metals
Hafnium Foil Market
Metals
US Ferrochrome Market
Metals
Copper and Copper Alloy Foil Market
Metals
Europe Metal Casting Market
Metals
Precious Metals Wire Market
Metals
Stainless Steel Market
Metals
Steel Ingots Market
Metals
South America Metal Finishing Market
Metals
Silver Powder and Flakes Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Lithium Foil Market
Metals
Global Electrolytic Copper Foil Market
Metals
Flat-Rolled Stainless Steel Market