
 Rubidium Market | 2026-2036
Rubidium Market Size, Share, and Industry Trends Forecast 2026-2036
Rubidium Market Intelligence
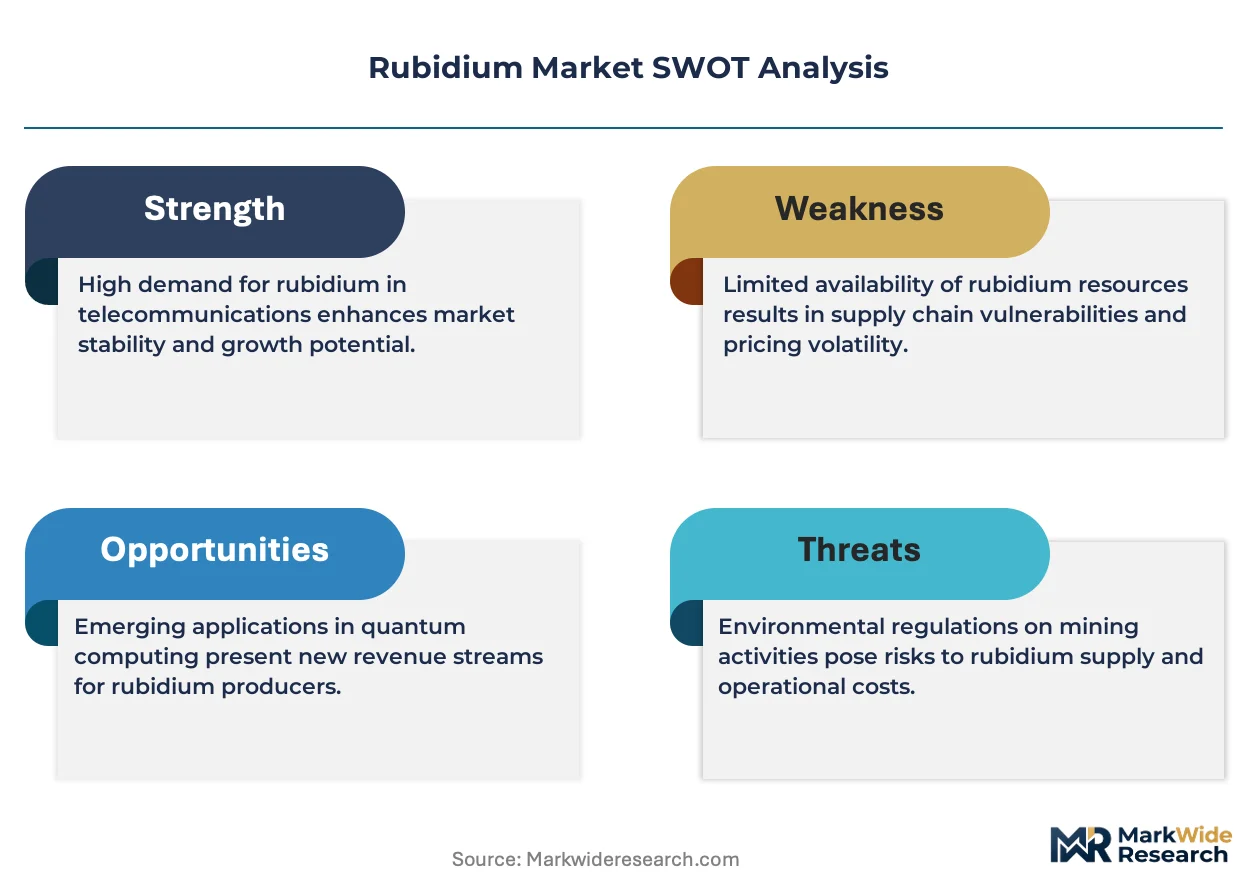
ISO 17025 accreditation for atomic clock calibration laboratories is redrawing competitive boundaries in rubidium supply. American Elements leverages vertical integration from specialty chemical synthesis to packaged isotope delivery. Ganfeng Lithium anchors its position through captive brine extraction assets in Jiangxi province. Merck KGaA differentiates via pharmaceutical-grade rubidium carbonate certified under European Pharmacopoeia monographs.
Rubidium is an alkali metal with atomic number 37, melting point 39.3 degrees Celsius, and primary commercial extraction from lepidolite and pollucite ores via acid digestion and fractional crystallization. It serves as the frequency-determining element in atomic clocks, where hyperfine transition at 6.834 GHz provides stability exceeding one part in ten to the thirteenth. Rubidium titanyl phosphate dominates optical device segments due to nonlinear optical coefficients enabling efficient second-harmonic generation. Atomic clock applications command premium pricing through defense and telecommunications procurement channels. Research-grade rubidium chloride maintains steady volume through university and national laboratory budgets.
REACH registration requirements under ECHA govern rubidium compound import and formulation within Europe, while FDA oversight applies to pharmaceutical applications in the United States. China's MIIT sets domestic content thresholds for frequency standards in critical infrastructure. Japan's METI coordinates rubidium isotope allocation through strategic stockpile mechanisms. Stakeholders must monitor evolving export control classifications for enriched isotopes and alignment between national frequency standard programs and commercial atomic clock deployment timelines.
Market Dynamics
Frequency standard mandates from China's MIIT are redirecting procurement flows across the rubidium supply chain, forcing requalification of sourcing relationships and accelerating captive production investments.
Growth Catalysts
- Telecommunications infrastructure:5G network densification requires atomic clock synchronization at base stations. Rubidium frequency standards provide holdover stability during GPS signal loss.
- REACH registration:ECHA compliance frameworks for rubidium compounds create entry barriers that favor established European formulators with dossier completion.
- Hyperfine transition engineering:Advances in laser cooling and magnetic shielding improve clock stability metrics, expanding addressable applications in scientific instrumentation.
Market Restraints
- Input cost volatility:Lepidolite and pollucite ore prices fluctuate with lithium market cycles, compressing margin predictability for primary extractors.
- Supply concentration risk:Jiangxi province hosts the majority of captive brine-to-carbonate capacity, creating single-geography exposure for downstream buyers.
- Cesium fountain substitution:National metrology laboratories are transitioning primary frequency standards to cesium fountain technology, reducing long-term rubidium demand at the precision tier.
Strategic Opportunities
- Quantum sensing applications:Cold atom interferometry for gravimetry and inertial navigation represents an emerging demand vertical with limited incumbent supply relationships.
- Dual carbon alignment:China's MEE carbon intensity targets favor rubidium extraction from lithium brine waste streams over hard rock mining, rewarding integrated lithium-rubidium operators.
- Pharmaceutical-grade certification:European Pharmacopoeia monograph compliance for rubidium carbonate opens formulation partnerships with radiopharmaceutical developers.
Industry Challenges
- Isotope enrichment bottleneck:Separating rubidium-87 for specialized atomic clock applications requires electromagnetic separation capacity concentrated at a handful of government facilities.
- ISO 17025 calibration backlog:Accreditation timelines for atomic clock calibration laboratories extend 18-24 months, delaying new supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubidium Market |
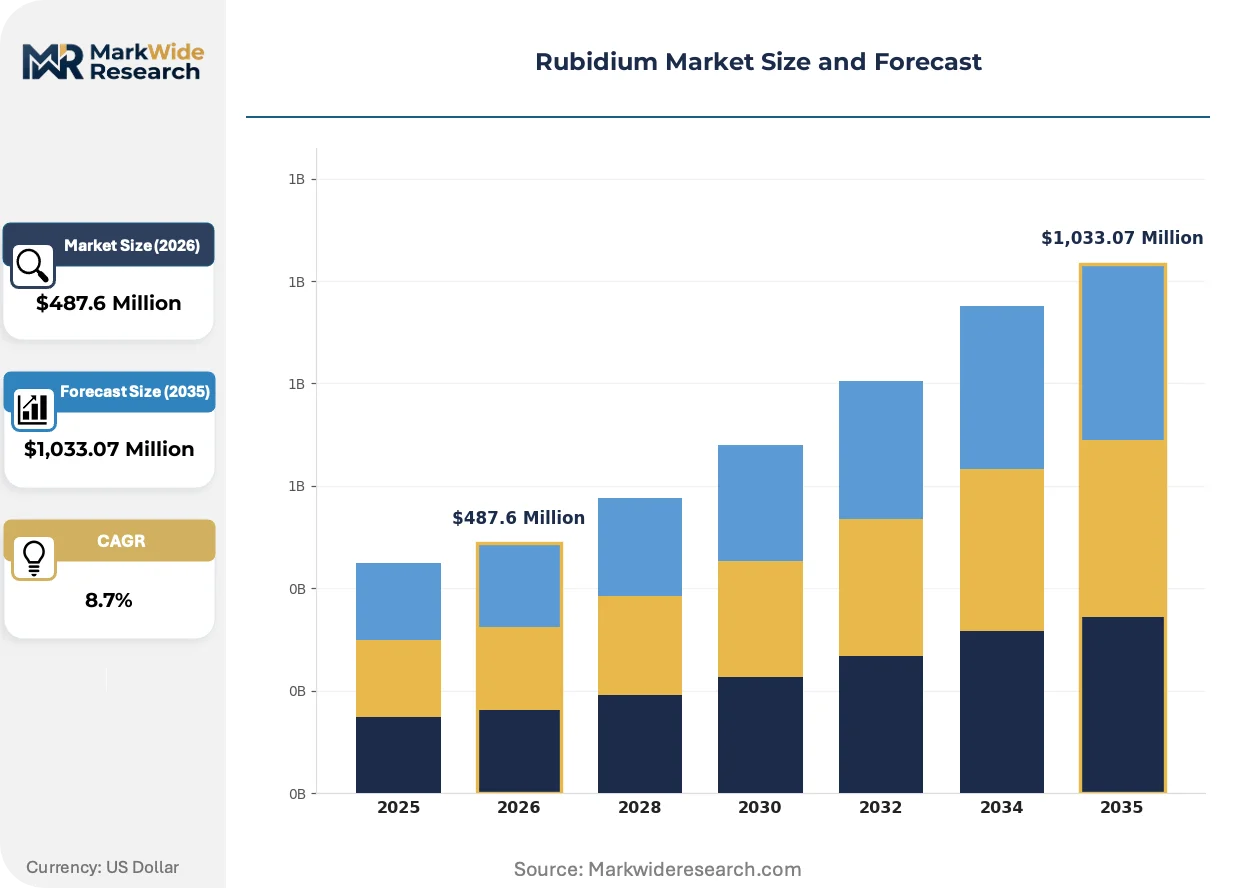
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubidium Chloride, Rubidium Carbonate, Rubidium Titanyl Phosphate, Rubidium Acetate Application: Atomic Clocks, Pharmaceutical, Research, Optical Devices End User: Aerospace, Telecommunications, Defense, Universities Delivery Mode: Bulk, Retail, Online, Direct Supply |
| Companies Covered | American Elements, Frequency Electronics, Ganfeng Lithium, International Lithium Corp, AccuBeat, Sinomine Resource Group, Lepidico, LANHIT, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubidium Market Strategic Shifts & Innovations
Frequency standard architectures are fragmenting across precision tiers, with rubidium positioning between chip-scale atomic clocks and cesium fountains while new optical lattice technologies threaten upward migration.
Chip-scale atomic clocks leveraging coherent population trapping are displacing traditional rubidium vapor cell designs in telecommunications timing modules. Base station OEMs are qualifying these devices for holdover applications where stability requirements have relaxed. This displacement is compressing addressable volume in the mid-precision tier while pushing rubidium suppliers toward defense and scientific segments.
China's MIIT domestic content thresholds for critical infrastructure frequency standards are reshaping supplier qualification protocols. Foreign atomic clock manufacturers must establish local assembly or joint venture structures to access state-owned telecommunications procurement channels. Equipment vendors are responding by licensing rubidium physics package designs to domestic partners rather than exporting finished goods.
Long-term purchase agreements with fixed pricing bands are replacing spot market procurement for high-purity rubidium compounds. Defense contractors and national metrology institutes are locking in multi-year supply security amid raw material volatility. This contracting evolution is most visible in Germany and Japan, where strategic stockpile coordination through METI and federal procurement offices favors relationship-based sourcing over transactional purchasing.
Rubidium Market Segmentation
Rubidium compounds flow through distinct procurement channels shaped by purity requirements and end-use criticality. Defense contractors and national metrology institutes source through direct supply agreements with fixed pricing bands, while research institutions access materials via specialized chemical distributors.
Product Type:
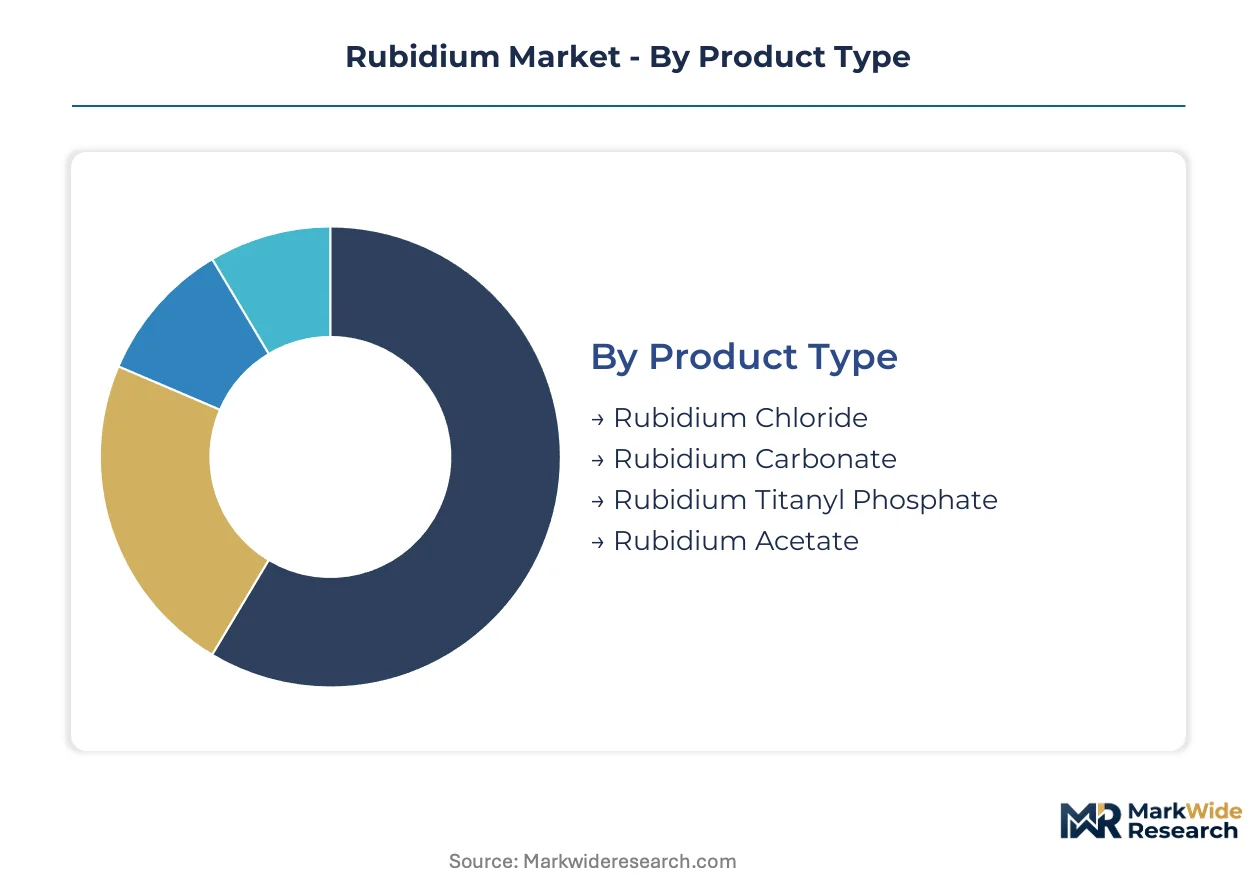
Channel mix varies sharply by compound specification—pharmaceutical-grade carbonates move through certified chemical distributors with ECHA dossier completion, while optical-grade titanyl phosphate ships direct from specialty synthesis houses to device manufacturers.
- Rubidium Carbonate:Primary feedstock for atomic clock vapor cells and pharmaceutical formulations. Demand concentrates in telecommunications infrastructure across Germany and Japan, where defense contractors lock in multi-year supply security amid raw material volatility from Jiangxi province brine operations.
- Rubidium Titanyl Phosphate:Nonlinear optical crystal with coefficients enabling efficient second-harmonic generation in laser systems. Aerospace and defense procurement channels in the United States command premium pricing through frequency converter applications in targeting and rangefinding systems.
- Rubidium Chloride:Research-grade material maintaining steady volume through university and national laboratory budgets.
- Rubidium Acetate:Niche organometallic precursor for specialized synthesis applications.
Rubidium carbonate dominates installed base through atomic clock proliferation. Rubidium titanyl phosphate is where expansion concentrates as directed-energy systems multiply.
Application:
Cost tier segmentation separates defense-grade frequency standards from commercial telecommunications modules, with pricing bands reflecting stability specifications rather than material input costs alone.
- Atomic Clocks:Frequency-determining element leveraging hyperfine transition at 6.834 GHz for stability exceeding one part in ten to the thirteenth. China's MIIT domestic content mandates are redirecting procurement flows, forcing foreign manufacturers to establish local assembly joint ventures for state-owned telecommunications access.
- Pharmaceutical:Rubidium carbonate certified under European Pharmacopoeia monographs for radiopharmaceutical development. European formulators with REACH dossier completion capture formulation partnerships as entry barriers favor established suppliers.
- Research:Steady demand through university and national laboratory budgets for fundamental physics and materials science.
- Optical Devices:Second-harmonic generation crystals for laser frequency conversion in scientific instrumentation.
Atomic clocks command the highest margin tier through defense procurement channels. Pharmaceutical applications are climbing the fastest as radiopharmaceutical developers seek certified supply partnerships.
End User:
Customer type determines contract structure—national programs coordinate through strategic stockpile mechanisms while commercial telecommunications deploy spot-market-flexible sourcing for non-critical timing modules.
- Defense:Long-term purchase agreements with fixed pricing bands predominate. Germany and Japan coordinate strategic stockpiles through federal procurement offices and METI, favoring relationship-based sourcing over transactional purchasing for high-purity compounds.
- Telecommunications:5G network densification requires atomic clock synchronization at base stations. Chip-scale atomic clocks leveraging coherent population trapping are displacing traditional rubidium vapor cell designs, compressing addressable volume in the mid-precision tier.
- Aerospace:Inertial navigation and satellite payload applications demand isotope-enriched materials with electromagnetic separation capacity concentrated at government facilities.
- Universities:Research-grade procurement through institutional chemical supply frameworks with ISO 17025 calibration requirements.
Defense maintains the deepest supply relationships through strategic stockpile coordination. Telecommunications is where volume expansion faces substitution pressure from chip-scale alternatives.
Delivery Mode:
Supply concentration in Jiangxi province shapes logistics—bulk shipments of carbonate predominate for integrated lithium-rubidium operators, while specialized optical materials move through direct channels to bypass distributor markups.
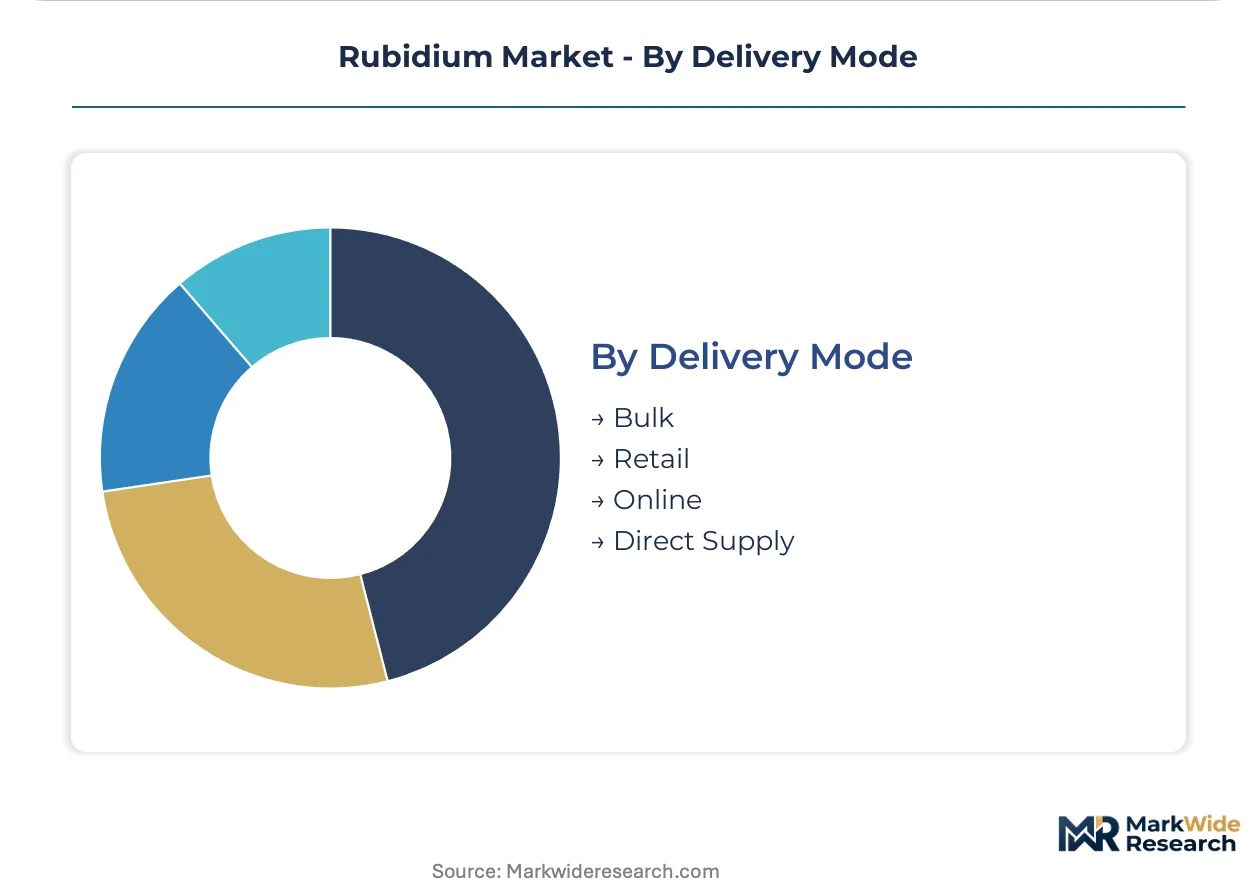
- Direct Supply:Predominant channel for defense contractors and national metrology institutes requiring multi-year supply security with fixed pricing bands amid raw material volatility.
- Bulk:Integrated lithium-rubidium operators in Jiangxi province ship carbonate concentrates to downstream formulators under captive supply arrangements.
- Retail:Research-grade materials through certified chemical distributors with ISO 17025 accreditation for atomic clock calibration laboratories.
- Online:Limited to standard-purity reagents for educational and routine analytical applications.
Direct supply dominates high-value defense and metrology procurement. Bulk channels are gaining share fastest as integrated lithium-rubidium operators expand captive downstream integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and national metrology institutes concentrate procurement across five key geographies, each with distinct regulatory frameworks and supply chain configurations. Atomic clock synchronization requirements for telecommunications infrastructure are redrawing regional demand patterns. Strategic stockpile coordination mechanisms favor relationship-based sourcing over transactional purchasing in Germany and Japan.
United States
Aerospace and defense applications anchor domestic rubidium consumption through frequency converter systems in targeting and rangefinding equipment. The FAA coordinates frequency standard deployment for aviation navigation infrastructure. Defense procurement channels in California and Massachusetts lock in multi-year supply agreements with fixed pricing bands.
Germany
Telecommunications infrastructure investments drive atomic clock deployment for 5G network synchronization. REACH registration requirements under ECHA govern compound import and formulation, creating entry barriers for non-compliant suppliers. Industrial clusters in Bavaria and Baden-Württemberg host precision optical device manufacturers sourcing rubidium titanyl phosphate.
Japan
National metrology institutes maintain demand for research-grade materials through university and laboratory procurement frameworks. METI coordinates rubidium isotope allocation through strategic stockpile mechanisms. Tokyo-Osaka industrial corridors concentrate optical device manufacturing for scientific instrumentation applications.
China
MIIT domestic content mandates redirect procurement flows for critical infrastructure frequency standards. Jiangxi province hosts captive brine-to-carbonate extraction capacity serving integrated lithium-rubidium operations. Beijing-Tianjin-Hebei and Yangtze River Delta clusters drive joint venture structures for foreign atomic clock manufacturers.
United Kingdom
Research institutions maintain steady volume through national laboratory budgets for fundamental physics applications. The country's national pharmaceutical regulator oversees radiopharmaceutical development partnerships requiring certified supply. Southeast England concentrations of defense electronics contractors source through direct supply agreements.
Rubidium Market Key Industry Players
Player mix skews toward integrated specialty chemical operators with captive mineral extraction assets. Market structure concentrates around three to four dominant suppliers controlling primary extraction and high-purity formulation capacity. Strategic archetypes include integrated lithium-rubidium operators, specialty chemical synthesis houses, and atomic clock physics package designers. Competitive moves center on backward integration into brine extraction assets and technology licensing arrangements for domestic content compliance.
Among integrated extraction operators, Ganfeng Lithium and Sinomine Resource Group exemplify the captive brine-to-compound archetype. American Elements occupies a position within specialty chemical synthesis and isotope delivery. These three companies represent the dominant supply-side configurations: Jiangxi-based brine integration, multi-asset mineral extraction, and verticalized specialty chemical production.
| Leading Market Players |
|---|
| American Elements |
| Frequency Electronics |
| Ganfeng Lithium |
| International Lithium Corp |
| AccuBeat |
| Sinomine Resource Group |
| Lepidico |
| LANHIT |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month ISO 17025 accreditation timelines for atomic clock calibration laboratories concentrate pricing power among incumbent suppliers with completed dossiers, while Jiangxi province brine operations tether input costs to lithium market cycles. Defense contractors absorb premium pricing through fixed-band long-term agreements, but telecommunications OEMs face compression as chip-scale alternatives relax stability requirements.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement for high-purity rubidium compounds, separating defense-grade frequency standards from commercial telecommunications modules through stability certification tiers. Price differentiation rests on European Pharmacopoeia monograph completion and REACH dossier status, with ECHA-compliant formulators capturing radiopharmaceutical partnerships. Cost compression in the mid-precision tier intensifies because coherent population trapping chip-scale clocks displace traditional vapor cell designs. Telecommunications OEMs exhibit highest price sensitivity through spot-market-flexible sourcing, while national metrology institutes accept premium positioning for isotope-enriched materials.
Supply Chain Analysis
Electromagnetic separation capacity for rubidium-87 enrichment at government facilities constitutes a chokepoint that constrains aerospace and satellite payload applications. Primary extraction concentrates in China, Canada, and Zimbabwe through lepidolite and pollucite ore processing, with downstream formulation anchored in Germany and Japan. Raw material flows draw from lithium brine waste streams, acid digestion reagents, and fractional crystallization equipment. Single-geography exposure in Jiangxi province creates vulnerability to MIIT domestic content enforcement. Distribution runs through direct supply agreements for defense contractors and certified chemical distributors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national metrology institutes and defense procurement offices that coordinate strategic stockpiles through METI and federal mechanisms, fragmenting price discovery for high-purity compounds.
For Market Incumbents: Shield margin position by deepening captive brine-to-carbonate integration in Jiangxi province and accelerating ISO 17025 accreditation investments for calibration laboratory networks. Chip-scale atomic clock substitution in telecommunications timing modules threatens volume in the mid-precision tier; respond by locking multi-year supply security with fixed pricing bands for defense and scientific segments. For New Entrants and Emerging Players: Lead with pharmaceutical-grade rubidium carbonate certified under European Pharmacopoeia monographs, targeting radiopharmaceutical developers in Germany and the United Kingdom where REACH dossier completion creates entry barriers for non-compliant suppliers. White-space opportunity sits in quantum sensing applications for cold atom interferometry gravimetry, with limited incumbent supply relationships and premium pricing tolerance from aerospace navigation programs. For Investors and Strategic Acquirers: Long-term, this sits as a strategic materials play because frequency standard mandates from China's MIIT and dual carbon alignment incentives favor integrated lithium-rubidium operators with waste stream extraction capabilities. Acquisition targets should display captive mineral assets in lithium brine provinces plus downstream high-purity formulation capacity. Watch cesium fountain transition timelines at national metrology laboratories as the inflection signal for rubidium demand compression at the precision tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive supply of rubidium from Jiangxi lithium waste streams secures input cost predictability against ore price volatility. |
| ISO 17025 Accreditation Investment | Calibration laboratory certification removes 18-24 month qualification barriers for defense and metrology procurement channels. |
| Domestic Joint Venture Licensing | Physics package design licensing to Chinese partners satisfies MIIT content thresholds for state-owned telecommunications access. |
| Pharmaceutical-Grade Certification | European Pharmacopoeia monograph compliance opens formulation partnerships with radiopharmaceutical developers in Germany. |
| Long-Term Supply Agreement Lock-In | Fixed pricing band contracts with defense contractors and national institutes hedge against raw material volatility from lithium cycles. |
Research Approach
Two parallel data streams informed the analysis: structured primary engagement with atomic clock manufacturers, specialty chemical procurement leads, lithium extraction operators, and national metrology institute supply officers; and secondary validation through customs trade records, ECHA REACH registration databases, MIIT policy circulars, and SEC filings from integrated extraction operators. Bottom-up volume triangulation across compound grades and applications reconciled against top-down market sizing from frequency standard deployment forecasts.
Across the analysis window, the forecasting framework modeled demand by product type, application criticality, end-user procurement structure, and regional regulatory cluster, with CAGRs derived from deployment timelines for 5G synchronization infrastructure and defense navigation systems. Inputs included hyperfine transition engineering advances, chip-scale atomic clock qualification rates, and strategic stockpile coordination mechanisms through METI and federal procurement offices.
The analysis sits within stated boundaries; outcomes outside continued MIIT domestic content enforcement, cesium fountain substitution pacing, and lithium market cycle stability would require recalibration. Forecasts reflect documented assumptions about telecommunications infrastructure investment trajectories and defense procurement continuity. Practitioners should keep alternative scenarios live as optical lattice clock technology maturity and quantum sensing application scale evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Brazing Consumable Market
Metals
Lanthanum Market
Metals
Metallurgical Silicon Market
Metals
US and Mexico Stainless Steel Market
Metals
GCC Metal Forging Market
Metals
Metal Coil Lamination Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Rare Earth Metals Market
Metals
Qatar Metalworking Market
Metals
Titanium Market
Metals
Monel Alloy Market
Metals
Zirconium Market
Metals
Niobium Market
Metals
US Ferrochrome Market
Metals
Steel Wire Market
Metals
India Steel Market