
 North America Refining Catalysts Market | 2026-2036
North America Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Refining Catalysts Market Analytics
Specialty chemical distribution channels serving the Gulf Coast refining corridor is reconfiguring around just-in-time catalyst replenishment and technical service bundling. Albemarle Corporation dominates bimetallic hydroprocessing catalyst supply through backward integration into precursor refining. BASF SE leverages its Ludwigshafen technical heritage to sustain formulation leadership in FCC additive systems. W. R. Grace & Co. specializes in high-accessibility zeolite architectures that extend cycle lengths in heavy resid units.
Refining catalysts are heterogeneous or homogeneous substances that accelerate petroleum conversion reactions without permanent consumption, typically comprising supported metal oxides on alumina or zeolite matrices with controlled pore diameters of 0.5–10 nanometers and surface areas exceeding 200 m²/g to maximize active site exposure for hydrodesulfurization and cracking selectivity. Their primary commercial purpose is enabling refineries to upgrade lower-value feedstocks into transportation fuels and petrochemical intermediates while meeting stringent product quality specifications. Fluid catalytic cracking additives command the largest product type position due to their ubiquity in gasoline-oriented refineries, though hydrocracking catalysts represent the fastest-expanding segment as operators process heavier, higher-sulfur crudes and integrate renewable feedstocks. Heterogeneous catalysis leads technology deployment by volume, while biocatalysis and hybrid systems are gaining traction in pilot-scale renewable diesel and sustainable aviation fuel applications where conventional thermal routes face carbon intensity constraints.
EPA Tier 3 sulfur standards and California Air Resources Board Low Carbon Fuel Standard requirements are forcing refiners to deepen hydrotreating severity and shorten catalyst replacement intervals, directly expanding annual catalyst consumption volumes. OSHA Process Safety Management and EPA Risk Management Plan frameworks govern catalyst handling, regeneration, and spent catalyst disposal, adding compliance layers that favor suppliers with integrated technical service capabilities. Stakeholders must monitor how renewable diesel and sustainable aviation fuel mandates reshape catalyst specifications, as feedstock flexibility requirements and oxygenate tolerance demands will determine which formulation platforms capture replacement demand across the North American refining fleet.
Market Dynamics
The North America refining catalysts market is restructuring around feedstock flexibility mandates as Gulf Coast refiners retrofit hydrocracking units to co-process renewable diesel and sustainable aviation fuel alongside conventional crude slates.
Growth Catalysts
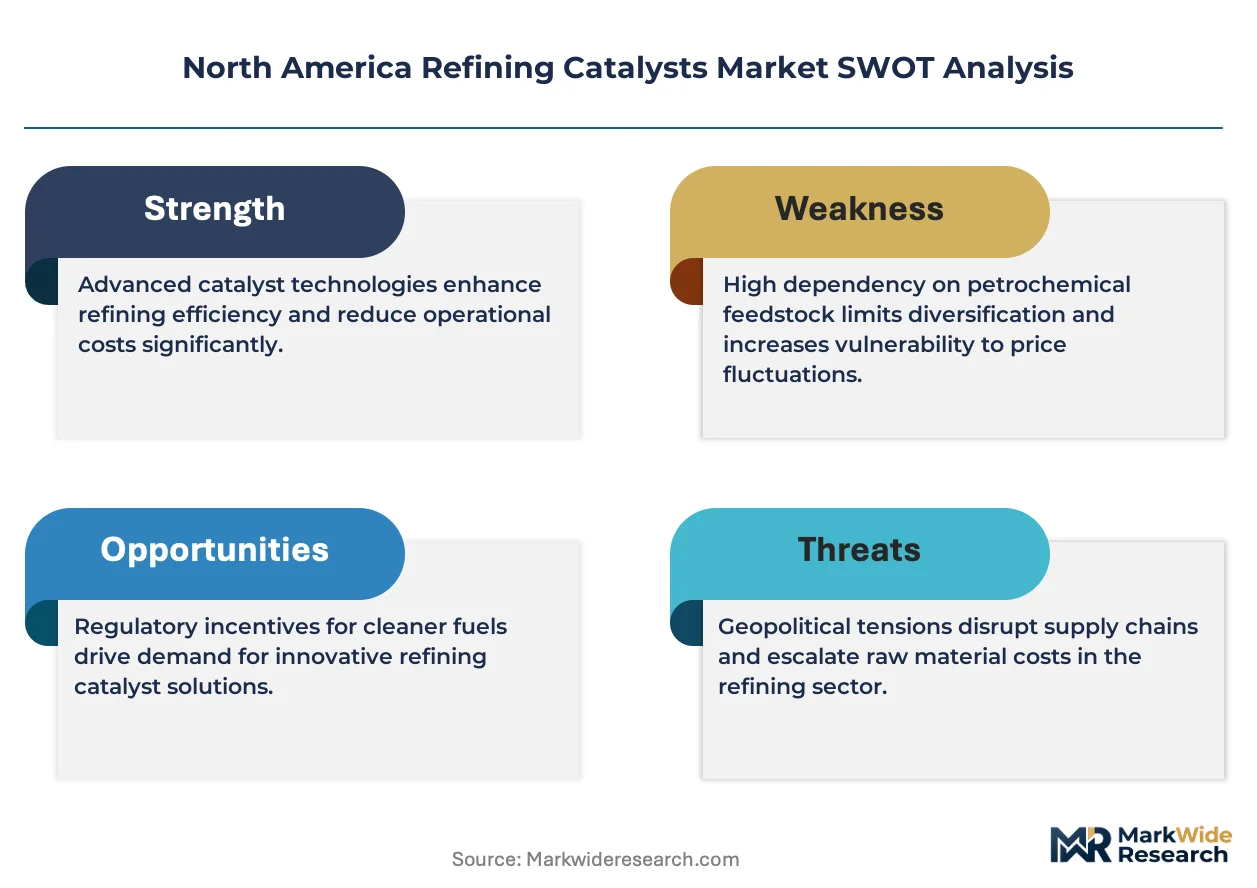
- EPA Tier 3 gasoline sulfur regulations:The 10 parts per million sulfur ceiling forces deeper hydrotreating severity across FCC naphtha and gasoline blendstock units. Catalyst refresh cycles compress as refiners chase sulfur parity.
- California Low Carbon Fuel Standard:The credit price mechanism incentivizes renewable diesel capacity additions at Bay Area and Los Angeles refineries. Hydrocracking catalyst demand intensifies for oxygenate-tolerant formulations.
- Heavy crude processing intensity:Permian Basin production growth and Venezuelan crude displacement are expanding resid hydroprocessing capacity along the Texas Gulf Coast. Metal-tolerant catalyst architectures see replacement volume concentration.
Market Restraints
- Molybdenum and cobalt precursor volatility:Bimetallic hydroprocessing catalyst production depends on concentrated mining supply from Chile and the Democratic Republic of Congo. Price swings compress formulation margins unpredictably.
- Zeolite supply concentration:Synthetic zeolite manufacturing for FCC additives clusters with three integrated suppliers controlling precursor refining and catalyst finishing. Buyers face limited alternative sourcing for high-accessibility architectures.
- Spent catalyst disposal constraints:EPA Resource Conservation and Recovery Act classification of hydroprocessing spent catalysts as hazardous waste adds logistics cost and liability. Regeneration economics deteriorate for smaller refiners.
Strategic Opportunities
- Canadian oil sands integration:Alberta upgraders and Sarnia-area refineries are expanding dilbit processing capacity. Bitumen-derived feedstock flexibility creates demand for high-metal-tolerance resid hydrocracking formulations.
- Renewable diesel co-processing:Fatty acid methyl ester and hydrotreated vegetable oil integration into existing hydrocracking trains requires modified catalyst acidity profiles. First-mover suppliers capture retrofit specification windows.
- Technical service bundling:Catalyst vendors are embedding unit optimization consulting and spent catalyst logistics into supply contracts. Integrated service platforms differentiate procurement decisions beyond formulation price.
Industry Challenges
- Hydroprocessing catalyst R&D talent scarcity:Formulation chemistry expertise in sulfided metal phase optimization and zeolite mesopore engineering concentrates with retiring technical specialists at legacy research centers.
- Renewable feedstock certification complexity:California Air Resources Board lifecycle carbon accounting and EPA Renewable Fuel Standard pathway approvals delay catalyst qualification timelines for co-processing applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Refining Catalysts Market |
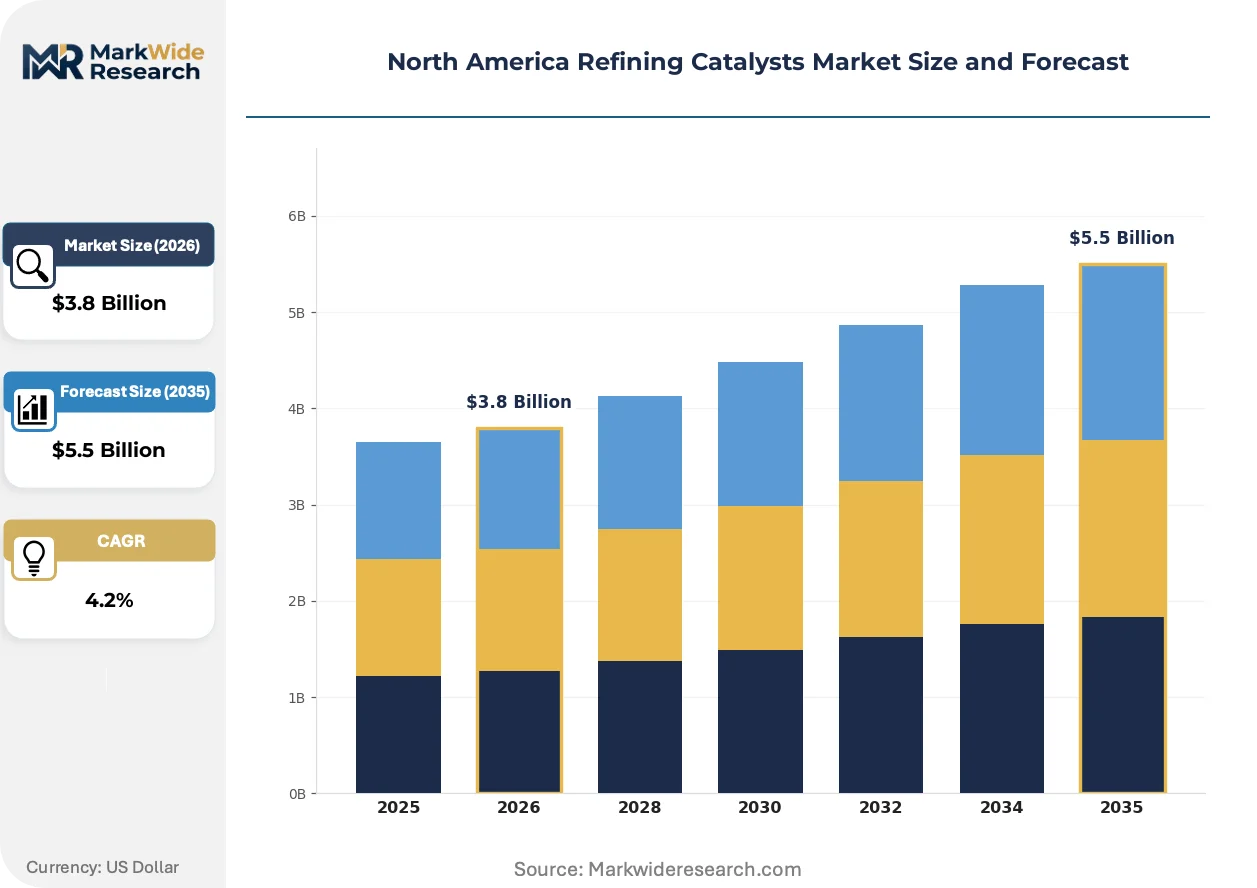
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocracking, Fluid Catalytic Cracking, Alkylation, Isomerization Technology: Heterogeneous Catalysis, Homogeneous Catalysis, Biocatalysis, Hybrid Systems End User: Petroleum Refineries, Chemical Manufacturers, Oil & Gas Companies, Power Plants Application: Gasoline Production, Diesel Production, Jet Fuel Production, Lubricants |
| Companies Covered | BASF SE, Albemarle Corporation, W. R. Grace & Co., Haldor Topsoe A/S, Honeywell UOP, Clariant, Johnson Matthey, Chevron Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Refining Catalysts Market Evolving Landscape
Catalyst technology trajectories are converging on feedstock flexibility and carbon intensity reduction as refiners navigate product slate transitions and regulatory compliance windows.
Zeolite architecture design is migrating from single-function gasoline maximization toward bifunctional cracking-hydrogenation platforms. Resid FCC operators in Texas and Louisiana are adopting hierarchical mesopore zeolites to handle higher Conradson carbon feedstocks. The shift is compressing demand for conventional Y-zeolite additives while expanding specification contests around diffusion pathway engineering.
EPA Tier 3 and California LCFS enforcement are tightening in parallel, creating overlapping compliance burdens for gasoline sulfur and carbon intensity. Refiners must simultaneously deepen hydrotreat and source lower-carbon blendstocks. FCC naphtha post-treating and renewable diesel hydrocracking catalyst segments absorb the most acute specification pressure.
Just-in-time catalyst replenishment is displacing bulk inventory stocking across Gulf Coast refinery procurement functions. Technical service bundling and performance-based supply contracts are consolidating distributor relationships. The shift concentrates most visibly in Texas, where complex refinery clusters prioritize working capital efficiency and unit uptime guarantees over spot purchasing flexibility.
North America Refining Catalysts Market Segmentation
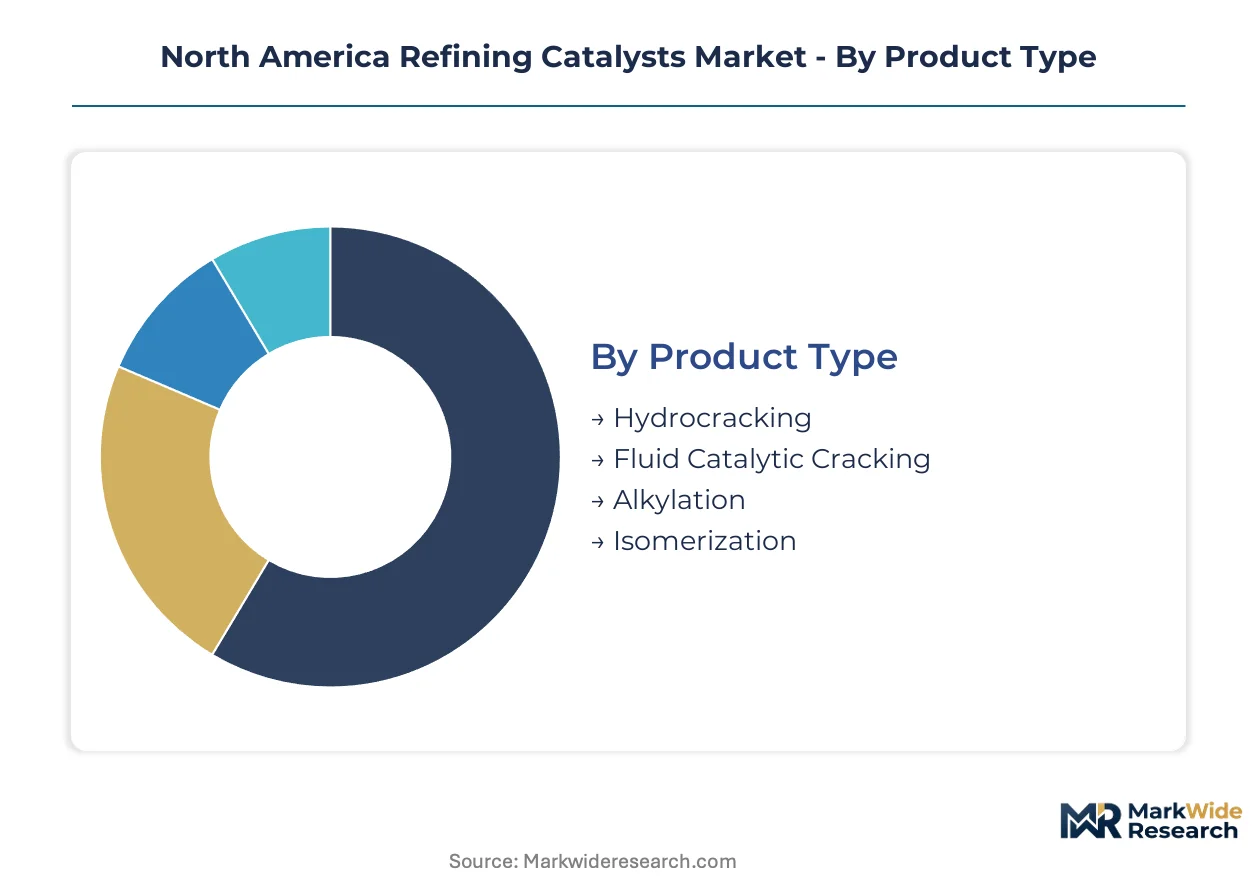
Refining catalyst procurement patterns diverge sharply across product chemistries and refinery configurations. Understanding these segment boundaries clarifies where formulation margins concentrate and which technology platforms face displacement pressure.
Product Type:
Cost tier differentiation separates commodity-scale hydrotreating formulations from premium hydrocracking architectures engineered for resid flexibility.
- Hydrocracking:Bimetallic sulfided catalysts on alumina supports achieve 90%+ conversion of heavy vacuum gas oil into middle distillates. Demand clusters along the Texas Gulf Coast as refiners upgrade coker feedstocks to capture diesel and jet fuel margins.
- Fluid Catalytic Cracking:Zeolite-based additives dominate gasoline-oriented refinery economics through controlled acid site density and mesopore engineering. FCC naphtha post-treating requirements under EPA Tier 3 are shortening additive replacement cycles in California and Texas.
- Alkylation:Solid acid catalysts displace liquid acid systems for isobutane-olefin alkylation.
- Isomerization:Chlorided alumina and zeolite platforms upgrade light naphtha octane for gasoline blending.
Hydrocracking holds installed capacity. FCC is rotating up the share rankings.
Technology:
Application maturity separates volume-dominant heterogeneous systems from emerging biocatalytic platforms targeting renewable fuel pathways.
- Heterogeneous Catalysis:Supported metal oxides and sulfides on structured supports enable fixed-bed and ebullated-bed hydroprocessing at commercial scale. This platform commands the dominant volume position across Gulf Coast resid upgrading and distillate hydrotreating units.
- Biocatalysis:Enzymatic and whole-cell systems are gaining pilot-scale traction for renewable diesel and sustainable aviation fuel production where thermal routes face carbon intensity constraints under California LCFS accounting.
- Homogeneous Catalysis:Soluble metal complexes serve specialty alkylation and oligomerization applications.
- Hybrid Systems:Combined thermal-catalytic-biocatalytic approaches are emerging for co-processing applications.
Heterogeneous catalysis holds installed capacity. Biocatalysis is rotating up the share rankings.
End User:
Customer type determines procurement scale and technical service bundling intensity across the value chain.
- Petroleum Refineries:Complex refineries in Texas and Louisiana drive the dominant catalyst consumption volumes through hydrocracking unit expansions and FCC additive refresh programs tied to sulfur specification compliance.
- Chemical Manufacturers:Petrochemical integrators in the Gulf Coast corridor purchase specialized alkylation and isomerization catalysts for olefin and aromatic production.
- Oil & Gas Companies:Upstream operators with captive refining assets procure catalysts through centralized procurement functions.
- Power Plants:Distillate-fired generation facilities represent a minor catalyst consumption channel.
Petroleum refineries hold installed capacity. Chemical manufacturers are rotating up the share rankings.
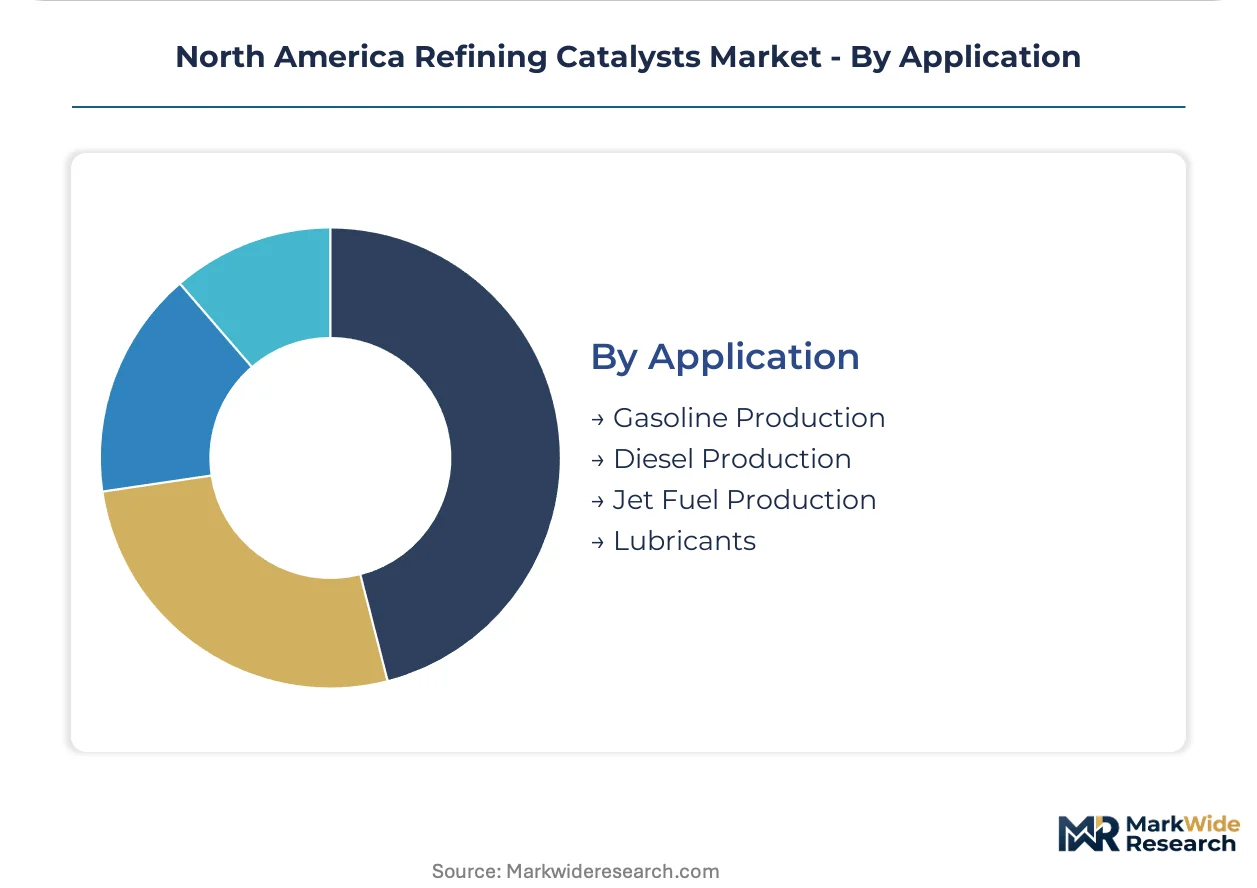
Application:
Volume concentration tracks transportation fuel demand patterns and regulatory specification timelines.
- Gasoline Production:FCC naphtha hydrotreating and isomerization catalysts face the most acute specification pressure from EPA Tier 3 sulfur ceilings. California and Texas refiners are deepening hydrotreat severity to achieve 10 ppm compliance.
- Diesel Production:Hydrocracking and hydrotreating catalysts for ultra-low-sulfur diesel production are expanding fastest as renewable diesel co-processing retrofits multiply across Bay Area and Los Angeles refineries.
- Jet Fuel Production:Kerosene hydrotreating catalysts serve commercial aviation specifications.
- Lubricants:Specialty hydrocracking for Group II/III base oils commands premium pricing.
Gasoline production holds installed capacity. Diesel production is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Louisiana command premium pricing leverage through Gulf Coast refinery density, while Canadian operators absorb logistics penalties from Alberta-to-Sarnia supply chains. This asymmetry concentrates catalyst vendor technical service investments south of the border.
United States
EPA Tier 3 gasoline sulfur mandates and California LCFS carbon intensity rules are shortening hydroprocessing catalyst cycles across Bay Area and Los Angeles refineries. The Department of Energy funds renewable diesel co-processing pilots at Gulf Coast facilities. Houston and Beaumont host the densest concentration of hydrocracking unit expansions processing Permian Basin heavy crudes.
Canada
Alberta oil sands upgraders and Sarnia-area refineries are expanding dilbit processing capacity for metal-tolerant resid hydrocracking formulations. Environment and Climate Change Canada carbon pricing mechanisms accelerate renewable diesel retrofit timelines. The Edmonton-to-Sarnia corridor drives catalyst demand for bitumen-derived feedstock flexibility.
Mexico
Pemex refinery modernization programs at Cadereyta and Salamanca are importing hydrocracking catalyst systems for heavy Maya crude upgrading. Mexican energy regulatory reforms open private sector participation in downstream catalyst procurement. Tula and Minatitlán refineries represent emerging demand nodes for FCC additive refresh programs.
North America Refining Catalysts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor refining and zeolite architecture supply. The North American refining catalysts market consolidates around three integrated suppliers controlling bimetallic precursor refining and high-accessibility zeolite finishing. Strategic archetypes separate backward-integrated metal oxide processors from formulation-focused additive designers and technical service bundlers. Capacity expansion and performance-based supply contracting constitute the dominant competitive moves as vendors embed unit optimization consulting into long-term agreements.
Among European-headquartered chemical conglomerates, BASF SE and Clariant occupy positions emphasizing Ludwigshafen technical heritage and specialty chemical formulation leadership respectively. Johnson Matthey represents the UK-based precious metal catalyst archetype with deep hydroprocessing heritage. Albemarle Corporation anchors the US-based bimetallic hydroprocessing catalyst tier through captive precursor refining capabilities. These three exemplify how geographic proximity to Gulf Coast demand clusters shapes competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Haldor Topsoe A/S |
| Honeywell UOP |
| Clariant |
| Johnson Matthey |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
The Texas Gulf Coast catalyst manufacturing corridor concentrates bimetallic precursor refining and zeolite finishing capacity within a 200-mile radius of Houston. This geographic clustering grants integrated suppliers substantial pricing leverage over refiners dependent on just-in-time replenishment cycles.
Pricing Analysis
The customization-premium spread separates configured-to-order hydrocracking formulations from standard FCC additive catalog pricing. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by certification grade (EPA Tier 3 compliance tier) and volume scale. Cost compression in standard-grade hydrotreating catalysts is intensifying because of molybdenum precursor volatility from Chilean mining concentration. Independent refiners exhibit the highest price sensitivity, while integrated majors with captive technical service bundling absorb premium pricing for cycle-length guarantees.
Supply Chain Analysis
Contract manufacturing concentration for synthetic zeolite architectures rests with three integrated suppliers controlling precursor refining and catalyst finishing in the United States, Germany, and Japan. Raw material dependencies draw from Chilean molybdenum, Congolese cobalt, and domestic alumina from Louisiana refineries. Single-source vulnerability concentrates in high-accessibility zeolite supply for heavy resid applications. Distribution runs through technical service bundlers embedding unit optimization consulting into supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against renewable fuel pathway disruption as bio-catalytic platforms gain pilot-scale traction under California LCFS carbon accounting frameworks.
For Market Incumbents: Harden formulation moats by deepening backward integration into bimetallic precursor refining and securing captive zeolite architecture supply. Expand technical service bundling capacity in Texas and Louisiana to embed unit optimization consulting into long-term agreements. Biocatalytic pilot-scale traction represents the primary substitution threat requiring monitoring.
For New Entrants and Emerging Players: Canadian oil sands upgraders present the most penetrable demand node for metal-tolerant resid hydrocracking formulations. Alberta-to-Sarnia logistics penalties disadvantage incumbent Gulf Coast suppliers on delivered cost. Target Environment and Climate Change Canada carbon pricing acceleration as the regulatory wedge for renewable diesel retrofit catalyst qualification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated bimetallic precursor processors with captive technical service platforms over pure-play formulation specialists. Long-term viability hinges on feedstock flexibility R&D pipelines spanning conventional crude and renewable diesel co-processing. Watch EPA Tier 3 enforcement acceleration and California LCFS credit price volatility as inflection indicators for catalyst refresh cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Captive molybdenum and cobalt supply secures margin stability against Chilean and Congolese mining volatility. |
| Technical Service Bundling Expansion | Embedded unit optimization consulting in Texas and Louisiana consolidates distributor relationships beyond formulation price. |
| Renewable Diesel Co-Processing Qualification | California LCFS compliance timelines accelerate oxygenate-tolerant hydrocracking catalyst specification windows. |
| High-Metal-Tolerance Resid Formulation Development | Alberta oil sands dilbit processing expansion creates differentiated demand for bitumen-derived feedstock flexibility. |
| Spent Catalyst Logistics Integration | EPA RCRA hazardous waste classification favors suppliers controlling regeneration and disposal compliance layers. |
Research Methodology
The analysis maps hydrocracking catalysts, FCC additives, alkylation catalysts, and isomerization platforms, each validated through refinery procurement directors, technical service managers, and catalyst R&D leads. Primary interviews with plant managers at Gulf Coast and California refineries combined with secondary validation from EPA enforcement databases, EIA refinery capacity reports, and SEC 10-K filings from integrated suppliers. Bottom-up unit-level catalyst consumption estimates triangulated against top-down regional refining capacity projections.
Assumptions held fixed include EPA Tier 3 sulfur enforcement timelines and California LCFS credit price mechanisms, while renewable diesel co-processing penetration rates and Permian Basin heavy crude production trajectories were varied across scenarios. Segmentation dimensions modeled span product chemistry, refinery complexity tier, and regional regulatory cluster. CAGRs were derived from unit-level refresh cycle compression rates and capacity expansion announcements across the projection horizon. Industry-specific inputs include hydrocracking severity indices and FCC naphtha post-treating catalyst replacement frequencies.
Practitioners should monitor California LCFS credit price volatility, EPA Tier 3 enforcement acceleration, and renewable fuel mandate expansion for early signals of specification pressure shifts. Forecasts reflect these documented assumptions alongside molybdenum precursor supply concentration and zeolite manufacturing capacity constraints. Quarterly review of refinery retrofit announcement flows and spent catalyst disposal cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Environmental Catalysts Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Global FCC Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Industrial Catalyst Market