
 South America Carbon Black Market | 2026-2036
South America Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
South America Carbon Black Market Analytics
Project finance tied to petrochemical complex expansions is reconfiguring competitive entry barriers across the South America Carbon Black Market. Cabot Corporation leverages its integrated refinery partnerships to secure advantaged feedstock access along Brazil's coast. Orion Engineered Carbons anchors its position through specialized furnace black production serving tire OEMs in Argentina. Birla Carbon sustains cost leadership via backward integration into carbonaceous raw material sourcing.
Carbon black consists of elemental carbon produced through incomplete combustion or thermal decomposition of hydrocarbons, with primary particle sizes ranging from ten to five hundred nanometers and surface areas between twenty and two hundred fifty square meters per gram; it functions predominantly as a reinforcing filler and pigment in rubber, plastics, and coating systems. The tire manufacturing application dominates volume consumption across the region, while coatings and printing inks command superior margin pools due to stricter purity and dispersion specifications. Synthetic carbon black leads production volumes, though acetylene black occupies a defensible niche in high-conductivity electronics applications serving Brazil's consumer goods sector.
ANVISA in Brazil and the Argentine Secretariat of Industry regulate product contact standards for carbon black in consumer-facing applications, while national environmental agencies enforce emissions thresholds on furnace and thermal process operations. These frameworks elevate compliance costs for imported material while creating preferential market access for producers with certified low-aromatic output. Stakeholders must monitor feedstock cost volatility and evolving national content rules to sustain procurement flexibility across the regional tire supply chain.
Market Dynamics
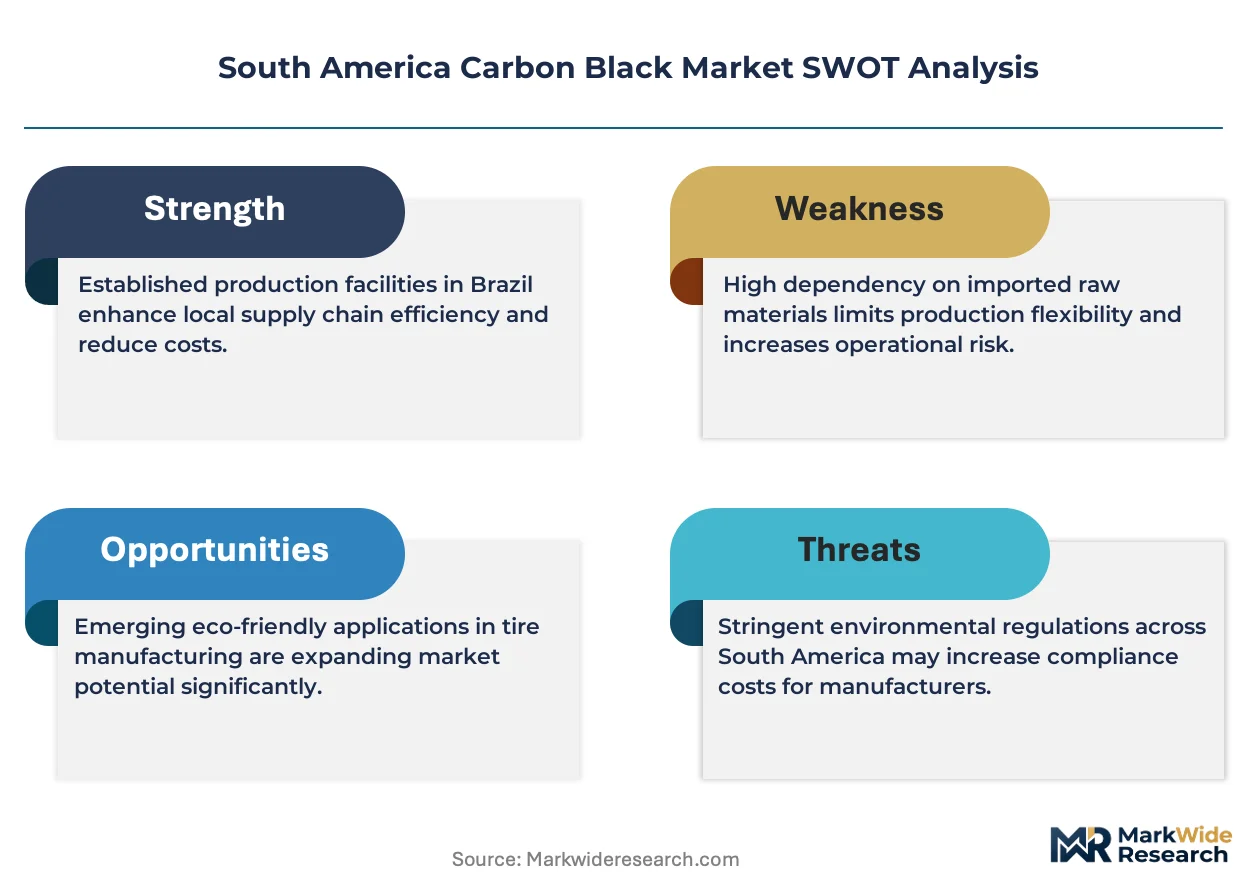
Feedstock cost volatility at Brazil's petrochemical complexes is forcing furnace black producers to renegotiate long-term supply contracts with domestic refiners, compressing margin buffers across the regional value chain.
Growth Catalysts
- ANVISA contact standards:Brazil's tightened purity mandates for rubber goods are disqualifying uncertified imports and redirecting procurement toward domestic furnace black producers with validated low-aromatic output.
- Tire OEM localization:Argentine and Brazilian tire manufacturers are expanding captive blending facilities to meet national content thresholds in government fleet procurement.
- Acetylene black conductivity:Electronics assemblers in São Paulo's consumer goods corridor are qualifying high-structure material for battery and cable applications.
Market Restraints
- Residual oil feedstock volatility:Price swings at Brazil's coastal refineries transmit directly to carbon black production economics, destabilizing contract pricing.
- Import dependency for thermal black:Argentina lacks domestic thermal process capacity, exposing specialty rubber compounders to currency-driven supply interruptions.
- High-purity coatings substitution:precipitated silica is capturing share in premium tire tread formulations where rolling resistance specifications tighten.
Strategic Opportunities
- Colombia's underdeveloped rubber sector:Tire retreading operations in Bogotá and Medellín represent unserved demand for standard-grade furnace black.
- Chilean mining conveyor belts:Copper extraction operations are expanding wear-resistant rubber consumption in Antofagasta and Calama.
- Bio-based feedstock qualification:Brazilian national development bank financing is accelerating pyrolysis oil pilot projects for sustainable carbon black.
Industry Challenges
- Furnace process emissions compliance:Retrofitting thermal oxidizers at aging Brazilian plants requires capital deployment amid compressed operating margins.
- Specialty carbon black certification timelines:ANVISA registration for food-contact grades extends 18-24 months, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Carbon Black Market |
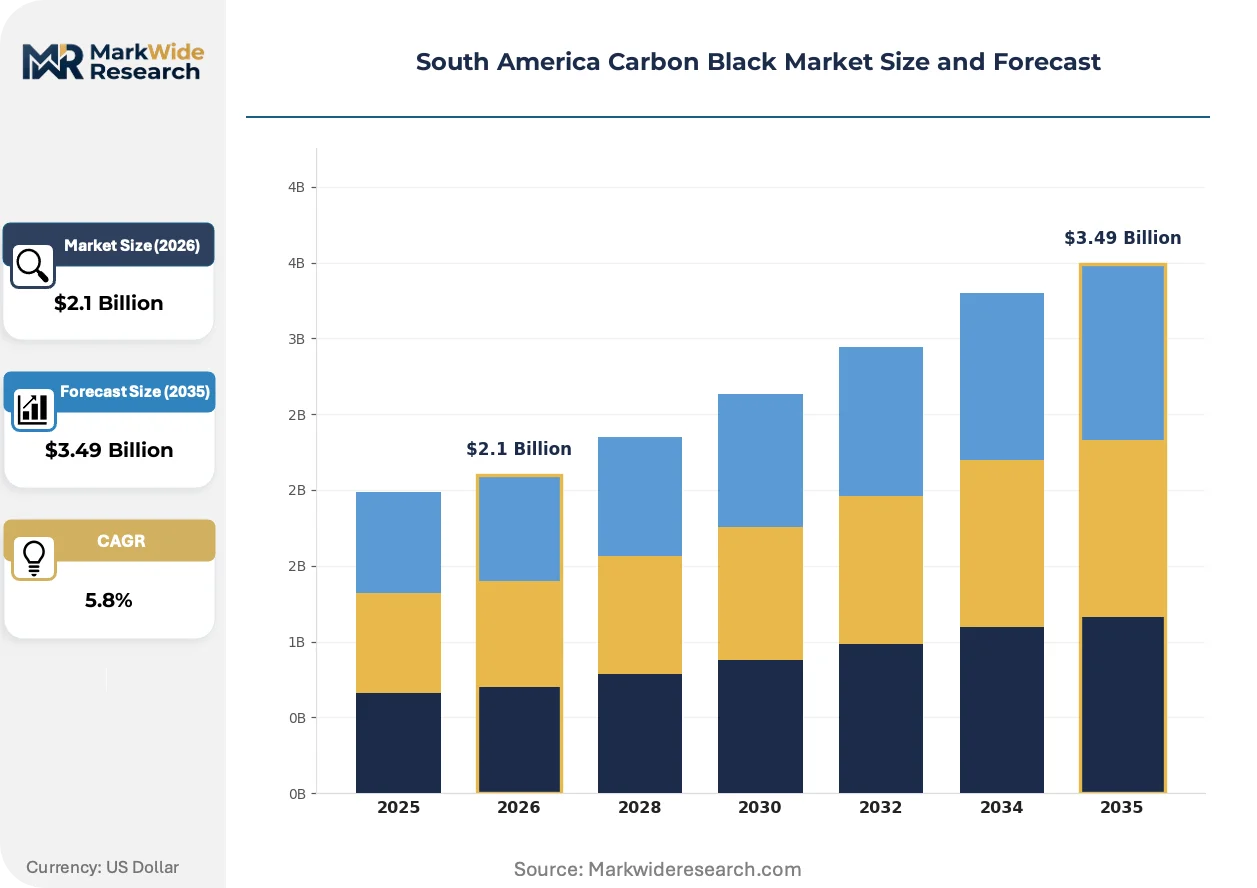
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Carbon Black, Synthetic Carbon Black, Acetylene Black, Lamp Black Application: Tire Manufacturing, Coatings, Plastics, Printing Inks End User: Automotive, Construction, Electronics, Consumer Goods Grade: Standard Grade, Premium Grade, High-Performance Grade, Industrial Grade |
| Companies Covered | Cabot Corporation, Mitsubishi Chemical Holdings Corporation, Orion Engineered Carbons, Birla Carbon, Phillips Carbon Black Ltd, Bridgestone Corporation, Tokai Carbon Co., Ltd, Koppers Inc., Hubron International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Carbon Black Market Evolving Landscape
Process intensification and regulatory tightening are converging to reshape how South American producers configure feedstock sourcing and furnace operations.
Oil-furnace reactor technology is collapsing the cost gap between commodity and semi-reinforcing grades. Brazilian producers retrofitting with quench tower optimization are capturing higher surface-area output from the same residual oil throughput. Tire compounders in São Paulo's industrial belt are qualifying this output for passenger car radial formulations previously requiring imported material.
ANVISA's updated rubber goods contact standards are elevating analytical testing burdens across the supply chain. Domestic producers must now document polycyclic aromatic hydrocarbon content below 0.1 percent for consumer-facing applications. Importers lacking certified laboratory partnerships face extended customs holds at Santos port, advantaging local furnace operators with in-house chromatography capabilities.
Buyer consolidation among Argentine tire OEMs is compressing supplier negotiation cycles. Three manufacturers now control over sixty percent of national compound procurement, shifting contract structures from spot purchases to eighteen-month framework agreements with volume guarantees. Procurement teams in Buenos Aires and Cordoba are bundling carbon black with silica and process oil into single-source tenders, squeezing distributor margins.
South America Carbon Black Market Segmentation
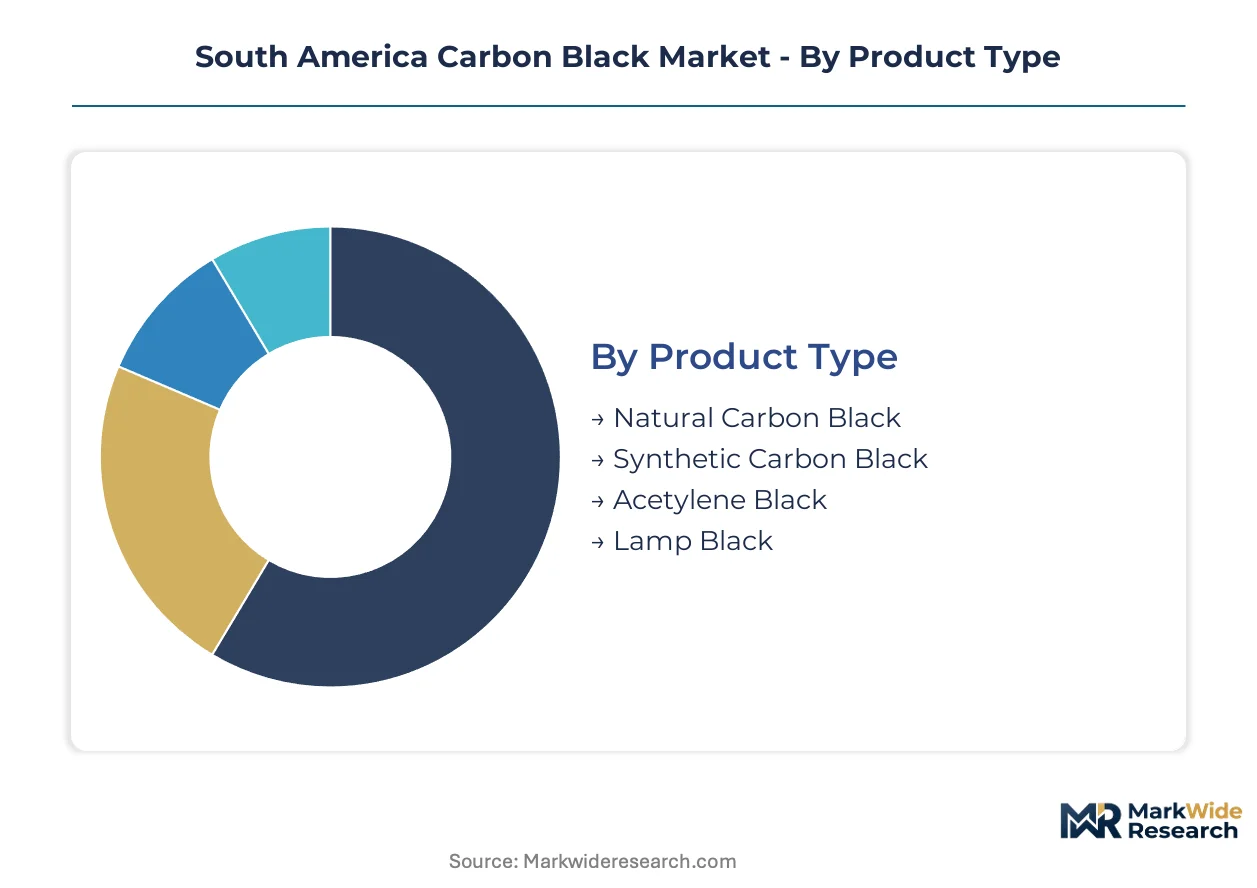
Carbon black segmentation in South America reflects divergent procurement cycles across tire OEMs, specialty compounders, and industrial buyers. Understanding these velocity differences enables suppliers to align inventory positioning with customer replenishment patterns and margin capture opportunities.
Product Type:
Synthetic carbon black turns inventory fastest through Brazilian tire plants, while acetylene black cycles slowest due to electronics qualification protocols. Natural carbon black and lamp black occupy intermediate velocity positions tied to coatings and specialty rubber applications.
- Synthetic Carbon Black:Furnace-processed material derived from residual oil or natural gas feedstock, with primary particle sizes tunable from twenty to one hundred nanometers. Brazilian tire manufacturers in the São Paulo-Rio corridor consume this grade in bulk for passenger and commercial vehicle tread compounds, driven by ANVISA-mandated low-aromatic certification requirements that favor domestic furnace operators with in-house testing capabilities.
- Acetylene Black:Produced through thermal decomposition of acetylene gas, yielding high-structure carbon with exceptional electrical conductivity and purity. Electronics assemblers in São Paulo's consumer goods corridor qualify this material for lithium-ion battery electrodes and antistatic cable sheathing, constrained by eighteen-to-twenty-four-month OEM validation timelines that compress volume ramp rates.
- Natural Carbon Black:Derived from vegetable or mineral sources with lower surface area and reinforcing efficiency. Argentine rubber goods producers blend limited quantities into non-critical industrial molded products where cost minimization outweighs performance specifications.
- Lamp Black:Traditionally produced through controlled combustion of liquid hydrocarbons, yielding larger particle sizes and lower structure. Colombian coatings formulators in Bogotá source this grade for decorative tinting applications with minimal regulatory burden.
Synthetic carbon black anchors the volume base while acetylene black gains share at the steepest rate.
Application:
Margin stratification across applications tracks purity requirements and compounder concentration, with coatings commanding premium realizations and tire manufacturing driving throughput scale.
- Tire Manufacturing:Reinforcing filler in tread, sidewall, and carcass compounds, requiring precise surface area and structure matching to polymer systems. Brazilian OEM captive blending facilities in São Paulo state source furnace black under eighteen-month framework agreements with volume guarantees, pressured by national content thresholds in government fleet procurement.
- Coatings:Pigmentation and UV protection in automotive refinish and industrial protective systems, demanding sub-micron dispersion and low grit content. Argentine import-dependent compounders face currency-driven supply interruptions for high-purity thermal black, elevating landed costs versus domestic furnace alternatives.
- Plastics:Conductive and UV-stabilizing additive in polyethylene and polypropylene masterbatches. Chilean mining equipment suppliers in Antofagasta specify carbon-black-loaded conveyor belt compounds for abrasion resistance in copper extraction operations.
- Printing Inks:Deep black pigmentation with gloss control in publication gravure and packaging flexographic systems. Brazilian ink formulators prioritize domestic furnace black with validated PAH documentation to avoid Santos port customs holds under ANVISA's tightened contact standards.
Tire manufacturing generates the highest throughput volumes while coatings deliver the steepest margin expansion trajectory.
End User:
Procurement sophistication varies sharply across end-user verticals, with automotive buyers imposing the most stringent qualification protocols and construction purchasers prioritizing cost minimization.
- Automotive:Tire OEMs and tier-one suppliers with integrated compound mixing operations. Argentine manufacturers in Buenos Aires and Cordoba bundle carbon black with silica and process oil into single-source tenders, compressing distributor margins and extending payment terms.
- Construction:Industrial rubber goods and sealant producers with dispersed, price-sensitive procurement. Colombian retreading operations in Medellín represent unserved demand for standard-grade furnace black amid underdeveloped domestic supply infrastructure.
- Electronics:Battery and cable manufacturers requiring high-conductivity acetylene black with documented trace metal content. São Paulo-based assemblers qualify suppliers through extended pilot production runs before committing to volume contracts.
- Consumer Goods:Rubber household products and packaging applications subject to direct ANVISA contact standards. Domestic Brazilian producers with certified low-aromatic output capture share previously held by uncertified imports facing extended customs processing.
Automotive anchors procurement volume while electronics expands most quickly on conductivity material qualification.
Grade:
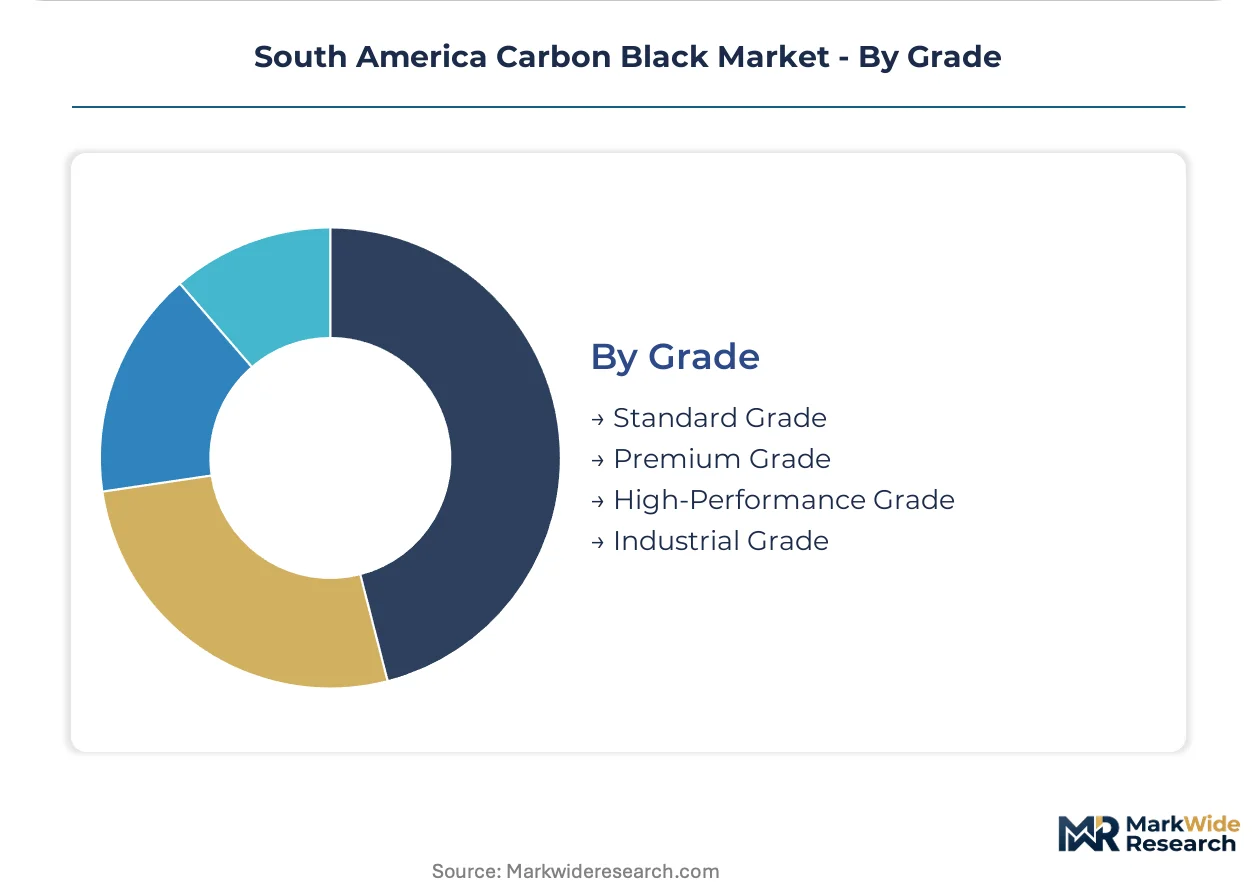
Grade tiering reflects performance certification depth and customer switching costs, with premium grades locking in compounder relationships and industrial grades trading on spot price sensitivity.
- Standard Grade:Commodity furnace black meeting baseline reinforcing specifications for commercial vehicle and off-road tire applications. Brazilian producers retrofitting with quench tower optimization capture higher surface-area output from identical residual oil throughput, qualifying this material for passenger radial formulations previously requiring imported premium grades.
- Premium Grade:Tighter particle size distribution and lower grit content for passenger vehicle OEM tires and high-performance coatings. ANVISA registration timelines of eighteen to twenty-four months for validated low-aromatic output create defensive moats for incumbent domestic producers with established laboratory partnerships.
- High-Performance Grade:Ultra-low PAH content and specialized surface chemistry for food-contact and medical rubber goods. Limited domestic production capacity in Argentina exposes specialty compounders to import dependency and currency volatility.
- Industrial Grade:Basic reinforcing specifications for conveyor belts, hoses, and molded industrial products. Chilean mining operations in Calama source this grade for wear-resistant rubber consumption with minimal certification burden.
Standard grade maintains volume dominance while premium grade captures expanding share on OEM qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's tightened purity mandates and Brazil's national development bank financing for sustainable feedstock projects are redirecting investment flows across South American carbon black production clusters.
Brazil
Tire OEM captive blending facilities in São Paulo state consume the bulk of regional furnace black volume, pressured by national content thresholds in government fleet procurement. ANVISA enforces sub-0.1 percent polycyclic aromatic hydrocarbon limits for consumer-facing rubber goods, advantaging domestic producers with in-house chromatography capabilities. The São Paulo-Rio de Janeiro industrial corridor anchors production gravity, with coastal refineries supplying residual oil feedstock to integrated carbon black plants.
Argentina
Three tire manufacturers now control over sixty percent of national compound procurement, shifting contract structures toward eighteen-month framework agreements with volume guarantees. The Argentine Secretariat of Industry regulates product contact standards for carbon black in consumer applications, elevating compliance costs for imported material. Buenos Aires and Cordoba host the concentrated buyer base, where procurement teams bundle carbon black with silica and process oil into single-source tenders.
Chile
Copper extraction operations in Antofagasta and Calama are expanding wear-resistant rubber consumption for mining conveyor belts, generating pull for industrial-grade furnace black. Chile's national environmental agency enforces emissions thresholds on industrial process operations, shaping local production economics. The Antofagasta Region concentrates mining-driven demand, with equipment suppliers specifying carbon-black-loaded compounds for abrasion resistance.
Colombia
Tire retreading operations in Bogotá and Medellín represent unserved demand for standard-grade furnace black amid underdeveloped domestic supply infrastructure. The country's national environmental regulator monitors industrial emissions from rubber processing facilities, though with less stringent thresholds than Brazil. Bogotá's coatings formulators source lamp black for decorative tinting applications with minimal certification burden.
South America Carbon Black Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tilting toward feedstock-integrated scale operators. The competitive landscape organizes around three strategic archetypes: integrated petrochemical players with refinery partnerships, specialized furnace black producers serving tire OEM qualification protocols, and regional distributors managing import logistics for specialty grades. Dominant competitive moves include backward integration into carbonaceous raw material sourcing and strategic partnerships with domestic refiners to secure residual oil offtake agreements.
Among the integrated multinational tier, Cabot Corporation anchors positions through coastal refinery partnerships in Brazil, while Orion Engineered Carbons occupies a specialist position serving Argentine tire OEM qualification requirements. Birla Carbon exemplifies cost-leadership archetypes through upstream control over carbonaceous raw material sourcing. These three entities represent the primary competitive anchors shaping regional supply configurations.
| Leading Market Players |
|---|
| Cabot Corporation |
| Mitsubishi Chemical Holdings Corporation |
| Orion Engineered Carbons |
| Birla Carbon |
| Phillips Carbon Black Ltd |
| Bridgestone Corporation |
| Tokai Carbon Co., Ltd |
| Koppers Inc. |
| Hubron International |
| Others |
Value Network & Pricing Analysis
The Santos port corridor links coastal Brazilian refineries to São Paulo tire plants, with freight cost volatility transmitting directly to landed price spreads between domestic furnace black and imported thermal grades. This logistics backbone concentrates supply-side leverage among feedstock-integrated producers while forcing distributors to absorb margin compression on spot purchases.
Pricing Analysis
ANVISA certification level creates the primary spread between premium and commodity furnace black, with validated low-aromatic output commanding fifteen-to-twenty percent realizations above uncertified imports. Pricing stratifies across premium, standard, and industrial tiers, with tire OEMs in Buenos Aires and Cordoba extracting volume discounts through eighteen-month framework agreements. Cost compression in standard-grade material is intensifying because Brazilian producers retrofitting quench tower optimization now qualify higher-surface-area output from identical residual oil throughput. Construction-sector buyers in Colombia represent the most price-sensitive segment, while electronics assemblers in São Paulo's consumer goods corridor accept premium realizations for documented trace metal content.
Supply Chain Analysis
Integrated petrochemical complexes in Brazil, Argentina, and Chile hold the bulk of regional furnace black capacity, with coastal refinery partnerships determining feedstock access economics. The supply chain draws from residual oil offtake agreements, natural gas feedstock procurement, and pyrolysis oil pilot projects under national development bank financing. Single-source vulnerability concentrates in Argentina's thermal black import dependency, where currency-driven supply interruptions expose specialty rubber compounders to extended replenishment cycles. Distribution runs through captive blending facilities at tire OEMs, bulk tanker shipments to industrial compounders, and containerized imports for specialty grades clearing customs at Santos and Buenos Aires ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as sustainable feedstock qualification opens new procurement channels previously blocked by petrochemical integration. ANVISA's tightened purity mandates accelerate domestic substitution for uncertified imports, extending runway for certified producers.
For Market Incumbents: Entrench position through backward integration into carbonaceous raw material sourcing and accelerated ANVISA registration for food-contact grades before eighteen-to-twenty-four-month timelines lock out competitors. Precipitated silica substitution in premium tire tread formulations threatens carbon black volume capture; defend by qualifying furnace black for rolling resistance specifications through surface chemistry modification. Capacity addition in Colombia's underdeveloped rubber sector captures retreading demand before infrastructure investment hardens competitive positions. For New Entrants and Emerging Players: Colombia's Bogotá and Medellín retreading corridors offer the most penetrable white-space for standard-grade furnace black, with minimal incumbent presence and lower certification burdens than Brazilian consumer-facing applications. Chilean mining conveyor belt specifications in Antofagasta and Calama generate pull for industrial-grade material with abbreviated qualification cycles. A go-to-market angle anchored to pyrolysis oil sustainability credentials accesses Brazilian national development bank financing and differentiates against residual oil-dependent incumbents. For Investors and Strategic Acquirers: Specialist furnace black producers with validated ANVISA laboratory partnerships and established tire OEM qualification protocols represent the most defensible acquisition archetype, with switching costs extending eighteen-month framework agreements into recurring revenue streams. Long-term viability hinges on feedstock flexibility across residual oil, natural gas, and emerging bio-based alternatives. The signal to watch is BNDES financing disbursement velocity for pyrolysis oil pilot projects, which would accelerate sustainable carbon black commercialization and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbonaceous Feedstock | Cabot Corporation's refinery partnerships demonstrate how upstream control secures residual oil offtake against coastal competitor access. |
| ANVISA Certification Investment | In-house chromatography capabilities at domestic Brazilian producers eliminate Santos port customs delays that disadvantage uncertified imports. |
| Pyrolysis Oil Pilot Scale-Up | BNDES-financed sustainable feedstock projects in São Paulo state redirect procurement qualification toward low-carbon intensity suppliers. |
| Colombia Distribution Infrastructure | Bogotá and Medellín retreading corridor penetration captures unserved demand before incumbent furnace black producers extend geographic coverage. |
| Acetylene Black Electronics Qualification | Eighteen-to-twenty-four-month OEM validation timelines in São Paulo's consumer goods corridor create defensive moats for early-qualified suppliers. |
Research Methodology
Desk research of customs trade databases, ANVISA regulatory filings, and petrochemical complex expansion disclosures preceded structured interviews with tire OEM procurement directors, carbon black plant managers, and Brazilian national development bank project officers. Primary fieldwork with downstream rubber compounders and secondary validation against SEC 10-K filings from integrated multinational producers enabled bottom-up volume triangulation against top-down feedstock consumption estimates.
Forecast assumptions held ANVISA regulatory stringency and national content thresholds fixed at current enforcement levels while varying feedstock cost trajectories and sustainable material adoption rates across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from production capacity utilization trends, tire OEM captive blending facility expansion schedules, and mining sector conveyor belt replacement cycles in Chile's copper extraction operations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pyrolysis oil specialists or precipitated silica compounders would shift outcomes beyond modeled ranges. Quarterly review of BNDES sustainable feedstock financing disbursements, ANVISA certification approval velocities, and Argentine tire OEM procurement consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Triazine Market