
 Copper and Copper Alloy Market | 2026-2036
Copper and Copper Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Copper Alloy Market Analysis
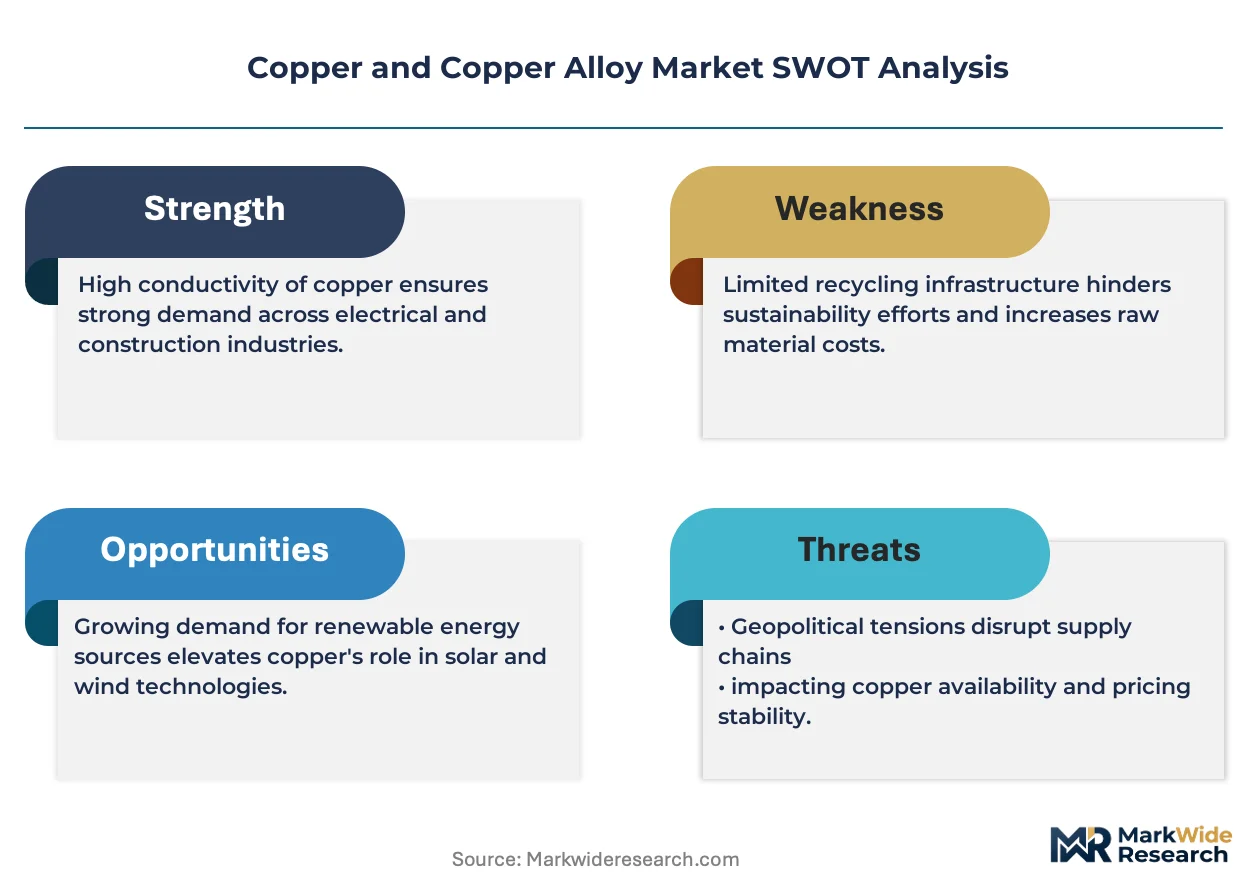
Subscription-based alloy certification and traceability services is recalibrating how copper products are specified and procured across industrial supply chains. Aurubis AG leverages its European refining network to anchor premium positions in low-carbon cathode segments. Jiangxi Copper Corporation dominates Asia-Pacific concentrate processing through integrated mine-to-smelter operations. Mitsubishi Materials Corporation specializes in high-performance copper alloys for semiconductor lead frames and thermal management applications.
Copper and copper alloys encompass metallic materials containing copper as the base element, typically exceeding 99.3% purity in electrolytic grades, with alloy additions such as tin, zinc, nickel, or beryllium engineered to enhance strength, corrosion resistance, or electrical conductivity through processes including continuous casting, hot rolling, and precipitation hardening. These materials serve as essential conductors, structural components, and heat exchangers across power generation, building systems, transportation, and electronic device manufacturing. Copper tube commands durable demand from plumbing and HVAC contractors seeking reliability in press-fit installation systems, while copper sheet segments capture margin pools in architectural cladding and electromagnetic shielding for data centers. Electrical grade material leads volume allocation due to grid modernization and renewable energy interconnection requirements.
REACH and RoHS frameworks in Europe restrict hazardous substance content in electrical and electronic equipment, redirecting formulation toward lead-free and cadmium-free alloy variants. China's GB standards and MEE environmental compliance mandates enforce sulfur dioxide emissions caps that reshape smelter economics and concentrate sourcing patterns. The US EPA and OSHA jointly regulate airborne metal exposure in fabrication facilities, influencing capital equipment decisions for dust collection and worker protection systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and scrap flow restrictions as these instruments increasingly determine competitive access to premium market tiers.
Market Dynamics
China's MEE emissions standards and dual carbon goals are forcing smelter consolidation toward low-carbon refining, while electric vehicle battery interconnect specifications pull fabrication capacity toward Southeast Asian hubs.
Growth Catalysts
- EV Motor Winding Demand:Automotive OEMs specify high-conductivity copper for traction motor windings, pulling volume through dedicated alloy grades certified for thermal cycling endurance.
- REACH and RoHS Reformulation:European electrical equipment mandates redirect alloy procurement toward lead-free and cadmium-free variants, creating specification premiums for compliant suppliers.
- Southeast Asian Fabrication Hubs:Electronics and automotive supply chain diversification concentrates demand in Vietnam and Indonesia, where new rolling and extrusion capacity comes online.
Market Restraints
- Concentrate Supply Concentration:Chilean and Peruvian mine output disruptions transmit directly to smelter feedstock costs, amplifying margin volatility for non-integrated processors.
- Aluminum Substitution in HVAC:Microchannel heat exchanger designs specify aluminum tube for residential air conditioning, compressing copper tonnage in volume segments.
- GB Standards Compliance Burden:China's sulfur dioxide emissions caps and wastewater discharge rules force capital-intensive scrubber retrofits at legacy smelters.
Strategic Opportunities
- Data Center Thermal Management:Liquid cooling rack architectures specify high-purity copper cold plates and manifolds, opening specification channels outside traditional electrical applications.
- Carbon Border Adjustment Positioning:EU CBAM implementation rewards verified low-carbon cathode production, creating tiered market access for European and Asian smelters with emissions certification.
- Subscription Traceability Services:Blockchain-linked alloy certification platforms enable premium pricing for conflict-free and carbon-accounted material in automotive and electronics procurement.
Industry Challenges
- Electrometallurgical Talent Scarcity:Hydrometallurgical and solvent extraction expertise gaps constrain smelter modernization timelines, particularly for atmospheric and pressure leaching circuit upgrades.
- Scrap Sortation Technology Gaps:Mixed-alloy feedstock identification and separation limitations reduce secondary copper recovery rates, forcing primary metal substitution in tight specification applications.
- Multi-Jurisdiction Certification Overlap:Simultaneous REACH, RoHS, and GB standard compliance creates testing redundancy and documentation complexity for exporters serving European and Chinese markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper and Copper Alloy Market |
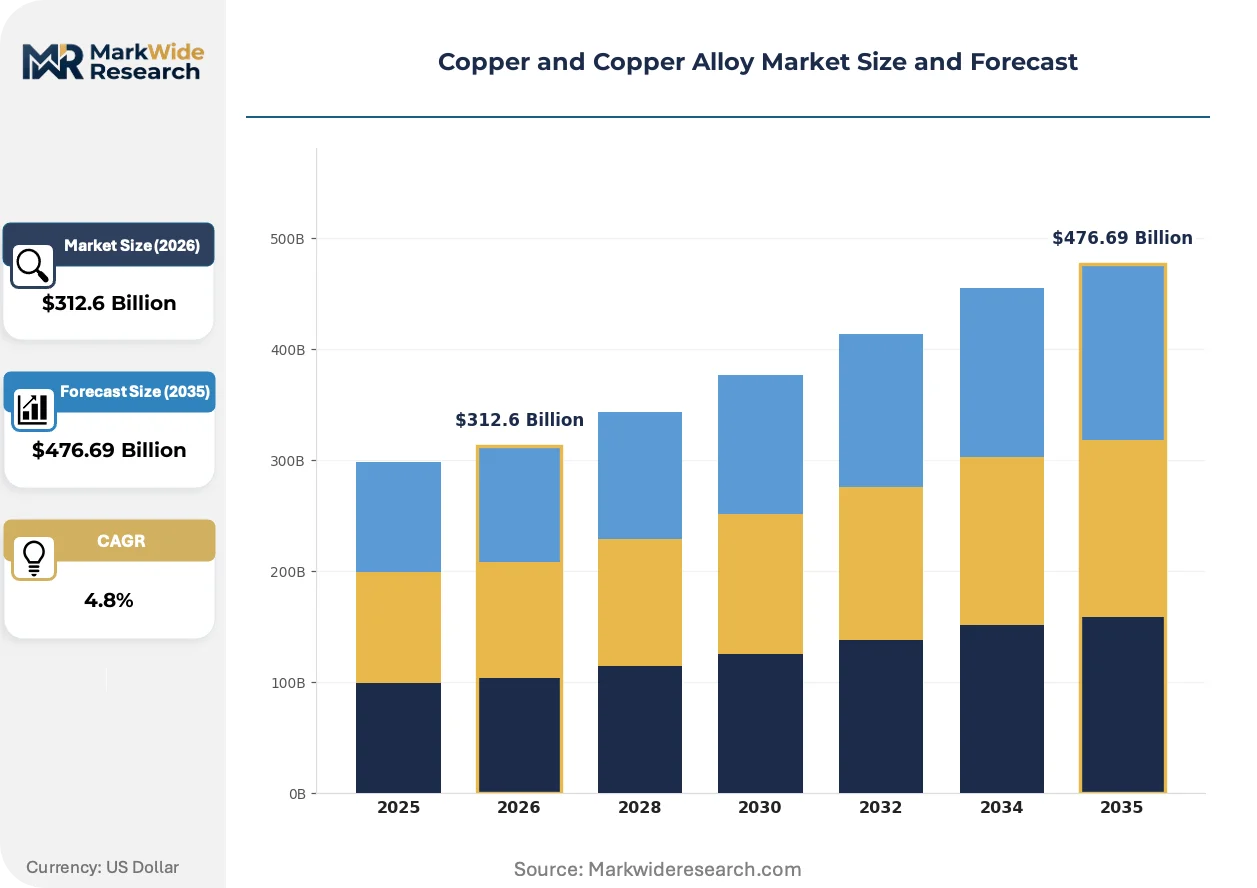
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Rod, Copper Scrap, Copper Sheet, Copper Tube Application: Electronics, Plumbing, Construction, Automotive End User: Manufacturers, Contractors, Distributors, Retailers Grade: Commercial, Electrical, Architectural, Others |
| Companies Covered | Mitsubishi Materials Corporation, poongsan corporation, Aurubis AG, AMPCO Metal, Amari Copper Metals, KME Group S.p.A., Jiangxi Copper Corporation, Copper Alloys Ltd., Wieland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Copper Alloy Market Emerging Trajectories
Continuous casting and solidification modeling software are compressing development cycles for customized alloy grades, while regulatory carbon accounting and procurement digitization reshape how material specifications are transmitted through supply chains.
Additive manufacturing feedstock development is converging with copper powder atomization and laser powder bed fusion process control, enabling conformal cooling channel geometries in injection mold tooling. Mold and die shops in Germany and Japan adopt these capabilities for shortened lead time and improved thermal uniformity. The technology is converging with traditional wrought product lines by creating hybrid manufacturing workflows where printed features integrate with machined copper bases.
EU CSRD disclosure requirements and the EU Green Deal taxonomy now classify copper smelter emissions intensity as a material sustainability metric, forcing asset-level carbon accounting integration into annual reporting. Financial institutions incorporate these disclosures into transition finance eligibility screening. European fabricators and OEMs respond by sourcing exclusively from smelters with verified Scope 1 and 2 emissions below sector thresholds, redirecting procurement volumes toward certified low-carbon cathode.
Direct long-term contracting between automotive OEMs and copper semis producers is displacing traditional merchant market and distributor intermediation for battery and motor material specifications. Tier 1 suppliers in South Korea and Germany now negotiate multi-year offtake agreements with fixed alloy chemistry and mechanical property bands. This pattern concentrates most visibly in electric vehicle platform supply chains where traceability and batch consistency requirements exceed standard commercial grade tolerances.
Copper and Copper Alloy Market Segmentation
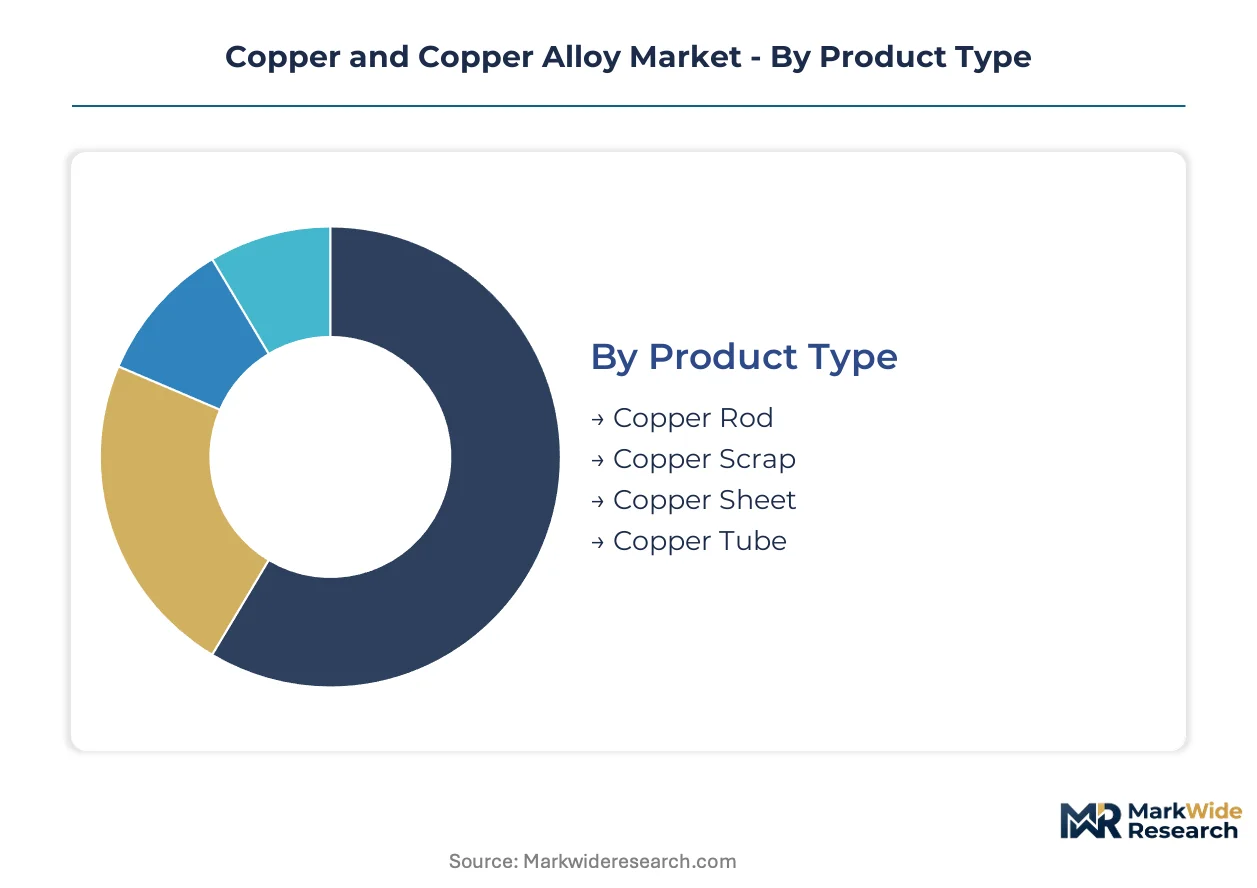
Copper and copper alloy procurement decisions pivot on conductivity specifications, forming constraints, and installation method compatibility. Segmentation reveals how volume commodities and precision grades occupy divergent margin structures within integrated supply chains.
Product Type:
Electrical grade material commands premium spreads over standard commercial forms, while rod and tube categories absorb the bulk of tonnage flows into construction and automotive channels.
- Copper Rod:Continuous cast and rolled rod serves as the primary feedstock for wire drawing operations, with 8mm and 12.5mm diameters dominating magnet wire and power cable production. Demand concentrates in Vietnamese and Indonesian fabrication hubs where new extrusion and drawing capacity supports electronics and automotive supply chain diversification.
- Copper Tube:Seamless tube in ASTM B88 and EN 1057 specifications anchors plumbing and HVAC contractor specifications, with press-fit joining systems now displacing traditional soldering in European and North American installation practices. Aluminum microchannel substitution in residential air conditioning compresses copper tonnage in volume heat exchanger segments.
- Copper Sheet:Cold-rolled sheet in architectural and electromagnetic shielding grades captures margin pools through surface finish control and gauge precision.
- Copper Scrap:No. 1 bare bright and No. 2 copper categories constitute critical secondary feedstock for smelters and direct-melt fabricators facing concentrate supply volatility.
Today's leader: Copper Rod. Tomorrow's challenger: Copper Tube.
Application:
Grid interconnection requirements and vehicle electrification are reallocating volume across traditional building systems and emerging energy infrastructure.
- Electronics:High-purity cathode transforms into foil, strip, and precision wire for printed circuit boards, semiconductor lead frames, and connector systems. Specifications from South Korean and German Tier 1 suppliers now mandate fixed alloy chemistry bands and batch traceability exceeding standard commercial tolerances.
- Automotive:Traction motor windings and battery interconnects pull dedicated alloy grades certified for thermal cycling endurance, with direct long-term contracting between OEMs and semis producers displacing traditional merchant market intermediation.
- Construction:Building wire, roofing, and architectural cladding applications specify commercial and architectural grades with surface oxidation control.
- Plumbing:Potable water tube in specific temper conditions dominates residential and commercial installation specifications.
Electronics holds the steepest expansion trajectory. Automotive is gaining share fastest.
End User:
Procurement authority concentrates with entities capable of verifying carbon intensity and alloy provenance across multi-tier supply chains.
- Manufacturers:Automotive OEMs and electronics assemblers negotiate multi-year offtake agreements with fixed mechanical property bands, prioritizing smelters with verified Scope 1 and 2 emissions below sector thresholds.
- Contractors:Plumbing and HVAC installation firms specify press-fit tube systems for reliability in commercial building projects.
- Distributors:Merchant stockists buffer volume commodities against concentrate price volatility for smaller fabrication accounts.
- Retailers:Hardware and building supply channels move standard commercial forms to maintenance and repair end markets.
Manufacturers dictate specification premiums. Distributors defend volume throughput.
Grade:
Conductivity certification and surface quality separate electrical and architectural premiums from commodity commercial material.
- Electrical:Cathode exceeding 101% IACS conductivity underpins grid modernization, renewable energy interconnection, and EV motor winding specifications. EU CBAM implementation rewards verified low-carbon production, creating tiered market access for certified smelters.
- Commercial:Standard conductivity material serves general fabrication with less stringent thermal or electrical performance requirements.
- Architectural:Surface finish, patina control, and color stability specifications command premiums in building envelope and interior applications.
- Others:Specialized alloy grades including beryllium-copper and nickel-silver serve wear-resistant and corrosion-critical niches.
Electrical grade captures value concentration. Architectural grade is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean mine supply disruptions transmit more acutely to German smelter economics than to Vietnamese fabrication hubs, illustrating how geographic concentration in extraction contrasts with dispersion in manufacturing.
China
Dual carbon targets and MEE sulfur dioxide emissions caps are shuttering legacy smelters in Hunan and Jiangxi provinces. The national environmental ministry enforces wastewater discharge rules that redirect investment toward hydrometallurgical refining circuits. Yangtze River Delta clusters around Shanghai anchor new low-carbon cathode capacity serving domestic EV battery interconnect demand.
United States
Grid modernization under FERC interconnection standards and IRA clean energy tax credits pull electrical grade copper into utility-scale solar and storage projects. EPA and OSHA jointly regulate airborne metal exposure in Midwest fabrication facilities, influencing dust collection capital decisions. Arizona and Utah smelter complexes face concentrate feedstock pressure from Chilean supply volatility.
Germany
EU CBAM implementation rewards verified low-carbon cathode production, creating tiered market access for Hamburg and Hamburg-adjacent refiners. REACH and RoHS frameworks redirect alloy procurement toward lead-free variants for automotive and electronics OEMs. North Rhine-Westphalia rolling mills supply precision strip to Stuttgart automotive clusters under multi-year offtake agreements.
Vietnam
Electronics and automotive supply chain diversification concentrates demand in northern industrial provinces around Hanoi and Hai Phong. New extrusion and drawing capacity supports South Korean Tier 1 supplier specifications for fixed alloy chemistry bands. The government prioritizes fabrication hub status through special economic zone incentives targeting copper semis investment.
Japan
Semiconductor lead frame and thermal management applications sustain high-performance alloy demand through METI-supported domestic manufacturing resilience programs. JIS standards govern precision strip and foil specifications for Osaka-Kobe electronics clusters. Kanto region fabricators negotiate direct long-term contracting with automotive OEMs for battery interconnect material.
Copper and Copper Alloy Market Vendor Landscape
Top-tier vendors anchor low-carbon cathode and certified alloy segments, while mid-scale processors compete on geographic proximity to Southeast Asian fabrication hubs. The vendor base stratifies across integrated miners with captive smelting, European refiners with emissions certification, and Asian fabricators with OEM-direct contracting capabilities. Strategic archetypes include concentrate-integrated giants, carbon-certified European specialists, and precision alloy developers for semiconductor thermal management. Competitive moves concentrate on smelter modernization for emissions compliance and direct OEM offtake agreements displacing merchant market intermediation.
Within the concentrate-integrated tier, Jiangxi Copper Corporation and Mitsubishi Materials Corporation exemplify mine-to-semis control structures. Aurubis AG occupies a position representing European low-carbon refining certification advantages under EU CBAM frameworks. These three anchors illustrate how geographic regulatory exposure—Chinese environmental compliance, Japanese precision manufacturing standards, and European carbon border adjustments—shapes competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| poongsan corporation |
| Aurubis AG |
| AMPCO Metal |
| Amari Copper Metals |
| KME Group S.p.A. |
| Jiangxi Copper Corporation |
| Copper Alloys Ltd. |
| Wieland |
| Others |
Supply Flow & Price Mechanics
Low-carbon cathode certification premiums versus standard commercial grades create a bifurcation that manifests in both spot-market discounts for unverified material and supply chain segregation between EU CBAM-compliant smelters and legacy processors. This tier divergence concentrates procurement authority with automotive OEMs and data center operators capable of verifying Scope 1 and 2 emissions across multi-tier supplier networks, while marginalizing merchant-market distributors in high-specification segments.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for copper rod and drawn wire as new extrusion capacity absorbs regional electronics demand. Three-tier pricing structure across premium low-carbon cathode, standard electrolytic, and secondary scrap-fed material reflects EU CBAM compliance premiums and concentrate supply volatility. Cost compression in standard commercial grades intensifies because Chilean mine disruptions transmit directly to smelter feedstock costs. Contract manufacturers in Southeast Asia exhibit highest price sensitivity, while German automotive OEMs prioritize certified low-carbon supply over unit cost.
Supply Chain Analysis
Copper concentrate supply rests on Chilean and Peruvian mine output, Chinese smelting capacity, and Indonesian fabrication hubs. Raw material flows draw from sulfide concentrates, solvent extraction-electrowon cathode, and No. 1 bare bright scrap streams. Single-source vulnerability concentrates in Andean mine supply exposed to labor stoppages and water scarcity. Distribution runs through direct long-term offtake agreements between OEMs and semis producers, displacing traditional merchant market intermediation in EV and data center segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on carbon-accounted production premiums and hydrometallurgical cost advantages that separate compliant smelters from legacy processors facing MEE emissions retrofit burdens.
For Market Incumbents: Anchor low-carbon cathode positions through EU CBAM certification investment and direct OEM offtake agreements that lock in premium spreads over merchant-market pricing. Aluminum microchannel substitution in residential HVAC threatens copper tube volume segments, requiring backward integration into precision alloy development for semiconductor thermal management applications. For New Entrants and Emerging Players: Additive manufacturing feedstock development offers a technology-first wedge into conformal cooling applications for injection mold tooling and data center cold plates. White-space concentration appears in blockchain-linked alloy certification platforms serving automotive traceability requirements, with entry through subscription-based verification services rather than capital-intensive smelting capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where hydrometallurgical expertise gaps constrain smelter modernization timelines, particularly for atmospheric and pressure leaching circuit upgrades. Long-term viability favors integrated mine-to-semis operators with verified emissions certification and captive concentrate supply. The signal to watch is EU CBAM tariff implementation pace and corresponding procurement shifts by German automotive clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Smelter Modernization for MEE Compliance | Chinese environmental ministry enforcement redirects investment toward hydrometallurgical circuits in Yangtze River Delta clusters. |
| Direct OEM Offtake Agreements | South Korean and German Tier 1 suppliers negotiate multi-year contracts with fixed alloy chemistry bands for EV platforms. |
| Blockchain Traceability Platform Launch | Subscription certification services enable premium pricing for conflict-free and carbon-accounted material in automotive procurement. |
| Backward Integration into Concentrate Supply | Jiangxi Copper and similar integrated operators secure feedstock stability against Chilean supply volatility. |
| Precision Alloy Development for Semiconductors | Mitsubishi Materials and Japanese competitors sustain margins through METI-supported domestic manufacturing resilience programs. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down smelter and fabrication capacity tracking forms the analytical core of this study. Primary interviews with copper semis procurement managers at automotive OEMs, smelter operations directors, electronics Tier 1 supplier quality engineers, and HVAC contractor purchasing agents combined with secondary validation from customs trade data, SEC 10-K filings, Chinese MEE emissions disclosures, and EU CBAM implementation documents. Triangulation across these sources reconciles apparent demand from wire drawing and extrusion operations against verified cathode production and concentrate import flows.
Input-output matrices map copper concentrate availability through smelter output to fabricated semis demand across rod, tube, sheet, and precision strip categories. Segmentation dimensions modeled include product form, conductivity grade tier, end-use application, and regional production hub. CAGRs derive from capacity utilization trends and substitution elasticity estimates. Industry-specific forecast inputs incorporate EV motor winding content per vehicle and data center liquid cooling adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chilean mine supply stability and EU carbon border adjustment implementation pace. Forecasts reflect documented assumptions regarding concentrate supply continuity, emissions certification adoption rates, and aluminum substitution limits in thermal management applications. A small set of named triggers—Andean labor stoppages, MEE enforcement intensity, CBAM tariff calibration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Crude Steel Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Aluminum Scrap Recycling Market
Metals
Metallurgical Coal Market
Metals
North America and Europe Metal Powder Market
Metals
Global Brazing Consumable Market
Metals
Industrial Silver Market
Metals
Gold Smelting Market
Metals
Aluminum Casting Market
Metals
Titanium Sponge Market
Metals
Industrial Metal Strips Market
Metals
Welding Materials Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Metal Alloys Market
Metals
Global Copper Cathode Market
Metals
Copper Azoles Market