
 Global Thin Film Coatings Market | 2026-2036
Global Thin Film Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin Film Coatings Market Intelligence
The European Union's REACH regulation is hardening the compliance requirements for chemical precursors used in thin film deposition processes, increasing R&D costs. Applied Materials leverages its significant scale in semiconductor equipment to engineer integrated deposition solutions compliant with these stringent standards. Oerlikon Balzers specializes in advanced surface solutions, navigating complex material regulations for clients in the automotive and aerospace industries. ULVAC dominates specific vacuum technology segments essential for high-volume electronics manufacturing in Japan and South Korea.
Thin film coatings are layers of material ranging from nanometers to several micrometers in thickness, applied to a substrate to alter its surface properties. These coatings modify optical, electrical, or mechanical characteristics, providing functions like anti-reflection, conductivity, or wear resistance. Physical Vapor Deposition (PVD) and Chemical Vapor Deposition (CVD) methods constitute the largest product type segments, driven by their versatility. Within applications, semiconductor devices and optical components command the highest value due to stringent performance and purity requirements.
Market access is governed by frameworks including the US Environmental Protection Agency (EPA) rules on precursor chemicals and China's mandatory GB standards for electronics. These regulations dictate acceptable material compositions, waste disposal from processes like electroplating, and facility-level worker safety protocols. Consequently, equipment manufacturers and coating providers must continually balance investments in next-generation deposition technologies, such as Atomic Layer Deposition, against tightening environmental compliance costs.
Market Dynamics
The central tension within the thin film coatings market stems from the escalating performance requirements of next-generation electronics colliding with increasingly stringent global regulations on chemical precursors, directly impacting material science innovation and supply chain architecture.
Growth Catalysts
- Semiconductor Advancement:The fabrication of 3D NAND memory and gate-all-around (GAA) transistors requires exceptionally precise and uniform thin films, driving demand for advanced deposition technologies like Atomic Layer Deposition (ALD).
- Renewable Energy Expansion:Government incentives for solar power in the United States and Europe spur demand for anti-reflective and conductive coatings that enhance the efficiency and durability of photovoltaic cells.
- Automotive Electronics:The proliferation of sensors, displays, and control units in modern vehicles creates a substantial volume market for coatings that provide electromagnetic shielding, wear resistance, and optical filtering.
Market Restraints
- Precursor Material Costs:The price and availability of high-purity metals and organometallic compounds, such as hafnium and cobalt precursors, are volatile and subject to geopolitical supply constraints, impacting production costs.
- Regulatory Friction:The European Union's REACH regulation imposes extensive documentation and testing requirements for new chemical substances, creating significant compliance hurdles and slowing the introduction of novel coating materials.
- Technical Complexity:Achieving defect-free coatings on large-area substrates or complex three-dimensional topographies remains a significant technical challenge, limiting yield and increasing manufacturing costs for certain high-value applications.
Strategic Opportunities
- Biomedical Applications:There is an expanding opportunity for biocompatible, anti-microbial, and drug-eluting thin film coatings for medical implants, surgical tools, and diagnostic devices, governed by regulators like the US FDA.
- Flexible Electronics:The emergence of foldable displays and wearable sensors creates a new market for durable, transparent, and conductive coatings that can withstand repeated mechanical stress without performance degradation.
- Sustainable Packaging:Developing advanced barrier coatings for food and beverage packaging offers a functional alternative to multi-layer plastics, aligning with corporate sustainability goals and regulations targeting single-use plastics.
Industry Challenges
- Process Engineering Talent:A persistent shortage of skilled engineers and technicians with expertise in operating, maintaining, and optimizing complex PVD, CVD, and ALD equipment constrains production scalability and process innovation.
- Capital Investment Cycles:The high cost of next-generation deposition equipment and the lengthy qualification timelines required by semiconductor and aerospace customers create significant financial barriers to entry and technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin Film Coatings Market |
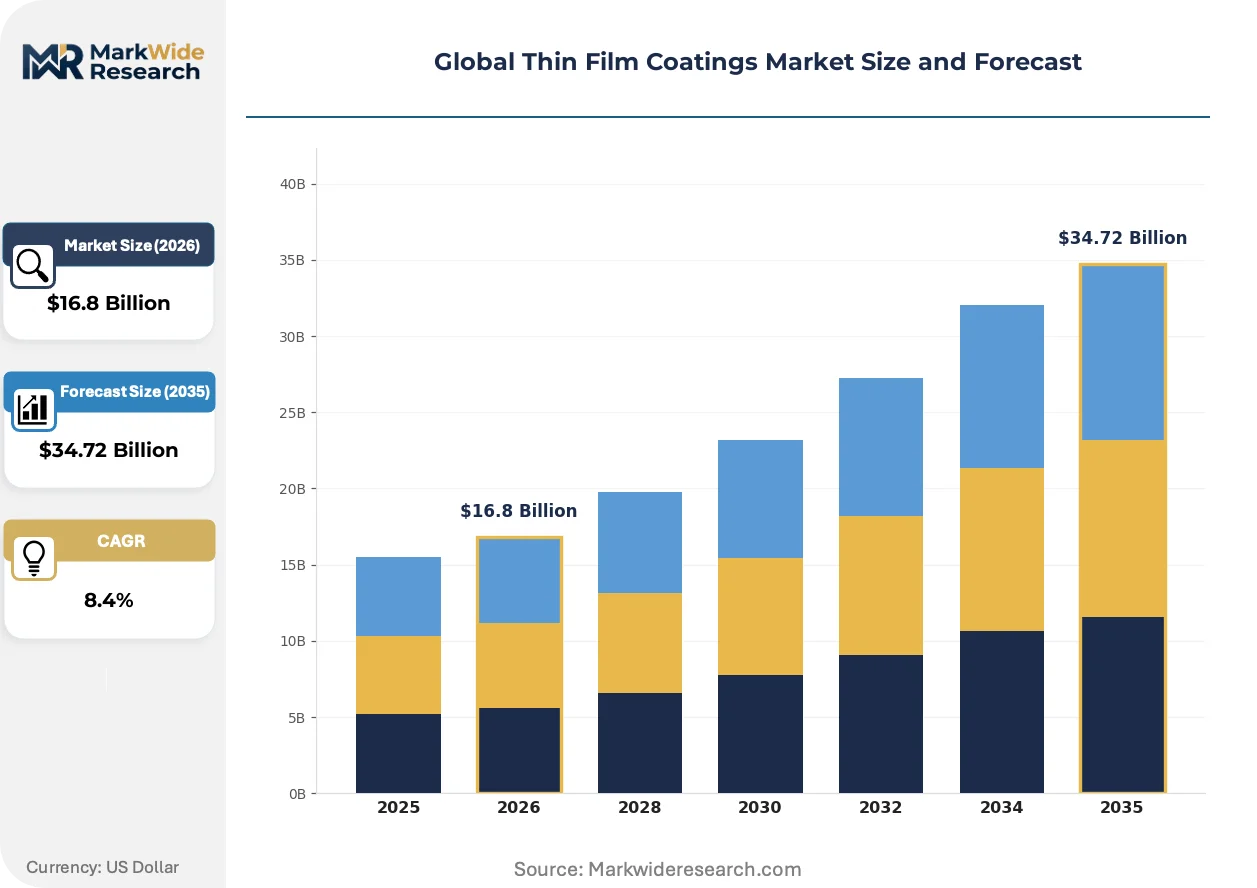
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Electroplating, Sol-Gel Coating Technology: Magnetron Sputtering, Thermal Evaporation, Plasma Enhanced CVD, Spin Coating, Electron Beam Evaporation Application: Optical Components, Semiconductor Devices, Solar Panels, Aerospace Equipment, Decorative Surfaces End User Industry: Electronics Manufacturing, Photovoltaic Production, Defense Contractors, Jewelry Fabrication, Scientific Instruments |
| Companies Covered | Bühler Group, DuPont de Nemours, Inc., Applied Materials, Hitachi, ZEISS Group, Oerlikon Balzers, ULVAC, Denton Vacuum, Veeco Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin Film Coatings Market Strategic Shifts & Innovations
Material science innovation is accelerating to meet dual mandates for higher device performance and improved environmental sustainability. This dynamic forces equipment makers and material suppliers to re-engineer process chemistries and deposition techniques to comply with new global standards.
Atomic Layer Deposition (ALD) enables the precise, conformal coating of surfaces with angstrom-level thickness control. Semiconductor manufacturers are adopting ALD for critical layers in advanced logic and memory devices below the 10nm node. This deposition technology is converging with sophisticated in-situ metrology, allowing for real-time process monitoring and control that dramatically improves device yield and performance consistency.
The European Union’s RoHS directive, which restricts hazardous substances in electrical and electronic equipment, continues to shape material selection. The directive's periodic reviews force the phasing out of certain materials used in older coating formulations, such as specific lead or cadmium compounds. Optical component and consumer electronics manufacturers are most affected, investing in R&D to qualify compliant, lead-free coating alternatives.
A shift from single-sourcing to multi-supplier qualification for critical raw materials is altering supply chain strategies. To ensure production continuity, high-volume electronics manufacturers now certify materials from several approved vendors for a single process step, reducing dependency on any one supplier. This risk mitigation practice is most visible in the advanced foundry ecosystems of Taiwan and South Korea.
Global Thin Film Coatings Market Segmentation
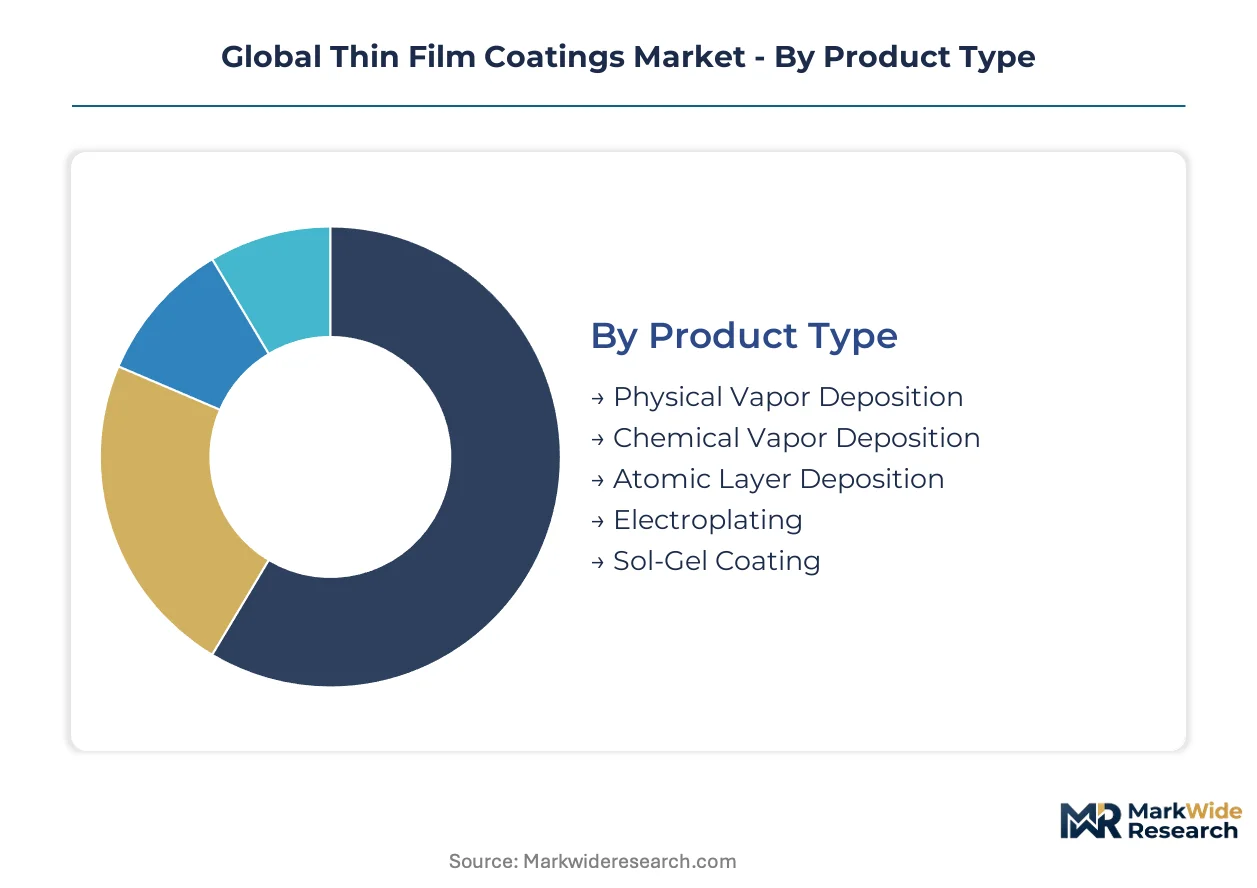
Understanding the varied segments within the thin film coatings market clarifies where technological investments are concentrated and which areas offer the highest growth potential. Each segment presents distinct material science challenges and requires specialized deposition equipment, influencing supplier strategies across the value chain. This detailed analysis delineates market dynamics by product type, underlying technology, specific application, and the diverse end-user industries.
Product Type:
The capital outlay required for thin film deposition equipment varies significantly across product types, with advanced methods demanding substantial upfront investment for precise control and high throughput.
- Physical Vapor Deposition:PVD involves physical processes like sputtering or evaporation to deposit thin films in a vacuum. This method offers excellent adhesion and material versatility, widely used for wear-resistant coatings on tools and decorative finishes on consumer goods.
- Chemical Vapor Deposition:CVD utilizes chemical reactions between gaseous precursors near the substrate surface to form a solid film. It provides conformal coating on complex geometries and is critical for semiconductor device fabrication in Taiwan's advanced foundries.
- Atomic Layer Deposition:ALD uses sequential, self-limiting gas-phase reactions to deposit ultrathin films with atomic-level precision. Semiconductor manufacturers in South Korea employ ALD for critical gate dielectrics and high-k materials in advanced logic chips.
- Electroplating:This electrochemical process deposits a metallic coating onto a conductive substrate from an electrolyte solution. Electroplating provides corrosion resistance and aesthetic appeal for automotive components and jewelry fabrication.
- Sol-Gel Coating:Sol-gel is a wet-chemical technique that produces ceramic or glass-like thin films from a colloidal suspension. Optical component manufacturers use sol-gel for anti-reflective and protective layers on lenses.
Physical Vapor Deposition absorbs the bulk of installed capacity; Atomic Layer Deposition is expanding most quickly.
Technology:
The efficiency and cost-effectiveness of deposition technologies drive their adoption across various industries, with some methods offering superior material utilization and process control.
- Magnetron Sputtering:This PVD technique uses a magnetic field to confine plasma near the target, enhancing deposition rates and film uniformity. Magnetron sputtering is a workhorse for applying conductive and optical coatings in electronics manufacturing and for decorative applications.
- Plasma Enhanced CVD:PECVD uses plasma to energize reactant gases, allowing deposition at lower temperatures than conventional CVD. Semiconductor fabrication facilities in Japan leverage PECVD for depositing dielectric and passivation layers without damaging temperature-sensitive substrates.
- Thermal Evaporation:Thermal evaporation heats a source material until it vaporizes and condenses onto a substrate in a vacuum. It is a cost-effective method for depositing metallic films for mirrors and basic optical filters.
- Spin Coating:Spin coating applies a liquid precursor onto a substrate which is then spun at high speed to create a uniform thin film. This technique is common in research and development for creating photoresist layers in microfabrication.
- Electron Beam Evaporation:This PVD method uses an electron beam to heat and vaporize source material, offering precise control over deposition rates and film thickness. Optical component producers utilize electron beam evaporation for multi-layer dielectric stacks.
The versatility of Magnetron Sputtering drives significant volume; Plasma Enhanced CVD offers specialized performance.
Application:
The stringency of performance requirements dictates the choice of thin film coatings, with high-value applications demanding superior purity, uniformity, and durability.
- Semiconductor Devices:Thin films are fundamental to semiconductor device architecture, forming transistors, interconnects, and insulating layers. The fabrication of advanced logic and memory chips in Taiwan requires ultra-pure, defect-free coatings for optimal electrical performance.
- Optical Components:Coatings on optical components modify light transmission, reflection, and absorption characteristics. Anti-reflective coatings on camera lenses and filters for scientific instruments enhance device functionality and clarity.
- Solar Panels:Thin films enhance the efficiency and longevity of photovoltaic cells by reducing reflection and protecting against environmental degradation. Government incentives in the United States and Europe spur demand for advanced coatings in solar panel production.
- Aerospace Equipment:Coatings provide critical functions such as wear resistance, thermal insulation, and corrosion protection for aircraft components. Defense contractors apply specialized films to turbine blades and structural parts for enhanced durability.
- Decorative Surfaces:Thin films are applied to consumer products to provide aesthetic appeal, scratch resistance, and tarnish protection. Jewelry fabrication and automotive interior trim utilize decorative coatings for enhanced visual quality.
Performance demands in Semiconductor Devices command premium pricing; Solar Panels represent a growing value segment.
End User Industry:
Different end-user industries drive demand for thin film coatings based on their unique product requirements, production scales, and regulatory environments.
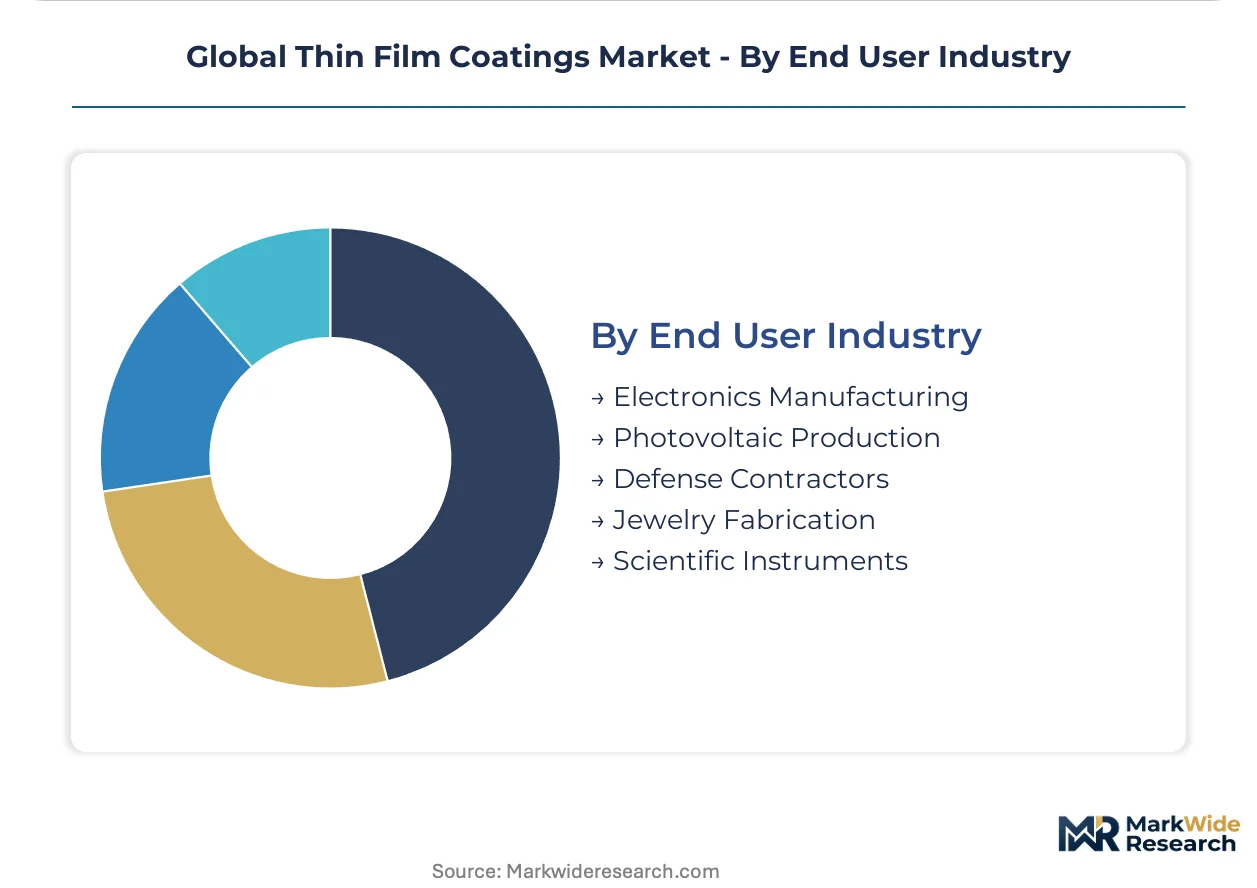
- Electronics Manufacturing:This industry requires thin films for integrated circuits, displays, and sensors, driven by the continuous miniaturization and performance enhancement of electronic devices. Consumer electronics manufacturers in Japan and South Korea are major consumers of advanced deposition technologies.
- Photovoltaic Production:The solar energy sector uses thin films to improve the efficiency, durability, and cost-effectiveness of solar cells and modules. Manufacturers are investing in anti-reflective and conductive coatings to meet global renewable energy targets.
- Defense Contractors:Thin films provide critical functionalities like stealth, wear resistance, and thermal management for military aircraft, missiles, and other defense systems. Regulators like the US EPA influence material selection for specialized defense applications.
- Jewelry Fabrication:Coatings enhance the aesthetic appeal, durability, and hypoallergenic properties of jewelry. Decorative films offer alternatives to traditional plating methods for watches and fashion accessories.
- Scientific Instruments:High-precision optical and protective coatings are essential for analytical equipment, microscopes, and medical devices. Manufacturers of diagnostic tools require biocompatible and chemically resistant films.
The regulatory landscape heavily influences demand within Electronics Manufacturing; Photovoltaic Production seeks efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's advanced foundry ecosystem drives significant concentration in the thin film coatings market. This hub benefits from focused government support and attracts high-purity deposition materials. Similar targeted incentives in other regions bolster local production capabilities.
Taiwan
Demand for thin film coatings in Taiwan is fueled by the relentless advancement of semiconductor devices, particularly in advanced logic and memory chips. Taiwan's government actively promotes semiconductor industry growth through targeted investment schemes and infrastructure development. The Hsinchu Science Park concentrates high-purity material suppliers and advanced foundries, fostering innovation in deposition technologies.
United States
The United States market sees strong demand from semiconductor manufacturing, renewable energy expansion, and the aerospace sector. The US Environmental Protection Agency (EPA) rules on precursor chemicals dictate acceptable material compositions and waste disposal protocols. Silicon Valley in California remains a central hub for advanced deposition technology research and development, attracting significant capital investment.
Germany
Germany's market for thin film coatings is propelled by its robust automotive electronics industry, precision industrial machinery, and optical components sector. The European Union's REACH regulation directly influences material selection and global supply chain strategies for German manufacturers. Bavaria's industrial clusters specialize in precision optics and advanced automotive component coatings, driving regional technological leadership.
South Korea
South Korea exhibits substantial demand for thin film coatings due to its high-volume electronics manufacturing, advanced logic chips, and memory device production. South Korea's Ministry of Trade, Industry and Energy supports domestic material and equipment development through various initiatives. Gyeonggi Province hosts major electronics manufacturers and Atomic Layer Deposition technology developers, forming a critical innovation nexus.
Japan
Japan's market is characterized by demand from high-volume electronics, scientific instruments, and precision optical components. Japan's Ministry of Economy, Trade and Industry (METI) promotes advanced materials research and development for domestic industries. Tokyo's metropolitan area contains numerous vacuum technology specialists and precision equipment manufacturers, supporting complex deposition processes.
Global Thin Film Coatings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the thin film coatings market. This market exhibits a tiered structure, encompassing large-scale equipment manufacturers, specialized material suppliers, and niche coating service providers. Competitive archetypes include integrated solution providers and those concentrating on specific deposition technologies like Atomic Layer Deposition. Strategic partnerships for technology co-development and targeted capacity expansion are dominant competitive moves.
Integrated solution providers, like Applied Materials, occupy a significant position in the market by offering comprehensive deposition systems. Oerlikon Balzers exemplifies advanced surface solutions, anchoring expertise in navigating complex material regulations for diverse industrial clients. ULVAC, a Japan-based company, sits within the vacuum technology segment, essential for high-volume electronics manufacturing in Asia. These players, through their archetypal roles, shape the industry's technological trajectory and compliance standards.
| Leading Market Players |
|---|
| Bühler Group |
| DuPont de Nemours, Inc. |
| Applied Materials |
| Hitachi |
| ZEISS Group |
| Oerlikon Balzers |
| ULVAC |
| Denton Vacuum |
| Veeco Instruments |
| Others |
Cost & Logistics Intelligence
Atomic Layer Deposition technology reshapes cost economics by demanding specialized equipment and high-purity precursors, simultaneously concentrating supply chains around key material providers and advanced foundries.
Pricing Analysis
Lead-time-driven pricing structures often prevail for critical thin film coatings, with premium prices commanded for rapid turnaround and specialized formulations. The dominant pricing model is contract-based long-term offtake, especially for semiconductor and aerospace applications. Price differentiation stems from the purity grade of deposition materials and specific regulatory certifications like REACH compliance. Pricing pressure stems from the high capital investment required for next-generation deposition equipment. Decorative surfaces represent the most price-sensitive segment, while semiconductor device manufacturers exhibit the least sensitivity due to stringent performance requirements.
Supply Chain Analysis
Domestic-content mandates for advanced electronics are reshaping sourcing strategies for thin film coating materials, encouraging localized production. Geographic supply concentration centers on Taiwan, South Korea, and Japan, which host major electronics manufacturing hubs. Raw material dependencies include high-purity hafnium and cobalt precursors. Geopolitical supply constraints represent a structural risk due to limited global sources for these specialized materials. Distribution runs through direct channels to high-volume electronics manufacturers and specialized foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thin film coatings market is in a technology-transition phase, with Atomic Layer Deposition (ALD) increasingly displacing older Physical Vapor Deposition (PVD) methods for critical applications.
For Market Incumbents: Anchor R&D investments in next-generation deposition technologies like ALD to counter the threat of specialized pure-play competitors. Pursue strategic partnerships with high-purity material suppliers to secure access to critical precursors. This fortifies supply chain resilience against geopolitical disruptions and tightens control over material quality for advanced semiconductor applications.
For New Entrants and Emerging Players: A price-point gap exists between high-performance, premium thin film coatings and more commoditized economy-tier options, creating market entry opportunities. Target the burgeoning biomedical applications market or flexible electronics with specialized, high-durability coatings. A go-to-market angle focused on rapid prototyping and custom formulation services can penetrate niche, high-value segments.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material suppliers given the escalating demand for high-purity precursors in advanced semiconductor manufacturing. Focus on companies with proprietary ALD or advanced CVD chemistries and strong intellectual property portfolios. A signal to watch is increased capital expenditure announcements from major semiconductor foundries, indicating sustained demand for cutting-edge deposition solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in ALD Technology Development | Applied Materials strengthens its position in advanced logic and memory chip fabrication. |
| Secure High-Purity Material Contracts | Oerlikon Balzers ensures consistent supply for its automotive and aerospace clients. |
| Expand Biomedical Coating Portfolio | New entrants capture growth in biocompatible and drug-eluting device applications. |
| Formulate Sustainable Packaging Solutions | DuPont de Nemours addresses corporate sustainability goals and single-use plastic regulations. |
| Acquire Vacuum Technology Specialists | ULVAC enhances its core capabilities for high-volume electronics manufacturing. |
Research Approach
Multi-period observation of deposition technology adoption rates and regulatory compliance costs anchored the trend analysis, supplemented by interviews with industry experts. Primary interviews included R&D directors, procurement leads from electronics manufacturers, and regulatory affairs specialists. Secondary validation drew from academic literature, patent databases, and national economic reports from Japan and South Korea. Bottom-up data aggregation and top-down market sizing provided robust triangulation.
An input-output matrix framework integrated market dynamics, segment-specific growth rates, and technology adoption curves across the analysis window. Segmentation dimensions modeled included product type, underlying technology, specific application, and end-user industry. Compound annual growth rates were derived from historical data and projected forward based on technological roadmaps. Forecast inputs included semiconductor capital expenditure trends and renewable energy installation targets.
Inputs from equipment manufacturers and material suppliers were available through the study window; gaps in emerging application data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and sustained investment in advanced electronics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Thin Film Materials Market
Functional Materials
Functional Acids Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Functional Composites Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functionalized Nanocomposites Market