
 Functional Composites Market | 2026-2036
Functional Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Composites Market Analysis
Aftermarket service revenue for composite component repair and refurbishment is tilting toward specialized service networks as OEMs seek to capture lifetime value. SGL Carbon leverages its carbon fiber precursor capabilities to anchor premium aerospace supply relationships. Hexcel Corporation sustains manufacturing scale across multiple fiber formats and resin systems. Teijin Limited specializes in aramid fiber composites for ballistic and industrial applications, differentiating through material science depth.
Functional composites are engineered materials combining two or more constituent phases with distinct physical or chemical properties, where carbon fiber reinforced polymers achieve specific strength-to-weight ratios exceeding 200 MPa/(g/cm³) and tailored thermal expansion coefficients for precision applications. Thermosetting composites dominate current aerospace structural programs due to established qualification databases and processing familiarity. Thermoplastic composites represent the fastest-expanding product category as automated fiber placement and out-of-autoclave manufacturing reduce cycle times. Bio-composites remain nascent but attract sustainability-driven procurement from European automotive OEMs seeking cradle-to-cradle material options.
REACH registration requirements in Europe govern chemical substances in resin matrices, while FAA airworthiness directives mandate damage tolerance and fatigue testing protocols for flight-critical composite structures. The EPA oversees volatile organic compound emissions from composite manufacturing processes in the United States, influencing facility location and capital equipment decisions. Stakeholders must monitor evolving MDR-equivalent standards for composite medical devices and anticipate how extended producer responsibility frameworks will reshape end-of-life material recovery economics.
Market Dynamics
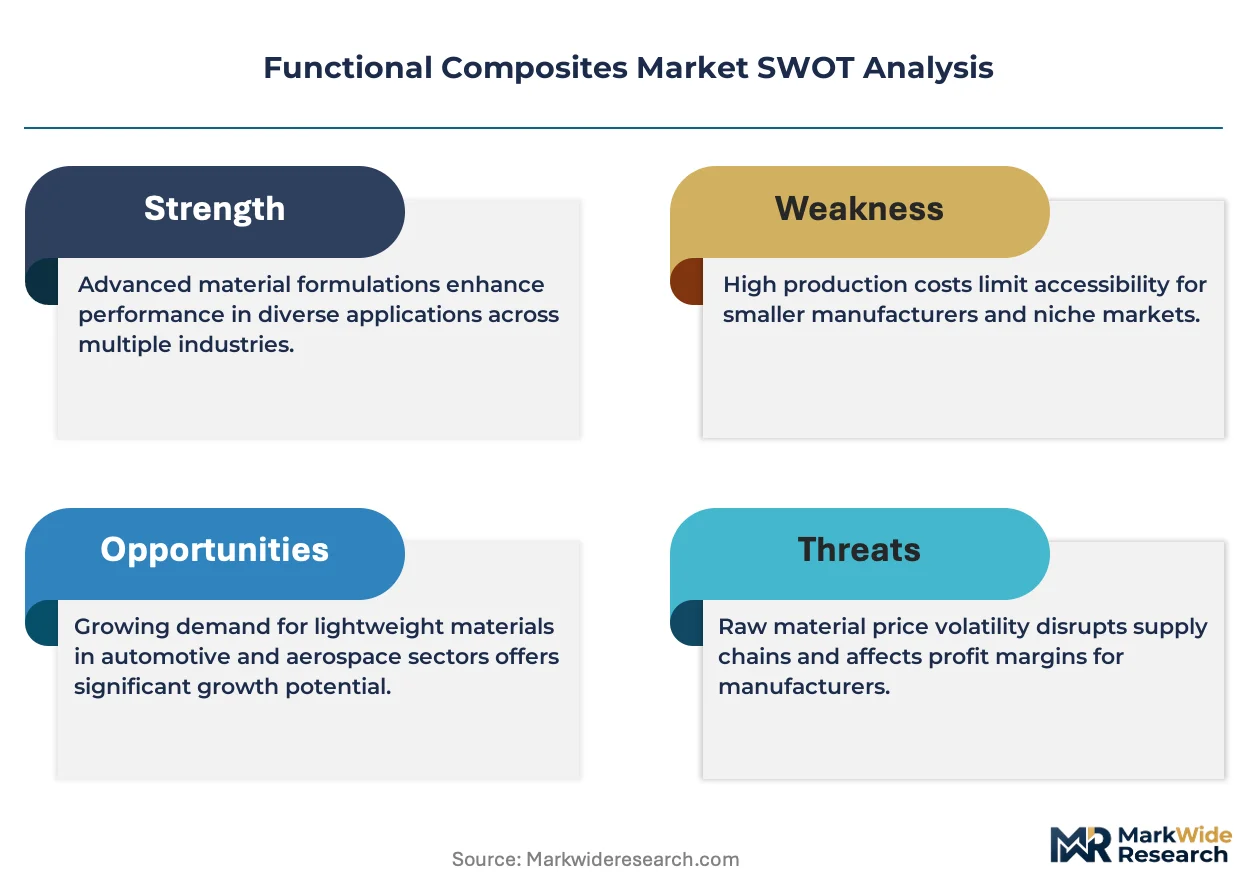
Thermoplastic composites are collapsing traditional thermoset dominance in aerospace primary structures as automated fiber placement and out-of-autoclave processing compress cycle times from hours to minutes.
Growth Catalysts
- REACH Registration Requirements:European chemical compliance frameworks are accelerating formaldehyde-free resin system development across automotive supplier networks.
- Bio-Composite Procurement Mandates:Stuttgart and Munich automotive clusters are driving cradle-to-cradle material specifications for interior structural components.
- FAA Airworthiness Directives:Damage tolerance testing protocols are standardizing qualification databases for flight-critical thermoplastic applications.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs swing with petrochemical feedstock markets, squeezing margin predictability for tier-two converters.
- German Supplier Concentration:Stuttgart-Munich corridor dominance creates single-source vulnerability for European aerospace qualification pathways.
- Thermoset Qualification Inertia:Established certification databases lock incumbent materials into long-cycle defense programs despite performance inferiority.
Strategic Opportunities
- Indian Defense Modernization:Indigenous fighter programs and naval vessel construction are opening qualification pathways for foreign composite suppliers under offset agreements.
- Automated Fiber Placement Convergence:Robotics integration with in-situ consolidation is collapsing labor content in wing box manufacturing.
- Extended Producer Responsibility:EU end-of-life recovery mandates are creating closed-loop material economics for carbon fiber recyclers.
Industry Challenges
- Damage Tolerance Engineering Talent:FAA certification expertise concentrates among retiring Boeing and Lockheed Martin specialists, constraining new program staffing.
- Autoclave Capital Intensity:Out-of-autoclave process validation requires parallel equipment investment during technology transition periods.
- Multi-Material Bonding Complexity:Dissimilar thermal expansion coefficients between thermoplastic composites and metallic substructures demand novel fastening system development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Composites Market |
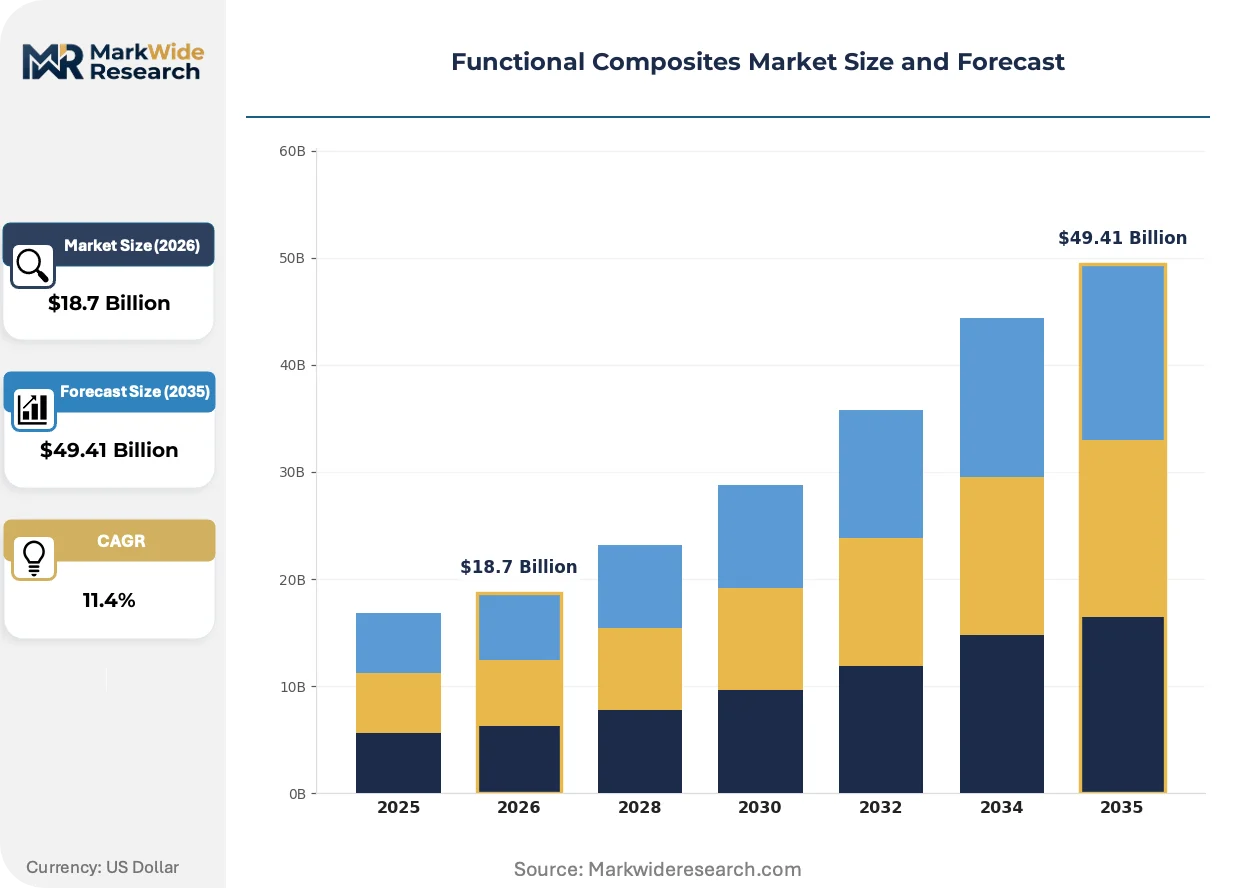
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Composites, Thermoplastic Composites, Hybrid Composites, Bio-composites End User Industry: Aerospace, Automotive OEMs, Construction, Electronics Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber Application: Structural Components, Thermal Insulation, Electrical Insulation, Surface Coatings |
| Companies Covered | SGL Carbon, Albany Engineered Composites, Toray Industries, Solvay, Umoe Advanced Composites, Hexcel Corporation, Mitsubishi Chemical Group, Toray Advanced Composites, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Composites Market Emerging Trajectories
Processing automation and regulatory chemistry restrictions are simultaneously compressing manufacturing economics and rewriting material formulation requirements across aerospace and automotive supply chains.
Continuous fiber-reinforced thermoplastic tapes with unidirectional carbon fiber architectures are collapsing autoclave-dependent processing for wing skins and fuselage sections. Boeing and Airbus tier-one suppliers are adopting in-situ consolidation heads for automated fiber placement at rates exceeding thermoset layup by an order of magnitude. This compression eliminates cure cycle bottlenecks and enables single-day part turnaround for development programs.
REACH Annex XVII restrictions on isocyanates in polyurethane resin systems are forcing reformulation of automotive interior composites toward epoxy and thermoplastic alternatives. ECHA substance evaluation timelines are extending registration uncertainty for novel bio-based hardeners. German automotive OEMs are responding with accelerated supplier qualification for formaldehyde-free phenolic prepregs in engine bay applications.
Aftermarket service unbundling is fragmenting composite repair revenue away from OEM captive networks toward independent MRO specialists. Airlines are negotiating component-by-component maintenance contracts rather than bundled airframe service agreements. This pattern concentrates in North American and Middle Eastern carrier fleets with aging A350 and 787 carbon fiber structures entering heavy check cycles.
Functional Composites Market Segmentation
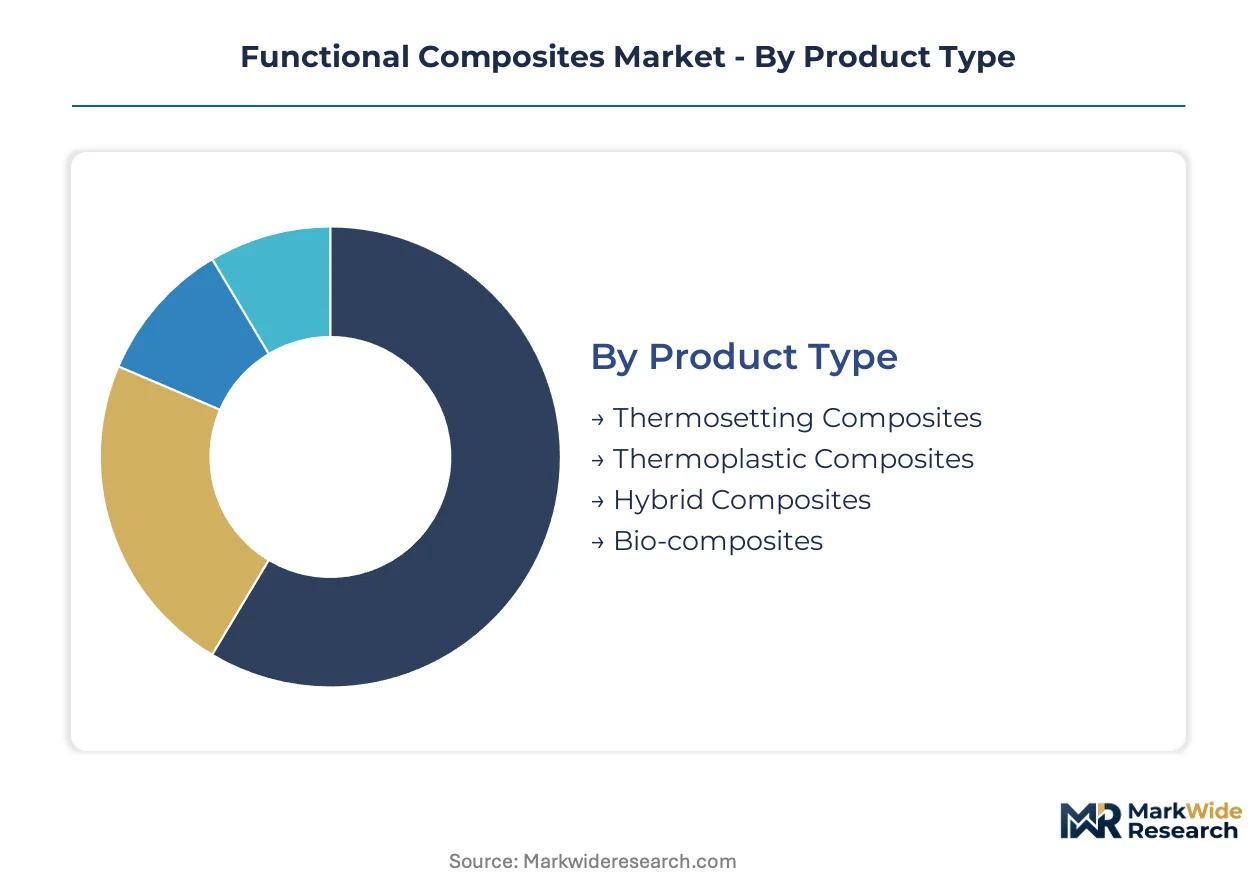
Functional composites demand fragments across incompatible processing chemistries, end-use certification regimes, and fiber reinforcement architectures. Procurement decisions hinge on specific strength targets, regulatory qualification pathways, and automated manufacturing compatibility.
Product Type:
Thermosetting systems anchor current aerospace programs while thermoplastic formats are displacing legacy materials through out-of-autoclave economics.
- Thermosetting Composites:Epoxy and phenolic resin matrices cured through autoclave or oven processes dominate wing skins and fuselage sections with established FAA damage tolerance databases. Boeing 787 and Airbus A350 primary structures lock in multi-decade demand from qualified supplier networks in Japan and Italy.
- Thermoplastic Composites:Polyetheretherketone and polyphenylene sulfide matrices enable in-situ consolidation during automated fiber placement, collapsing cycle times from hours to minutes for development programs. German automotive suppliers around Stuttgart are qualifying these for bumper beams and seat structures under REACH-compliant resin mandates.
- Hybrid Composites:Combining thermoset and thermoplastic layers or discontinuous fiber formats balances cost and performance for industrial robotics arms.
- Bio-composites:Flax and hemp fiber reinforcements in bio-based matrices attract European interior component procurement seeking cradle-to-cradle certification.
Thermosetting formats handle the majority of qualified aerospace throughput; thermoplastic composites are climbing the fastest on share through automotive and next-generation aircraft programs.
End User Industry:
Certification intensity and production volume separate premium structural applications from commodity thermal management markets.
- Aerospace:Primary flight structures, engine nacelles, and interior components demand FAA/EASA qualification databases with damage tolerance testing protocols. Boeing and Airbus tier-one suppliers concentrate in Wichita, Toulouse, and Hamburg.
- Automotive OEMs:Structural components, body panels, and underhood applications prioritize crash energy management and corrosion resistance. BMW and Porsche procurement teams in Munich specify carbon fiber roofs and thermoplastic bumper beams.
- Construction:Bridge decks, rebar, and architectural facades utilize glass fiber composites for durability in corrosive environments.
- Electronics:Printed circuit board substrates and electromagnetic shielding housings require controlled dielectric properties and thermal conductivity.
Aerospace commands the highest qualification premiums; automotive OEMs are expanding volume fastest as electrification reduces powertrain metal content.
Material:
Fiber selection trades stiffness-to-weight performance against impact tolerance and raw material security.
- Carbon Fiber:Polyacrylonitrile-based precursors yield tensile moduli exceeding 230 GPa for wing spars and pressure vessels. Toray, SGL Carbon, and Hexcel supply Japanese, German, and US aerospace programs respectively.
- Glass Fiber:E-glass and S-glass formats dominate corrosion-resistant construction and automotive semi-structural applications at lower cost points.
- Aramid Fiber:Kevlar and Twaron brands deliver ballistic protection and vibration damping for military helmets and aerospace fairings.
- Natural Fiber:Jute, flax, and hemp reinforcements serve interior automotive panels and consumer goods with reduced carbon footprint credentials under EU Green Deal procurement guidelines.
Carbon fiber captures the majority of aerospace value; natural fiber is expanding most quickly through European sustainability mandates.
Application:
Structural load-bearing requirements impose stricter qualification protocols than functional surface or insulation layers.
- Structural Components:Primary and secondary load-bearing elements including wing boxes, fuselage frames, and suspension links require laminate-level strength and stiffness validation. Airbus A220 wing skins and BMW i3 passenger cells exemplify certified applications.
- Thermal Insulation:Low thermal conductivity composites protect battery enclosures and exhaust systems in electric and hybrid vehicles.
- Electrical Insulation:Dielectric strength and tracking resistance specifications govern transformer housings and high-voltage cable trays.
- Surface Coatings:Gel coats and functional top layers provide UV resistance, radar absorption, or aesthetic finishes over structural substrates.
Structural components absorb the dominant share of R&D investment; thermal insulation is gaining share fastest through electric vehicle thermal management requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive buyers in Germany tolerate premium pricing for REACH-compliant thermoplastic solutions, while Indian defense procurement operates under stringent offset-driven cost discipline. Aerospace qualification premiums concentrate in US and French supply chains.
United States
FAA airworthiness directives drive damage tolerance testing investment for Boeing and Lockheed Martin tier-one networks. EPA volatile organic compound regulations shape facility location decisions in Washington state and Kansas. Wichita's aerospace cluster sustains automated fiber placement adoption for next-generation wing programs.
Germany
REACH Annex XVII restrictions on isocyanates force polyurethane resin reformulation across Stuttgart-Munich automotive corridors. ECHA substance evaluation timelines extend registration uncertainty for bio-based hardeners. BMW and Porsche procurement teams in Munich specify carbon fiber roofs and thermoplastic bumper beams under cradle-to-cradle mandates.
Japan
METI carbon neutrality roadmaps accelerate thermoplastic composite adoption in automotive lightweighting programs. JIS standards govern fiber-reinforced plastic quality certification for industrial robotics applications. Toray's precursor supply relationships anchor aerospace material flows through Nagoya manufacturing complexes.
India
Indigenous fighter programs and naval vessel construction open qualification pathways under offset agreement frameworks. BIS standards for fiber-reinforced plastics remain under development, creating transitional certification ambiguity. Bengaluru and Hyderabad defense clusters attract foreign composite suppliers seeking local partnership structures.
China
MIIT dual carbon goals redirect automotive composite procurement toward lightweight structural solutions. GB standards for carbon fiber reinforced plastics tighten quality consistency requirements for domestic suppliers. Shanghai and Tianjin aerospace subclusters expand thermoplastic processing capacity for COMAC narrowbody programs.
Functional Composites Market Vendor Landscape
Carbon fiber precursor specialists and resin system formulators split the market along raw material control vectors. Supplier networks concentrate around qualified aerospace tier-one relationships and automotive OEM direct contracting channels. Three archetypes dominate: integrated precursor-to-prepay operators, specialized resin compounders, and automated manufacturing equipment integrators. Capacity expansion and strategic qualification partnerships constitute the dominant competitive moves as firms secure position in emerging thermoplastic programs.
Within the integrated precursor tier, SGL Carbon and Toray Industries exemplify backward control over carbon fiber supply chains. Hexcel Corporation occupies a position among US-based formulators with multi-format fiber capabilities. Teijin Limited anchors the aramid specialization segment through material science depth in ballistic and industrial applications.
| Leading Market Players |
|---|
| SGL Carbon |
| Albany Engineered Composites |
| Toray Industries |
| Solvay |
| Umoe Advanced Composites |
| Hexcel Corporation |
| Mitsubishi Chemical Group |
| Toray Advanced Composites |
| Teijin Limited |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile price volatility in petrochemical feedstock markets compresses margin predictability for tier-two carbon fiber converters, forcing three-tier pricing stratification across premium aerospace-qualified, standard industrial-grade, and economy automotive-specification tiers while simultaneously reshaping supply chain geography toward precursor-integrated producers.
Pricing Analysis
Aftermarket service revenue for composite component repair and refurbishment drives lifetime value capture as airlines unbundle from OEM captive networks. Pricing stratifies across premium aerospace-qualified prepregs, standard industrial laminates, and economy automotive bulk molding compounds. Cost compression in automotive thermoplastic tiers intensifies because REACH-compliant resin reformulation adds qualification overhead. Tier-one aerospace buyers show least price sensitivity; commodity construction segments exhibit highest elasticity.
Supply Chain Analysis
Polyacrylonitrile precursor supply draws from Japanese, German, and US petrochemical complexes before carbonization at Toray, SGL Carbon, and Hexcel facilities. Raw material flows hinge on acrylonitrile monomer, pitch-based alternatives, and bio-based lignin feedstocks. Single-source vulnerability concentrates in the Stuttgart-Munich corridor for European aerospace qualification pathways. Distribution runs through qualified tier-one aerospace networks and direct OEM contracting channels for automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated fiber placement interoperability between thermoplastic tape suppliers and robotic equipment integrators is collapsing traditional material-former boundaries, creating platform-economics dynamics where qualification database control equals ecosystem leverage.
For Market Incumbents: Entrench damage tolerance certification expertise through apprenticeship programs with retiring Boeing and Lockheed Martin specialists, countering talent scarcity that constrains new program staffing. Deepen backward integration into carbon fiber precursor production to anchor margin control against acrylonitrile volatility. Secure in-house automated fiber placement capacity before equipment lead times extend.
For New Entrants and Emerging Players: Indian defense offset agreements for indigenous fighter and naval vessel programs represent the most penetrable entry point for foreign composite suppliers lacking established FAA qualification databases. Bio-composite formulations for European automotive interior components under cradle-to-cradle mandates offer second white-space targeting. Partner with Stuttgart-Munich tier-two automotive suppliers for REACH-compliant thermoplastic qualification pathways.
For Investors and Strategic Acquirers: Automated manufacturing equipment integrators with in-situ consolidation head technology command scarcity premiums as Boeing and Airbus tier-one suppliers accelerate thermoplastic adoption. Long-term viability hinges on positioning within next-generation narrowbody wing programs. Watch for FAA airworthiness directive finalization on thermoplastic damage tolerance protocols as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | SGL Carbon and Toray anchor supply security against acrylonitrile price swings. |
| Automated Fiber Placement Capacity Expansion | Wichita and Hamburg clusters compress wing box cycle times from hours to minutes. |
| REACH-Compliant Resin System Qualification | German automotive OEMs mandate formaldehyde-free phenolic prepregs for engine bay applications. |
| Damage Tolerance Certification Investment | FAA protocols standardize qualification databases for flight-critical thermoplastic structures. |
| Extended Producer Responsibility Partnership | EU end-of-life recovery mandates create closed-loop economics for carbon fiber recyclers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, ECHA substance registrations, and customs trade data for carbon fiber and precursor flows. Primary interviews engaged aerospace tier-one procurement directors, automotive composite engineers at BMW and Porsche, thermoplastic processing equipment specialists, and carbon fiber recycling operators. Secondary validation drew from SEC 10-K filings of Hexcel and Toray, REACH Annex XVII restriction updates, and production databases for Boeing 787 and Airbus A350 programs. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Forecast inputs considered thermoplastic composite adoption rates in next-generation aircraft programs, automotive electrification content shifts, and defense offset agreement volumes. Segmentation dimensions modeled include resin chemistry class, fiber reinforcement architecture, end-use certification intensity, and regional regulatory cluster. CAGRs derived from regression against historical qualification cycle times and processing automation penetration curves. Industry-specific inputs incorporated automated fiber placement equipment installation rates and REACH registration timeline probabilities.
Stress conditions across acrylonitrile price bands, FAA certification timeline delays, and German supplier corridor disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding thermoplastic damage tolerance database maturation and automotive procurement mandate enforcement. Cross-checking against IHS Markit aerospace production forecasts and European automotive registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Ferroelectric Materials Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Functional Acids Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Flexible Thin Film Market