
 Functionalized Nanocomposites Market | 2026-2036
Functionalized Nanocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Functionalized Nanocomposites Market Foresight
Specialty chemical distribution channels are reshaping how functionalized nanocomposites reach end users, with regional distributors consolidating technical service capabilities to support formulation trials. Arkema S.A. leverages its fluoropolymer backbone to anchor high-performance polymer nanocomposite supply for semiconductor cleanroom applications. Nanocyl SA specializes in controlled carbon nanotube functionalization, sustaining premium positioning through plasma treatment expertise that competing commodity fillers cannot replicate.
Functionalized nanocomposites are engineered materials in which nanoparticles undergo surface modification through covalent bonding, grafting, or silanization to achieve dispersion stability and interfacial adhesion within a matrix, typically targeting mechanical reinforcement, thermal conductivity, or barrier performance. Polymer nanocomposites dominate current volume as mature compounding infrastructure supports scale, while carbon nanotube grades command concentrated margin pools in electronics and aerospace applications where electrical conductivity and specific strength requirements exclude conventional fillers. Ceramic nanocomposites are gaining traction in drug delivery systems where surface functionalization enables targeted bioavailability, though regulatory validation timelines constrain near-term revenue contribution.
EPA oversight of nanoparticle environmental release and REACH registration requirements for surface-modified substances in Europe are elevating compliance costs for uncertified producers while creating certification premiums for verified grades. FDA evaluation pathways for nanocomposite-enabled pharmaceutical applications and ECHA substance-specific dossiers further fragment market access timelines across jurisdictions. Stakeholders must monitor evolving toxicity testing protocols and pre-registration data obligations, as regulatory alignment between the EPA and ECHA on nanomaterial characterization standards will determine which functionalization platforms achieve cross-border commercial viability.
Market Dynamics
REACH registration thresholds for surface-modified nanomaterials are forcing European formulators toward certified functionalized grades, while aerospace OEM procurement of carbon nanotube-reinforced panels concentrates demand around integrated polymer-nanofiller pilot clusters.
Growth Catalysts
- EPA Environmental Release Guidelines:Tightening thresholds for unmodified nanoparticle discharge in the United States push industrial compounders toward verified functionalized grades that demonstrate controlled dispersion stability.
- Aerospace Structural Lightweighting:Aircraft manufacturers scale procurement of carbon nanotube-reinforced panels to achieve specific strength targets that exclude conventional mineral fillers.
- Plasma Treatment Expertise:Controlled functionalization processes enable dispersion stability in high-performance polymer matrices for semiconductor cleanroom applications.
Market Restraints
- Multi-Jurisdictional Registration Costs:ECHA substance-specific dossiers and EPA pre-manufacture notification requirements create overlapping compliance burdens for uncertified producers.
- Raw Material Concentration:Carbon nanotube feedstock supply concentrates among specialized chemical intermediates suppliers with captive plasma treatment capabilities.
- Regulatory Timeline Fragmentation:FDA evaluation pathways for nanocomposite-enabled drug delivery systems extend commercialization horizons beyond typical investment cycles.
Strategic Opportunities
- Underpenetrated Pharmaceutical Applications:Surface-functionalized ceramic nanocomposites enable targeted bioavailability in drug delivery systems awaiting regulatory validation.
- EU Green Deal Industrial Mandates:Carbon footprint reduction requirements accelerate substitution of metal components with lightweight polymer nanocomposites in automotive platforms.
- Technical Service Consolidation:Regional specialty distributors integrate formulation trial capabilities to capture margin from compounders seeking application-specific dispersion optimization.
Industry Challenges
- Interfacial Adhesion Engineering Talent:Scarce expertise in covalent bonding and silanization chemistry constrains scale-up of qualified functionalization protocols.
- Legacy Compounding Infrastructure Retrofit:Existing twin-screw extrusion lines require capital-intensive modification to achieve dispersion stability with high-aspect-ratio nanofillers.
- Cross-Border Characterization Standards:Misalignment between EPA and ECHA nanomaterial testing protocols forces redundant toxicity studies for multi-regional product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functionalized Nanocomposites Market |
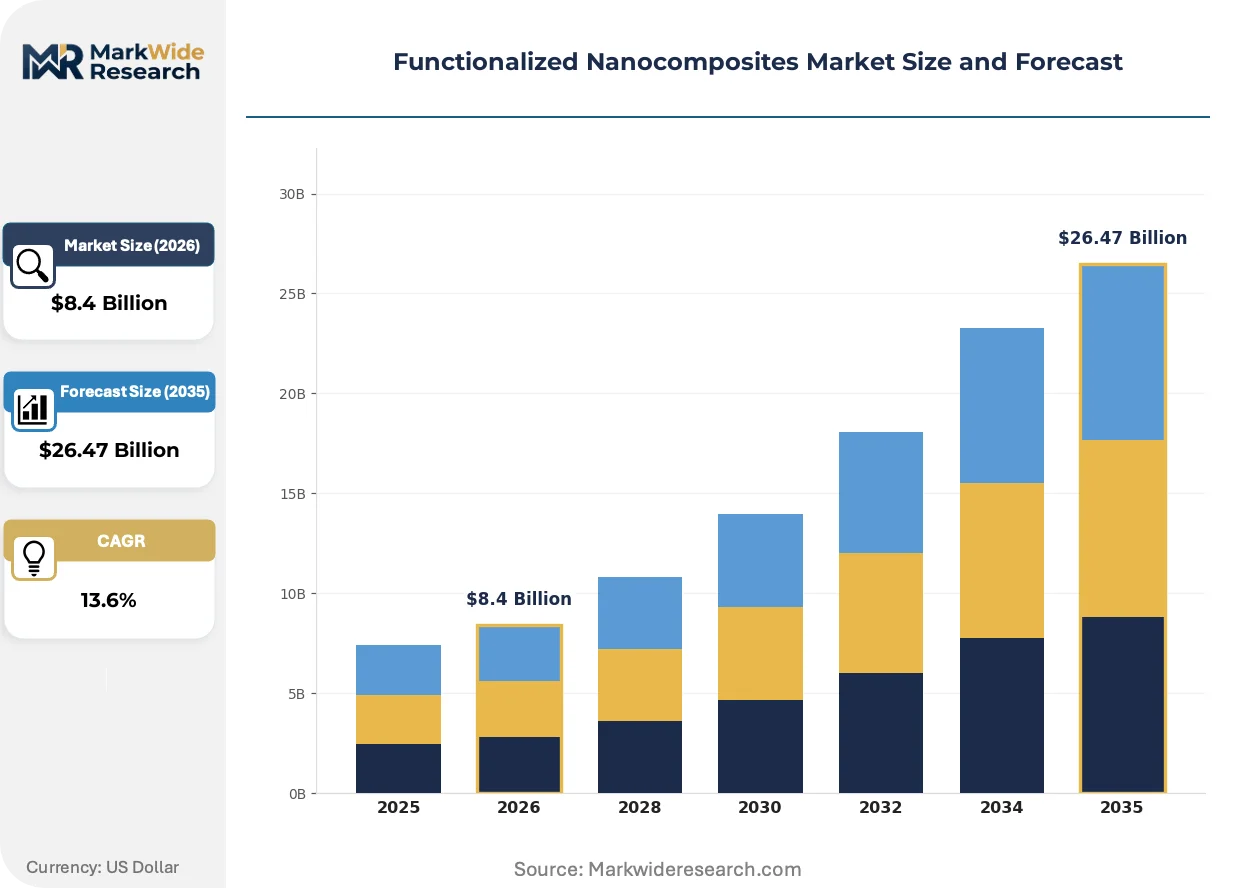
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Nanocomposites, Ceramic Nanocomposites, Metal Nanocomposites, Carbon Nanotubes Functionalization Technique: Covalent Bonding, Non-Covalent Bonding, Grafting, Plasma Treatment, Silanization Application: Electronics, Aerospace Components, Drug Delivery Systems, Coatings, Water Treatment End User Industry: Semiconductor Manufacturers, Aircraft Manufacturers, Pharmaceutical Firms, Paint & Coatings Firms |
| Companies Covered | Arkema S.A., Nanocyl SA, Cabot Corporation, Solvay S.A., Imerys S.A., Evonik Industries AG, 3M Company, Dow Chemical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functionalized Nanocomposites Market Shifts & Advancements
Functionalization chemistry is collapsing traditional boundaries between bulk compounding and specialty performance materials, as surface modification protocols enable commodity polymer infrastructure to produce aerospace-grade nanocomposites.
Plasma-induced grafting is collapsing the performance gap between multi-wall carbon nanotubes and single-wall variants for electrical conductivity applications. Automotive wiring harness manufacturers in Germany adopt plasma-treated grades at accelerated qualification cycles. This compression of performance tiers is collapsing premium pricing structures that previously separated aerospace-specification materials from industrial grades.
REACH registration requirements for surface-modified substances are elevating compliance costs for uncertified nanomaterial producers across Europe. Industrial compounders now demand certified functionalized grades with pre-submitted ECHA dossiers to avoid manufacturing interruptions. Ceramic nanocomposite developers targeting pharmaceutical applications face the steepest documentation burdens, redirecting R&D investment toward EPA-aligned characterization protocols that promise future mutual recognition.
Specialty chemical distributors are consolidating technical service capabilities to capture formulation trial revenue previously retained by compounders. Regional distributors in the Rhineland now host pilot extrusion lines for automotive OEM qualification runs, displacing traditional supplier-direct engagement models. This channel restructuring concentrates most visibly in Germany, where integrated polymer-nanofiller clusters around Cologne and Leverkusen enable same-day sample turnaround for aviation specification testing.
Functionalized Nanocomposites Market Segmentation
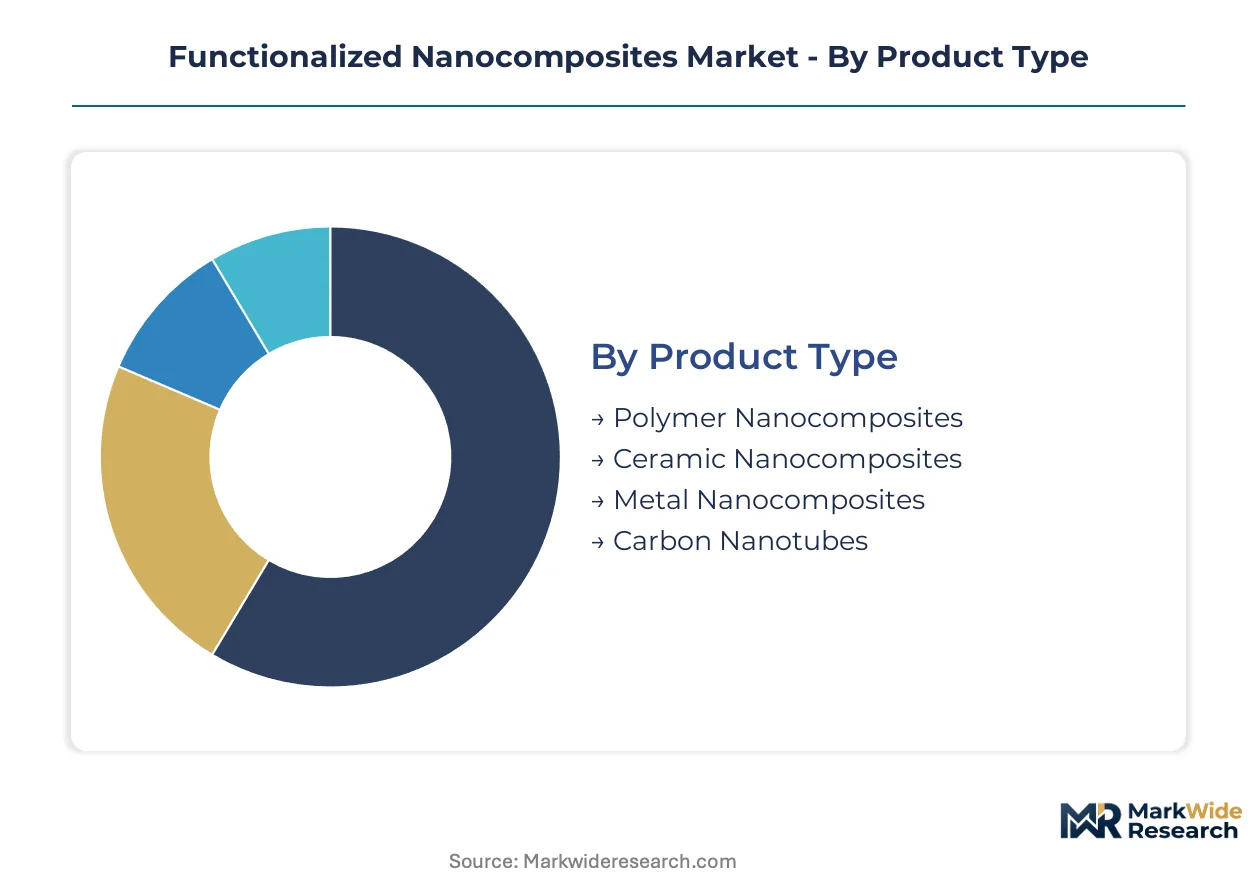
Functionalized nanocomposites require precise segmentation because surface modification chemistry determines matrix compatibility and end-use qualification. Product type and functionalization technique together dictate which regulatory pathways and customer specifications apply.
Product Type:
Mature polymer infrastructure supports scale for commodity grades while emerging ceramic platforms await pharmaceutical validation timelines.
- Polymer Nanocomposites:Surface-modified nanoparticles disperse within thermoplastic and thermoset matrices using existing twin-screw extrusion infrastructure. Aircraft manufacturers in Germany and Japan concentrate procurement for structural lightweighting programs requiring REACH-registered grades.
- Ceramic Nanocomposites:Engineered for targeted bioavailability in drug delivery systems where surface functionalization enables controlled release kinetics. FDA evaluation pathways in the United States and EMA timelines in Europe extend commercialization horizons beyond typical investment cycles.
- Metal Nanocomposites:Hybrid systems combining metallic matrices with ceramic or carbon nanofillers for thermal management applications.
- Carbon Nanotubes:Multi-wall and single-wall variants command premium positioning in semiconductor cleanroom and aerospace electrical conductivity applications.
Polymer nanocomposites retain volume leadership; ceramic nanocomposites hold the steepest expansion curve.
Functionalization Technique:
Cost tier separates established wet chemistry methods from capital-intensive plasma processes that sustain margin premiums.
- Plasma Treatment:Controlled surface activation enables dispersion stability in high-performance matrices without compromising nanofiller structural integrity. Specialty chemical distributors in the Rhineland consolidate technical service capabilities around plasma expertise to support automotive OEM qualification runs.
- Silanization:Organosilane coupling agents create covalent bridges between inorganic nanofillers and organic polymer matrices. EPA environmental release guidelines in the United States push industrial compounders toward verified silanized grades demonstrating controlled dispersion stability.
- Covalent Bonding:Direct chemical attachment of functional groups to nanoparticle surfaces for permanent surface modification.
- Non-Covalent Bonding:Physical adsorption of surfactants or polymers for reversible surface modification in cost-sensitive applications.
- Grafting:Polymer chain attachment via living polymerization techniques for tailored interfacial properties.
Silanization dominates current volume; plasma treatment captures the highest value per kilogram.
Application:
Customer type stratification separates specification-driven aerospace and semiconductor buyers from price-sensitive coatings and water treatment segments.
- Electronics:Semiconductor cleanroom applications demand plasma-treated carbon nanotube grades with verified ionic purity and controlled electrical conductivity. Procurement concentrates among integrated device manufacturers in Taiwan and South Korea requiring ECHA-aligned characterization protocols.
- Aerospace Components:Carbon nanotube-reinforced panels achieve specific strength targets excluding conventional mineral fillers. Aircraft manufacturers scale procurement through integrated polymer-nanofiller pilot clusters around Cologne and Leverkusen.
- Drug Delivery Systems:Surface-functionalized ceramic nanocomposites enable targeted bioavailability awaiting regulatory validation.
- Coatings:Barrier performance applications in automotive and industrial finishes using cost-optimized functionalization routes.
- Water Treatment:Adsorptive nanocomposite membranes for contaminant removal in municipal and industrial purification systems.
Electronics commands the highest pricing tier; drug delivery systems face the longest path to revenue recognition.
End User Industry:
Supply concentration aligns with geographic clusters where regulatory pre-certification and technical service integration reduce qualification friction.
- Semiconductor Manufacturers:Cleanroom-grade nanocomposite specifications require plasma treatment expertise and ionic contamination controls. Demand concentrates in fabrication hubs where specialty distributors host pilot extrusion lines for same-day sample turnaround.
- Aircraft Manufacturers:Structural lightweighting mandates drive carbon nanotube panel procurement through REACH-registered supply chains. EU Green Deal industrial mandates accelerate substitution of metal components with lightweight polymer nanocomposites.
- Pharmaceutical Firms:Ceramic nanocomposite developers face steepest documentation burdens from FDA and EMA evaluation pathways.
- Paint & Coatings Firms:Volume buyers of cost-optimized functionalized grades for barrier and durability performance.
Aircraft manufacturers anchor current demand volume; pharmaceutical firms represent the most delayed but highest-margin opportunity set.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration thresholds for surface-modified nanomaterials and EPA environmental release guidelines are redirecting procurement toward certified functionalized grades across major industrial economies.
United States
Aerospace manufacturers in Washington State and California scale carbon nanotube-reinforced panel procurement for structural lightweighting programs. EPA pre-manufacture notification requirements for unmodified nanoparticles push compounders toward verified grades with controlled dispersion stability. Integrated polymer-nanofiller pilot clusters in the Boston-Cambridge corridor serve semiconductor cleanroom applications.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg accelerate substitution of metal components with lightweight polymer nanocomposites under EU Green Deal industrial mandates. ECHA substance-specific dossiers for surface-modified substances elevate compliance costs for uncertified producers. The Cologne-Leverkusen cluster hosts same-day sample turnaround capabilities for aviation specification testing.
China
Semiconductor fabrication hubs in the Yangtze River Delta and Pearl River Delta concentrate demand for plasma-treated carbon nanotube grades with ionic purity controls. MIIT standards for nanomaterial characterization align partially with OECD guidelines but retain domestic testing protocols. Shanghai-based specialty distributors integrate pilot extrusion lines for automotive OEM qualification runs.
Japan
Integrated device manufacturers in the Tokyo-Osaka corridor procure REACH-registered functionalized grades for electronics applications. METI safety assessment frameworks for manufactured nanomaterials create parallel documentation requirements to ECHA protocols. Nagoya-area automotive suppliers qualify carbon nanotube-reinforced composites for next-generation vehicle platforms.
South Korea
Memory and logic chip producers in the Seoul Capital Area and Busan-Ulsan region drive specification-grade nanocomposite procurement. MFDS evaluation pathways for nanocomposite-enabled pharmaceutical applications extend timelines for ceramic platform developers. Daegu-Gyeongbuk textile and materials clusters experiment with functionalized nanocomposite integration for industrial filtration systems.
Functionalized Nanocomposites Market Competitive Landscape
On the supply side, the industry is bifurcated between diversified chemical conglomerates with captive nanofiller production and specialized functionalization houses with plasma treatment expertise. The vendor base separates into three strategic archetypes: integrated polymer producers backward into nanofiller supply, dedicated nanomaterial functionalization specialists, and regional compounders with formulation trial capabilities. Dominant competitive moves include M&A targeting plasma treatment technology access and capacity expansion around integrated polymer-nanofiller pilot clusters.
Within the specialized functionalization tier, Nanocyl SA and Arkema S.A. exemplify divergent positioning strategies. Nanocyl SA represents the dedicated nanomaterial archetype, occupying a position anchored in controlled carbon nanotube functionalization capabilities. Arkema S.A. sits within the diversified chemical conglomerate archetype, leveraging fluoropolymer backbone integration to supply high-performance polymer nanocomposites. Cabot Corporation occupies a mid-tier position between these extremes, representing scale-driven carbon black and nanomaterial production with regional distribution consolidation. These three anchors illustrate how competitive positioning stratifies across technology depth, vertical integration scope, and geographic service density.
| Leading Market Players |
|---|
| Arkema S.A. |
| Nanocyl SA |
| Cabot Corporation |
| Solvay S.A. |
| Imerys S.A. |
| Evonik Industries AG |
| 3M Company |
| Dow Chemical |
| BASF SE |
| Others |
Supply & Pricing Matrix
Rhineland logistics corridors connecting the Cologne-Leverkusen nanocomposite cluster to Bavarian automotive plants impose freight cost premiums that compound supply concentration effects, amplifying price spreads between REACH-certified functionalized grades and uncertified alternatives while steering procurement toward integrated pilot-line operators with same-day sample capabilities.
Pricing Analysis
Certification level creates the primary spread between REACH-registered plasma-treated carbon nanotubes and commodity silanized grades. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA dossier completeness, with semiconductor cleanroom specifications commanding the highest tier. Cost compression in standard-grade polymer nanocomposites is intensifying because automotive OEMs consolidate volume procurement around qualified Rhineland distributors. Paint and coatings firms exhibit the greatest price sensitivity, while aircraft manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for carbon nanotube feedstock. Manufacturing concentrates in Belgium, Germany, and South Korea for plasma treatment capabilities, while China and Japan anchor multi-wall nanotube precursor production. Raw material dependencies include acetylene feedstock, organosilane coupling agents, and fluoropolymer backbones. Single-source vulnerability persists for high-purity plasma treatment equipment. Distribution runs through specialty chemical distributors with integrated pilot extrusion lines rather than direct supplier engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functionalized nanocomposites sit in an early-cycle expansion phase, with EU Green Deal industrial mandates accelerating metal-to-polymer substitution in automotive platforms beyond current supply capacity.
For Market Incumbents: Entrench plasma treatment expertise through captive equipment acquisition and ECHA dossier pre-submission to lock out commodity competitors. Arkema S.A. and Nanocyl SA demonstrate how fluoropolymer backbone integration and controlled functionalization protocols respectively create defensible positioning against emerging Chinese silanization houses. Prioritize backward integration into carbon nanotube precursor supply to offset raw material concentration risk. For New Entrants and Emerging Players: Pharmaceutical ceramic nanocomposites awaiting FDA validation represent the most penetrable entry point for specialized functionalization houses, as regulatory documentation burdens deter diversified chemical conglomerates. Regional distributors in South Korea and Japan lacking pilot extrusion capabilities present channel partnership opportunities. Target qualification support services rather than direct material supply to circumvent capital-intensive plasma equipment requirements. For Investors and Strategic Acquirers: REACH-ECHA alignment on nanomaterial characterization standards reshapes the acquisition landscape toward EPA-protocol-ready functionalization platforms with cross-border commercial viability. Five-to-ten-year viability favors specialists with pharmaceutical validation pipelines over commodity polymer compounders. Monitor ECHA substance-specific dossier approval velocity as the signal for which functionalization chemistries achieve scalable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Treatment Capacity Expansion | Captures premium pricing from semiconductor cleanroom specifications in Taiwan and South Korea. |
| ECHA Dossier Pre-Submission | Secures manufacturing continuity for European automotive and aerospace OEM procurement. |
| Backward Integration into Carbon Nanotube Precursors | Reduces dependency on Chinese and Japanese acetylene-based feedstock suppliers. |
| Pharmaceutical Ceramic Platform Development | Opens highest-margin opportunity set pending FDA and EMA validation timelines. |
| Regional Distributor Technical Service Integration | Displaces direct supplier engagement with pilot extrusion capabilities for same-day qualification. |
Research Methodology
A spread of perspectives from nanomaterial R&D directors, automotive OEM procurement leads, specialty chemical distribution partners, and regulatory affairs specialists at ECHA and EPA converged on the working assumptions. Primary interview insights triangulated against customs trade data, SEC 10-K filings from diversified chemical conglomerates, REACH registration databases, and OECD nanomaterial guidance documents. Bottom-up volume estimates from functionalization technique segments reconciled with top-down aerospace and semiconductor demand projections.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, functionalization technique, application, and end-use industry. CAGRs derived from installed capacity expansion timelines and OEM qualification cycle velocities. Forecast inputs included EU Green Deal industrial mandate implementation schedules and EMA-FDA pharmaceutical evaluation pathway convergence probabilities.
Practitioners should monitor ECHA-EPA characterization protocol alignment, carbon nanotube feedstock tariff developments, and pharmaceutical ceramic nanocomposite FDA approval milestones for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Smart Card Materials Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Functional Composites Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Thermal Interface Pads and Material Market