
 Functional Acids Market | 2026-2036
Functional Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Acids Market Foresight
Biobased fermentation technology is tilting production economics toward microbial-derived acids and away from petrochemical routes. BASF SE leverages integrated fermentation complexes in Ludwigshafen to sustain cost leadership in citric acid derivatives. Cargill, Inc. anchors North American supply through its Blair, Nebraska biorefinery, converting corn dextrose into lactic acid at industrial scale. Jungbunzlauer Suisse AG dominates Swiss pharmaceutical-grade acid output with dedicated crystallization lines meeting EP and USP monographs.
Functional acids comprise organic carboxylic compounds—typically C2-C6 chain lengths—produced via submerged fermentation or chemical synthesis, characterized by pH reduction, metal chelation, and preservative functionality in aqueous systems. Citric acid occupies the largest value pool due to its ubiquity in beverage acidification and pharmaceutical buffering, while propionic acid registers the fastest structural growth as grain preservative demand intensifies amid climate-driven storage losses. Lactic acid concentrates margin in polymer-grade specifications for polylactic acid feedstock, where polymerization-grade purity commands premium positioning over standard food grades.
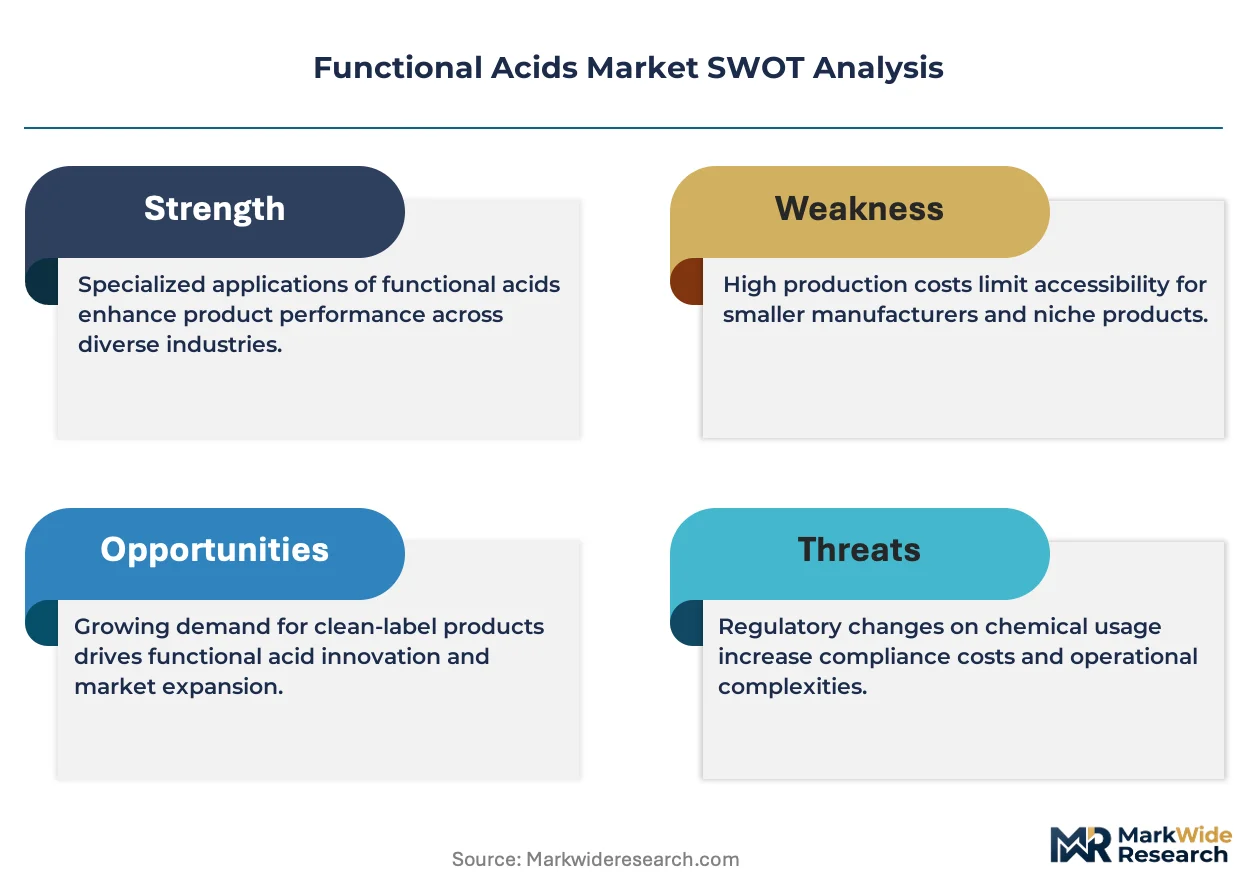
EPA biofuel mandates and FDA food additive regulations shape US product standards and facility certification requirements, while REACH registration in Europe imposes full toxicological dossiers on acid importers. The EU F-Gas Regulation indirectly redirects preservative demand toward organic acids as synthetic refrigerant alternatives proliferate. Stakeholders must monitor fermentation feedstock cost volatility and regulatory divergence between jurisdictions to calibrate capacity allocation and certification investments.
Market Dynamics
Biobased fermentation complexes are compressing petrochemical acid margins across all major producing regions, as integrated biorefineries achieve feedstock-to-derivative cost structures that chemical synthesis routes cannot match.
Growth Catalysts
- REACH Registration Thresholds:ECHA's tightened purity dossiers for acid imports into Europe are filtering out low-grade suppliers and consolidating demand around certified fermentation-derived sources.
- Brazilian Antibiotic Phase-Out:ANVISA's restrictions on growth promoters in animal nutrition are redirecting feed additive procurement toward propionic and formic acid preservatives.
- Submerged Fermentation Scale-Up:Continuous culture systems with automated pH control are cutting citric acid batch times by half at industrial biorefineries.
Market Restraints
- Corn Dextrose Price Volatility:Feedstock costs for North American lactic acid producers swing with ethanol policy and planting conditions, compressing margin predictability.
- Swiss Crystallization Lock-In:Pharmaceutical-grade acid output concentrates in Alpine facilities with dedicated EP/USP lines, creating supply concentration risk for high-purity grades.
- Synthetic Refrigerant Substitution:The EU F-Gas Regulation's hydrofluorocarbon phase-down is displacing some traditional acidulant applications in cooling systems.
Strategic Opportunities
- Southeast Asia Clean-Label Expansion:Food processors in Vietnam and Indonesia are expanding acidulants procurement for preservative-free positioning in export markets.
- Polylactic Acid Feedstock Premium:Polymer-grade lactic acid specifications command substantial margin separation from standard food grades as bioplastic capacity scales.
- Carbon Border Adjustment Mechanism:The EU CBAM's eventual coverage of organic chemicals will advantage low-carbon fermentation routes over naphtha-derived production.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA food additive petitions, REACH dossier updates, and EP monograph revisions strain regulatory affairs bandwidth.
- Fermentation Specialist Scarcity:Industrial microbiologists with scaled bioprocess experience command premium compensation, constraining greenfield project staffing.
- Legacy Chemical Synthesis Asset Stranding:Petrochemical acid plants face accelerated depreciation as biobased capacity achieves cost parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Acids Market |
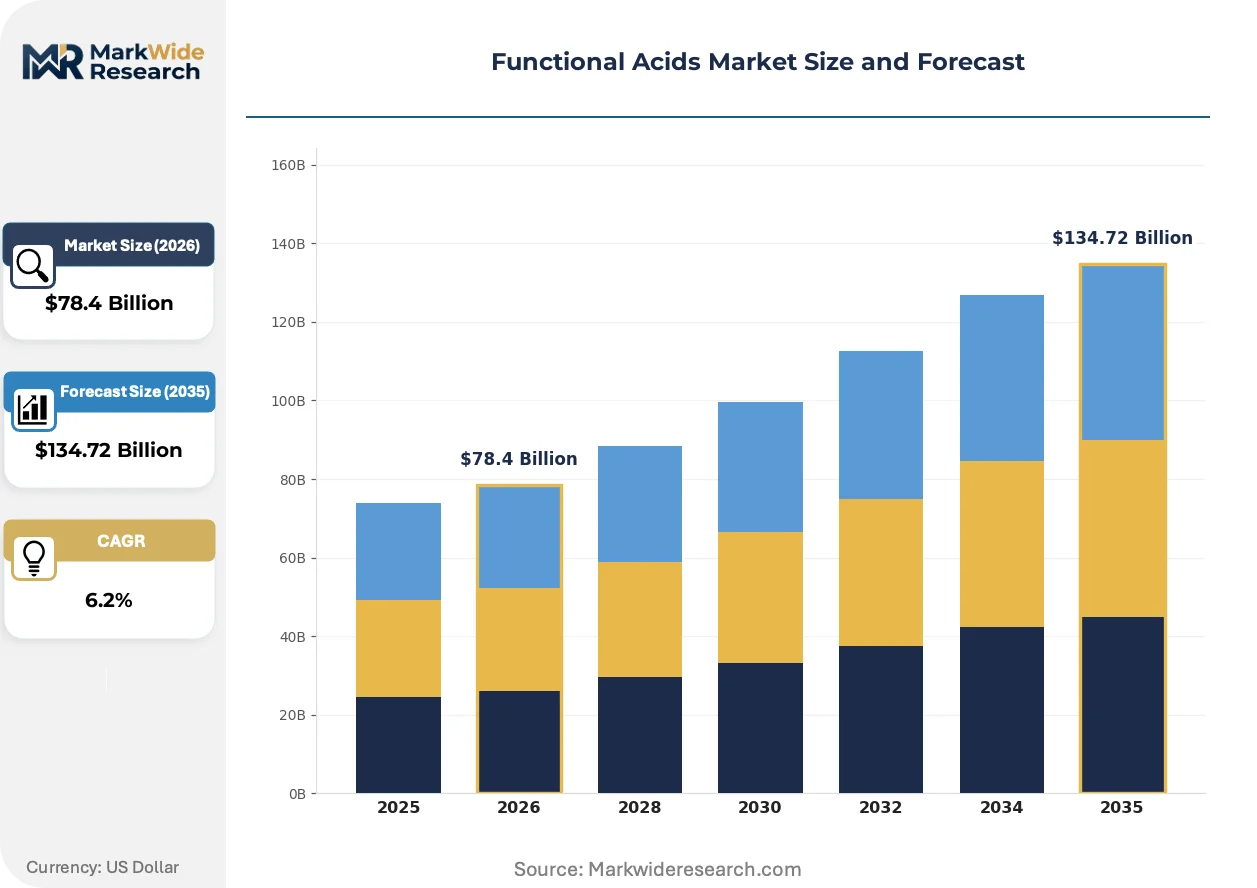
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Malic Acid, Tartaric Acid, Propionic Acid Application: Food & Beverage, Personal Care, Cleaning Agents, Pharmaceuticals, Agriculture, Animal Nutrition Form: Liquid, Powder, Granules, Crystalline End User Industry: Food Processing Units, Cosmetic Manufacturers, Chemical Synthesizers, Crop Protectors, Veterinary Products |
| Companies Covered | BASF SE, Cargill, Inc., Archer Daniels Midland Company, Corbion N.V., Jungbunzlauer Suisse AG, Evonik Industries AG, DuPont de Nemours, Inc., Tate & Lyle PLC, Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Acids Market Shifts & Advancements
Continuous processing and metabolic engineering are converging to rewrite production economics, while regulatory frameworks on both sides of the Atlantic recalibrate competitive access conditions.
Precision genome-edited yeast strains with enhanced citric acid export pumps are rendering obsolete traditional Aspergillus niger batch fermentation. Pharmaceutical buffer manufacturers are adopting these lines first, drawn by reduced contamination risk and tighter metabolite profiles. The technology is compressing fermentation residence times from seven days to under four, collapsing working capital requirements for citrate derivatives.
The EU F-Gas Regulation's hydrofluorocarbon quota system is redirecting cold-chain preservative demand toward organic acids as synthetic refrigerant alternatives proliferate. Food logistics operators in Germany and France are reformulating transport cooling systems around propionic acid-based solutions. This shift concentrates procurement influence with integrated acid producers capable of certifying food-contact compliance under EFSA migration limits.
Direct procurement contracts between Southeast Asian food conglomerates and fermentation facilities are displacing traditional distributor networks for acidulant supply. Thai and Vietnamese processors now negotiate volume commitments directly with Ludwigshafen and Blair facilities, bypassing regional chemical traders. This channel compression is most visible in beverage acidification, where specification consistency and lot traceability outweigh price flexibility.
Functional Acids Market Segmentation
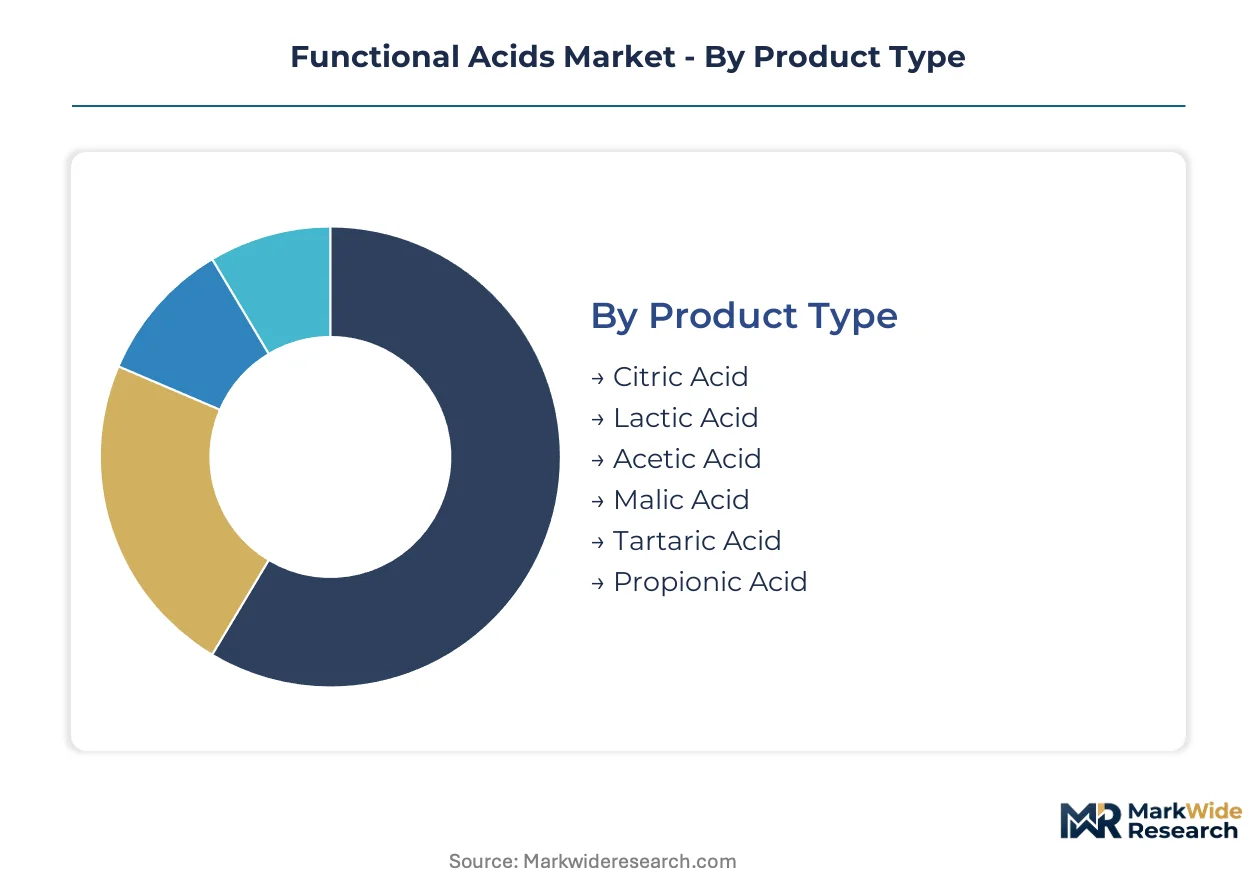
Functional acids demand fragments across molecular specifications, purity grades, and delivery formats that dictate manufacturing scale and certification requirements. Each segmentation axis reveals distinct margin structures, with pharmaceutical and polymer-grade specifications commanding substantial premiums over commodity food grades.
Product Type:
Use-case spectrum spans beverage acidification, pharmaceutical buffering, bioplastic feedstock, and grain preservation, with each application imposing distinct purity and chain-length requirements.
- Citric Acid:Tricarboxylic acid produced via Aspergillus niger submerged fermentation dominates beverage acidification and pharmaceutical buffering. Demand concentrates in Southeast Asian food processing units expanding clean-label formulations for export markets.
- Lactic Acid:C3 hydroxy acid exists in L- and D-stereoisomer configurations with polymer-grade purity commanding premium positioning over standard food grades. Brazilian polylactic acid feedstock procurement is accelerating as bioplastic capacity scales.
- Acetic Acid:Simplest carboxylic acid serves vinegar production and chemical synthesis feedstock.
- Malic Acid:Dicarboxylic acid provides tartness enhancement in confectionery and beverages.
- Tartaric Acid:Naturally occurring acid from grape fermentation targets wine stabilization and cream of tartar production.
- Propionic Acid:Short-chain fatty acid functions as grain preservative and mold inhibitor in animal feed.
The dominant share belongs to citric acid, while lactic acid is closing the gap fastest.
Application:
Volume concentration tracks regulatory divergence between food-contact approval jurisdictions and pharmaceutical certification requirements.
- Food & Beverage:Largest consumption category spanning acidulants, preservatives, and flavor modifiers in processed foods and soft drinks. Vietnam and Indonesia processors are expanding direct procurement from fermentation facilities to secure lot traceability.
- Pharmaceuticals:Buffering agents and active pharmaceutical ingredients require EP and USP monograph compliance with dedicated crystallization lines. Swiss Alpine facilities concentrate high-purity output, creating supply concentration risk for critical grades.
- Personal Care:pH adjusters and preservative boosters in cosmetic formulations.
- Cleaning Agents:Descaling and chelating functionality in industrial and household formulations.
- Agriculture:Soil acidification and nutrient availability enhancement.
- Animal Nutrition:ANVISA restrictions on antibiotic growth promoters in Brazil are redirecting feed additive procurement toward propionic and formic acid preservatives.
Food and beverage applications anchor volume, though pharmaceuticals deliver the steepest margin expansion trajectory.
Form:
Physical state selection hinges on solubility kinetics, storage stability, and downstream handling economics in customer formulations.
- Liquid:Ready-to-use aqueous solutions dominate beverage manufacturing and chemical synthesis where rapid dispersion matters. Blair, Nebraska biorefinery ships bulk liquid lactic acid to North American polymer producers.
- Powder:Spray-dried formulations serve dry-mix applications in bakery and nutritional supplements.
- Granules:Free-flowing agglomerated particles reduce dust generation in feed milling operations.
- Crystalline:High-purity geometric forms meet pharmaceutical EP and USP specifications with defined particle size distribution.
Liquid form holds the largest installed base, while crystalline grades are expanding most quickly on pharmaceutical demand.
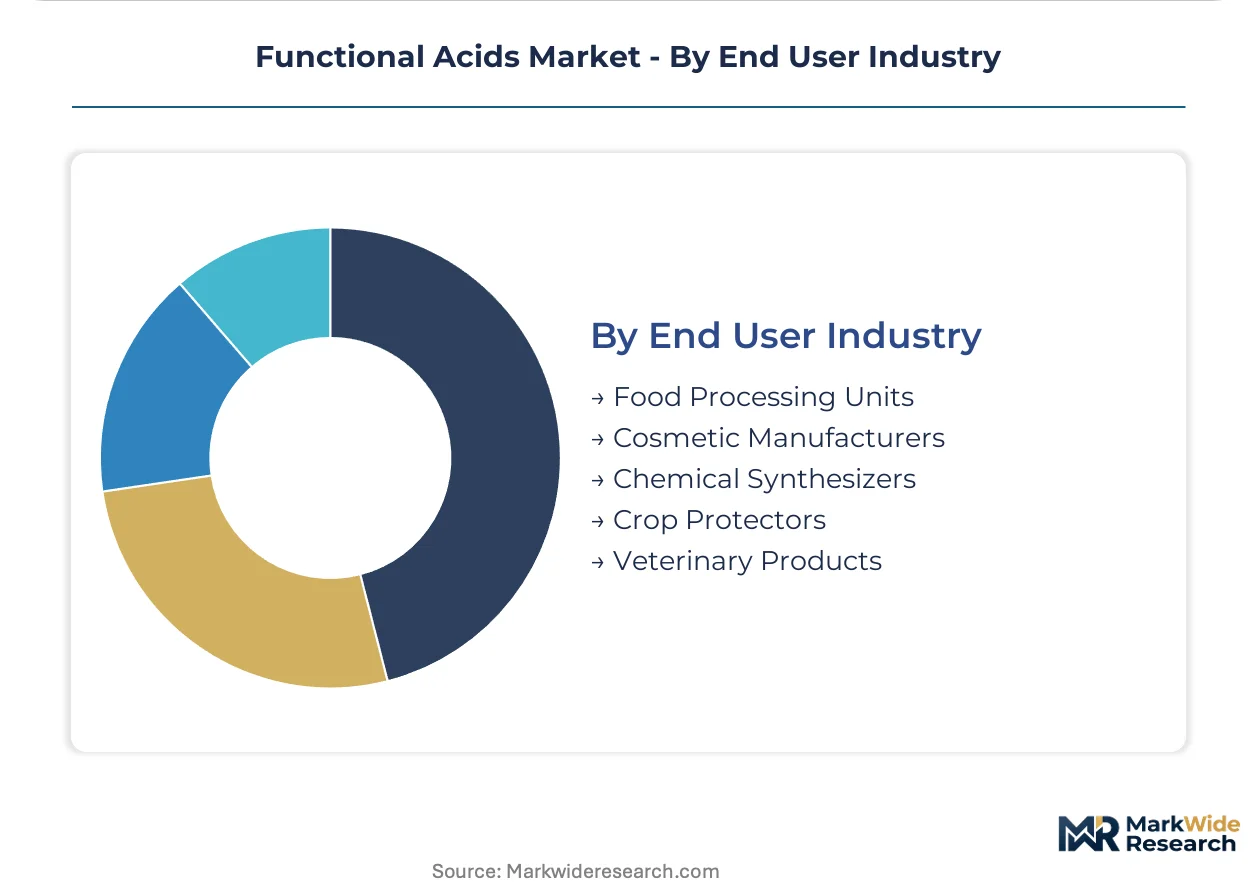
End User Industry:
Customer concentration varies from fragmented food processors to consolidated pharmaceutical buffer manufacturers with stringent audit requirements.
- Food Processing Units:Diverse manufacturers of beverages, confectionery, and prepared foods driving clean-label acidulant procurement. Thai and Vietnamese conglomerates now negotiate volume commitments directly with Ludwigshafen fermentation complexes.
- Chemical Synthesizers:Industrial consumers converting acids into esters, salts, and derivative intermediates.
- Cosmetic Manufacturers:Formulators requiring pH adjustment and preservation in personal care products.
- Crop Protectors:Agricultural chemical producers integrating acids into pesticide formulations.
- Veterinary Products:Animal health manufacturers substituting organic acids for antibiotic growth promoters under tightening regulatory restrictions.
Food processing units command the dominant procurement volume, while veterinary products are gaining share fastest on antibiotic phase-out mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across major economies are tightening as fermentation-derived acid production concentrates in feedstock-rich regions while pharmaceutical-grade demand pulls toward specialized crystallization hubs. Trade flows now track regulatory certification requirements more closely than raw logistics costs.
United States
EPA biofuel mandates and FDA food additive regulations are reshaping domestic production standards for acidulants and preservatives. Corn belt biorefineries in Iowa and Nebraska supply dextrose-derived lactic acid to polymer producers seeking bioplastic feedstock. The Blair, Nebraska fermentation complex anchors North American supply through direct procurement contracts with food processors.
Germany
ECHA's REACH dossier requirements for acid imports are filtering out uncertified suppliers and consolidating demand around Ludwigshafen fermentation complexes. The EU F-Gas Regulation's hydrofluorocarbon phase-down is redirecting cold-chain preservative demand toward organic acid alternatives. BASF SE leverages integrated fermentation infrastructure to sustain cost leadership in citric acid derivatives for European pharmaceutical buffer manufacturers.
Brazil
ANVISA restrictions on antibiotic growth promoters in animal nutrition are accelerating propionic and formic acid procurement by integrated poultry and pork producers. São Paulo state feed mills are reformulating rations around organic acid preservatives as regulatory compliance tightens. Polylactic acid feedstock demand from southern bioplastic ventures is pulling polymer-grade lactic acid specifications.
Switzerland
Swissmedic pharmaceutical-grade standards and EP monograph compliance requirements concentrate high-purity acid output in Alpine facilities with dedicated crystallization lines. Basel and Zurich clusters serve European pharmaceutical buffer manufacturers with defined particle size distribution specifications. Jungbunzlauer Suisse AG dominates this premium tier through captive supply of USP-grade citric and lactic acid derivatives.
Vietnam
Food processors in Ho Chi Minh City and Hanoi are expanding direct acidulant procurement from European fermentation facilities to secure lot traceability for export-market clean-label positioning. The country's national food safety regulator is tightening additive approval timelines for imported acidulants. Beverage manufacturers now negotiate volume commitments directly with Ludwigshafen and Blair facilities, bypassing regional chemical traders.
Functional Acids Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fermentation complexes that achieve feedstock-to-derivative cost structures chemical synthesis routes cannot match. Three strategic archetypes dominate: multinational chemical conglomerates with captive biorefinery networks, specialized fermentation houses with pharmaceutical-grade certification depth, and agricultural processors leveraging crop dextrose streams. Capacity expansion and backward integration into fermentation feedstock supply represent the dominant competitive moves.
Among European chemical conglomerates, BASF SE and Evonik Industries AG occupy positions anchored by Ludwigshafen-scale fermentation infrastructure. Cargill, Inc. exemplifies the agricultural processor archetype through its Blair biorefinery integration. Jungbunzlauer Suisse AG sits within the specialized fermentation tier, representing Swiss pharmaceutical-grade certification concentration. These three anchors illustrate how geographic feedstock access and regulatory certification depth stratify competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Inc. |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Jungbunzlauer Suisse AG |
| Evonik Industries AG |
| DuPont de Nemours, Inc. |
| Tate & Lyle PLC |
| Kemin Industries, Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors govern acidulant landed costs across European food processing clusters, concentrating pricing power with Ludwigshafen fermentation complexes that command premium positioning over peripheral chemical synthesis plants while compressing margins for distributors caught between fixed-volume contracts and spot feedstock volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across polymer-grade lactic acid procurement. Price differentiation rests on USP certification tier and volume scale commitments, with pharmaceutical buffer manufacturers least sensitive and commodity food processors most responsive to dextrose-linked index adjustments. Pricing pressure stems from Brazilian feed mills consolidating propionic acid purchasing power. Cost compression in standard food grades is intensifying because Jungbunzlauer's Alpine crystallization lines capture margin separation.
Supply Chain Analysis
Tariff exposure between US corn belt states and Southeast Asian food processors dominates supply chain risk calculus for lactic acid derivatives. Production gravity centers on Germany, the United States, and Switzerland, with raw material dependencies on corn dextrose, molasses feedstock, and pharmaceutical-grade crystallization reagents. Single-source vulnerability concentrates in Swiss EP/USP-certified facilities. Distribution runs through direct procurement contracts displacing regional chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional acids market tracks a cyclical recovery anchored to fermentation feedstock cost normalization following ethanol policy volatility.
For Market Incumbents: Build certification moats around polymer-grade lactic acid specifications. Secure backward integration into corn dextrose supply through captive biorefinery partnerships. Add crystallization capacity in Alpine jurisdictions to defend against Jungbunzlauer's pharmaceutical-grade concentration. ANVISA's antibiotic phase-out timeline threatens feed additive incumbents lacking propionic acid fermentation scale. For New Entrants and Emerging Players: Vietnam's beverage acidification segment offers the most penetrable white-space target for citric acid suppliers. Indonesian clean-label food processors seek lot-traceable acidulant sources bypassing traditional distributor networks. A direct-procurement go-to-market angle with Ho Chi Minh City conglomerates unlocks volume commitments against Ludwigshafen incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates with stranded acid synthesis assets facing biobased cost parity. Five-to-ten-year viability favors fermentation specialists with pharmaceutical certification depth over legacy chemical plants. Watch ECHA REACH dossier revision timelines as inflection indicators for import-filtering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's Blair biorefinery captures corn dextrose cost advantage against spot-market volatility. |
| Pharmaceutical-Grade Certification Investment | Swiss Alpine crystallization lines command USP-grade premium positioning in European buffer markets. |
| Direct Procurement Channel Development | Thai and Vietnamese food processors bypass regional traders for Ludwigshafen volume commitments. |
| Continuous Fermentation Scale-Up | Automated pH control systems cut citric acid batch residence times at industrial biorefineries. |
| Polylactic Acid Feedstock Partnership | Brazilian bioplastic ventures pull polymer-grade lactic acid specifications from southern producers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration filings, and SEC 10-K disclosures. Plant managers at Nebraska and Ludwigshafen fermentation complexes, procurement leads at Southeast Asian food processors, and regulatory affairs directors at pharmaceutical buffer manufacturers provided operating data. Bottom-up capacity modeling triangulates against top-down demand segmentation.
Forecast inputs span grade tier, end-use industry, and regional production hub configurations across the projection horizon. CAGRs derive from segment-level volume trajectories calibrated to fermentation capacity expansion timelines and regulatory approval pathways. Feedstock cost volatility indices and REACH dossier processing rates inform scenario boundaries.
Practitioners should monitor corn dextrose price swings and ECHA purity threshold revisions for early signals of margin compression or supply consolidation. Forecasts reflect assumptions about fermentation technology diffusion and regulatory divergence between FDA and EFSA jurisdictions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Functional Composites Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Thin Film Materials Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Piezoelectric Smart Materials Market