
 Thermal Interface Pads and Material Market | 2026-2036
Thermal Interface Pads and Material Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Interface Pads and Material Market Analysis
Asian specialty chemical producers is decoupling from traditional silicone supply chains as regional refiners expand high-purity polydimethylsiloxane output. Henkel AG & Co. KGaA leverages its adhesives heritage to anchor European automotive thermal bonding contracts. 3M sustains broad patent coverage across fluoropolymer-filled gap pad architectures. Shin-Etsu Chemical dominates upstream silicone monomer supply, giving it cost leverage across pad and sheet derivatives.
Thermal interface pads and materials are engineered compositions—typically silicone elastomers, graphite laminates, or epoxy resins loaded with ceramic or metallic fillers—designed to bridge microscopic air gaps between heat-generating components and dissipating surfaces, with thermal conductivity specifications ranging from one to over ten watts per meter-kelvin depending on filler loading and matrix chemistry. Their primary purpose is reducing thermal contact resistance in electronics assemblies where passive or active cooling alone cannot manage junction temperatures. Silicone pads occupy the largest volume position due to decades of process compatibility with automated dispensing and compression assembly, while phase change materials represent the fastest-expanding category as power electronics packaging shifts toward transient thermal overload protection rather than steady-state dissipation. Graphite sheets command premium positioning in ultra-thin segments where through-plane conductivity must exceed two hundred watts per meter-kelvin across sub-millimeter thicknesses.
The EPA regulates volatile organic compound emissions from solvent-based thermal epoxy manufacturing under Clean Air Act Title V permitting, while the EU REACH framework restricts certain boron nitride and alumina filler sourcing from conflict-affected supply routes. Japan's METI enforces JIS standards on thermal pad flammability ratings for domestic consumer electronics exports. Stakeholders must monitor how emerging PFAS restrictions in the EU and US states reshape filler surface treatment chemistries and force reformulation timelines.
Market Dynamics
Phase change thermal pad procurement by electric vehicle battery pack manufacturers is compressing qualification timelines and forcing material suppliers to validate transient thermal performance under overload conditions rather than steady-state metrics alone.
Growth Catalysts
- EU F-Gas Regulation:Tightening disclosure requirements for imported thermal interface products are accelerating reformulation toward lower-GWP chemistries in European-bound supply chains.
- Automotive electronics corridor:Demand concentration around Stuttgart and Munich is pulling specialized silicone compounding capacity into southern Germany.
- Cell-level heat flux management:EV battery architectures are specifying phase change pads at individual cell interfaces, expanding addressable material volume per pack.
Market Restraints
- High-purity polydimethylsiloxane supply:Asian refinery expansion is creating geographic concentration risk for upstream silicone monomer feedstocks.
- PFAS surface treatment restrictions:Emerging EU and US state-level limits on per- and polyfluoroalkyl substances are forcing reformulation of boron nitride and alumina filler coatings.
- Graphite sheet substitution ceiling:Through-plane conductivity requirements above 200 W/m-K in sub-millimeter formats limit viable material alternatives to synthetic graphite laminates.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for domestic electronics manufacturing are creating localized thermal pad demand outside established automotive corridors.
- Dual carbon goals:China's MIIT mandates for industrial energy efficiency are expanding specification of high-conductivity gap pads in server and power electronics cooling.
- Direct-to-battery OEM contracting:Bypassing traditional tiered distribution to secure long-term supply agreements with cell manufacturers is opening margin capture potential.
Industry Challenges
- REACH compliance timeline compression:Full material disclosure requirements for boron nitride and alumina sourcing are extending qualification cycles by 8-14 months.
- Automated dispensing integration:Legacy compression assembly equipment requires retrofit to handle phase change material viscosity transitions during thermal cycling.
- Cross-border certification stacking:Simultaneous EPA Title V, EU REACH, and Japan METI JIS flammability approvals are multiplying testing overhead for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Interface Pads and Material Market |
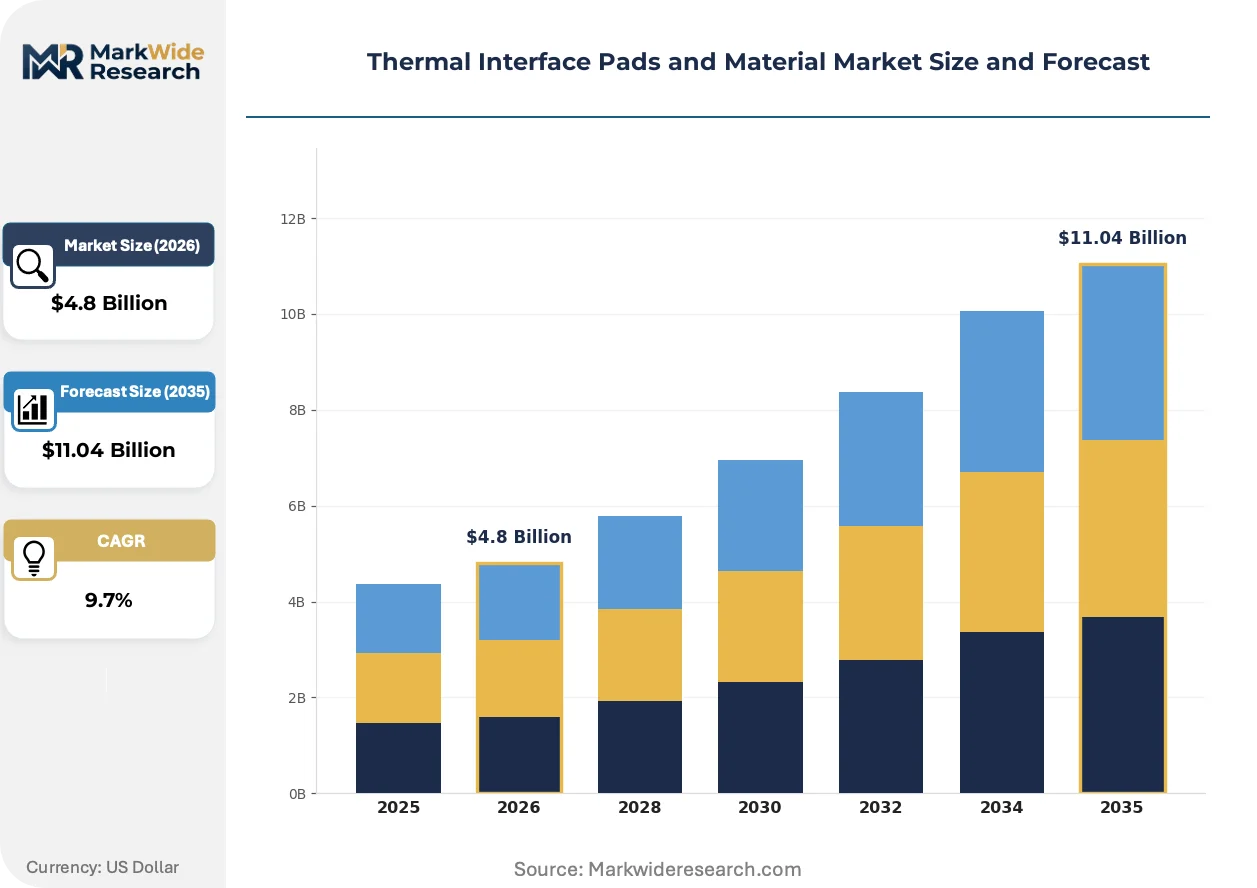
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Pads, Graphite Sheets, Thermal Epoxy, Phase Change Materials End User: Consumer Electronics, Automotive Manufacturers, Aerospace, Medical Devices Application: Power Electronics, LEDs, CPUs, Heat Sinks Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Honeywell International Inc., 3M, Henkel AG & Co. KGaA, Parker Hannifin Corporation, Dow, Laird Technologies Inc., Momentive, Indium Corporation, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Interface Pads and Material Market Emerging Trajectories
Material architectures are converging around transient thermal overload protection as power electronics packaging abandons steady-state dissipation assumptions, while regulatory chemistry restrictions and procurement centralization reshape competitive positioning.
Hybrid silicone-phase change composites are unifying the process compatibility of elastomer pads with the latent heat absorption of paraffin-based phase change materials. Automotive inverter manufacturers in Germany and Japan are qualifying these formulations for 10-30 second overload events. The technology is unifying previously separate pad and phase change categories into single-component solutions, compressing supplier lists and raising technical barriers to specification.
REACH Article 33 disclosure mandates for conflict-affected filler sourcing are extending supply chain due diligence obligations to boron nitride and alumina procurement. The regulation is forcing thermal material suppliers to document smelter and mine origin for ceramic fillers previously treated as commodity inputs. Battery pack manufacturers with EU assembly operations are now requiring batch-level traceability documentation, privileging suppliers with captive or long-term contracted filler supply.
Consolidated procurement by EV battery OEMs is collapsing traditional tiered distribution structures. Cell manufacturers are negotiating direct thermal material supply agreements that bypass module and pack integrators, capturing 12-18 point margin compression previously retained by intermediaries. This pattern is most visible in China and South Korea, where CATL and LG Energy Solution have established approved material lists with locked pricing indexed to silicone monomer futures.
Thermal Interface Pads and Material Market Segmentation
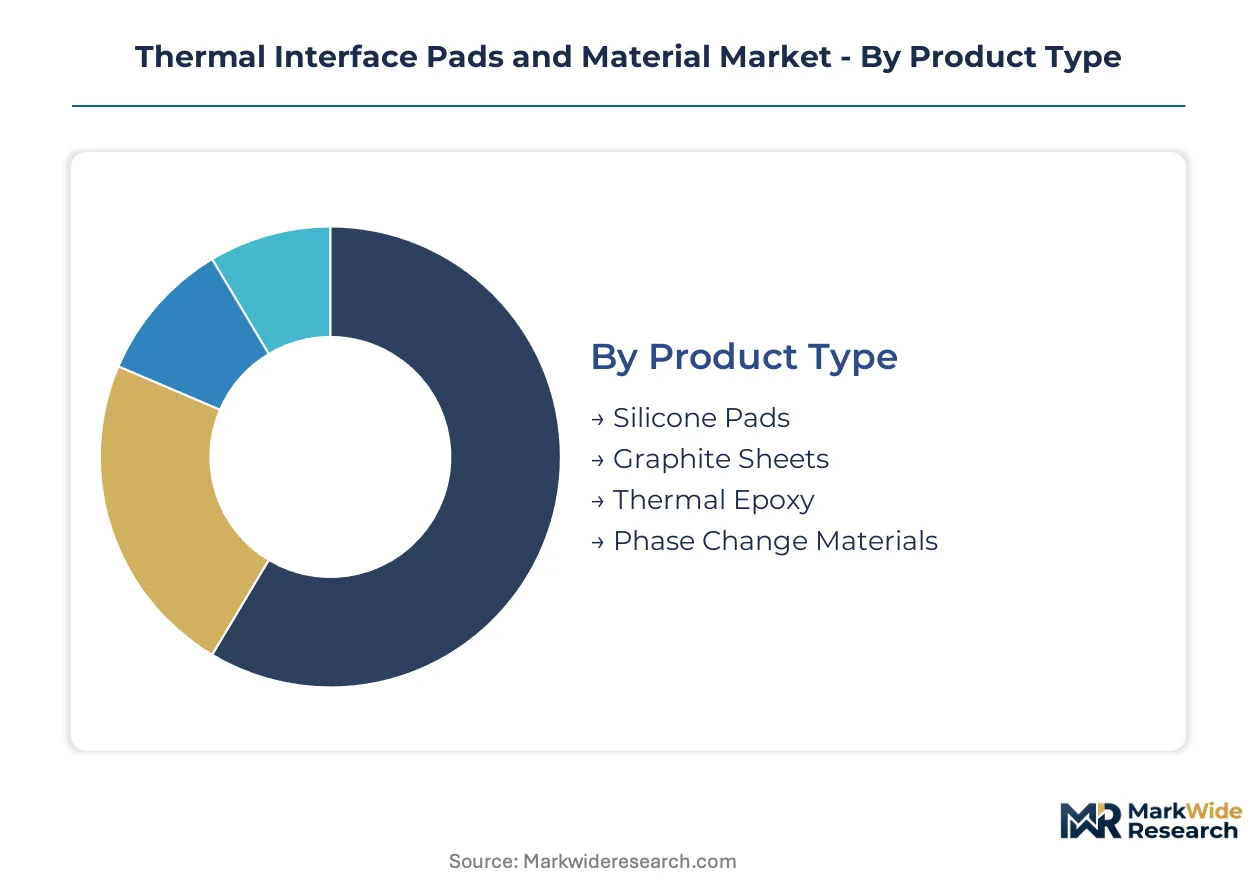
Thermal interface materials fragment across performance specifications, assembly processes, and regulatory exposure profiles. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier competitive positions.
Product Type:
Customization intensity spans from commodity silicone formulations to engineered phase change architectures with proprietary filler loadings.
- Silicone Pads:Polydimethylsiloxane elastomers loaded with boron nitride or alumina ceramic fillers deliver 1-8 W/m-K thermal conductivity with Shore A hardness tunable for automated dispensing compatibility. Automotive electronics corridors in Germany specify these for inverter modules where process repeatability outweighs peak conductivity requirements. REACH Article 33 disclosure mandates are extending qualification cycles for European-bound supply.
- Phase Change Materials:Paraffin or polyolefin matrices transition from solid to viscous flow at 45-65°C, absorbing transient thermal spikes through latent heat rather than steady-state conduction. EV battery pack manufacturers in China and South Korea are compressing validation timelines to secure cell-level thermal protection. Direct OEM contracting is collapsing traditional tiered distribution margins.
- Graphite Sheets:Synthetic graphite laminates achieve 200-400 W/m-K through-plane conductivity in sub-millimeter formats for smartphone and tablet thermal spreading.
- Thermal Epoxy:Two-part adhesive systems bond heat sinks to substrates with permanent structural attachment and moderate thermal transfer.
Most installed capacity flows through silicone pads. Expansion is steepest in phase change materials.
End User:
Customer sophistication ranges from price-sensitive consumer electronics assemblers to aerospace qualification regimes demanding multi-year traceability documentation.
- Automotive Manufacturers:German OEMs and tier-1 suppliers around Stuttgart and Munich specify thermal pads for power electronics packaging with JIS flammability and REACH compliance stacked across certification requirements. Cell-level heat flux management in EV architectures is multiplying material volume per battery pack.
- Consumer Electronics:Smartphone and laptop assemblers prioritize ultra-thin graphite sheets and silicone pads for CPU thermal spreading where thickness constraints dominate specification.
- Aerospace:Satellite and avionics applications demand outgassing-tested materials with decade-long reliability documentation.
- Medical Devices:Imaging equipment and patient-contact electronics require biocompatibility certifications alongside thermal performance validation.
Procurement centralization concentrates in automotive. Volume growth is accelerating fastest in consumer electronics.
Application:
Functional requirements diverge between steady-state dissipation and transient overload protection across electronic assembly nodes.
- Power Electronics:IGBT and SiC inverter modules in electric vehicles specify phase change materials for 10-30 second overload events. Hybrid silicone-phase change composites are unifying previously separate material categories into single-component solutions.
- CPUs:Server and data center processors drive demand for high-conductivity gap pads under China's MIIT energy efficiency mandates.
- LEDs:Solid-state lighting assemblies use silicone pads for thermal management in commercial and residential fixtures.
- Heat Sinks:Passive cooling assemblies employ thermal epoxies for permanent structural bonding.
Specification density peaks in power electronics. Adoption velocity is climbing fastest in CPU cooling.
Thickness:
Manufacturing complexity escalates as thickness diminishes, with ultra-thin formats requiring specialized lamination and defect control.
- Ultra-Thin:Sub-0.5mm synthetic graphite sheets serve smartphone thermal spreading where through-plane conductivity must exceed 200 W/m-K. Japanese and South Korean electronics assemblers dominate procurement.
- Thin:0.5-1.0mm silicone pads balance conformability with thermal performance for consumer electronics CPUs.
- Medium:1.0-3.0mm gap pads accommodate surface irregularities in automotive power module assemblies.
- Thick:Above 3.0mm formats address large-gap industrial and telecom infrastructure applications.
Production volume concentrates in thin and medium formats. Technical differentiation is sharpest in ultra-thin segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive thermal material demand while China dominates upstream silicone feedstock supply, creating a bifurcated procurement geography that reshapes supplier strategies across both regions.
Germany
Stuttgart and Munich anchor Europe's automotive electronics corridor, where EV battery pack manufacturers specify phase change thermal pads for cell-level heat flux management. The EU F-Gas Regulation tightens disclosure requirements for imported thermal interface products, accelerating reformulation timelines. Baden-Württemberg's tier-1 supplier clusters compress qualification cycles to secure localized silicone compounding capacity.
China
CATL and BYD drive procurement centralization through direct thermal material supply agreements that bypass traditional distribution tiers. MIIT dual carbon goals mandate high-conductivity gap pads in server and power electronics cooling applications. The Yangtze River Delta concentrates synthetic graphite sheet production for ultra-thin consumer electronics formats.
United States
EPA Title V permitting governs volatile organic compound emissions from solvent-based thermal epoxy manufacturing in domestic production facilities. Data center operators in Northern Virginia and Texas specify high-performance gap pads under energy efficiency procurement standards. The EPA's emerging PFAS restrictions force reformulation of boron nitride filler surface treatments.
Japan
METI enforces JIS flammability standards on thermal pad exports for consumer electronics, creating certification barriers for non-domestic suppliers. Shin-Etsu Chemical's upstream silicone monomer dominance gives Japanese producers cost leverage across pad derivatives. The Kanto region's electronics assemblers concentrate demand for sub-millimeter graphite sheets in smartphone thermal spreading.
South Korea
LG Energy Solution establishes approved material lists with locked pricing indexed to silicone monomer futures, compressing supplier margins. The country's national chemical regulator aligns with REACH disclosure frameworks for battery-bound thermal material exports. Busan-Ulsan industrial complexes host phase change material qualification labs serving domestic EV battery OEMs.
Thermal Interface Pads and Material Market Vendor Landscape
German and Japanese producers anchor the premium formulation tier; Chinese and South Korean specialists hold volume positions in standardized silicone pad categories. The market structures around three strategic archetypes: diversified chemical conglomerates with adhesives heritage, upstream silicone monomer producers with backward integration into finished pads, and specialized thermal material pure-plays. Competitive moves concentrate on direct-to-OEM contracting bypass and hybrid silicone-phase change composite development.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and 3M occupy positions exemplifying adhesive-heritage entry into automotive thermal bonding. Shin-Etsu Chemical anchors the upstream-integrated archetype, representing cost leverage through captive silicone monomer supply. These three entities illustrate how competitive positioning fragments between formulation expertise and feedstock control.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corporation |
| Dow |
| Laird Technologies Inc. |
| Momentive |
| Indium Corporation |
| Shin-Etsu Chemical |
| Others |
Supply Flow & Price Mechanics
EV battery OEM procurement centralization in China and South Korea anchors the dominant pricing model around long-term offtake contracts indexed to silicone monomer futures, compressing spot market liquidity and amplifying supplier margin pressure during feedstock volatility.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for synthetic graphite sheets, forcing Japanese and South Korean producers to differentiate through ultra-thin lamination precision. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with automotive OEMs least price-sensitive due to stacked REACH and JIS compliance requirements. Cost compression in commodity silicone pads is intensifying because Asian refinery expansion has saturated standardized formulations. Consumer electronics assemblers exhibit highest price sensitivity, prioritizing thickness conformance over thermal conductivity specifications.
Supply Chain Analysis
Container freight rates from Asian specialty chemical hubs to European automotive corridors directly determine landed cost competitiveness for phase change material suppliers. Feedstock supply concentrates in China, Japan, and Germany, with high-purity polydimethylsiloxane monomer, boron nitride ceramic fillers, and synthetic graphite precursor laminates forming critical input dependencies. Single-source vulnerability runs through Shin-Etsu Chemical's upstream silicone monopoly, exposing downstream pad manufacturers to allocation risk during semiconductor-grade demand spikes. Distribution runs through direct OEM contracting that bypasses traditional electronics distributors, collapsing tiered margin structures previously retained by intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where EV battery architectures specifying cell-level phase change protection have shifted procurement toward transient thermal performance validation, privileging suppliers with captive filler supply and accelerated qualification capabilities.
For Market Incumbents: Deploy backward integration into boron nitride and alumina filler supply to defend against REACH Article 33 disclosure mandates extending qualification cycles. Secure long-term silicone monomer offtake with Yangtze River Delta refiners before capacity absorption tightens feedstock availability. Deepen hybrid silicone-phase change R&D to unify previously separate material categories and compress competitor specification windows. For New Entrants and Emerging Players: The premium-economy price gap in automotive thermal materials creates entry space for mid-tier suppliers offering REACH-compliant silicone pads without JIS certification overhead. Target India's PLI scheme electronics manufacturing clusters where localized thermal pad demand lacks established supplier relationships. Pursue direct contracting with emerging EV battery OEMs outside CATL and LG Energy Solution approved material lists. For Investors and Strategic Acquirers: Chemical conglomerates with adhesives heritage are the most active acquirer in this space, seeking thermal material capabilities to complement existing automotive bonding portfolios. Five-to-ten year viability hinges on PFAS-free filler surface treatment IP and conflict-affected sourcing documentation infrastructure. Monitor EU F-Gas Regulation enforcement actions as the inflection signal for reformulation investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Fillers | Captive boron nitride supply secures REACH compliance documentation for European automotive contracts. |
| Hybrid Composite Development | Silicone-phase change unification raises technical barriers against commodity pad competitors. |
| Direct-to-OEM Contracting | Bypassing tiered distribution captures margin compression previously retained by module integrators. |
| PFAS-Free Surface Treatment | Eliminating perfluoroalkyl coatings ensures continued EU and US state market access. |
| Regional Compounding Capacity | Localized silicone formulation in Stuttgart corridor reduces logistics exposure and qualification timelines. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermal material procurement leads at EV battery OEMs, silicone compounding plant managers, and automotive tier-1 supplier quality engineers with secondary validation against customs trade data, EPA Title V permitting records, and ECHA REACH registration databases. Bottom-up segment sizing triangulated against top-down chemical industry association reports.
Segment-weighting across product type, end user, application, and thickness dimensions drove volume and value allocation throughout the forecast period. CAGRs derived from elasticity modeling against EV battery production forecasts and consumer electronics assembly volumes. Industry-specific inputs included silicone monomer futures pricing curves and phase change material qualification timeline compression observed in CATL and LG Energy Solution supplier audits.
Caveats apply where PFAS regulatory scope expansion or conflict-affected filler sourcing disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Functional Composites Market
Functional Materials
Functional Acids Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Thin Film Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Flexible Thin Film Market