
 UHMWPE for Li-Battery Market | 2026-2036
UHMWPE for Li-Battery Market Size, Share, and Industry Trends Forecast 2026-2036
UHMWPE for Li-Battery Market Insights
A shift from outsourced separator supply toward captive in-house production is repositioning procurement strategies across the lithium-ion value chain. Celanese leverages its polymer expertise to anchor North American supply security for battery-grade UHMWPE. Braskem competes through backward integration into ethylene feedstock, sustaining cost advantages in high-molecular-weight resin production. Asahi Kasei dominates Asian separator markets with specialized biaxial stretching technology that extends film uniformity at sub-20-micron gauges.
Ultra-high molecular weight polyethylene for lithium-ion batteries refers to a linear, unbranched polyethylene with molecular weights exceeding 3.5 million g/mol, processed into microporous membranes through solvent extraction or mechanical stretching to achieve pore sizes of 0.03-0.1 microns for ion transport. The material serves as a critical safety barrier between anode and cathode, preventing internal short circuits while permitting lithium-ion diffusion at rates exceeding 10^-4 S/cm electrolyte conductivity. Cathode materials command the largest product-type position due to high-voltage cycling demands, while solid-state delivery mode segments attract disproportionate R&D investment as automotive OEMs pursue thermal runaway elimination. Electric vehicles anchor application demand, though energy storage systems represent the fastest-growing margin pool as grid-scale deployments multiply.
FDA biocompatibility standards for implantable power sources, EPA perfluorinated substance restrictions affecting alternative separator chemistries, and China's GB/T standards for lithium-ion battery safety collectively elevate UHMWPE purity requirements and traceability protocols. The EU Battery Regulation's recycled-content mandates and carbon-footprint disclosure rules are reshaping material certification pathways for European-bound cell production. Stakeholders must monitor how solid-state electrolyte maturation alters separator thickness specifications and whether polymer producers can secure qualified resin supply ahead of gigafactory commissioning timelines.
Market Dynamics
Battery-grade UHMWPE separator production is consolidating around captive resin supply chains as gigafactory operators demand qualified material ahead of commissioning timelines, compressing the window for polymer producers to achieve certification.
Growth Catalysts
- EU Battery Regulation:Recycled-content mandates and carbon-footprint disclosure rules are accelerating material traceability investments across European-bound cell production, pulling qualified UHMWPE supply toward certified pathways.
- Solid-state battery R&D:Automotive OEMs pursuing thermal runaway elimination are disproportionately funding separator thickness reduction programs, expanding addressable resin demand for sub-12-micron membrane specifications.
- East Asian manufacturing corridors:South Korea's battery production belt and China's Jiangsu province are concentrating cathode-active-material processing, creating localized pull for high-purity separator feedstock.
Market Restraints
- Ethylene feedstock volatility:High-molecular-weight resin production depends on specialized ethylene supply chains concentrated in Gulf Coast petrochemical complexes, exposing margin structures to hydrocarbon price swings.
- Qualified supplier scarcity:Only a limited number of polymer producers have achieved battery-grade purity certification, creating single-source risk for separator manufacturers scaling production.
- Aramid fiber substitution:Ceramic-coated aramid separators are capturing niche share in high-voltage cathode applications where dimensional stability exceeds UHMWPE performance limits.
Strategic Opportunities
- Energy storage systems:Grid-scale battery deployments are multiplying faster than electric vehicle demand, creating a margin-rich application segment with less stringent cycle-life requirements.
- North American reshoring:IRA domestic content incentives are repositioning separator supply geography, opening qualification pathways for resin producers with US-based polymerization assets.
- Dual-carbon policy alignment:China's MEE emission intensity targets are accelerating low-carbon ethylene sourcing, rewarding producers with integrated renewable feedstock access.
Industry Challenges
- Electrolyte compatibility testing:Each new electrolyte formulation requires 18-24 month validation cycles for separator wettability and ionic conductivity, compressing product development timelines.
- Membrane thickness standardization:Absence of unified IEC testing protocols for sub-20-micron gauges forces redundant certification across customer specifications, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHMWPE for Li-Battery Market |
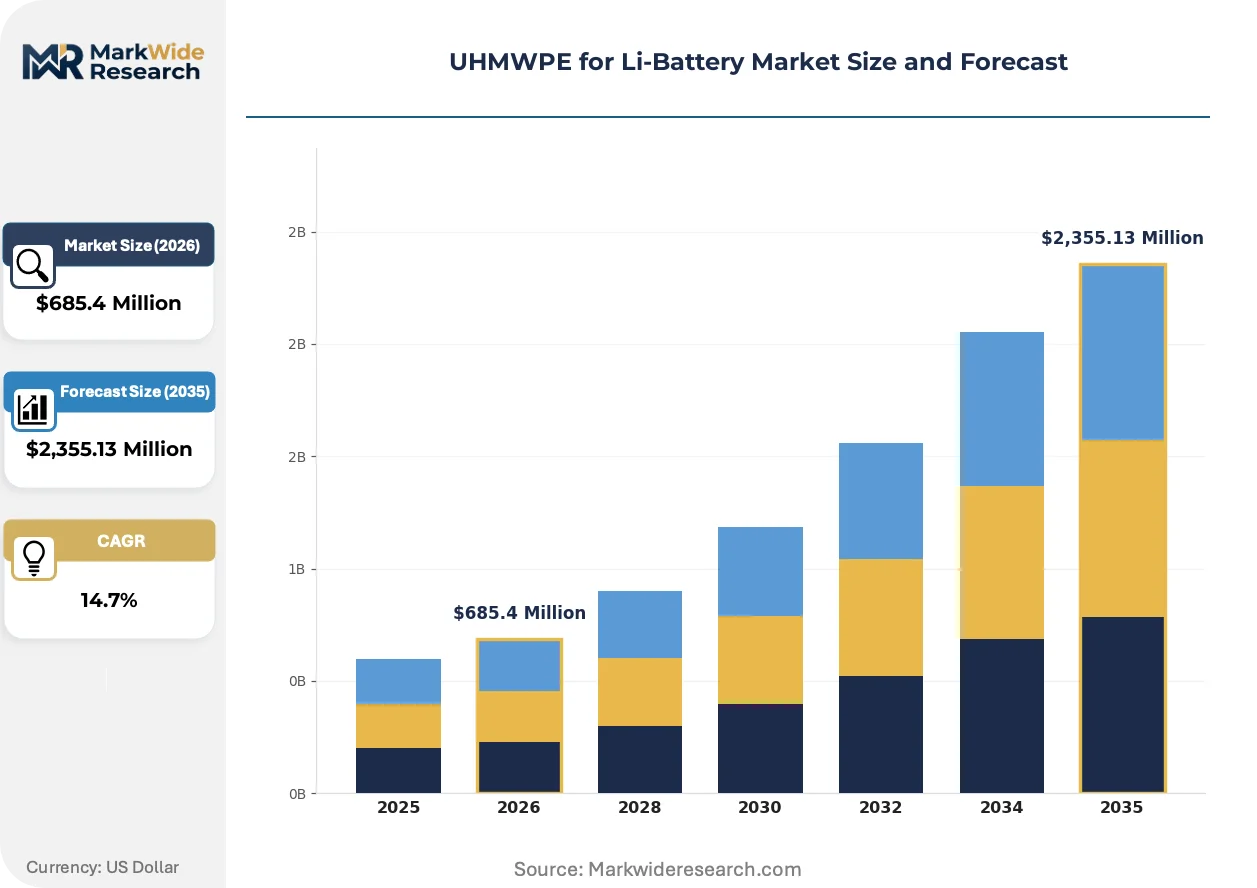
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,355.13 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anode Materials, Cathode Materials, Electrolytes, Conductive Additives Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Power Tools Delivery Mode: Solid State, Liquid, Gel, Composite End User: Aerospace, Automotive OEMs, Telecommunications, Industrial Equipment |
| Companies Covered | Celanese, Braskem, KPIC, LyondellBasell, Asahi Kasei, Sinopec Beijing Yanshan, Mitsui Chemicals, Shanghai Lianle, Sinopec Yangzi Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHMWPE for Li-Battery Market Trends and Innovations
Separator manufacturing is bifurcating between wet-process solvent extraction and dry-process mechanical stretching, with equipment suppliers racing to deliver biaxial stretching systems capable of sub-15-micron uniformity at gigafactory scale.
Wet-process solvent extraction technology is modularizing separator production lines, enabling cell manufacturers to replicate standardized membrane specifications across multiple plant locations without requalifying resin sources. Korean equipment vendors are shipping turnkey extraction-skid packages to European gigafactory sites, collapsing the traditional 36-month process development cycle into 18-month replication windows. This modularity is compressing the competitive advantage of incumbent separator specialists with proprietary solvent systems.
China's NMPA battery safety standards are tightening thermal-shutdown temperature requirements for separators used in nickel-rich cathode configurations, forcing membrane producers to narrow pore-size distributions below 0.05-micron variance. The regulation is accelerating adoption of ceramic-coating layers applied to UHMWPE substrates, adding process complexity but enabling compliance with 150°C dimensional stability mandates. High-voltage cathode segments in Jiangsu and Fujian provinces are absorbing the first qualified volumes.
Automotive OEMs are consolidating separator procurement through direct material qualification rather than delegating specification to cell suppliers, compressing the vendor base to resin producers with documented carbon-intensity footprints. This concentration is displacing traditional distributor channels in European and North American supply chains, with BMW and Volkswagen implementing approved-supplier lists that bypass incumbent trading relationships. The shift is most visible in German and Hungarian cell production clusters serving premium electric vehicle platforms.
UHMWPE for Li-Battery Market Segmentation
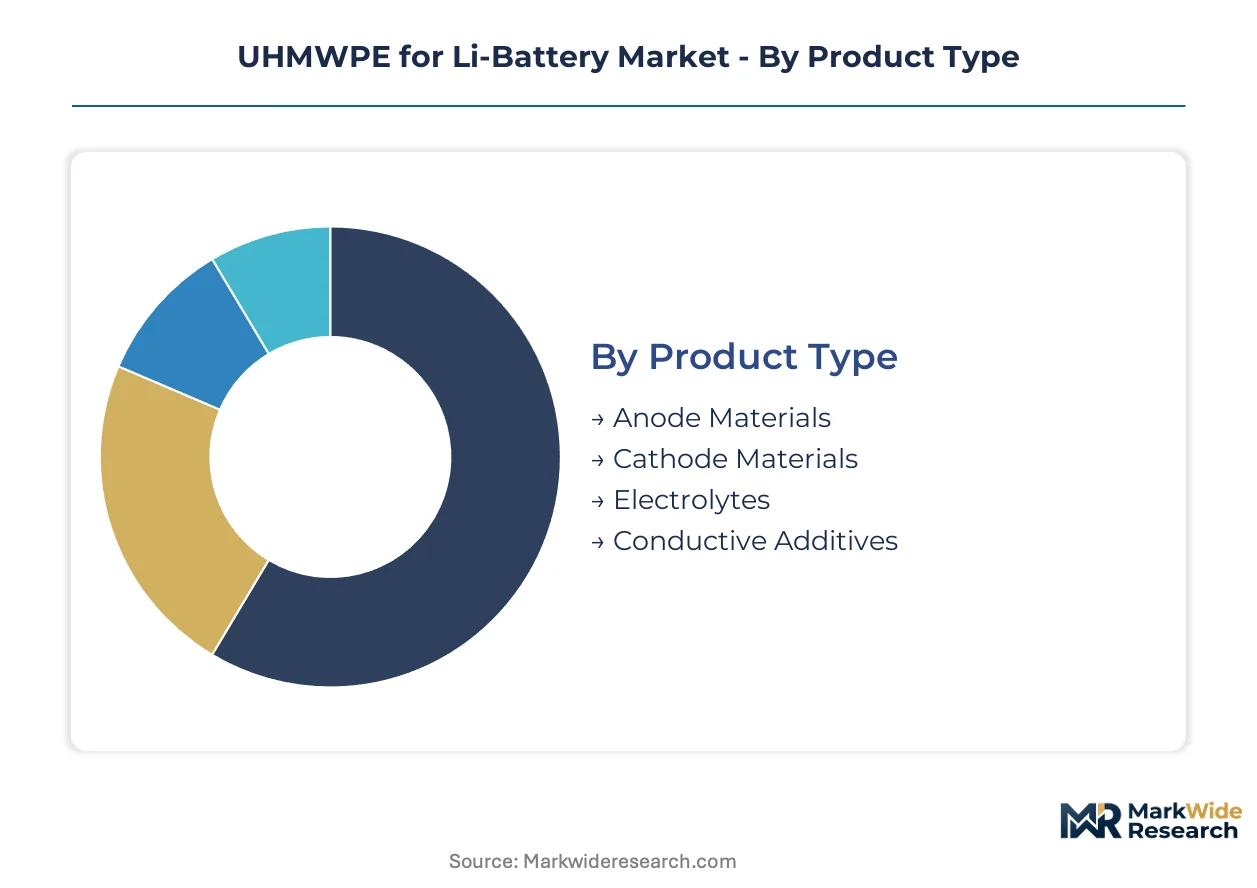
Separator specification tiers determine resin qualification pathways and pricing power across the lithium-ion value chain. Each segmentation axis reveals distinct procurement patterns, from cathode voltage requirements to solid-state electrolyte compatibility thresholds.
Product Type:
Separator substrate chemistry aligns with electrode voltage windows and cycling stability demands.
- Cathode Materials:UHMWPE membranes for high-voltage cathodes require sub-20-micron gauges with ceramic coating layers to meet NMPA thermal-shutdown mandates. Jiangsu province cell producers are absorbing the first qualified volumes for nickel-rich configurations. Mature deployment sits with Cathode Materials. Newer deployment is concentrated in Conductive Additives.
- Anode Materials:Silicon-anode compatibility drives pore-size optimization toward 0.03-micron lower bounds to prevent dendrite penetration during fast-charge cycles. South Korean gigafactory operators specify anode-side separators separately from cathode-facing membranes.
- Electrolytes:Separator wettability testing against carbonate-based formulations dominates validation protocols.
- Conductive Additives:Carbon-coated UHMWPE variants are emerging for solid-state cell architectures.
Volume concentration favors cathode-facing membranes due to higher voltage stress and regulatory scrutiny.
Application:
End-use thermal profiles dictate separator thickness and coating specifications.
- Electric Vehicles:Automotive OEMs enforce 150°C dimensional stability minimums through direct material qualification rather than cell-supplier delegation. BMW and Volkswagen approved-supplier lists bypass traditional distributor channels in European production clusters. Mature deployment sits with Electric Vehicles. Newer deployment is concentrated in Energy Storage Systems.
- Energy Storage Systems:Grid-scale deployments multiply faster than automotive demand, creating a margin-rich segment with relaxed cycle-life requirements but escalating fire-safety codes from FERC and national grid operators.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize thin-gauge flexibility over thermal extremes.
- Power Tools:High-discharge-rate cycling drives puncture-resistance specifications for contractor-grade equipment.
Margin structures favor stationary storage where certification overhead is lower and volume commitments are longer-term.
Delivery Mode:
Electrolyte physical state determines separator porosity and ionic conductivity targets.
- Solid State:Automotive OEMs disproportionately fund separator thickness reduction programs toward sub-12-micron specifications to compress cell stack resistance. Solid-state R&D pipelines are expanding addressable resin demand for ultra-thin membrane substrates. Mature deployment sits with Liquid. Newer deployment is concentrated in Solid State.
- Liquid:Conventional carbonate electrolyte systems dominate current production volumes with established wettability validation protocols.
- Gel:Polymer-gel electrolytes require modified pore structures for gel-phase penetration.
- Composite:Hybrid solid-liquid architectures are emerging for transition-phase cell designs.
Electrolyte compatibility testing cycles of 18-24 months per new formulation compress product development timelines across all delivery modes.
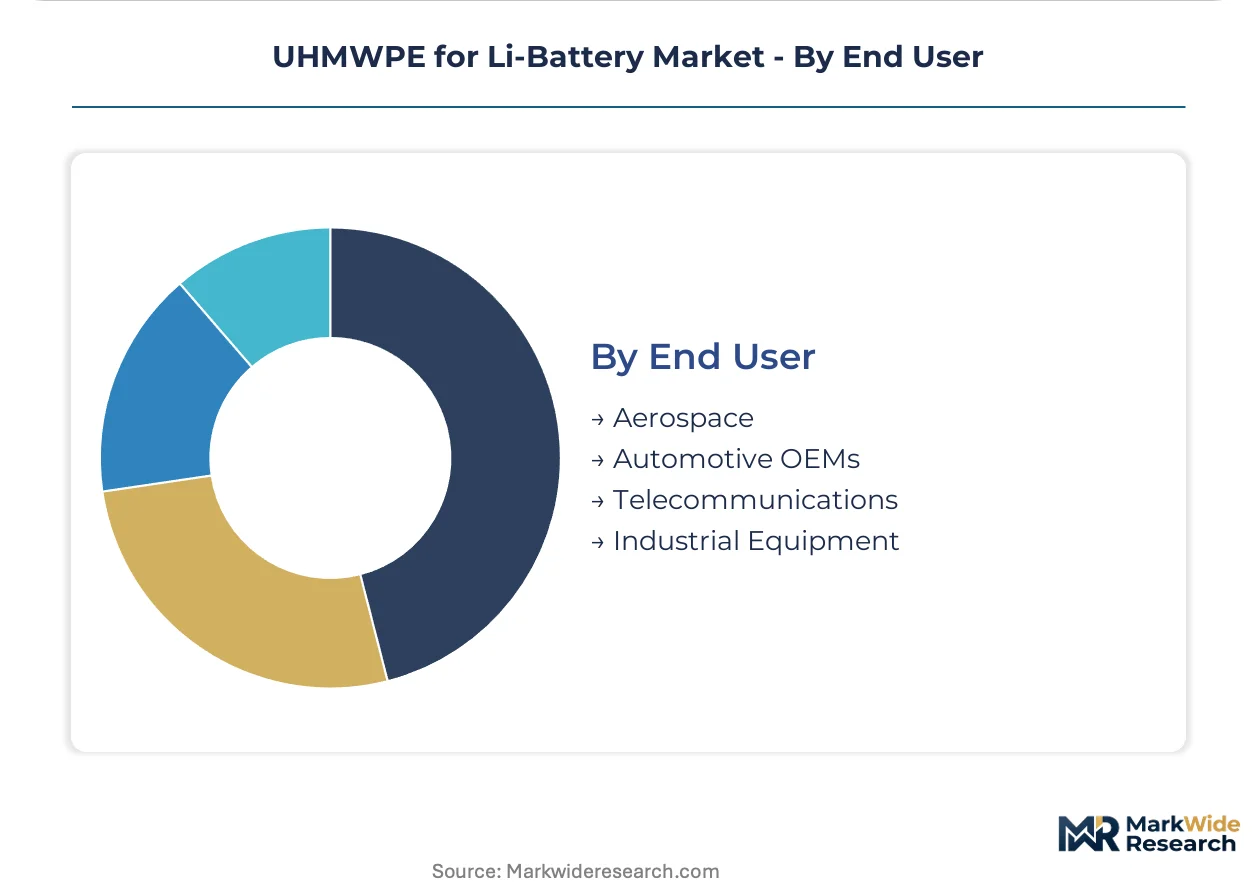
End User:
Industry-specific safety certification tiers segment procurement authority and specification stringency.
- Automotive OEMs:Direct material qualification with documented carbon-intensity footprints is displacing distributor channels. IRA domestic content incentives are repositioning separator supply geography toward North American resin producers with US-based polymerization assets. Mature deployment sits with Automotive OEMs. Newer deployment is concentrated in Aerospace.
- Aerospace:FAA and EASA battery safety standards for electric aircraft impose the most stringent puncture-resistance and thermal-runaway containment specifications, with qualification timelines extending 36-48 months.
- Telecommunications:Backup power systems for 5G infrastructure prioritize calendar life over cycle count.
- Industrial Equipment:Forklift and material-handling applications drive demand for high-throughput charging compatibility.
Procurement authority concentration favors automotive and aerospace segments where OEMs bypass cell suppliers for direct separator specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ethylene feedstock availability anchors geographic production patterns for battery-grade UHMWPE resin. Gulf Coast petrochemical complexes supply North American polymerization assets, while East Asian naphtha crackers feed high-molecular-weight production lines. Regional qualification timelines diverge based on gigafactory commissioning schedules and regulatory certification pathways.
United States
IRA domestic content incentives are repositioning separator supply geography toward resin producers with US-based polymerization assets. EPA perfluorinated substance restrictions affect alternative separator chemistries, elevating UHMWPE purity requirements. Texas and Louisiana Gulf Coast complexes concentrate ethylene feedstock supply for high-molecular-weight resin production.
China
Jiangsu province cell producers are absorbing the first qualified volumes for nickel-rich cathode configurations. NMPA battery safety standards tighten thermal-shutdown temperature requirements, forcing membrane producers to narrow pore-size distributions. The Yangtze River Delta manufacturing corridor concentrates cathode-active-material processing and separator feedstock demand.
Germany
BMW and Volkswagen approved-supplier lists bypass traditional distributor channels in European production clusters. EU Battery Regulation recycled-content mandates and carbon-footprint disclosure rules accelerate material traceability investments. Hungarian and German cell production sites serving premium electric vehicle platforms concentrate procurement authority.
South Korea
Korean equipment vendors ship turnkey extraction-skid packages to European gigafactory sites, collapsing traditional process development cycles. MFDS alignment with international battery safety standards streamlines export qualification for domestic separator manufacturers. The battery production belt between Seoul and Busan concentrates cell manufacturing and resin qualification testing.
Japan
METI funding for solid-state battery R&D disproportionately supports separator thickness reduction programs toward sub-12-micron specifications. JIS standards for lithium-ion component safety elevate traceability protocols for European-bound exports. Kansai region chemical producers maintain specialized biaxial stretching technology for sub-20-micron membrane uniformity.
UHMWPE for Li-Battery Market Competitive Landscape
Global majors compete with regional champions across resin qualification and separator manufacturing technology. The vendor base stratifies between integrated petrochemical conglomerates with captive ethylene supply and specialized membrane fabricators with proprietary stretching equipment. Three archetypes dominate: Gulf Coast-based polymer producers with backward integration into feedstock, East Asian equipment-integrated specialists with biaxial stretching mastery, and Chinese state-affiliated resin producers with domestic gigafactory relationships. Competitive moves center on captive resin supply chain construction and direct automotive OEM qualification bypassing cell manufacturer intermediaries.
Among integrated polymer producers, Celanese and Braskem exemplify the feedstock-anchored archetype with North American ethylene access, while Asahi Kasei occupies a position representing East Asian equipment-integrated specialization. These three companies illustrate how geographic feedstock advantages and process technology differentiation create distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Celanese |
| Braskem |
| KPIC |
| LyondellBasell |
| Asahi Kasei |
| Sinopec Beijing Yanshan |
| Mitsui Chemicals |
| Shanghai Lianle |
| Sinopec Yangzi Petrochemical |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM direct qualification programs anchor pricing power for certified UHMWPE resin producers, compressing distributor margins while elevating contract-based long-term offtake structures for gigafactory-scale volumes.
Pricing Analysis
Warranty and technical service bundling separates premium resin tiers from unbundled commodity supply, with automotive OEMs demanding 18-24 month electrolyte compatibility validation as standard inclusion. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and carbon-intensity documentation, with IRA domestic content incentives elevating North American supply premiums. Pricing pressure stems from ethylene feedstock volatility at Gulf Coast complexes, squeezing margin structures for non-integrated producers. Energy storage system buyers exhibit highest price sensitivity due to relaxed cycle-life requirements, while aerospace qualification timelines render that segment least sensitive to unit cost.
Supply Chain Analysis
Battery-grade purity certification gates access to qualified supplier lists, with only limited polymer producers achieving NMPA, EU Battery Regulation, and automotive OEM standards simultaneously. Resin supply concentrates in China, South Korea, and the United States, with Jiangsu province cell producers and Texas Gulf Coast ethylene complexes anchoring opposite ends of the value chain. High-molecular-weight resin production draws from specialized ethylene feedstock, ceramic coating precursor chemicals, and precision biaxial stretching equipment. Single-source vulnerability pervades the qualified supplier base, as separator manufacturers scaling production face constrained alternative sources. Distribution runs through direct automotive OEM procurement channels, displacing traditional trading relationships in European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified resin scarcity props pricing premiums across the UHMWPE separator value chain, with certification bottlenecks limiting supply expansion faster than gigafactory demand growth.
For Market Incumbents: Deepen backward integration into ethylene feedstock to defend margin structures against Gulf Coast petrochemical price swings. Secure captive resin supply ahead of competitor qualification timelines, while accelerating ceramic-coating layer R&D to meet NMPA thermal-shutdown mandates for nickel-rich cathode configurations. Aramid fiber substitution in high-voltage applications demands dimensional stability performance upgrades. For New Entrants and Emerging Players: Energy storage system buyers represent the most penetrable white-space segment, with grid-scale deployments multiplying faster than automotive demand and lower certification overhead enabling faster market entry. North American IRA domestic content incentives create geographic arbitrage opportunity for resin producers with US-based polymerization assets. Target direct qualification with stationary storage integrators as the primary go-to-market pathway. For Investors and Strategic Acquirers: The window for entry favors integrated petrochemical conglomerates with captive ethylene supply and existing polymer expertise, as qualification timelines exceed typical venture capital horizons. Acquisition candidates include regional champions with established automotive OEM relationships and documented carbon-intensity footprints. Solid-state battery separator thickness reduction programs toward sub-12-micron specifications signal inflection demand for ultra-thin membrane substrate capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Gulf Coast petrochemical complex access insulates margin structures from hydrocarbon volatility. |
| Ceramic Coating Layer R&D Investment | NMPA thermal-shutdown mandates for nickel-rich cathodes require 150°C dimensional stability compliance. |
| Direct Automotive OEM Qualification | BMW and Volkswagen approved-supplier lists bypass traditional distributor channels in European production clusters. |
| North American Polymerization Asset Expansion | IRA domestic content incentives reposition separator supply geography toward US-based resin producers. |
| Solid-State Separator Thickness Reduction Program | Automotive OEM R&D funding expands addressable resin demand for sub-12-micron membrane specifications. |
Research Methodology
Independent corroboration across resin plant managers, separator manufacturing technical directors, automotive OEM procurement leads, and gigafactory supply chain executives underwrites the qualitative findings in this study. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings of listed petrochemical conglomerates, NMPA battery safety standard documentation, and EU Battery Regulation impact assessments establishes demand-side and supply-side triangulation. Bottom-up resin production estimates and top-down gigafactory capacity absorption models converge on volume figures.
Comparable-period anchoring to historical cathode-active-material processing expansion and separator qualification timeline data structures the forecast window across the analysis window. Segmentation dimensions modeled include product type, application thermal profile, delivery mode electrolyte compatibility, and end-user certification tier. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity commissioning schedules. Solid-state battery R&D pipeline maturation and ceramic coating adoption rates constitute key industry-specific forecast inputs.
Revisions become necessary when solid-state electrolyte commercialization timelines accelerate, qualified supplier counts expand beyond current scarcity levels, or ethylene feedstock cost structures shift materially. Forecasts reflect assumptions regarding certification timeline stability and gigafactory commissioning schedule adherence. A model refresh is warranted upon material change in NMPA or EU Battery Regulation separator performance mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Smart Card Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Functional Composites Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Thin Film Materials Market