
 Flexible Thin Film Market | 2026-2036
Flexible Thin Film Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Thin Film Market Foresight
Polymer substrate replacement of rigid glass is consolidating cost structures across roll-to-roll manufacturing lines. First Solar leverages cadmium telluride deposition expertise to sustain utility-scale cost advantages. Kaneka Corporation anchors amorphous silicon production in Japanese domestic supply chains. Heliatek competes in organic photovoltaic segments through specialized tandem cell architectures.
Flexible thin film denotes electronically functional layers deposited on pliable polymer or metal foil substrates, typically achieving thicknesses below 100 micrometers through vacuum deposition, solution processing, or printing techniques. These structures enable conformal integration into curved surfaces, powering applications from solar harvesting to biometric sensing where mechanical compliance is essential. Photovoltaic Films currently lead value generation, while Perovskite technology segments attract concentrated R&D investment due to rapid efficiency improvements. Wearable Devices applications command premium positioning within Consumer Electronics channels, whereas Medical Devices segments prioritize biocompatibility certifications over cost minimization.
ISO 13485 governs medical device quality systems, REACH restricts hazardous substance migration in European supply chains, and China's GB standards mandate flame retardancy in consumer electronics substrates. Regulatory divergence between jurisdictions forces manufacturers to maintain parallel certification tracks, elevating compliance costs for cross-border suppliers. Stakeholders must evaluate whether regional certification investments justify market access against concentrated production economics.
Market Dynamics
Roll-to-roll manufacturing consolidation is compressing unit economics while China's GB standards and dual carbon goals force parallel certification tracks that fragment supplier compliance investments across East Asian production clusters.
Growth Catalysts
- Perovskite tandem architectures:Rapid efficiency gains in organic photovoltaic segments pull R&D capital from conventional silicon deposition methods. Laboratory breakthroughs translate into pilot line investments.
- REACH substance restrictions:European supply chain compliance mandates accelerate substitution of halogenated flame retardants in polymer substrates, favoring suppliers with pre-certified material libraries.
- Wearable device integration:Seoul's display technology corridor concentrates demand for conformal power harvesting layers in biometric monitoring applications.
Market Restraints
- Indium supply concentration:Transparent conductive oxide deposition depends on Chinese refined indium output, creating price volatility exposure for sputtering target consumers.
- Barrier film technical limits:Water vapor transmission rates below 10^-6 g/m²/day remain difficult to achieve in single-layer polymer structures without ceramic nanolaminates.
- ISO 13485 certification timelines:Medical device substrate qualification extends commercialization cycles by 18-24 months versus consumer electronics channels.
Strategic Opportunities
- India BIS standards alignment:Domestic solar manufacturing incentives under PLI schemes create localized demand for flexible photovoltaic backsheet materials.
- Building-integrated photovoltaics:Architectural facade applications require large-area deposition capabilities that roll-to-roll lines can scale faster than rigid panel assembly.
- Biodegradable substrate convergence:Cellulose nanofiber and polylactic acid films merge sustainability positioning with mechanical compliance for disposable medical sensors.
Industry Challenges
- Vacuum deposition technician scarcity:Atomic layer deposition and chemical vapor deposition process engineering expertise concentrates in Japanese and South Korean equipment vendor ecosystems.
- Legacy flat panel display equipment retrofit:Gen 8.5+ glass handling infrastructure requires substantial modification for polymer web tension control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Thin Film Market |
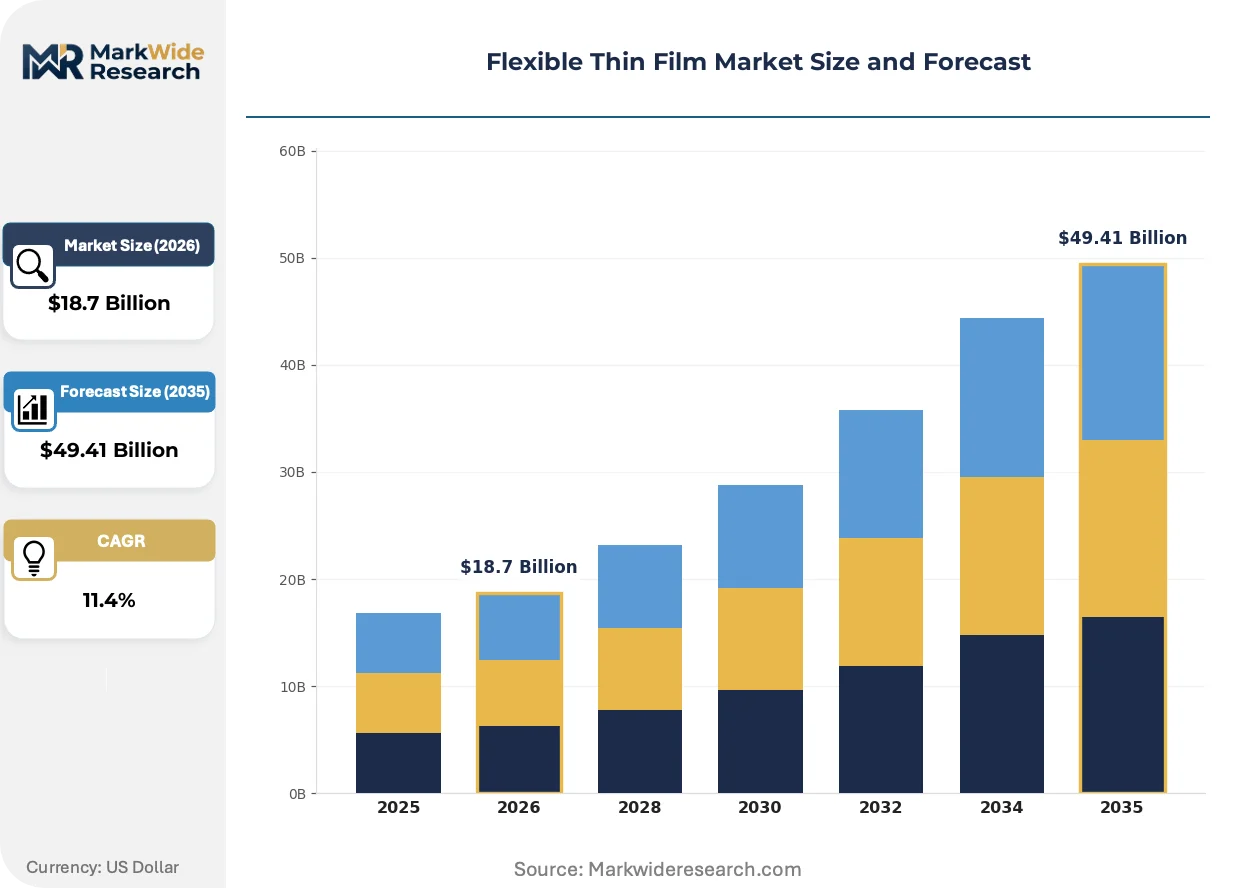
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Films, Organic Light Emitting Diodes, Thermoelectric Films, Flexible Batteries, Sensors, Conductive Films Technology: Organic Electronics, Amorphous Silicon, Cadmium Telluride, Copper Indium Gallium Selenide, Perovskite, Nanomaterials Application: Wearable Devices, Smart Cards, Electronic Paper, Medical Devices, Security Systems, Consumer Electronics End User Industry: Consumer Goods, Aerospace, Defense, Telecommunications, Energy Storage, Biotechnology |
| Companies Covered | Vital Materials, Umicore, Indium Corporation, JX Nippon Mining & Metals, Kaneka Corporation, First Solar, Ascent Solar Technologies, Hanergy Thin Film Power Group, Heliatek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Thin Film Market Shifts & Advancements
Active materials deposition techniques are bifurcating between high-throughput solution processing and precision vacuum methods, with equipment suppliers racing to bridge the throughput-quality tradeoff in tandem cell manufacturing.
Perovskite-silicon tandem structures are absorbing the majority of venture funding in next-generation photovoltaic architectures. Automotive roof-integrated solar suppliers in Germany and Japan are qualifying these stacks for 25-year automotive warranties. The technology is absorbing market share projections that previously favored pure organic photovoltaics.
China's MIIT energy efficiency mandates for electronics manufacturing are tightening power consumption limits for vacuum deposition equipment. Domestic tool vendors must certify to revised GB standards by 2026 or face exclusion from state-backed fab construction projects. Korean display material suppliers are pre-emptively redesigning heating elements to maintain access to cross-border equipment sales.
Medical device OEMs now specify biocompatibility certification at the substrate level rather than finished device level, compressing supplier qualification timelines. ISO 10993 testing documentation transfers directly from film manufacturers to downstream converters in Minnesota and Massachusetts medical technology clusters. This pattern shortens procurement cycles for Class II wearable diagnostic patches while raising barriers for uncertified substrate entrants.
Flexible Thin Film Market Segmentation
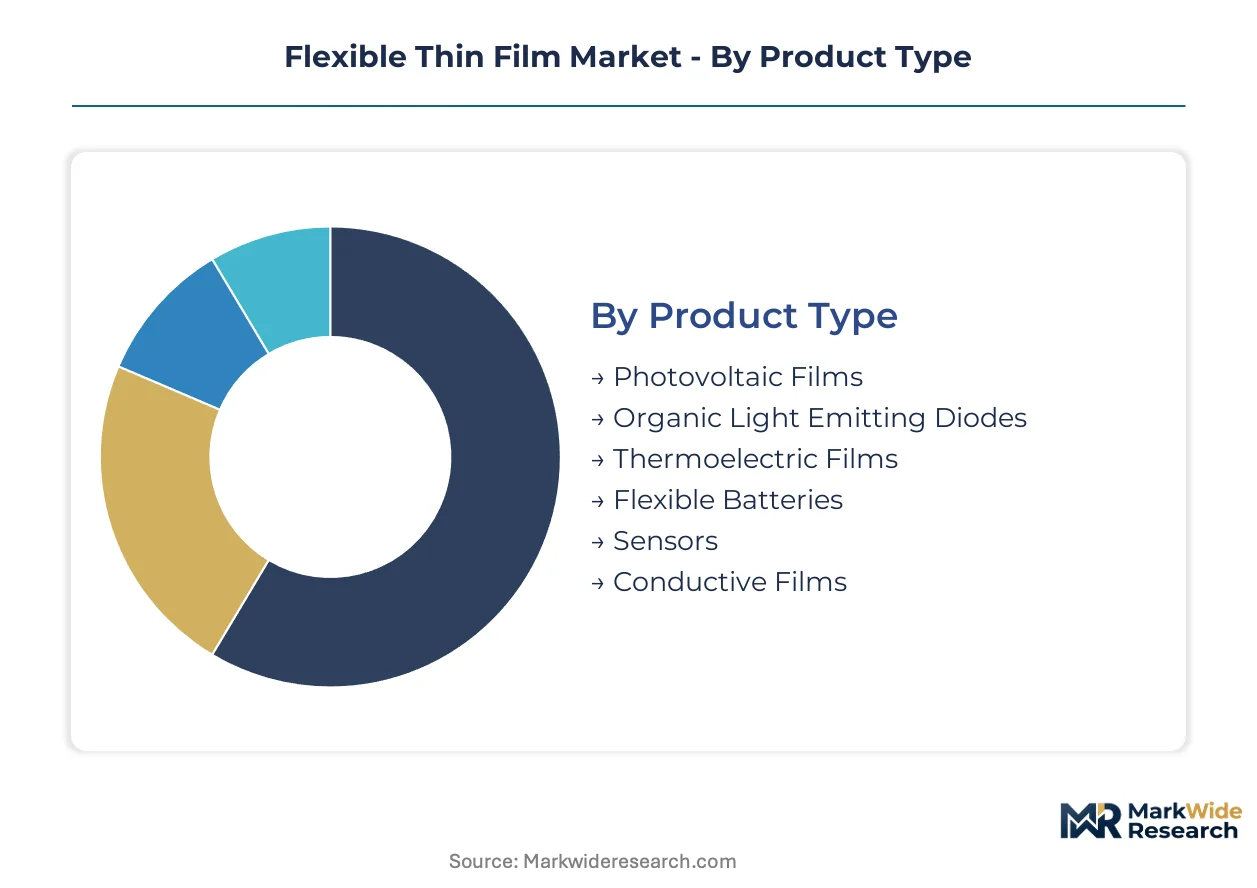
Flexible thin film manufacturers configure production assets around deposition chemistry and substrate handling requirements. Segmentation reveals where roll-to-roll infrastructure investments concentrate versus batch processing niches.
Product Type:
Supply concentration clusters around photovoltaic and display-grade deposition lines capable of handling 100-meter-plus polymer webs.
- Photovoltaic Films:Cadmium telluride and copper indium gallium selenide layers dominate utility-scale flexible solar applications. First Solar and Hanergy production lines in Ohio and Shandong Province anchor global supply for building-integrated installations.
- Organic Light Emitting Diodes:Small-molecule and polymer emitter stacks require ultra-high vacuum thermal evaporation with sub-nanometer thickness control. Seoul's display corridor concentrates evaporator equipment vendors serving Samsung Display and LG Chem rigid-to-flexible conversion programs.
- Thermoelectric Films:Bismuth telluride and skutterudite compounds on polyimide substrates serve industrial waste heat recovery.
- Flexible Batteries:Solid-state lithium-polymer and zinc-carbon architectures enable conformal power storage in wearable patches.
- Sensors:Piezoelectric PVDF and capacitive pressure layers integrate into biometric monitoring systems.
- Conductive Films:Silver nanowire and carbon nanotube networks replace indium tin oxide in touch-sensitive surfaces.
Photovoltaic Films absorb the bulk of installed capacity; Flexible Batteries are expanding most quickly.
Technology:
Cost tier stratification separates high-throughput solution processing from precision vacuum methods requiring Japanese and Korean equipment vendor ecosystems.
- Perovskite:Solution-processed methylammonium lead halide and all-inorganic cesium formulations achieve rapid efficiency gains in tandem architectures. Oxford PV and Swift Solar pilot lines in Brandenburg and California qualify automotive warranty standards for roof-integrated solar.
- Organic Electronics:Small-molecule and polymer semiconductors enable low-temperature deposition on temperature-sensitive substrates. Heliatek's Dresden manufacturing anchors European supply for building-integrated organic photovoltaics.
- Amorphous Silicon:Hydrogenated silicon thin films on stainless steel foil serve established photovoltaic applications.
- Cadmium Telluride:Vapor transport deposition achieves lowest utility-scale levelized cost of energy.
- Copper Indium Gallium Selenide:Co-evaporation and selenization processes deliver high-efficiency flexible solar.
- Nanomaterials:Graphene and carbon nanotube conductive layers serve transparent electrode applications.
Cadmium Telluride commands the largest production footprint; Perovskite shows the steepest expansion trajectory.
Application:
Application demand splits between premium-priced medical certification tracks and high-volume consumer electronics channels with compressed qualification timelines.
- Wearable Devices:Conformal power harvesting and biometric sensing layers integrate into fitness bands and clinical patches. Samsung Electronics and Apple procurement specifications drive Seoul and Shenzhen supplier qualification programs.
- Medical Devices:ISO 10993 biocompatibility requirements govern substrate selection for diagnostic patches and implantable sensors. Minnesota and Massachusetts OEM clusters specify pre-certified film suppliers to compress procurement cycles.
- Smart Cards:Embedded security chips and antenna coils require flexible interconnect substrates.
- Electronic Paper:Electrophoretic and electrochromic displays serve low-power signage applications.
- Security Systems:Tamper-evident and radio-frequency identification tags utilize conductive printed features.
- Consumer Electronics:Flexible displays and haptic feedback layers integrate into smartphones and tablets.
Consumer Electronics channels generate highest shipment volumes; Medical Devices command steepest pricing premiums.
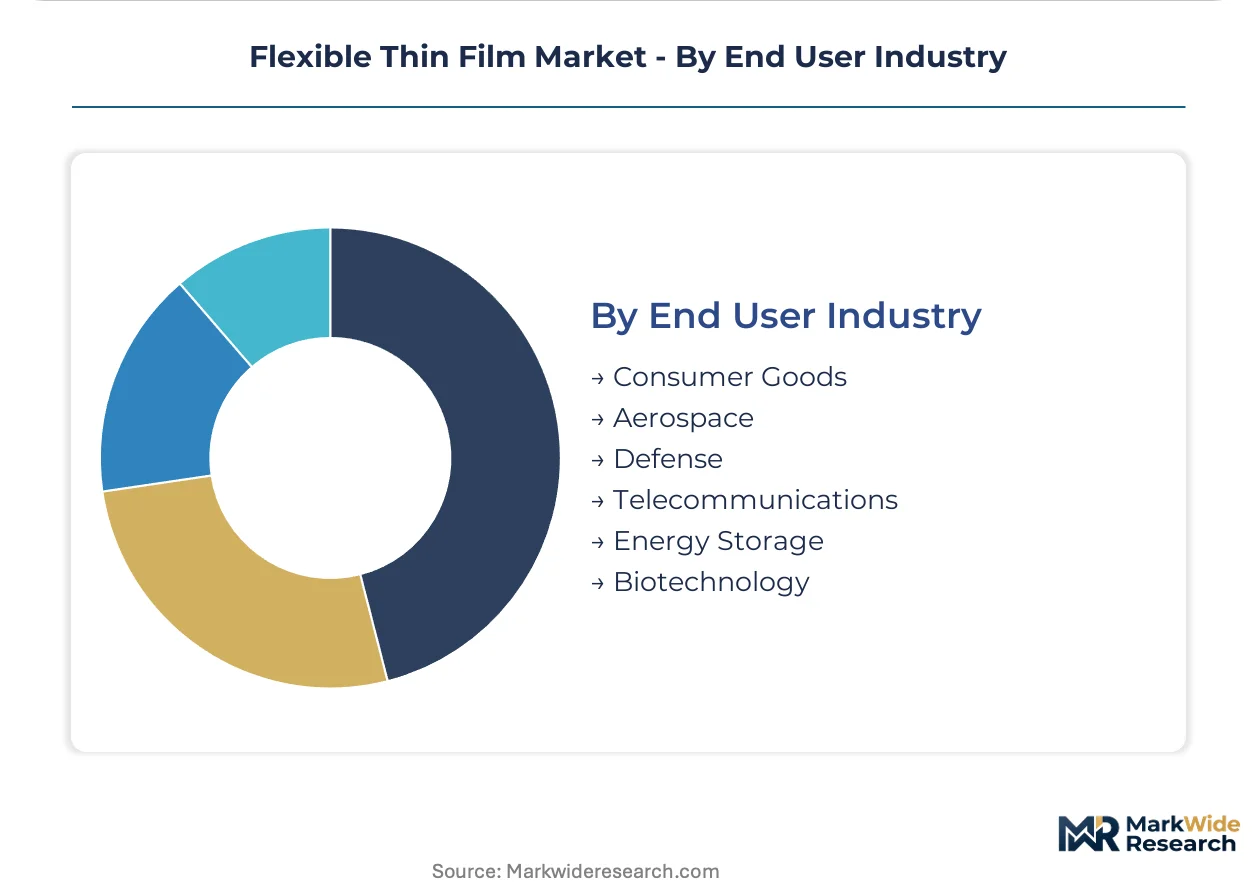
End User Industry:
Customer type differentiation separates defense procurement with extended qualification periods from biotechnology's compressed innovation cycles.
- Consumer Goods:Mass-market packaging and disposable electronics drive roll-to-roll throughput requirements. Procter & Gamble and Unilever sustainability mandates accelerate biodegradable substrate adoption.
- Energy Storage:Grid-scale and portable power applications demand barrier films with water vapor transmission rates below 10^-6 g/m²/day.
- Aerospace:Satellite and unmanned aerial vehicle power systems specify radiation-hardened flexible solar.
- Defense:Soldier-worn power and conformal antenna applications require ITAR-controlled supply chains.
- Telecommunications:Flexible printed circuit boards and antenna substrates serve 5G infrastructure deployment.
- Biotechnology:Single-use bioreactor sensors and cell culture monitoring patches prioritize biocompatibility.
Consumer Goods absorbs dominant production capacity; Biotechnology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's display technology corridor concentrates wearable device procurement specifications, while Chinese GB standards and dual carbon goals reshape material certification requirements for domestic producers.
China
MIIT energy efficiency mandates tighten power consumption limits for vacuum deposition equipment, requiring domestic tool vendors to certify to revised GB standards by 2026. Dual carbon goals accelerate substitution of halogenated flame retardants in polymer substrates. Shandong Province anchors Hanergy production lines for building-integrated installations.
South Korea
Samsung Display and LG Chem rigid-to-flexible conversion programs drive evaporator equipment procurement from Seoul corridor vendors. MFDS medical device regulations compress supplier qualification timelines for diagnostic patch substrates. Busan-Ulsan manufacturing clusters specialize in barrier film nanolaminate production.
United States
Minnesota and Massachusetts medical technology clusters specify ISO 10993 pre-certified film suppliers to accelerate Class II wearable diagnostic patch procurement. FDA biocompatibility requirements govern substrate selection for implantable sensors. First Solar maintains cadmium telluride production lines in Ohio for utility-scale applications.
Germany
REACH substance restrictions mandate substitution of halogenated flame retardants in European supply chains, favoring suppliers with pre-certified material libraries. Heliatek's Dresden manufacturing anchors organic photovoltaic supply for building-integrated segments. Bavaria-based automotive suppliers qualify perovskite-silicon tandems for roof-integrated solar warranties.
Japan
METI industrial policy supports hydrogenated amorphous silicon thin film production on stainless steel foil. JIS standards govern quality specifications for display-grade deposition equipment. Kaneka Corporation maintains domestic supply chain anchors for established photovoltaic applications.
Flexible Thin Film Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated material producers commanding premium positioning in medical certification tracks while roll-to-roll converters dominate high-volume consumer electronics channels. The vendor base organizes around three archetypes: deposition chemistry specialists, substrate handling integrators, and equipment-technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure evaporator equipment access and pre-certified material libraries.
Among Japanese and Korean metal suppliers, JX Nippon Mining & Metals and Umicore occupy positions within the transparent conductive oxide and sputtering target value chain. First Solar represents the scale-driven archetype for vapor transport deposition in utility-scale applications. These firms exemplify how geographic concentration of vacuum deposition expertise shapes competitive access to East Asian equipment vendor ecosystems.
| Leading Market Players |
|---|
| Vital Materials |
| Umicore |
| Indium Corporation |
| JX Nippon Mining & Metals |
| Kaneka Corporation |
| First Solar |
| Ascent Solar Technologies |
| Hanergy Thin Film Power Group |
| Heliatek |
| Others |
Supply & Pricing Matrix
Indium refined output from Chinese smelters feeds through sputtering target manufacturers to transparent conductive oxide deposition tiers, with pricing power accumulating at the refining stage while downstream converters absorb volatility through long-term offtake structures.
Pricing Analysis
Volume-scale contract manufacturers compete on throughput metrics while medical certification specialists command margin premiums through ISO 10993 pre-certification. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade biocompatibility tiers from consumer electronics commodity channels. Cost compression in standard-grade photovoltaic backsheet materials is intensifying because Chinese domestic capacity additions under dual carbon mandates are expanding supply faster than building-integrated demand absorption. Consumer electronics procurement teams exhibit highest price sensitivity due to compressed qualification timelines, whereas Minnesota and Massachusetts medical device OEMs prioritize certification documentation over unit cost minimization.
Supply Chain Analysis
China's GB standards and MIIT energy efficiency mandates are forcing domestic-content certification for vacuum deposition equipment, reshaping sourcing patterns for Korean display material suppliers seeking cross-border sales. Manufacturing gravity centers on China, South Korea, and Japan, with indium refining concentrated in Chinese smelters and evaporator equipment anchored in Japanese and Korean vendor ecosystems. Raw material flows draw from refined indium output, polymer substrate webs, and ceramic nanolaminate barrier layers. Single-source vulnerability in Chinese indium refining creates price volatility exposure for sputtering target consumers. Distribution runs through roll-to-roll converter networks serving Seoul's display corridor and Shenzhen consumer electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around deposition chemistry specialists with captive equipment access, as vacuum deposition technician scarcity and legacy flat panel retrofit costs force sub-scale batch processors toward exit.
For Market Incumbents: Cement barrier film nanolaminate production capabilities in Busan-Ulsan clusters to defend against emerging Chinese domestic suppliers with state-backed fab construction access. Deepen upstream control over sputtering target supply through offtake agreements with JX Nippon Mining & Metals and Umicore, locking in indium price stability against commodity volatility.
For New Entrants and Emerging Players: Launch via biodegradable substrate partnerships with Minnesota medical device OEMs seeking ISO 10993 pre-certified cellulose nanofiber alternatives to compress procurement cycles. Target India's PLI-scheme solar manufacturing incentives for flexible photovoltaic backsheet qualification, exploiting localized demand creation before incumbent roll-to-roll converters establish domestic production footprints.
For Investors and Strategic Acquirers: Perovskite tandem pilot line qualification for automotive warranty standards is the leading indicator that next-generation photovoltaic architectures are crossing the commercialization threshold. Position acquisition screening around deposition chemistry specialists with existing vacuum equipment vendor relationships in Japanese and Korean ecosystems, as capability scarcity in atomic layer deposition process engineering will intensify consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Roll-to-Roll Capacity Expansion | First Solar and Hanergy scale vapor transport deposition lines to capture building-integrated photovoltaic demand in Ohio and Shandong Province. |
| Backward Integration into Indium Refining | Transparent conductive oxide suppliers secure captive sputtering target supply against Chinese smelter concentration risk. |
| GB Standards Certification Investment | Korean equipment vendors redesign heating elements to maintain access to Chinese state-backed fab construction projects. |
| Biocompatibility Pre-Certification Program | Film manufacturers transfer ISO 10993 documentation directly to Minnesota and Massachusetts medical device OEMs. |
| Perovskite Tandem Joint Venture | Oxford PV and Swift Solar qualify automotive warranty standards for roof-integrated solar in Brandenburg and California. |
Research Methodology
Trade databases, equipment vendor technical specifications, and national energy agency filings formed the secondary backbone for this analysis. Primary interviews with vacuum deposition process engineers, medical device procurement managers at Minnesota OEM clusters, and roll-to-roll converter operations directors in Seoul's display corridor combined with bottom-up and top-down triangulation across the analysis window.
Historical trendline analysis of deposition capacity additions and substrate handling technology adoption patterns informed the analytical framework across the modeling period. Segmentation dimensions included deposition chemistry type, substrate material class, application end-use, and regional certification cluster. CAGRs were derived from capacity utilization trajectories and efficiency improvement curves in perovskite and organic photovoltaic segments.
The model assumes a particular technology adoption path; alternative pathways for all-inorganic cesium perovskite formulations would alter the outlook if laboratory stability breakthroughs accelerate commercialization timelines. Forecasts reflect assumptions regarding GB standards enforcement consistency and indium supply concentration persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Smart Card Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Thin Film Materials Market
Functional Materials
Functional Acids Market
Functional Materials
Functional Composites Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Global Thin Film Coatings Market