
 Global Smart Material Market | 2026-2036
Global Smart Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Material Market Foresight
ISO 10993 biocompatibility certification is redrawing competitive boundaries in medical-grade smart materials. TDK Corporation leverages its piezoelectric ceramic expertise to anchor sensor supply chains across automotive and consumer electronics. BASF competes through polymer chemistry scale, while CeramTec dominates engineered ceramic substrates for implantable devices.
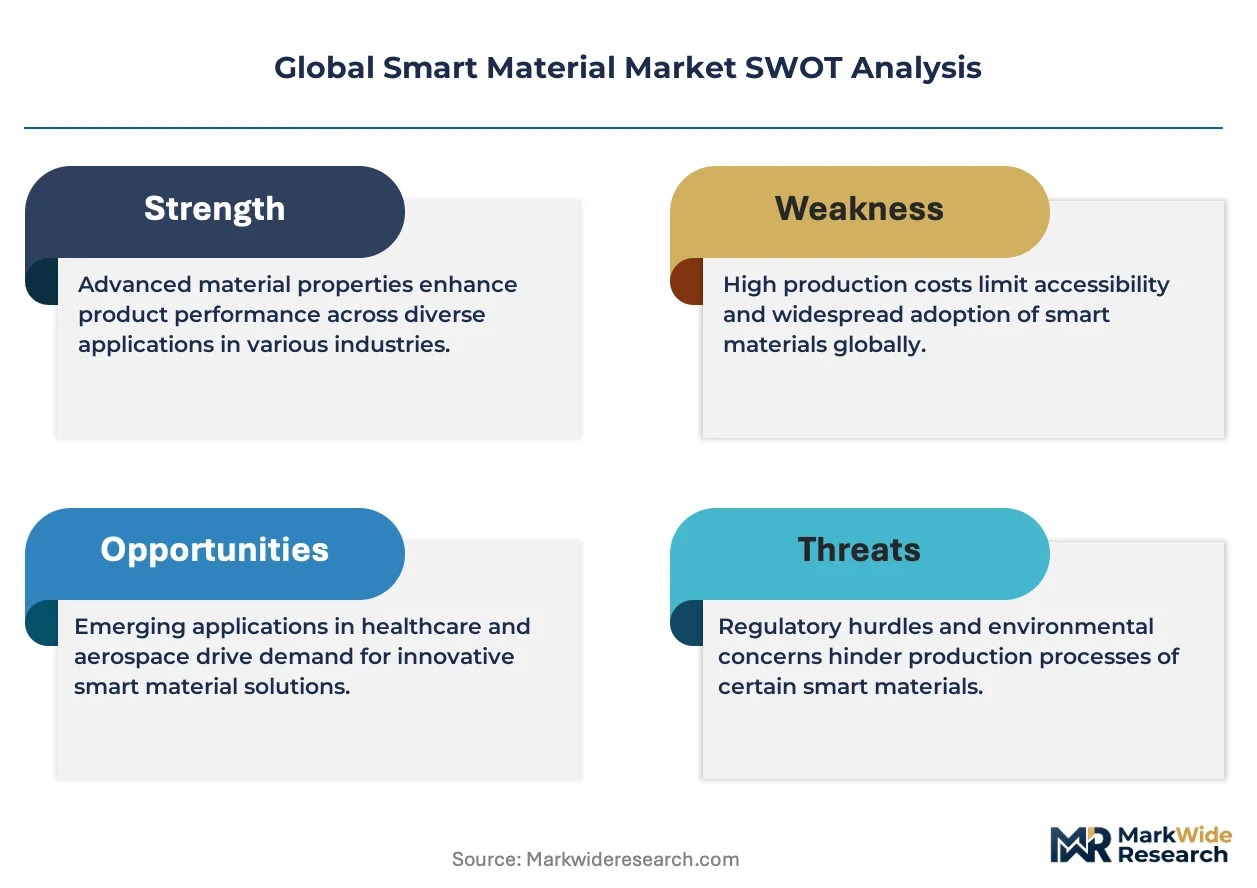
Smart materials are engineered substances that reversibly alter their mechanical, thermal, optical, or electrical properties in response to external stimuli such as electric fields, magnetic fields, temperature shifts, or mechanical stress, typically manufactured through sol-gel processing, sputter deposition, or advanced powder metallurgy to achieve precise microstructural control. Their primary purpose is to enable autonomous system adaptation without external control systems, reducing component count and energy consumption in precision applications. Piezoelectric materials lead current revenue generation due to mature manufacturing infrastructure and established supply chains in actuator and sensor production. Shape memory alloys represent the fastest-growing product category, driven by orthopedic and cardiovascular device demand where superelastic Nitinol enables minimally invasive delivery systems. Smart coatings technology concentrates margin pools in corrosion protection and self-cleaning surface applications for aerospace and marine end users.
FDA 21 CFR Part 820 quality system regulation governs medical device smart material validation, while REACH restricts hazardous substance content in European-sold electroactive polymers. EPA Toxic Substances Control Act reporting requirements shape R&D priorities for U.S.-based electrorheological fluid developers. Stakeholders must monitor evolving convergence between EMA medical device guidance and EU AI Act risk classification for adaptive diagnostic systems.
Market Dynamics
REACH compliance deadlines and EU Green Deal mandates are forcing material disclosure upgrades across electroactive polymer supply chains, compressing certification timelines for European suppliers while redirecting procurement toward German industrial clusters around Stuttgart and Karlsruhe.
Growth Catalysts
- EU Green Deal mandates:Carbon-neutral manufacturing targets are accelerating demand for energy-efficient actuators in automotive assembly lines across Germany, France, and Italy.
- Shape memory alloys in cardiovascular devices:Superelastic Nitinol enables minimally invasive stent delivery systems, with orthopedic applications expanding into spinal correction hardware.
- Aerospace adaptive structures:Next-generation airframe programs in the United States and Japan are expanding procurement of piezoelectric vibration dampening systems for fuel efficiency gains.
Market Restraints
- Rare earth element concentration:Piezoelectric ceramic production depends on Chinese-processed lanthanide oxides, creating supply vulnerability for Japanese and German sensor manufacturers.
- FDA 21 CFR Part 820 compliance costs:Medical device validation timelines extend 18-24 months for implantable smart materials, freezing out mid-cap developers without dedicated regulatory affairs teams.
- Conventional hydraulic actuators:Mature infrastructure in heavy machinery segments resists displacement by electrorheological fluid systems despite efficiency advantages.
Strategic Opportunities
- India PLI scheme for advanced materials:Production-linked incentives targeting specialty chemicals and ceramics are drawing contract manufacturing investment away from Southeast Asian hubs.
- EU AI Act risk classification:Adaptive diagnostic systems with embedded smart sensors face new conformity assessment pathways, creating first-mover advantage for pre-certified suppliers.
- Self-healing concrete integration:Shape memory polymer fibers in civil infrastructure represent untapped demand from Japan's earthquake-resistant construction codes.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Certified laboratory capacity constraints in Europe delay medical-grade smart material launches by 8-14 months.
- Legacy PLC system integration:Industrial automation customers require custom middleware to connect smart material actuators with existing Siemens and Rockwell control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Material Market |
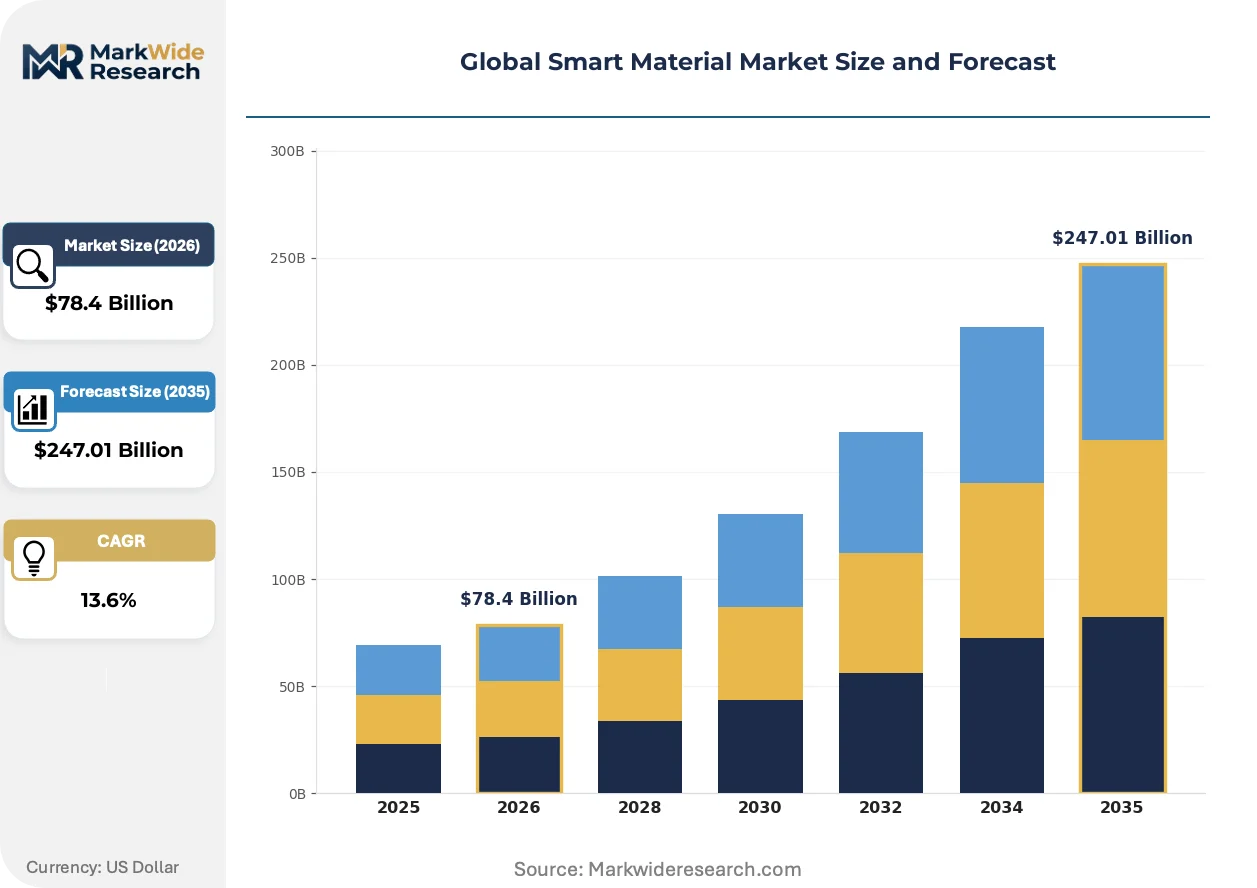
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shape Memory Alloys, Piezoelectric Materials, Electrorheological Fluids, Magnetorheological Materials Technology: Self-Healing, Biodegradable Polymers, Smart Coatings, Adaptive Structures Application: Aerospace, Healthcare Devices, Automotive, Consumer Electronics End User: Manufacturers, Product Designers, Researchers, End Consumers |
| Companies Covered | TDK Corporation, Kyocera Corporation, CeramTec, APC International Ltd., CTS Corporation, LORD Corporation, BASF, 3M, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Material Market Shifts & Advancements
Smart material functionality is splitting between commodity sensor applications and high-value adaptive systems, with manufacturing process innovation determining which suppliers capture margin in each tier.
Piezoelectric energy harvesting is bifurcating across two performance tiers. Thin-film polymers power disposable medical patches and logistics trackers for pharmaceutical cold chains. Bulk ceramic stacks anchor vibration energy recovery in heavy rail and industrial machinery. Medical device OEMs in Switzerland and Germany are qualifying polymer systems for 18-month disposable lifecycles, while Japanese rail operators deploy ceramic arrays for 25-year infrastructure assets.
REACH Annex XIV authorization requirements are expanding substance restrictions for electroactive polymers sold in Europe. ECHA evaluations of persistent organic pollutants now cover fluorinated coatings used in marine corrosion protection. Danish and Dutch shipyards are accelerating qualification of silicone-based alternatives ahead of 2027 sunset dates, shifting specification authority from procurement teams to environmental compliance officers.
Specification authority is migrating from component buyers to systems integrators in automotive Tier-1 supply chains. Bosch and Continental now mandate smart material performance data through standardized CAN bus interfaces, disqualifying suppliers without embedded diagnostics. This pattern concentrates most visibly in Stuttgart's supplier ecosystem, where Mercedes-Benz and Porsche program managers enforce unified sensor communication protocols across multi-source actuator procurement.
Global Smart Material Market Segmentation
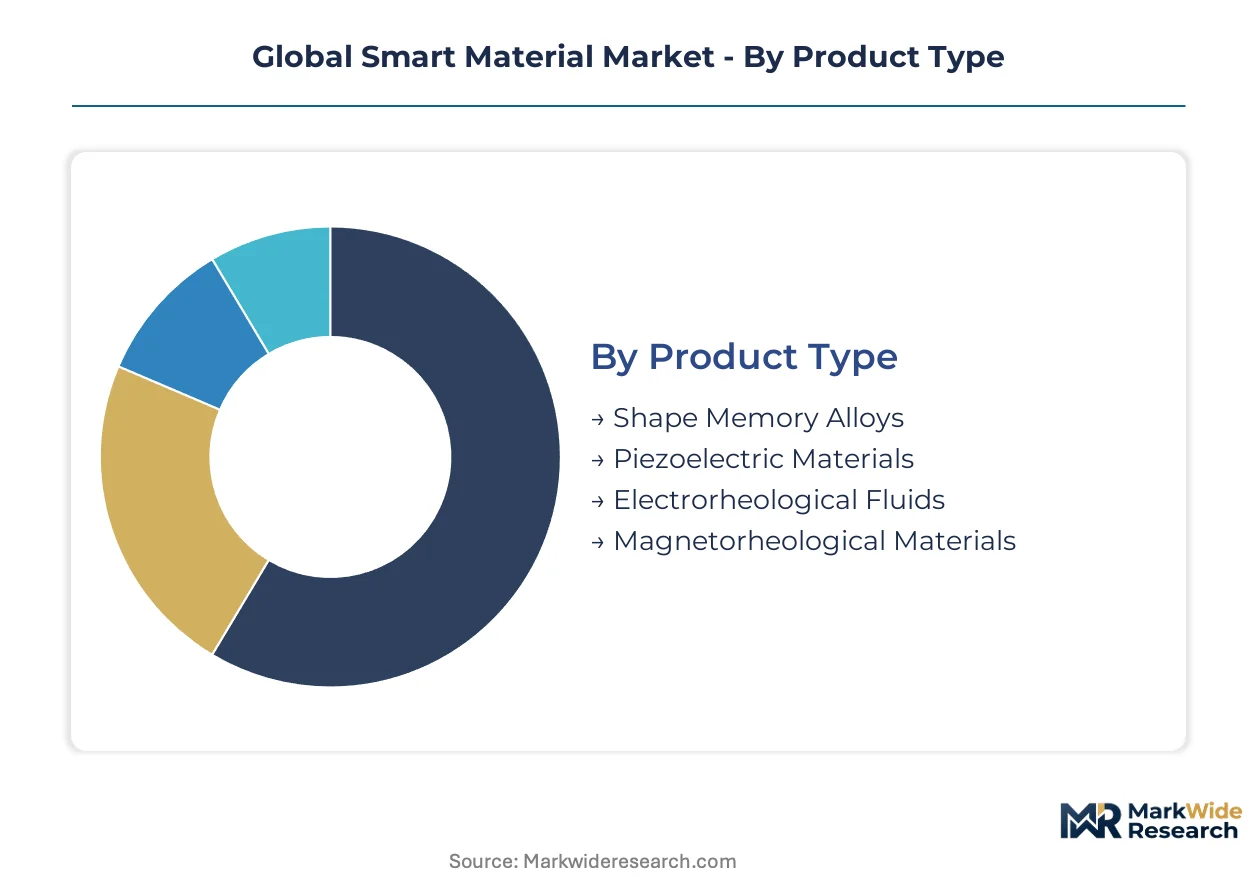
Smart material procurement channels diverge sharply between specification-driven industrial contracts and commoditized component spot markets. Channel selection determines margin capture, with direct OEM relationships commanding premium pricing against distributor-mediated volumes.
Product Type:
Channel concentration varies by material chemistry, with piezoelectric ceramics flowing through specialized electronics distributors while shape memory alloys route through medical device contract manufacturers.
- Shape Memory Alloys:Nitinol-based systems exhibit thermally induced phase transformation between austenite and martensite crystal structures. Orthopedic stent manufacturers in Germany and cardiovascular device producers in the United States concentrate procurement through qualified contract manufacturers due to FDA 21 CFR Part 820 validation requirements.
- Piezoelectric Materials:Ceramic and polymer systems generate electrical charge under mechanical stress through dipole alignment. Automotive sensor procurement in Stuttgart's supplier ecosystem and consumer electronics assembly in Japan flow through Arrow and Avnet distribution networks with embedded diagnostics.
- Electrorheological Fluids:Suspensions of polarizable particles in dielectric base oils alter viscosity under electric field application. Heavy machinery OEMs source through direct mill relationships.
- Magnetorheological Materials:Iron particle suspensions enable rapid damping adjustment for seismic isolation systems. Civil infrastructure contractors procure through specialty chemical distributors.
Piezoelectric materials dominate installed base. Shape memory alloys are where expansion concentrates.
Technology:
Cost tier stratification separates military-aerospace qualification premiums from mass-market consumer pricing, with smart coatings and adaptive structures commanding 3-5x manufacturing overhead against biodegradable alternatives.
- Self-Healing:Microcapsule-embedded polymers and vascular network systems autonomously repair cracks through triggered release of healing agents. Aerospace OEMs in Japan qualify systems for 25-year airframe lifecycles, with automotive paint applications in Germany expanding through BASF supply agreements.
- Biodegradable Polymers:Aliphatic polyesters and protein-based materials decompose through enzymatic hydrolysis. Medical suture manufacturers in Switzerland and single-use packaging converters in France drive demand through ECHA-compliant supply chains.
- Smart Coatings:Stimuli-responsive surfaces alter wettability, color, or corrosion resistance through environmental triggers. Marine operators in Denmark accelerate silicone-based qualification ahead of fluorinated coating sunset dates.
- Adaptive Structures:Morphing composites and compliant mechanisms reconfigure geometry under load. Next-generation fighter programs in the United States and Japan expand piezoelectric actuator procurement for fuel efficiency.
Smart coatings command margin concentration in corrosion protection. Self-healing systems are climbing the fastest in qualification pipelines.
Application:
Customer type determines specification authority, with aerospace primes and automotive Tier-1s mandating performance data protocols while healthcare device OEMs prioritize biocompatibility certification.
- Aerospace:Adaptive wing surfaces and vibration dampening systems reduce drag and structural fatigue. Boeing and Airbus procurement teams in the United States and France specify piezoelectric arrays through qualified supplier lists with 18-month qualification cycles.
- Healthcare Devices:Implantable sensors and drug delivery systems require ISO 10993 biocompatibility validation. Spinal correction hardware manufacturers in Germany and stent producers in Switzerland concentrate demand through CeramTec substrate supply.
- Automotive:Energy-efficient actuators and haptic feedback systems assemble across Mercedes-Benz and Porsche production lines in Stuttgart. Bosch mandates CAN bus interface standardization, disqualifying non-compliant suppliers.
- Consumer Electronics:Haptic actuators and energy harvesting systems integrate into smartphones and wearables. TDK Corporation anchors sensor supply chains through direct OEM relationships in Japan and South Korea.
Automotive applications dominate volume throughput. Healthcare devices are gaining share fastest in margin contribution.
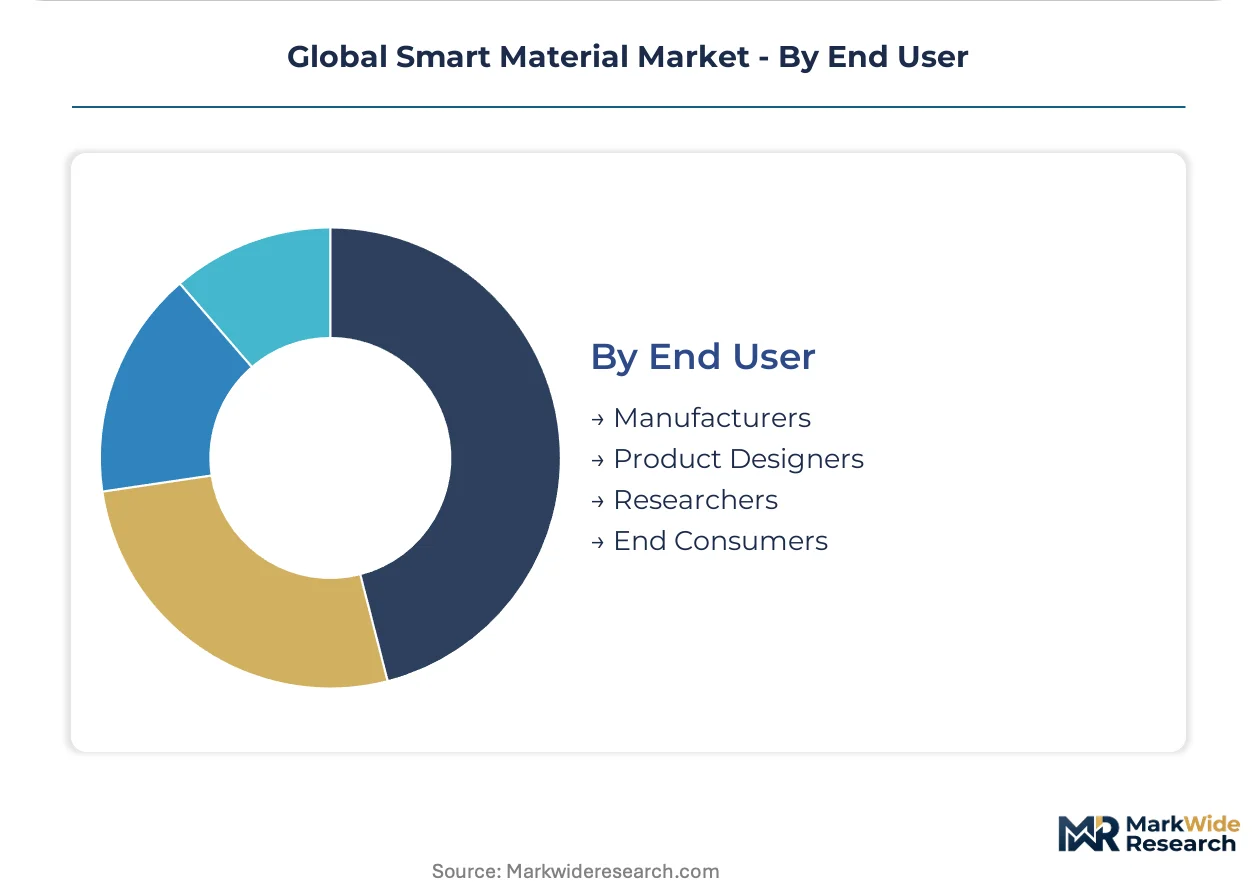
End User:
Geographic procurement gravity centers on German industrial clusters for manufacturers, with researchers distributed across Swiss and Japanese academic institutions.
- Manufacturers:Industrial OEMs and contract fabricators specify material performance through standardized procurement protocols. German automotive suppliers around Karlsruhe consolidate electroactive polymer purchasing through centralized environmental compliance officers.
- Product Designers:Industrial design firms and systems integrators bridge technical specifications with user experience requirements. Stuttgart-based studios specify smart material performance data through unified sensor communication protocols.
- Researchers:Academic institutions and national laboratories advance material characterization and novel synthesis methods. ETH Zurich and Karlsruhe Institute of Technology concentrate EU-funded projects on biodegradable polymer development.
- End Consumers:Individual purchasers access smart materials through finished goods rather than direct procurement. Fitness wearable buyers in Japan and medical device patients in the United States represent terminal demand.
Manufacturers control specification authority. Researchers are where technology transfer concentrates for commercial pipeline development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and national production incentives are redrawing procurement geography, with industrial clusters in Germany, Japan, and the United States capturing specification authority while India and China scale contract manufacturing capacity.
United States
Aerospace adaptive structures and cardiovascular device demand drive procurement concentration. FDA 21 CFR Part 820 governs medical-grade smart material validation, extending qualification timelines for implantable systems. Boeing procurement teams in Washington State specify piezoelectric arrays through qualified supplier lists with 18-month certification cycles.
Germany
Automotive energy-efficient actuators and orthopedic stent manufacturing anchor demand. REACH compliance deadlines compress certification timelines for electroactive polymer suppliers. Stuttgart's supplier ecosystem concentrates Mercedes-Benz and Porsche program managers enforcing unified sensor communication protocols across multi-source actuator procurement.
Japan
Piezoelectric sensor supply chains and vibration dampening systems for rail infrastructure dominate procurement. METI standards shape domestic qualification requirements for ceramic actuator arrays. Tokyo-based OEMs deploy bulk ceramic stacks for 25-year infrastructure assets while qualifying thin-film polymers for consumer electronics integration.
India
Contract manufacturing investment in specialty ceramics and electroactive polymers accelerates under PLI scheme incentives. BIS certification requirements guide import substitution strategies for sensor-grade materials. Gujarat and Tamil Nadu industrial corridors attract fabrication capacity relocating from Southeast Asian hubs.
China
Rare earth element processing concentration creates supply leverage for lanthanide oxide-dependent piezoelectric ceramics. MIIT industrial policy directs domestic capacity expansion in actuator-grade materials. Yangtze River Delta clusters integrate upstream rare earth refining with downstream sensor component fabrication.
Global Smart Material Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with ceramic chemistry expertise alongside specialized sensor component fabricators. Market structure concentrates around three tiers: multinational chemical conglomerates with polymer scale, precision ceramics specialists with medical-grade certification, and regional electronics component distributors with embedded diagnostics capability. Dominant competitive moves include backward integration into rare earth oxide supply and strategic partnerships with automotive Tier-1 systems integrators mandating standardized CAN bus interfaces.
Within the diversified conglomerate tier, TDK Corporation and Kyocera Corporation occupy anchor positions spanning piezoelectric ceramic expertise across automotive and consumer electronics sensor supply chains. CeramTec exemplifies the precision ceramics specialist archetype, concentrating engineered substrates for implantable medical devices requiring ISO 10993 biocompatibility validation. BASF and DuPont represent polymer chemistry scale players competing through REACH-compliant electroactive material supply to European industrial clusters.
| Leading Market Players |
|---|
| TDK Corporation |
| Kyocera Corporation |
| CeramTec |
| APC International Ltd. |
| CTS Corporation |
| LORD Corporation |
| BASF |
| 3M |
| DuPont |
| Others |
Supply & Pricing Matrix
Chinese rare earth oxide processing capacity anchors cost floors for piezoelectric ceramics, concentrating pricing power among lanthanide refiners while forcing Japanese and German sensor manufacturers to absorb input volatility or pursue backward integration into oxide supply.
Pricing Analysis
Certification level creates the primary spread across ISO 10993 biocompatibility tiers, with FDA-grade medical substrates commanding premium positioning against industrial sensor grades. Three-tier pricing structure across medical-certified, automotive-qualified, and economy electronics grades stratifies margin capture. Cost compression in commodity piezoelectric polymers is intensifying because contract manufacturers in India scale specialty ceramics capacity under PLI scheme incentives. Healthcare device OEMs in Switzerland exhibit lowest price sensitivity due to regulatory switching costs, while consumer electronics assemblers in South Korea drive hardest bargain on volume procurement.
Supply Chain Analysis
Strategic stockpiling of rare earth oxides dominates inventory strategy among Japanese ceramic manufacturers confronting Chinese export quota uncertainty, while European electroactive polymer suppliers maintain lean just-in-time positions given REACH compliance-driven formulation volatility. Supply concentrates in China for lanthanide oxide refining, Germany for automotive-grade actuator assembly, and Japan for precision ceramic fabrication. Raw material flows draw from Australian rare earth concentrates, German specialty chemical precursors, and Japanese powder metallurgy equipment. Single-source vulnerability around Chinese-processed dysprosium and terbium oxides threatens continuity for high-temperature piezoelectric applications. Distribution runs through Arrow and Avnet networks for electronics-grade materials, with direct mill relationships governing heavy machinery electrorheological fluid procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart material market is entering a cyclical recovery phase as aerospace adaptive structure programs in the United States and Japan accelerate procurement timelines following pandemic-delayed qualification cycles.
For Market Incumbents: Compound certification barriers by deepening ISO 10993 laboratory partnerships and securing REACH pre-registration for next-generation electroactive polymer formulations before 2027 sunset dates. Add ceramic actuator capacity in Karlsruhe's industrial corridor to defend against Indian contract manufacturing inroads. Prioritize backward integration into rare earth oxide supply through offtake agreements with Australian concentrate producers. For New Entrants and Emerging Players: Lead with self-healing concrete fiber applications targeting Japan's earthquake-resistant construction codes, where specification authority remains fragmented among civil engineering contractors rather than concentrated at Tier-1 systems integrators. Target biodegradable polymer development partnerships with ETH Zurich and Karlsruhe Institute of Technology researchers for technology transfer pipelines. Pursue white-label supply to German automotive Tier-2s seeking CAN bus-compliant alternatives to Bosch-mandated protocols. For Investors and Strategic Acquirers: Precision ceramics specialists with captive ISO 10993 testing infrastructure represent the most defensible acquisition archetype as biocompatibility certification backlogs extend medical-grade material launch timelines. Long-term viability hinges on positioning upstream of automotive electrification and minimally invasive surgical device trends. Watch FDA 510(k) clearance velocity for adaptive diagnostic systems as inflection indicator for embedded sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxide Supply | Captive lanthanide sourcing insulates Japanese and German ceramic manufacturers from Chinese quota volatility. |
| ISO 10993 Laboratory Partnership Expansion | Certified testing capacity in Europe reduces medical-grade smart material launch delays by 8-14 months. |
| REACH Pre-Registration for Electroactive Polymers | Early ECHA compliance secures market access ahead of 2027 fluorinated coating sunset dates. |
| CAN Bus Interface Standardization Investment | Embedded diagnostics capability qualifies suppliers for Stuttgart automotive Tier-1 procurement mandates. |
| Biodegradable Polymer R&D Collaboration | ETH Zurich and Karlsruhe Institute partnerships accelerate ECHA-compliant medical suture development. |
Research Methodology
Operator-level perspectives from ceramic plant managers, automotive Tier-1 procurement leads, biomedical engineers at implantable device OEMs, and ECHA compliance officers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, ECHA substance registration databases, FDA 510(k) clearance records, and Japanese METI industrial production surveys. Bottom-up demand modeling across piezoelectric actuator, shape memory alloy, and electroactive polymer product lines triangulated against top-down aerospace and automotive production forecasts.
Sensitivity analysis tested forecast robustness across rare earth oxide price volatility scenarios, REACH authorization timeline variations, and automotive platform electrification adoption curves. Segmentation dimensions modeled include material chemistry, certification grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than extrapolated from historical trends. Industry-specific inputs incorporated Boeing and Airbus qualified supplier list expansion timelines, German automotive production schedules, and Japanese rail infrastructure refurbishment programs.
The analysis sits within stated boundaries; outcomes outside sustained aerospace procurement acceleration, stable Chinese rare earth export policy, or continued EU Green Deal enforcement would require recalibration. Forecasts reflect documented assumptions regarding qualification cycle durations and regulatory compliance cost trajectories. Revision becomes warranted when FDA medical device clearance backlogs or ECHA substance evaluation delays cross thresholds that compress commercialization timelines beyond manufacturer capital recovery horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Functional Composites Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Functional Acids Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Flexible Thin Film Market
Functional Materials
UHMWPE for Li-Battery Market