
 Global Positive Material Identification Market | 2026-2036
Global Positive Material Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Positive Material Identification Market Outlook
Germany's industrial testing infrastructure is narrowing the gap between laboratory-grade precision and shop-floor portability. Thermo Fisher Scientific leverages its mass spectrometry heritage to dominate high-end laboratory deployments. Hitachi High-Tech Analytical Science anchors the Asia-Pacific portable segment through its Vulcan LIBS product line. Bruker Corporation differentiates via silicon drift detector technology that extends XRF sensitivity for light element identification.
Positive material identification refers to non-destructive analytical techniques that verify elemental composition and grade of metals, alloys, and polymers against certified reference standards, typically achieving detection limits below 100 ppm for transition metals. XRF technology leads deployment volumes due to its balance of speed, non-destructive operation, and minimal sample preparation requirements across manufacturing quality control stations. Portable systems represent the fastest-expanding deployment category as battery-powered handheld units displace benchtop workflows in field inspection and recycling yard environments. Laboratory-grade instruments retain margin concentration through multi-technique configurations combining XRF with spark OES for ultra-low carbon analysis in steel certification.
FDA enforces material verification for surgical implant alloys through its 21 CFR Part 820 quality system regulation, while REACH and RoHS compliance obligations within Europe mandate supply chain documentation of restricted substances. China's GB standards and NMPA medical device regulations impose parallel testing burdens on exporters serving domestic hospitals and aerospace contractors. Stakeholders must monitor divergence between regional certification requirements as dual carbon goals in Beijing and the EU Green Deal accelerate restrictions on heavy metal content across industrial feedstocks.
Market Dynamics
Portable XRF analyzers are compressing inspection timelines from laboratory days to shop-floor seconds, forcing incumbents to defend benchtop margins against handheld commoditization while aerospace and automotive OEMs rewrite supplier qualification protocols around point-of-use verification.
Growth Catalysts
- REACH and RoHS stringency:ECHA enforcement of restricted substance documentation across EU industrial supply chains mandates elemental verification at multiple custody transfer points, expanding analyzer deployment at tier-2 and tier-3 suppliers.
- Aerospace alloy verification:FAA airworthiness directives and OEM incoming inspection protocols require positive material identification for flight-critical titanium and nickel superalloy components, driving repeat calibration service contracts.
- China's dual carbon goals:Beijing's restrictions on heavy metal content in industrial feedstocks force exporters to GB standards to install verification stations before customs clearance and domestic distribution.
Market Restraints
- Helium supply concentration:Spark OES instruments depend on helium purge for ultra-low carbon detection in steel, and Qatar's dominance of liquefied helium exports creates input cost volatility and allocation risk for laboratory-grade systems.
- Detector material bottlenecks:Silicon drift detector fabrication concentrates among a limited set of semiconductor foundries, constraining production scaling for high-sensitivity portable units.
- LIBS technical ceiling:Laser-induced breakdown spectroscopy struggles with reproducibility on aluminum alloys below 0.5% magnesium content, limiting displacement of spark OES in precision aerospace applications.
Strategic Opportunities
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade automotive and electrical steel create demand for integrated XRF-OES verification lines at greenfield mill complexes in Odisha and Karnataka.
- Battery recycling verification:Cathode material recovery from lithium-ion batteries requires rapid lithium-cobalt-nickel fingerprinting, opening a channel for handheld LIBS units at European and North American recycling yards.
- Medical device NMPA compliance:China's tightened surgical implant alloy documentation creates service revenue potential for certification laboratories supporting Western manufacturers exporting to domestic hospitals.
Industry Challenges
- Spectroscopy technician scarcity:Interpretation of overlapping emission lines in complex alloys requires specialized training, and maintenance engineering programs at German and Japanese technical institutes graduate insufficient operators for installed base expansion.
- Multi-technique integration complexity:Laboratory customers demand unified software platforms spanning XRF, spark OES, and combustion analysis, forcing vendors to absorb substantial R&D overhead for interoperability certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Positive Material Identification Market |
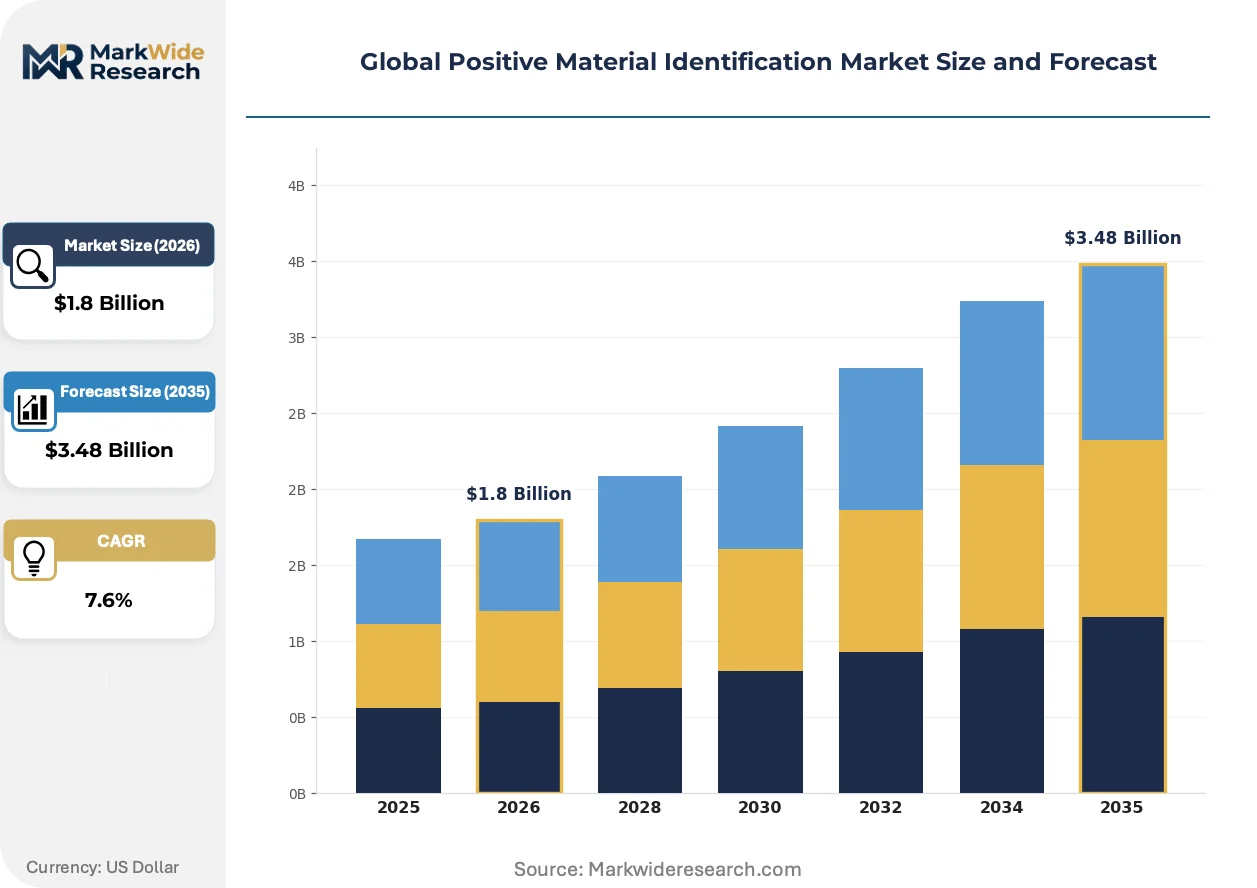
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: XRF, LIBS, NIR, FTIR End User: Manufacturing, Construction, Aerospace, Recycling Application: Metal Analysis, Polymer Verification, Hazardous Material Detection, Quality Control Deployment: Portable Systems, Laboratory-Grade Instruments, Fixed Installations, Software Solutions |
| Companies Covered | Thermo Fisher Scientific, Hitachi High-Tech Analytical Science, Bruker Corporation, Olympus Corporation, Ametek Inc., SGS S.A., Bureau Veritas, Oxford Instruments, Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Positive Material Identification Market Strategic Shifts
Artificial intelligence is penetrating spectral interpretation workflows, compressing the gap between raw detector output and actionable grade classification while regulatory divergence between jurisdictions forces manufacturers toward modular hardware architectures.
Silicon drift detectors with graphene-based window materials are rendering obsolete traditional polymer-window XRF systems for light element analysis. Automotive OEMs in Stuttgart and Wolfsburg now mandate magnesium and aluminum verification at press shop entry points that previously relied on supplier certificates. The structural consequence is collapsing the price premium for laboratory-grade light element sensitivity into mid-range portable units.
The EU AI Act's risk classification framework for automated decision systems is reclassifying unsupervised grade-matching algorithms as high-risk when deployed for safety-critical aerospace components. Industrial laboratories in Toulouse and Hamburg must now maintain human-in-the-loop validation protocols and algorithmic audit trails. Spark OES vendors are responding with explainable AI modules that trace each spectral match to specific emission line libraries.
After-sales service unbundling is fragmenting the traditional analyzer revenue model. German automotive tier suppliers now procure calibration standards and software updates through separate procurement channels rather than bundled maintenance contracts. This pattern is most pronounced in Bavaria's supplier parks, where centralized metrology pools share reference materials across multiple OEM programs, compressing per-site service contract values while expanding total consumables volume.
Global Positive Material Identification Market Segmentation
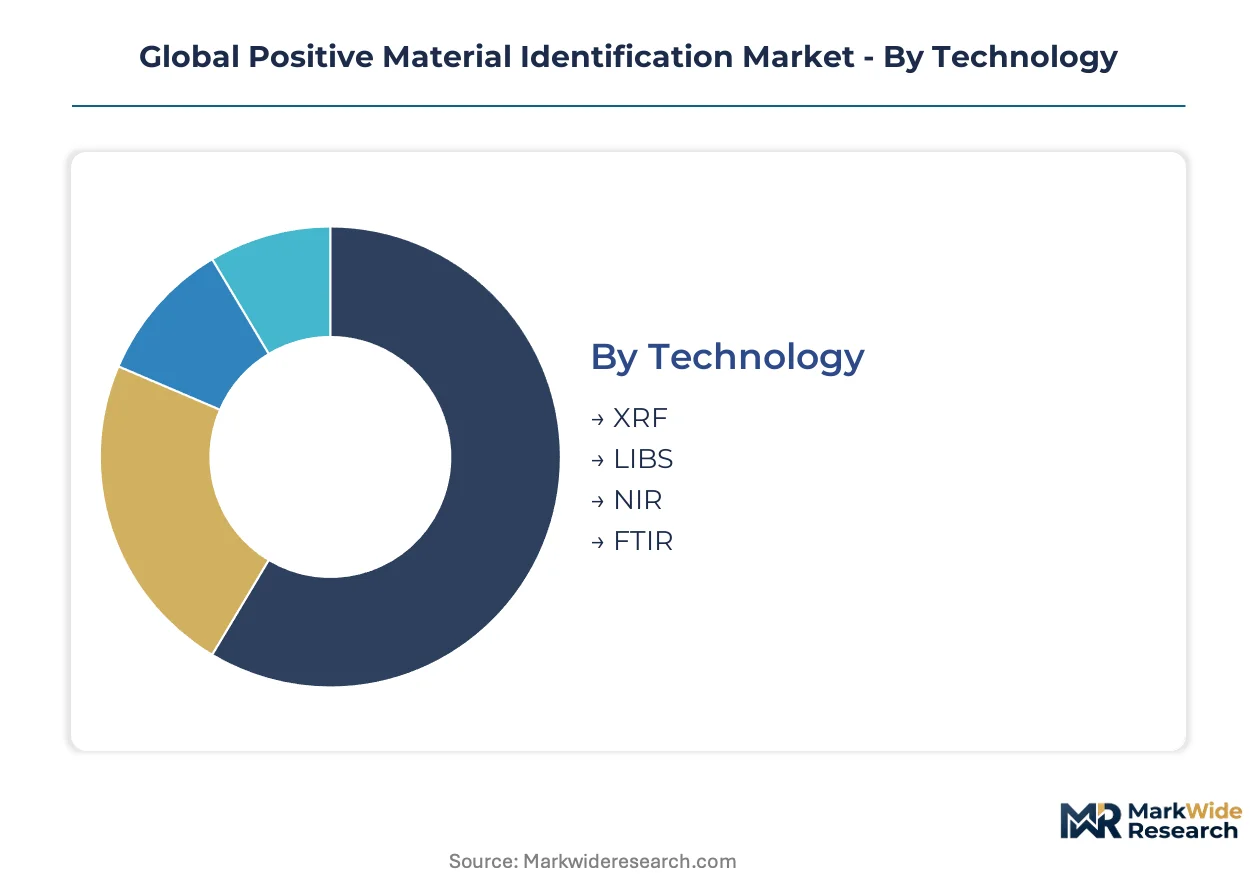
Technology and deployment choices in positive material identification reflect a fundamental trade-off between analytical precision and operational mobility. End-use requirements from aerospace certification to scrap yard sorting create divergent performance specifications that segment the vendor landscape.
Technology:
Mature spectroscopic platforms coexist with emerging photonic methods across industrial quality control workflows.
- XRF:X-ray fluorescence dominates installed volumes through its balance of non-destructive operation, minimal sample preparation, and quantitative accuracy for transition metals above 100 ppm. Automotive OEMs in Stuttgart and Wolfsburg mandate XRF verification at press shop entry points for magnesium and aluminum alloys. Benchtop units with silicon drift detectors extend light element sensitivity that previously required laboratory confinement.
- LIBS:Laser-induced breakdown spectroscopy offers instantaneous analysis without radiation licensing burdens, attracting adoption at European and North American battery recycling yards for lithium-cobalt-nickel fingerprinting. Reproducibility constraints below 0.5% magnesium content in aluminum alloys limit displacement of spark OES in precision aerospace applications.
- NIR:Near-infrared spectroscopy addresses polymer verification through molecular overtone detection, serving packaging manufacturers facing EU REACH documentation obligations for recycled content certification.
- FTIR:Fourier-transform infrared systems deliver detailed molecular fingerprinting for complex polymer matrices and composite materials in medical device manufacturing.
XRF handles the majority of throughput; LIBS is the fastest mover on share.
End User:
Customer sophistication spans from centralized laboratory operations to distributed field inspection networks.
- Manufacturing:Incoming material inspection at automotive and industrial machinery plants drives the largest equipment procurement volumes, with German tier suppliers enforcing strict alloy verification protocols across supplier parks in Bavaria.
- Aerospace:OEMs and their certified suppliers require positive material identification for flight-critical titanium and nickel superalloy components under FAA airworthiness directives, generating repeat calibration service contracts and traceable documentation systems.
- Construction:Structural steel verification at fabrication yards and infrastructure project sites employs portable analyzers to confirm grade compliance against national building codes.
- Recycling:Scrap metal processors and battery recovery operations utilize rapid-sorting handheld units to classify feedstock value and identify restricted substances before furnace entry.
Manufacturing commands the greatest equipment deployment; aerospace generates the highest service attach rates.
Application:
Functional requirements range from elemental quantification to regulatory compliance documentation.
- Metal Analysis:Alloy grade verification against certified reference standards constitutes the core use case across aerospace, automotive, and primary metals industries.
- Quality Control:Statistical process control integration at production lines demands analyzer connectivity to manufacturing execution systems for automated disposition decisions.
- Hazardous Material Detection:RoHS and REACH compliance screening for restricted heavy metals in electrical and electronic equipment concentrates demand among electronics manufacturers exporting to European markets.
- Polymer Verification:Recycled content authentication and additive package identification serve packaging and medical device sectors facing tightened supply chain documentation requirements.
Metal analysis absorbs the dominant share of analytical capacity; hazardous material detection is climbing the fastest as regulatory jurisdictions multiply.
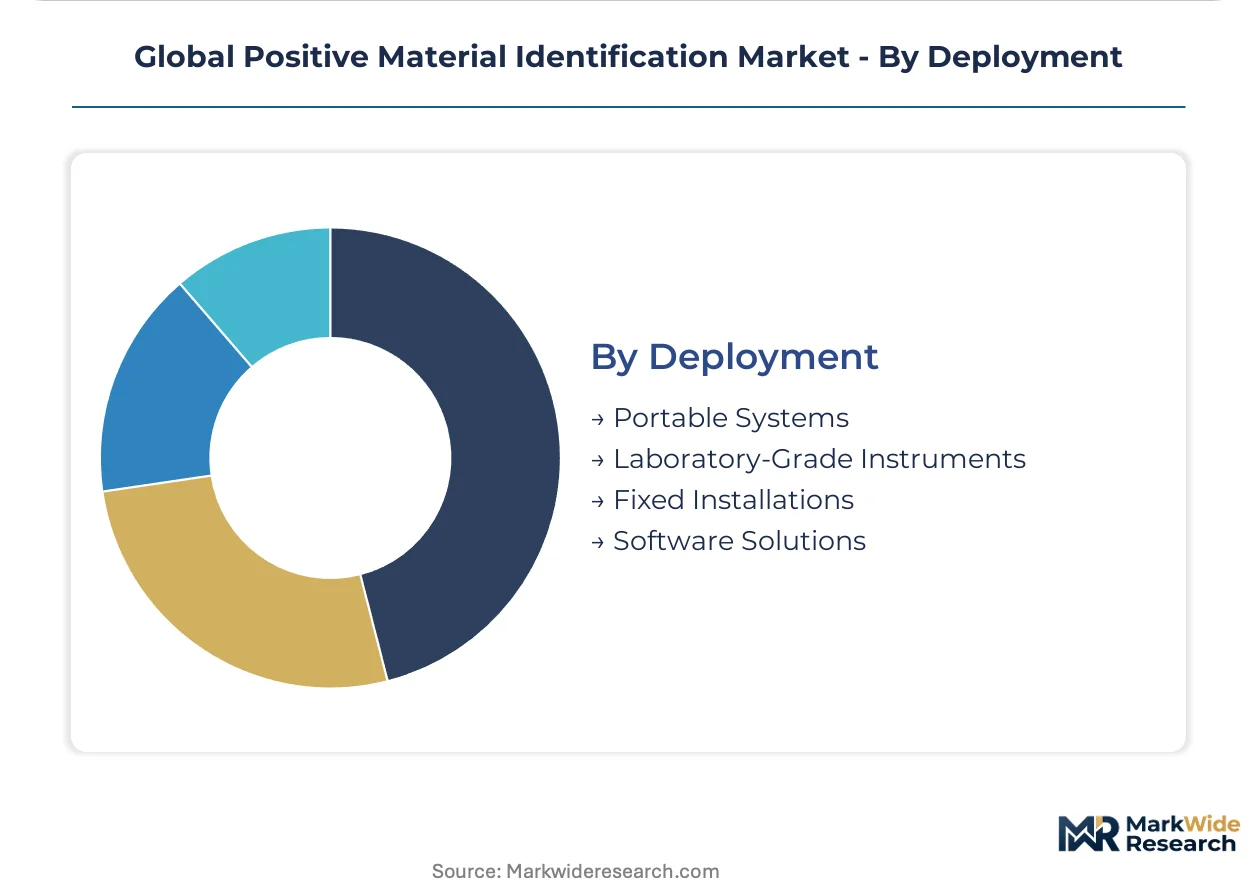
Deployment:
Physical form factors reflect a migration from centralized laboratory infrastructure toward point-of-use verification.
- Portable Systems:Battery-powered handheld units displace benchtop workflows in field inspection and recycling environments, compressing inspection timelines from laboratory days to shop-floor seconds. Detector material bottlenecks constrain production scaling for high-sensitivity configurations.
- Laboratory-Grade Instruments:Multi-technique configurations combining XRF with spark OES retain margin concentration through ultra-low carbon analysis capabilities in steel certification, though helium supply concentration creates input cost volatility.
- Fixed Installations:Conveyor-integrated sorting systems at scrap processing facilities and steel mill entry points enable high-throughput automated classification.
- Software Solutions:Spectral interpretation platforms and grade library management tools unbundle from hardware bundles as German automotive tier suppliers separate calibration standards procurement from maintenance contracts.
Portable systems are gaining share fastest; laboratory-grade instruments defend the margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium supply concentration in Qatar and detector fabrication bottlenecks in East Asian foundries concentrate upstream vulnerability for laboratory-grade systems. Demand fragmentation across aerospace certification hubs and automotive manufacturing clusters shapes regional deployment patterns. Regulatory divergence between the EU's REACH enforcement and China's GB standards creates compliance complexity for multinational equipment vendors.
United States
FAA airworthiness directives mandate positive material identification for flight-critical titanium and nickel superalloy components across Boeing's Seattle-area supply base. FDA enforces material verification for surgical implant alloys through its 21 CFR Part 820 quality system regulation. Aerospace OEMs in Wichita and defense contractors in Connecticut drive repeat calibration service contracts.
Germany
Automotive OEMs in Stuttgart and Wolfsburg enforce strict incoming material inspection protocols across Bavarian supplier parks. ECHA enforcement of REACH documentation expands analyzer deployment at tier-2 and tier-3 suppliers throughout Baden-Württemberg. KBA certification requirements for automotive steel grades sustain demand for integrated XRF-OES verification lines.
China
Beijing's dual carbon goals restrict heavy metal content in industrial feedstocks, forcing exporters to install verification stations before customs clearance. NMPA tightened surgical implant alloy documentation creates service revenue potential for certification laboratories supporting domestic hospitals. GB standards compliance burdens concentrate demand in Yangtze River Delta manufacturing zones.
Japan
METI industrial standards and JIS certification requirements sustain precision aerospace applications resistant to portable LIBS displacement. Automotive and industrial machinery manufacturers in Aichi Prefecture maintain laboratory-grade multi-technique configurations. Spark OES retains margin concentration through ultra-low carbon analysis capabilities for specialty steel exports.
India
PLI scheme incentives for high-grade automotive and electrical steel create demand for verification infrastructure at greenfield mill complexes in Odisha and Karnataka. CDSCO medical device regulations impose parallel testing burdens on exporters serving domestic hospitals. BIS standards enforcement expands across Maharashtra and Gujarat industrial corridors.
Global Positive Material Identification Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream of detector fabrication and optical subassembly supply. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation conglomerates with mass spectrometry heritage, portable-focused specialists leveraging LIBS and XRF miniaturization, and third-party testing laboratories bundling equipment with certification services. Competitive moves concentrate on M&A for detector technology access and strategic partnerships to secure helium supply alternatives for spark OES instruments.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific exemplifies the laboratory-grade platform integrator archetype through its mass spectrometry heritage. Hitachi High-Tech Analytical Science and Bruker Corporation occupy positions spanning portable and benchtop segments, with the former anchoring Asia-Pacific deployment and the latter differentiating via silicon drift detector technology. Bureau Veritas and SGS S.A. represent the third-party certification laboratory model, bundling analyzer procurement with ongoing compliance documentation services.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hitachi High-Tech Analytical Science |
| Bruker Corporation |
| Olympus Corporation |
| Ametek Inc. |
| SGS S.A. |
| Bureau Veritas |
| Oxford Instruments |
| Rigaku Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in silicon drift detector foundries across East Asia is compressing margins for high-sensitivity portable units while forcing buyers into longer order queues and premium pricing for laboratory-grade configurations. This utilization squeeze simultaneously inflates input costs and concentrates pricing power among detector suppliers, reshaping procurement strategies across the vendor landscape.
Pricing Analysis
REACH and RoHS enforcement dictates the pricing tier structure across the European supplier base, with certification-grade laboratory systems commanding substantial premiums over portable units lacking traceable documentation workflows. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified multi-technique platforms from automotive shop-floor handhelds and unbundled software subscriptions. Cost compression in the portable segment is intensifying because detector material bottlenecks constrain supply elasticity while recycling yards absorb price-sensitive volume. Tier-2 automotive suppliers in Bavaria exhibit the highest price sensitivity, whereas FAA-certified aerospace laboratories demonstrate minimal elasticity due to liability exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for detector component sourcing, with semiconductor fabrication concentrating in Taiwan, South Korea, and Japan. Spark OES instruments rest on helium purge systems tethered to Qatari liquefaction capacity, silicon drift detectors hinge on East Asian foundry output, and optical subassemblies feed from German and Japanese precision manufacturing clusters. Single-source vulnerability in helium supply creates allocation risk for laboratory-grade steel certification systems. Distribution runs through direct OEM sales for aerospace applications, regional distributor networks for automotive tier suppliers, and third-party certification laboratories bundling equipment with compliance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration service contracts and consumables procurement are expanding faster than hardware shipments, transforming vendor economics toward recurring revenue models. This service-attach dynamic rewards players who capture ongoing verification workflows rather than one-time instrument placements.
For Market Incumbents: Build certification moats around FAA and ECHA compliance documentation systems that lock aerospace OEMs into multi-year calibration protocols. Absorb R&D overhead for unified software platforms spanning XRF, spark OES, and combustion analysis to defend against portable commoditization. Add captive helium storage capacity or secure long-term offtake agreements to mitigate Qatari supply concentration threatening spark OES margins.
For New Entrants and Emerging Players: Build out battery recycling verification capabilities at European and North American lithium-ion recovery yards, where rapid lithium-cobalt-nickel fingerprinting demand outpaces established LIBS deployment. Target India's PLI-funded greenfield steel mills in Odisha and Karnataka with integrated XRF-OES verification lines. Partner with third-party testing laboratories to bundle hardware with NMPA compliance documentation for Western medical device exporters serving Chinese hospitals.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across laboratory-grade multi-technique configurations as detector fabrication bottlenecks and helium supply constraints tighten working capital requirements. The five-to-ten-year viability window favors platform integrators with mass spectrometry heritage over pure-play portable specialists facing handheld commoditization. Acquisition targets should demonstrate installed base density in aerospace or automotive certification hubs with attachable service revenue. Monitor ECHA enforcement intensity and FAA airworthiness directive expansion as inflection signals for compliance-driven replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Detector Technology Acquisition | Silicon drift detector fabrication access secures supply chain control for high-sensitivity portable production. |
| Helium Supply Partnership | Long-term offtake agreements with Qatari liquefaction capacity mitigate input cost volatility for spark OES instruments. |
| Software Platform Integration | Unified spectral interpretation workflows reduce customer switching costs and expand consumables attachment rates. |
| Battery Recycling Channel Development | European and North American lithium-ion recovery yards represent underpenetrated demand for handheld LIBS verification. |
| Certification Laboratory Partnership | Third-party testing bundling captures NMPA compliance service revenue from Western medical device exporters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment vendor disclosures to construct segment-level demand estimates. Primary interviews engaged quality control directors at automotive OEMs, aerospace certification engineers, recycling yard operators, and aftermarket service heads to validate deployment patterns and procurement timelines. Secondary sources included ECHA enforcement records, FAA airworthiness directives, NMPA medical device submissions, and SEC filings from analytical instrumentation conglomerates. Bottom-up equipment shipment tallies were cross-checked against top-down industrial testing expenditure surveys.
Forecast inputs incorporate technology adoption curves across portable, laboratory-grade, and fixed installation categories, segmented by end-use industry, deployment form factor, and regional regulatory cluster. Metal analysis, quality control, hazardous material detection, and polymer verification applications were modeled separately with distinct replacement cycle assumptions. CAGRs were derived from regression against industrial capital expenditure indices and regulatory enforcement intensity metrics. Helium supply concentration and detector fabrication capacity served as supply-side constraints in the projection framework.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified analytical instrumentation conglomerates or state-funded Chinese equipment vendors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Functional Acids Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Thin Film Materials Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functional Composites Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Smart Material Market