
 Ferroelectric Materials Market | 2026-2036
Ferroelectric Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Ferroelectric Materials Market Analysis
Project finance tied to semiconductor fabrication expansion is reconfiguring capital requirements for ferroelectric material suppliers. Sakai Chemical leverages captive barium titanate synthesis to sustain margin control across ceramic capacitor supply chains. Nippon Chemical anchors high-purity lead zirconate titanate output for Japanese memory foundries. Murata Manufacturing Co., Ltd. dominates multilayer ceramic capacitor integration, extending backward into proprietary powder formulations.
Ferroelectric materials exhibit spontaneous electric polarization reversible under applied external fields, with Curie temperatures and coercive field strength defining operational envelopes for memory and sensing applications. Barium titanate formulations occupy mature volume positions in ceramic capacitor manufacturing, while lead zirconate titanate thin films capture expanding share in ferroelectric random-access memory architectures. Strontium bismuth tantalate competes for niche aerospace sensor deployments where lead-free compliance carries premium positioning.
EPA hazardous substance rules and REACH Annex XVII restrictions on lead compounds shape formulation roadmaps across North American and European supply chains. Japan's METI directs domestic producers toward green material transitions through revised chemical substance management protocols. Stakeholders must monitor substitution timelines for lead-free perovskite alternatives against performance benchmarks in high-reliability applications.
Market Dynamics
Memory foundry procurement of lead zirconate titanate formulations is tightening purity specifications faster than reformulation cycles can accommodate, compressing supplier qualification timelines and fragmenting qualified vendor pools.
Growth Catalysts
- Non-volatile memory expansion:Ferroelectric RAM architectures in Japanese and South Korean fabrication clusters are absorbing specialized thin-film formulations at accelerating rates.
- REACH Annex XVII compliance deadlines:European capacitor manufacturers are stockpiling high-grade barium titanate ahead of phased lead restrictions, pulling forward volume commitments.
- Automotive sensor electrification:Strontium bismuth tantalate deployments in aerospace and defense sensing arrays are expanding addressable specifications for lead-free alternatives.
Market Restraints
- Raw material concentration:High-purity titanium dioxide feedstock concentrates among Chinese sulfate-process suppliers, exposing formulation costs to export license volatility.
- Coercive field limitations:Barium titanate's temperature-dependent polarization decay restricts operational envelopes in high-reliability automotive underhood applications.
- EPA hazardous substance rules:Lead-containing compositions face escalating disposal and worker exposure compliance burdens across North American manufacturing footprints.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor packaging are creating first-mover advantages for domestic ferroelectric material qualification.
- Thin-film deposition convergence:Atomic layer deposition integration with ferroelectric stack engineering is opening sub-10 nanometer memory cell geometries.
- Green chemistry mandates:Japan's METI chemical substance management protocols are accelerating R&D subsidies for perovskite alternative discovery.
Industry Challenges
- Specialized deposition technician scarcity:Pulsed laser deposition and metalorganic chemical vapor deposition expertise concentrates among legacy Japanese equipment specialists.
- Cleanroom capex intensity:Ferroelectric thin-film fabrication requires Class 1000 or better environments, constraining entry for mid-scale regional suppliers.
- Cross-border formulation IP:Perovskite composition patents held by Japanese and US research institutions complicate licensing for emerging market producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferroelectric Materials Market |
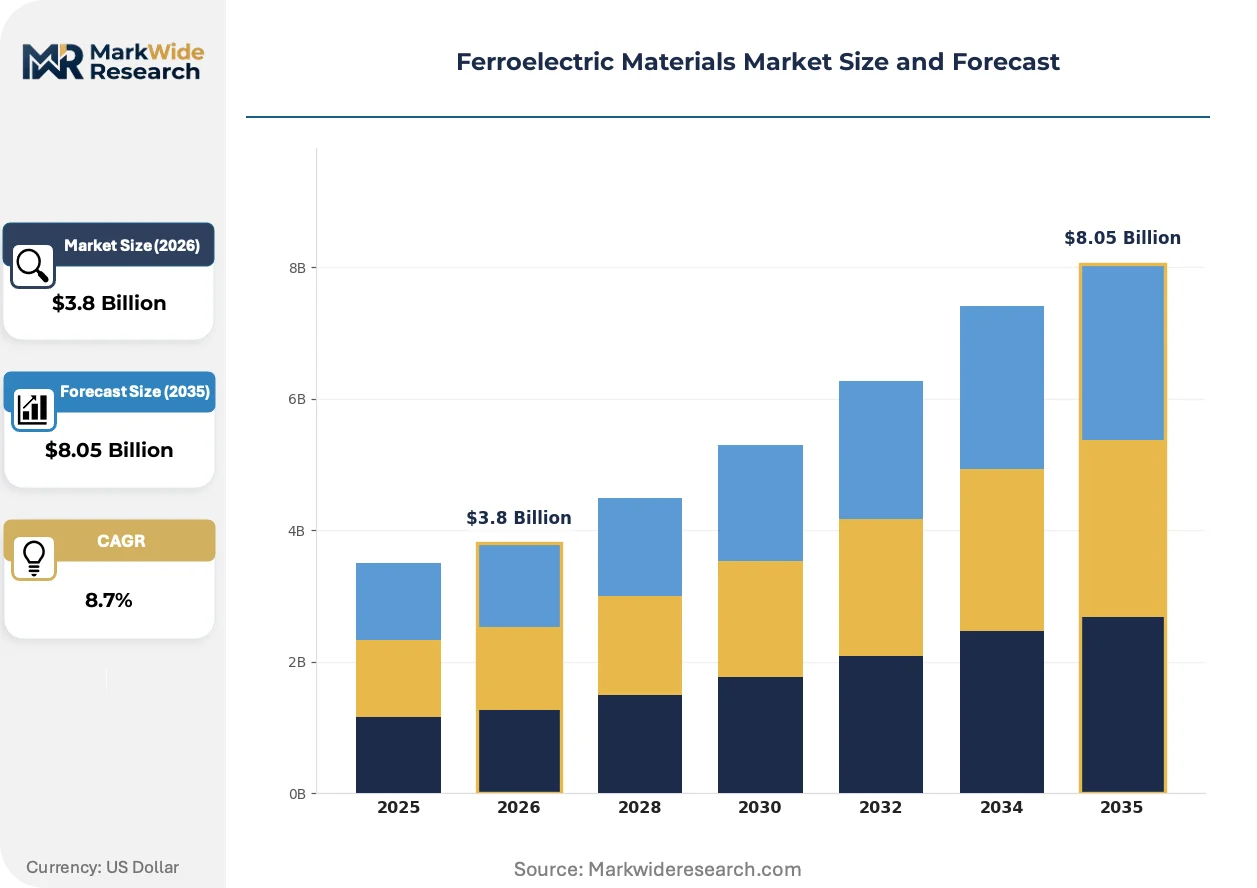
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Titanate, Lead Zirconate Titanate, Strontium Bismuth Tantalate, Others Application: Memory Devices, Sensors, Actuators, Energy Harvesting End User Industry: Automotive, Consumer Electronics, Aerospace, Telecommunications Form Factor: Thin Film, Ceramic, Single Crystal, Polycrystalline |
| Companies Covered | Sakai Chemical, Nippon Chemical, Ferro Corporation, Fuji Titanium, Shandong Sinocera, KCM Corporation, Shanghai Dian Yang, PI Ceramic GmbH, Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferroelectric Materials Market Emerging Trajectories
Hafnium oxide-based ferroelectrics are disrupting established material hierarchies through CMOS-compatible integration, while regulatory chemistry restrictions are accelerating substitution timelines beyond traditional qualification cycles.
Atomic layer deposition of hafnium zirconium oxide stacks is rendering obsolete conventional sol-gel lead zirconate titanate processing for embedded memory applications. Samsung and TSMC process engineers have integrated these films at 28 nanometer nodes and below. The technology is rendering obsolete capital-intensive sputtering equipment investments across European and North American pilot lines.
REACH Annex XVII lead compound restrictions are tightening purity certification requirements for capacitor-grade formulations entering European customs zones. Formulators must now document full material substance inventories through SCIP database submissions. High-reliability automotive and medical device segments are absorbing premium pricing for pre-certified green-alternative compositions.
Memory foundry buyers are consolidating qualified material suppliers into dual-source contracts with volume guarantees and technical co-development clauses. Direct procurement relationships are displacing traditional specialty chemical distributor networks in East Asian supply chains. This concentration is most visible in Japanese multilayer ceramic capacitor supply chains, where Murata and TDK have internalized powder formulation capabilities.
Ferroelectric Materials Market Segmentation
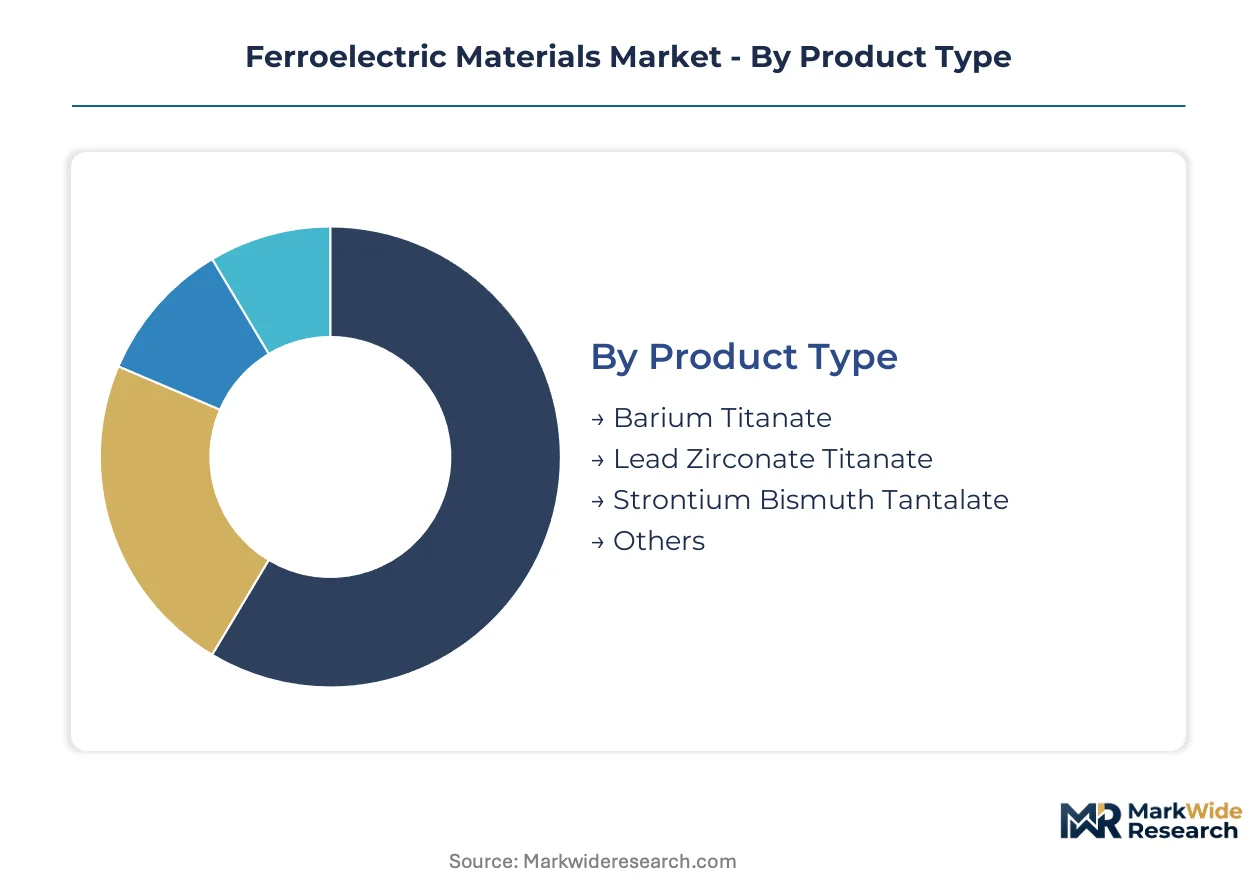
Segmentation in ferroelectric materials tracks how formulation chemistry, device architecture, and end-use reliability requirements create divergent supply chain configurations. Technical service intensity varies sharply across memory foundry thin-film procurement versus commodity ceramic capacitor supply.
Product Type:
After-sales technical support intensity scales with formulation complexity and regulatory certification burden, creating tiered service architectures across supplier portfolios.
- Barium Titanate:Perovskite-structured ceramic dominates multilayer capacitor manufacturing through dielectric constant stability and cost-efficient powder processing. Japanese and South Korean fabrication clusters absorb volume shipments for consumer electronics and automotive underhood applications, with REACH pre-certification now mandatory for European customs entry.
- Lead Zirconate Titanate:High remnant polarization and low coercive field make this the preferred thin-film formulation for ferroelectric RAM architectures. Memory foundries in Japan and South Korea are consolidating qualified suppliers into dual-source contracts with embedded technical co-development clauses and purity documentation through SCIP database submissions.
- Strontium Bismuth Tantalate:Layered perovskite structure delivers lead-free compliance for aerospace sensor arrays and defense applications where EPA hazardous substance rules restrict lead compound deployment.
- Others:Hafnium zirconium oxide and bismuth ferrite formulations are emerging through CMOS-compatible atomic layer deposition integration at sub-28 nanometer nodes.
By volume, Barium Titanate leads. By growth pace, Lead Zirconate Titanate is ahead.
Application:
Application-driven procurement patterns separate thin-film memory stack engineering from bulk ceramic commodity supply, with qualification timelines and technical service models diverging accordingly.
- Memory Devices:Ferroelectric RAM and embedded non-volatile storage require atomic layer deposition of hafnium zirconium oxide or pulsed laser deposition of lead zirconate titanate at sub-10 nanometer geometries. Japanese foundries and Samsung process lines are absorbing specialized thin-film formulations faster than European and North American pilot lines can qualify alternative deposition chemistries.
- Sensors:Piezoelectric transduction in automotive knock detection, aerospace pressure sensing, and medical ultrasound depends on temperature-stable polarization response. Strontium bismuth tantalate captures premium positioning in lead-free aerospace deployments where METI green chemistry protocols and REACH Annex XVII restrictions converge.
- Actuators:High-field strain response in precision positioning systems favors bulk ceramic or single-crystal lead zirconate titanate for industrial automation and optical equipment.
- Energy Harvesting:Vibration-to-electric conversion in wireless sensor networks exploits piezoelectric coupling coefficients in modified barium titanate compositions.
Memory Devices command the steepest expansion trajectory. Sensors maintain the most stable premium pricing architecture.
End User Industry:
End-use reliability specifications stratify supply chains, with automotive and aerospace demanding extended qualification documentation versus consumer electronics volume procurement.
- Automotive:Underhood temperature cycling requirements expose barium titanate's Curie temperature limitations, driving hybrid formulations and ceramic capacitor redundancy architectures. EPA hazardous substance rules and evolving NHTSA electrification standards are tightening material substance inventory requirements.
- Consumer Electronics:Smartphone and wearable multilayer ceramic capacitor consumption concentrates procurement leverage among Murata, TDK, and Samsung Electro-Mechanics, with backward integration into captive powder synthesis.
- Aerospace:Defense and satellite applications specify strontium bismuth tantalate for lead-free compliance combined with radiation-hard polarization stability.
- Telecommunications:Base station and optical network hardware relies on high-Q ceramic resonators and filter formulations with tight dielectric loss specifications.
Consumer Electronics generates the largest absolute volume. Automotive is climbing the fastest as electrification multiplies sensor and capacitor counts per vehicle.
Form Factor:
Manufacturing capital intensity and cleanroom requirements concentrate thin-film supply among legacy Japanese equipment specialists, while ceramic processing permits broader geographic dispersion.
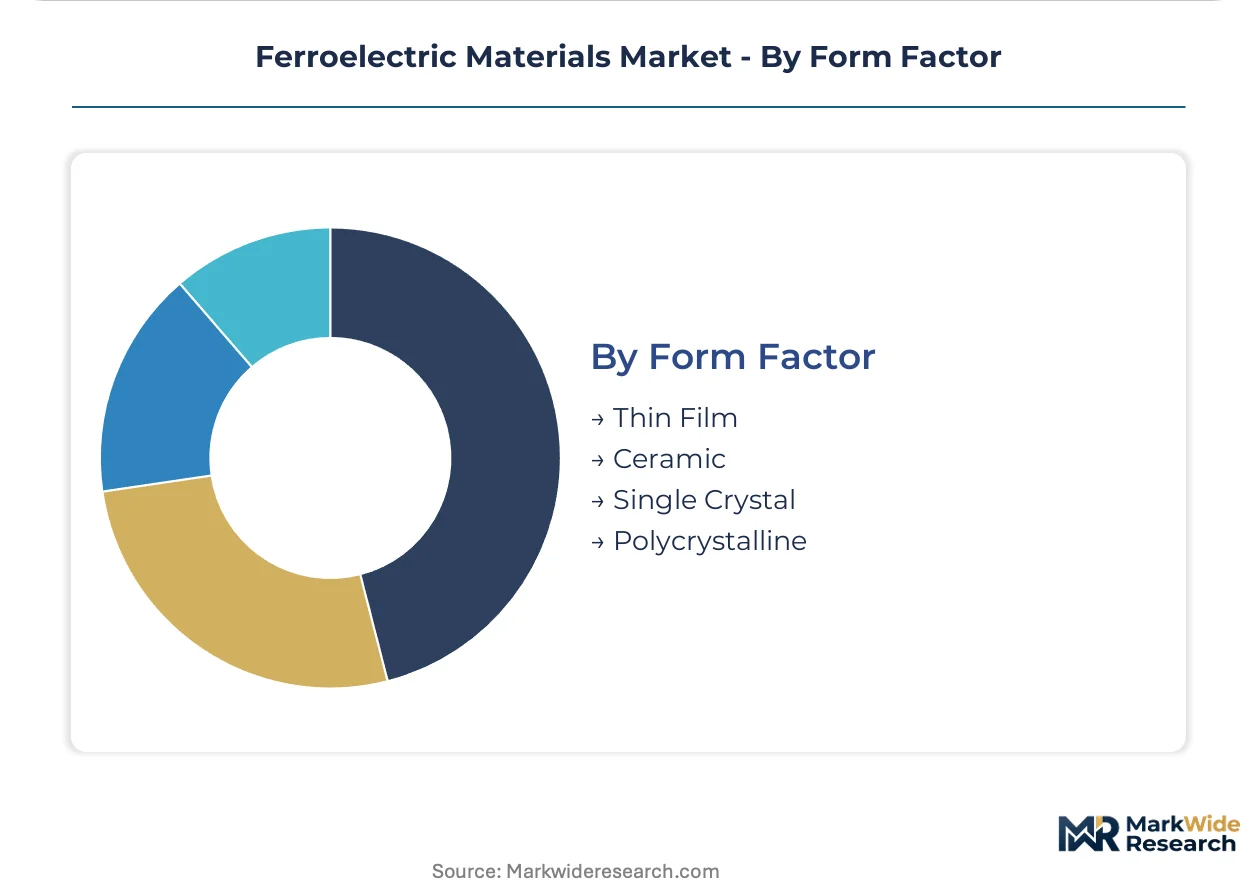
- Thin Film:Atomic layer deposition and pulsed laser deposition of hafnium zirconium oxide or lead zirconate titanate requires Class 1000 or better environments. Samsung and TSMC integration at 28 nanometer nodes and below is displacing sputtering equipment investments across European pilot lines.
- Ceramic:Tape casting and sintering of barium titanate multilayer structures scales efficiently for consumer electronics volume, with Sakai Chemical's captive synthesis sustaining margin control.
- Single Crystal:Czochralski and flux growth methods for high-purity lead zirconate titanate serve niche aerospace and medical ultrasound transducer applications.
- Polycrystalline:Sintered bulk ceramics for actuator and energy harvesting applications balance cost against electromechanical coupling efficiency.
Ceramic dominates current shipment volumes. Thin Film is expanding most quickly as embedded memory architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for high-purity titanium dioxide feedstock tilts trade balances toward Chinese sulfate-process suppliers, while Japanese and South Korean fabrication clusters drive outbound demand for specialized thin-film formulations. Memory foundry procurement patterns concentrate purchasing power in East Asian customs zones, with European REACH compliance costs reshaping cross-border shipment economics.
Japan
Memory device manufacturers in Tokyo and Osaka metropolitan areas absorb lead zirconate titanate formulations at accelerating rates for ferroelectric RAM architectures. METI chemical substance management protocols direct domestic producers toward green material transitions through revised substance inventories. The Kanto and Kansai industrial corridors host Murata Manufacturing and TDK captive powder synthesis operations that internalize ceramic capacitor supply chains.
South Korea
Samsung and SK Hynix process lines integrate hafnium zirconium oxide stacks at 28 nanometer nodes and below, displacing legacy sputtering equipment investments. The national semiconductor regulator enforces material substance documentation aligned with evolving export control frameworks. The Seoul Capital Area and Busan-Ulsan corridor concentrate atomic layer deposition cleanroom capacity for embedded memory pilot production.
United States
EPA hazardous substance rules escalate disposal and worker exposure compliance burdens for lead-containing compositions across North American manufacturing footprints. NHTSA electrification standards tighten material substance inventory requirements for automotive underhood capacitor deployments. The Pacific Northwest and Greater Boston maintain thin-film research clusters despite capital flight toward East Asian volume production.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify extended qualification documentation for multilayer ceramic capacitors in electrified powertrain architectures. ECHA REACH Annex XVII restrictions on lead compounds compress supplier qualification timelines for capacitor-grade formulations entering European customs zones. The Eindhoven-Randstadt corridor across the Dutch-German border hosts specialty chemical distributors managing SCIP database submissions.
China
Domestic sulfate-process suppliers concentrate high-purity titanium dioxide feedstock, exposing formulation costs to export license volatility and dual carbon goal compliance audits. MIIT industrial standards govern barium titanate powder specifications for consumer electronics multilayer capacitor manufacturing. The Yangtze River Delta and Pearl River Delta fabrication clusters absorb volume shipments while stockpiling inventory ahead of regulatory uncertainty.
Ferroelectric Materials Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in powder synthesis and thin-film deposition equipment. The vendor base organizes into three tiers: captive synthesis operations serving internal capacitor manufacturing, independent specialty chemical formulators, and equipment-integrated deposition service providers. Strategic differentiation concentrates on backward integration into barium titanate powder production and qualification speed for lead-free perovskite alternatives.
Among Japanese chemical specialists, Sakai Chemical and Nippon Chemical occupy positions representing captive synthesis and high-purity lead zirconate titanate supply archetypes respectively. Murata Manufacturing Co., Ltd. anchors the platform-integrator tier through backward integration into proprietary powder formulations. German precision ceramic fabricator PI Ceramic GmbH sits within the specialty component segment serving niche actuator and sensor applications.
| Leading Market Players |
|---|
| Sakai Chemical |
| Nippon Chemical |
| Ferro Corporation |
| Fuji Titanium |
| Shandong Sinocera |
| KCM Corporation |
| Shanghai Dian Yang |
| PI Ceramic GmbH |
| Murata Manufacturing Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta fabrication clusters concentrate barium titanate powder synthesis capacity, translating upstream chemical feedstock leverage into downstream pricing power for multilayer ceramic capacitor formulations. This geographic concentration shapes how memory foundries negotiate thin-film procurement contracts against commodity-grade ceramic supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by REACH pre-certification status and SCIP database documentation completeness. Price differentiation hinges on purity grade and volume scale, with automotive underhood specifications commanding premium positioning. Cost compression in standard-grade barium titanate is intensifying because Chinese sulfate-process suppliers face dual carbon goal compliance audits. Memory foundry procurement teams exhibit lowest price sensitivity due to embedded technical co-development clauses.
Supply Chain Analysis
Murata Manufacturing and TDK internalize captive powder synthesis operations, while Samsung and TSMC foundries dominate atomic layer deposition capacity for hafnium zirconium oxide integration. Geographic supply concentration centers on Japan, South Korea, and China for high-purity titanium dioxide feedstock and finished thin-film formulations. Raw material dependencies rest on sulfate-process titanium dioxide, high-grade barium carbonate, and zirconium oxychloride precursors. Single-source vulnerability concentrates in Chinese titanium dioxide export license volatility. Distribution runs through direct procurement relationships displacing specialty chemical distributor networks in East Asian supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized deposition expertise scarcity constrains supply expansion for sub-28 nanometer ferroelectric memory architectures, creating asymmetric returns for holders of pulsed laser deposition and atomic layer deposition technical capabilities.
For Market Incumbents: Harden qualification speed advantages for lead-free perovskite alternatives against hafnium oxide substitution threats by deepening R&D subsidies alignment with Japan's METI chemical substance management protocols. Consolidate dual-source contract structures with volume guarantees to lock out emerging thin-film deposition service providers. Prioritize backward integration into high-purity titanium dioxide sourcing to insulate margin structures from Chinese export license volatility. For New Entrants and Emerging Players: Establish a beachhead in Indian electronics manufacturing corridors where PLI scheme incentives for semiconductor packaging create first-mover qualification opportunities absent entrenched supplier relationships. Target aerospace sensor arrays specifying strontium bismuth tantalate for lead-free compliance, where EPA hazardous substance rules and REACH Annex XVII restrictions limit incumbent flexibility. Lead with technical co-development proposals rather than price competition to bypass volume-scale disadvantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thin-film deposition equipment-integrated service providers serving memory foundry dual-source contracts. Long-term viability over the mid-term projection horizon favors acquisition targets with captive barium titanate synthesis operations and SCIP database submission capabilities. Monitor hafnium zirconium oxide adoption rates at Samsung and TSMC process nodes as the critical inflection signal for lead zirconate titanate substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Feedstock | Insulates margin structures from Chinese sulfate-process export license volatility and dual carbon compliance audits. |
| Atomic Layer Deposition Capacity Expansion | Captures embedded memory demand from Samsung and TSMC at sub-28 nanometer nodes displacing legacy sputtering. |
| REACH Pre-Certification Investment | Unlocks European customs entry for capacitor-grade formulations ahead of Annex XVII phased lead restrictions. |
| Technical Co-Development Partnerships | Locks memory foundry procurement into dual-source contracts with embedded volume guarantees and IP sharing. |
| Green Perovskite Alternative R&D | Aligns with Japan's METI chemical substance management protocols and accelerates lead-free qualification timelines. |
Methodological Framework
A spread of perspectives from thin-film deposition equipment specialists, memory foundry process engineers, ceramic capacitor procurement leads, and specialty chemical formulators converged on the working assumptions underpinning this analysis. Primary fieldwork with atomic layer deposition technicians and multilayer ceramic capacitor plant managers was cross-checked against secondary validation from SEC filings of Japanese chemical specialists, MIIT industrial standard disclosures, and ECHA SCIP database submission patterns. Bottom-up volume triangulation from fabrication cluster absorption rates was reconciled with top-down value estimates across the analysis window.
Demand-supply balance modeling tracked formulation chemistry, device architecture, and end-use reliability requirements as segmentation dimensions, with additional granularity on cleanroom certification tier for thin-film supply. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of foundry capacity expansion announcements across the modeling period. Industry-specific forecast inputs included titanium dioxide export license issuance rates and METI green chemistry R&D subsidy allocations.
Stress conditions across Chinese dual carbon goal enforcement intensity, REACH Annex XVII implementation pacing, and hafnium zirconium oxide process yield improvements were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of Samsung and TSMC node migration announcements, ECHA substance restriction proposal timelines, and Indian PLI scheme beneficiary lists is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Global Smart Material Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Functional Acids Market
Functional Materials
Functional Composites Market
Functional Materials
Smart Card Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Thin Film Materials Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Flexible Thin Film Market