
 Asia-Pacific Lithium Foil Market | 2026-2036
Asia-Pacific Lithium Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lithium Foil Market Insights
China's dual carbon goals and Japan's battery subsidy frameworks are expanding the addressable market for high-purity lithium foil across the Asia-Pacific region. Ganfeng Lithium Co., Ltd leverages integrated spodumene-to-foil refining to sustain cost advantages in ultra-thin foil grades. Tianqi Lithium anchors Australasian feedstock security through long-term offtake positions. JX Nippon Mining & Metals Corporation competes on electrochemical consistency for solid-state cell prototypes.
Asia-Pacific lithium foil comprises rolled or cast lithium metal strips, typically ranging from sub-20-micron ultra-thin grades to 200-micron thick variants, serving primarily as anode material in next-generation batteries. The metal's low electrochemical potential and high specific capacity make it irreplaceable for lithium-metal and solid-state architectures. Coil-type and roll-type formats dominate volume flows into automated electrode coating lines, while ultra-thin foil commands premium positioning for solid-state prototypes where surface uniformity determines cycle life. Electronics and automotive end users represent the fastest-growing demand pools, with aerospace qualification timelines extending the addressable horizon.
China's MEE enforces wastewater and emissions standards on lithium conversion facilities, while Japan's METI coordinates battery supply chain resilience through domestic content requirements. South Korea's MFDS and KATS align with IEC 62660 cell safety protocols that propagate upstream to foil purity specifications. Stakeholders must track how China's GB standards evolution and Japan's JIS certification timelines for solid-state components reshape qualification barriers and sourcing geography across the region.
Market Dynamics
Solid-state battery developers in Japan and South Korea are accelerating procurement timelines for ultra-thin lithium metal anodes, compressing qualification cycles and forcing foil suppliers to synchronize rolling mill output with prototype cell builds.
Growth Catalysts
- Japan's battery subsidy frameworks:METI's domestic content requirements for next-generation cells are pulling high-purity foil through dedicated supply agreements with rolling specialists.
- Solid-state architectures:Sub-20-micron anode designs for lithium-metal batteries are creating specification premiums that reward surface uniformity capabilities.
- China's dual carbon goals:MEE emissions standards on conversion facilities are filtering out marginal producers and consolidating orders with integrated refiners.
Market Restraints
- Spodumene concentrate volatility:Australasian feedstock contract renegotiations are transmitting cost instability into foil rolling economics.
- Jiangsu-Fujian corridor concentration:Cathode and electrolyte clustering alongside foil mills creates geographic single-point vulnerability for just-in-time electrode coating lines.
- Surface oxide sensitivity:Lithium's atmospheric reactivity necessitates argon-environment handling that constrains throughput scaling.
Strategic Opportunities
- South Korea's KATS alignment with IEC 62660:Upstream propagation of cell safety protocols to foil purity specifications is creating certification-based supplier lock-in for early qualifiers.
- Aerospace qualification timelines:Extended certification cycles for aviation energy storage are extending addressable market horizons beyond automotive saturation curves.
- Coil-to-coil automation:Direct foil-to-electrode integration is eliminating intermediate slitting and winding steps for high-volume solid-state producers.
Industry Challenges
- Thin-rolling metallurgist scarcity:Sub-50-micron gauge control expertise resides with a narrow cohort of Japanese and Chinese specialists nearing retirement.
- GB standards evolution timing:Uncertainty around China's revised lithium metal purity classifications is freezing long-term contract pricing mechanisms.
- Argon recovery capex:Inert atmosphere rolling mill retrofits require capital commitments that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lithium Foil Market |
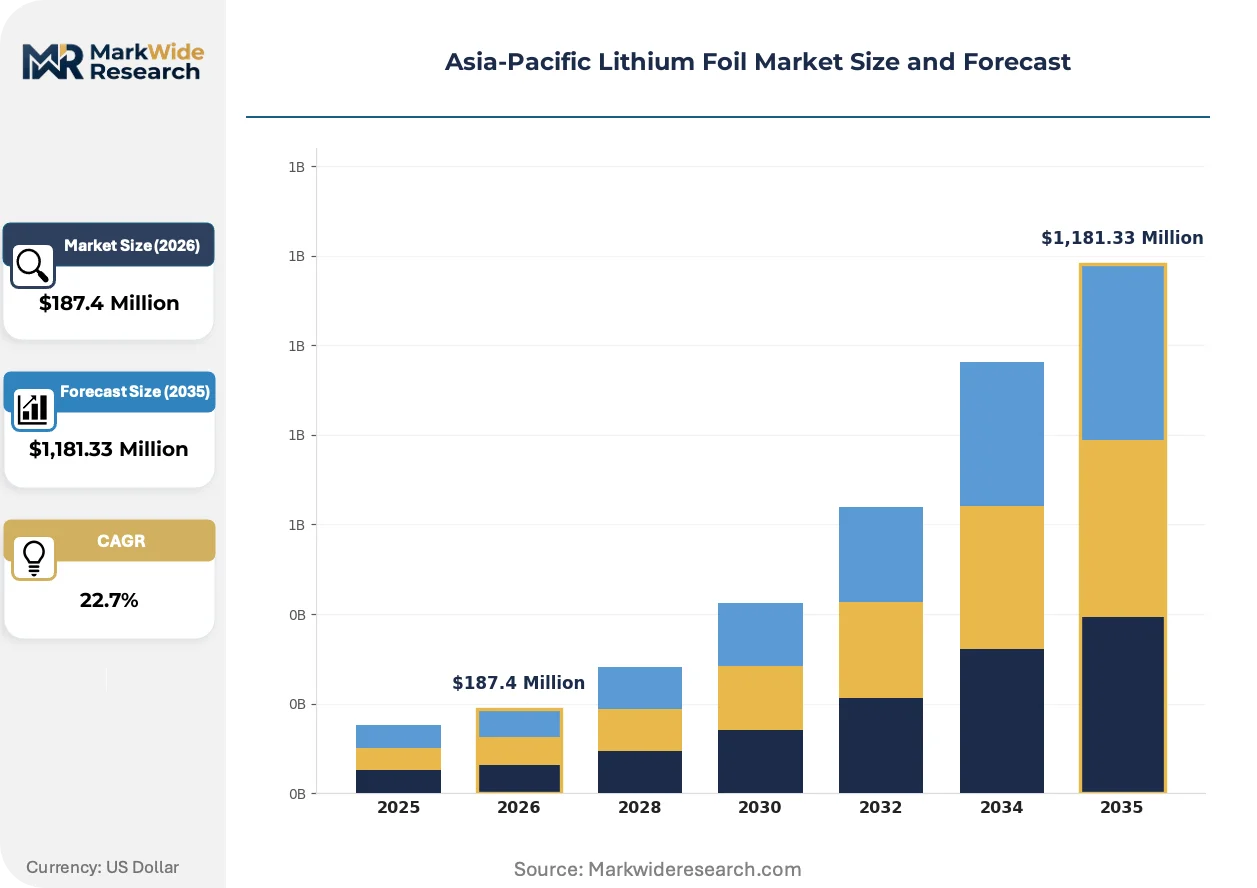
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Type, Sheet Type, Roll Type, Coil Type End User: Electronics, Automotive, Energy Storage, Aerospace Thickness: Thin Foil, Medium Foil, Thick Foil, Ultra-Thin Foil Application: Battery Manufacturing, Electrode Production, Conductive Coating, Heat Shielding |
| Companies Covered | China Energy Lithium Co., Ltd, Ganfeng Lithium Co., Ltd, Tianqi Lithium, CNNC Jianzhong, Hongwei Lithium, Honjo Metal Co., Ltd., UACJ Foil Corporation, Showa Denko, JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lithium Foil Market Trends and Innovations
Electrochemical consistency requirements from solid-state developers are compressing tolerance bands for thickness variation and surface roughness, forcing foil rolling operations to adopt semiconductor-grade process control.
Multi-layer composite foils incorporating lithium-silver or lithium-magnesium interlayers are unifying mechanical stability with ionic conductivity in single-strip formats. Solid-state prototype teams at Korean automotive OEMs are qualifying these variants for 2026 platform integration. This unifying architecture is collapsing the traditional separation between anode current collectors and active material deposition layers.
China's MEE enforcement of wastewater discharge limits on lithium conversion facilities is compelling rolling mills to install closed-loop brine recovery systems. The regulatory pressure is raising operational compliance costs by fifteen to twenty-five percent for non-integrated producers. Jiangsu-based suppliers are responding by consolidating upstream spodumene conversion in-house to capture effluent treatment economies.
Automotive cell manufacturers are consolidating supplier panels from six-to-eight foil vendors down to two-to-three qualified partners per platform. This concentration is displacing spot-market purchasing with multi-year offtake commitments indexed to lithium hydroxide benchmarks. The shift is most visible in Japan, where Toyota and Nissan procurement teams are negotiating five-year supply agreements with rolling specialists.
Asia-Pacific Lithium Foil Market Segmentation
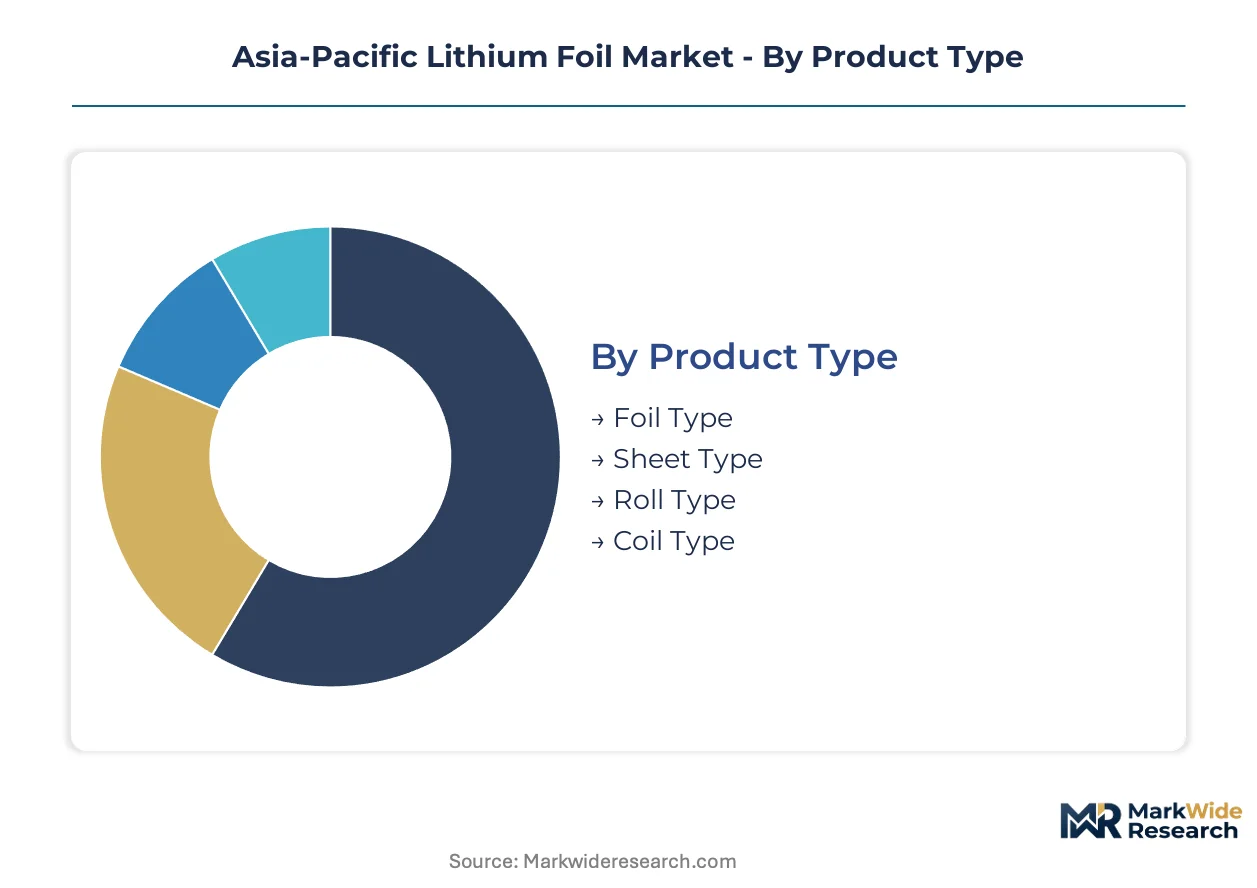
Lithium foil segmentation in Asia-Pacific reflects divergent purity and handling protocols across battery architectures. Certification requirements from Japan's METI and South Korea's MFDS propagate differently through each product tier, reshaping supplier qualification barriers.
Product Type:
Coil-type and roll-type formats face distinct certification burdens under Japan's JIS standards for automated electrode coating compatibility, while sheet-type variants navigate China's GB standards evolution for lithium metal classification.
- Roll Type:Continuous strip format wound on cylindrical cores, optimized for high-speed coating lines. Demand concentrates in South Korea's Gyeonggi battery cluster where Hyundai and Samsung SDI operations require seamless coil-to-coil automation for solid-state prototype builds.
- Coil Type:Large-diameter wound formats designed for direct electrode integration without intermediate slitting. Procurement is accelerating in Japan's Aichi prefecture where Toyota's solid-state pilot lines specify surface uniformity tolerances tighter than 0.5 microns.
- Foil Type:Standard cut-sheet and continuous strip variants serving conventional lithium-metal cell assembly.
- Sheet Type:Precut rectangular formats for manual electrode stacking in laboratory and pilot-scale environments.
Leading the category by volume: Coil Type. Growing fastest: Roll Type.
End User:
Cost tier stratification separates aerospace qualification timelines—where extended certification cycles support premium positioning—from automotive procurement where scale economies dominate supplier selection.
- Automotive:Cell manufacturers consolidating supplier panels from six-to-eight vendors down to two-to-three qualified partners per platform, displacing spot-market purchasing with multi-year offtake commitments indexed to lithium hydroxide benchmarks. Toyota and Nissan procurement teams in Japan are negotiating five-year supply agreements with rolling specialists.
- Electronics:Consumer device battery suppliers in China's Guangdong corridor drive specifications for sub-50-micron gauges where surface oxide sensitivity necessitates argon-environment handling that constrains throughput scaling.
- Energy Storage:Grid-scale battery integrators sourcing thicker foil grades for cost-optimized stationary applications.
- Aerospace:Aviation energy storage developers extending addressable market horizons beyond automotive saturation curves through extended qualification timelines for electrochemical consistency.
Dominating procurement spend: Automotive. Expanding most quickly: Electronics.
Thickness:
Application maturity separates ultra-thin grades—where sub-20-micron specifications command semiconductor-grade process control—from thick foil variants serving established lithium-metal battery architectures.
- Ultra-Thin Foil:Sub-20-micron gauges for solid-state prototypes where surface uniformity determines cycle life. Japan's METI domestic content requirements are pulling high-purity material through dedicated supply agreements with rolling specialists capable of thickness variation below 0.3 microns.
- Thin Foil:20-50 micron range capturing solid-state platform integration timelines at Korean automotive OEMs qualifying for 2026 production.
- Medium Foil:50-100 micron grades balancing mechanical handling stability with electrochemical performance.
- Thick Foil:100-200 micron variants for conventional lithium-metal cells where processing tolerance permits atmospheric handling with controlled humidity.
Highest specification premiums: Ultra-Thin Foil. Steepest volume expansion: Thin Foil.
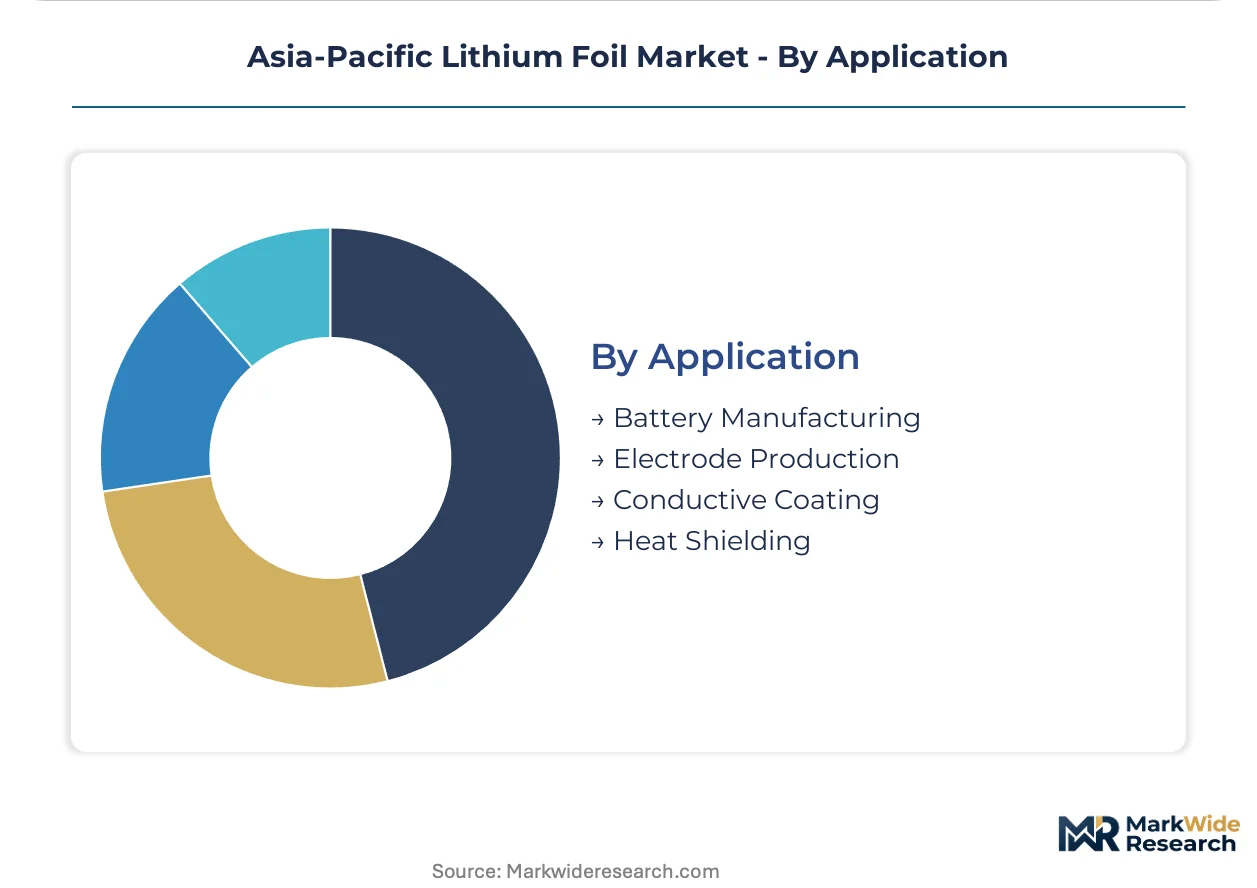
Application:
Supply concentration in Jiangsu and Fujian manufacturing corridors shapes electrode production demand, where cathode and electrolyte clustering alongside foil mills creates geographic single-point vulnerability for just-in-time coating lines.
- Battery Manufacturing:Direct cell assembly operations integrating lithium metal anodes into finished electrochemical storage devices. China's MEE wastewater enforcement is compelling rolling mills to install closed-loop brine recovery systems, raising operational compliance costs by fifteen to twenty-five percent for non-integrated producers in the Jiangsu-Fujian corridor.
- Electrode Production:Intermediate coating and calendering operations supplying finished anodes to cell manufacturers. South Korea's KATS alignment with IEC 62660 propagates cell safety protocols upstream to foil purity specifications, creating certification-based supplier lock-in for early qualifiers.
- Conductive Coating:Surface metallization applications for specialized current collector substrates.
- Heat Shielding:Thermal management applications leveraging lithium's thermal conductivity in aerospace and industrial contexts.
Commanding procurement volume: Battery Manufacturing. Gaining share fastest: Electrode Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Fujian provinces anchor Asia-Pacific lithium foil production, with cathode and electrolyte suppliers clustering alongside rolling mills in manufacturing corridors that feed automated electrode coating lines across the region.
China
Domestic solid-state battery developers in Suzhou and Ningde are scaling procurement of ultra-thin lithium metal anodes. The MEE enforces wastewater discharge limits on conversion facilities, filtering out marginal producers. Jiangsu-based suppliers consolidate upstream spodumene conversion in-house to capture effluent treatment economies.
Japan
Toyota and Nissan procurement teams in Aichi prefecture negotiate five-year supply agreements with rolling specialists for solid-state pilot lines. METI coordinates domestic content requirements through battery subsidy frameworks. Nagoya-area operations specify surface uniformity tolerances tighter than 0.5 microns for coil-type formats.
South Korea
Hyundai and Samsung SDI operations in Gyeonggi province drive demand for seamless coil-to-coil automation. The MFDS and KATS align with IEC 62660 cell safety protocols that propagate upstream to foil purity specifications. Busan-Ulsan corridor suppliers face compressed qualification cycles for 2026 platform integration.
Australia
Pilbara and Greenbushes spodumene concentrate operations transmit feedstock cost instability into regional foil rolling economics. Long-term offtake positions anchor Australasian supply security for integrated refiners. Perth-based traders renegotiate contract terms that cascade through Chinese conversion facilities.
Taiwan
Electronics battery suppliers in Hsinchu Science Park drive specifications for sub-50-micron gauges where surface oxide sensitivity constrains throughput scaling. Semiconductor-grade process control expertise migrates toward foil rolling operations. Taipei-based equipment vendors supply argon-environment handling systems to regional mills.
Asia-Pacific Lithium Foil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity and thickness specification tiers, with sub-20-micron ultra-thin grades commanding semiconductor-grade process control premiums. The vendor base stratifies into three archetypes: integrated spodumene-to-foil refiners capturing effluent treatment economies, rolling specialists competing on electrochemical consistency for solid-state prototypes, and commodity converters serving conventional lithium-metal architectures. Dominant competitive moves include backward integration into upstream feedstock positions and multi-year offtake commitments indexed to lithium hydroxide benchmarks.
Within the integrated refiner tier, Ganfeng Lithium Co., Ltd and Tianqi Lithium exemplify players capturing upstream economies through captive spodumene conversion. Among Japanese rolling specialists, JX Nippon Mining & Metals Corporation occupies a position competing on electrochemical consistency metrics for solid-state cell prototypes. These three anchors represent distinct strategic postures: feedstock security, surface uniformity capability, and metallurgical process control respectively.
| Leading Market Players |
|---|
| China Energy Lithium Co., Ltd |
| Ganfeng Lithium Co., Ltd |
| Tianqi Lithium |
| CNNC Jianzhong |
| Hongwei Lithium |
| Honjo Metal Co., Ltd. |
| UACJ Foil Corporation |
| Showa Denko |
| JX Nippon Mining & Metals Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive spodumene-to-foil integration anchors supply position and pricing power for Asia-Pacific lithium foil producers, with Jiangsu-based refiners capturing effluent treatment economies that commodity converters cannot replicate. China's MEE wastewater enforcement filters marginal producers while METI domestic content requirements in Japan pull premium material through dedicated supply agreements.
Pricing Analysis
Yield-based pricing tied to electrode coating throughput anchors contract structures, with sub-20-micron ultra-thin grades commanding semiconductor-grade premiums for solid-state prototypes. Three-tier pricing structure across ultra-thin, thin, and thick foil grades separates surface uniformity capabilities from atmospheric-handling tolerance. Cost compression in thick foil variants is intensifying because spodumene concentrate volatility transmits through Chinese conversion facilities. Automotive cell manufacturers show least price sensitivity for qualified ultra-thin supply, while grid-scale storage integrators drive hardest bargain on medium-thick grades.
Supply Chain Analysis
Certification gating under Japan's JIS standards and South Korea's KATS alignment with IEC 62660 propagates cell safety protocols upstream to foil purity specifications. Supply concentrates in China, Japan, and South Korea, with Jiangsu-Fujian manufacturing corridors feeding automated electrode coating lines across the region. Raw material dependencies draw from Australasian spodumene concentrate, argon gas supply for inert atmosphere handling, and precision rolling mill equipment. Single-source vulnerability concentrates in thin-rolling metallurgist expertise residing with Japanese and Chinese specialists nearing retirement. Distribution runs through direct mill-to-cell-manufacturer contracts displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific lithium foil is consolidating around integrated refiners as MEE emissions enforcement and METI domestic content requirements force commodity converters toward exit. Marginal producers lacking captive feedstock or certification capabilities face displacement.
For Market Incumbents: Deepen backward integration into Pilbara and Greenbushes spodumene positions to insulate rolling economics from concentrate contract volatility. Secure argon-environment rolling mill capacity before thin-gauge metallurgist scarcity intensifies. METI qualification timelines for solid-state components represent the critical certification lever to defend against Korean challengers. For New Entrants and Emerging Players: Begin with aerospace qualification pathways where extended certification cycles support premium positioning absent automotive scale requirements. Taiwan's Hsinchu electronics corridor offers penetrable white space for sub-50-micron gauge specialists. Partner with Taipei-based equipment vendors for argon-handling system deployment rather than building in-house metallurgical capability. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Japanese rolling specialists possessing JIS-certified surface uniformity capabilities. Five-to-ten year viability favors integrated refiners with Jiangsu production footprints and captive spodumene conversion. Watch for GB standards finalization on lithium metal purity classifications as inflection signal for contract pricing mechanism unfreezing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spodumene Feedstock | Captures effluent treatment economies under China's MEE enforcement for Jiangsu-based refiners. |
| JIS Certification Investment for Coil-Type Formats | Locks in Toyota and Nissan procurement teams for Aichi prefecture solid-state pilot lines. |
| Argon-Environment Rolling Mill Retrofit | Enables sub-20-micron gauge production for Korean automotive OEM 2026 platform integration. |
| Multi-Year Offtake Commitment Structuring | Displaces spot-market purchasing with lithium hydroxide benchmark indexing across automotive cell manufacturers. |
| Thin-Rolling Metallurgist Capability Acquisition | Addresses retirement-driven scarcity of sub-50-micron gauge control expertise in Japan and China. |
Research Methodology
Independent corroboration across rolling mill operations managers, cathode procurement leads at Korean cell manufacturers, and METI battery subsidy program administrators underwrites the qualitative findings. Primary fieldwork captured plant-level production data from Jiangsu-Fujian corridor facilities alongside regulatory interpretation from compliance officers. Secondary validation drew from customs/trade data on spodumene concentrate flows, SEC filings of listed lithium producers, GB standards evolution documentation, and IEC 62660 protocol amendments. Bottom-up foil production estimates triangulated against top-down battery cell demand projections.
Rate-of-change decomposition across the projection horizon separates volume growth from specification premium capture. Segmentation modeling incorporated product type, thickness grade, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from rolling mill capacity utilization curves weighted against solid-state platform integration timelines. Forecast inputs included spodumene contract renegotiation patterns and JIS certification pipeline visibility for coil-type formats.
Underlying measurement precision varies by segment; ultra-thin foil specifications carry tighter precision than thick foil commodity grades due to prototype-scale production visibility. Forecasts reflect assumptions on METI subsidy continuation and MEE enforcement intensity that could revise materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Global Smart Material Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Functional Composites Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Smart Card Materials Market
Functional Materials
Thin Film Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Functional Additives and Barrier Coatings Market