
 Chrome Plating Market | 2026-2036
Chrome Plating Market Size, Share, and Industry Trends Forecast 2026-2036
Chrome Plating Market Analysis
India's expanding automotive supplier base is reshaping regional sourcing patterns for decorative and hard chrome finishes. US Chrome leverages captive plating capacity across the Midwest to serve heavy equipment OEMs with consistent turnaround times. Pioneer Metal Finishing anchors its position through specialized aerospace approvals that competitors struggle to replicate. MacDermid Enthone dominates the chemistry supply layer, controlling proprietary trivalent bath formulations that reduce wastewater treatment burdens.
Chrome plating deposits a thin chromium layer onto metal substrates through electrochemical reduction, typically achieving thicknesses from 0.0001 inch for decorative finishes to 0.010 inch for industrial wear resistance. The process creates a hard, corrosion-resistant surface that extends component life in aggressive operating environments. Trivalent chrome chemistry now leads growth trajectories as environmental compliance tightens, while hard chrome plating occupies the margin pool in aerospace and oilfield applications where durability specifications are non-negotiable. Electroplating technology sustains volume leadership across automotive component lines, though vacuum plating gains traction in electronics for precision thickness control.
The EPA regulates hexavalent chromium emissions under the Clean Air Act National Emission Standards for Hazardous Air Pollutants, forcing facility-level abatement investments. OSHA's permissible exposure limits for hexavalent chromium in plating shops mandate engineering controls that elevate operating costs for legacy bath operators. REACH authorization requirements in the European Union restrict hexavalent compound use without demonstrated socioeconomic justification. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate chemistry portfolios accordingly.
Market Dynamics
REACH authorization requirements for hexavalent chromium compounds are forcing plating facilities across the European Union to retool entire production lines, while trivalent chemistry suppliers capture margin from this mandated transition.
Growth Catalysts
- Automotive OEM chassis demand:German and US manufacturers are expanding corrosion-resistant component orders as electric vehicle platforms require lighter, more durable underbody structures.
- REACH substitution mandate:The European Union's authorization framework is accelerating trivalent chrome bath conversions across plating lines that previously relied on hexavalent chemistry.
- Industrial machinery expansion:Domestic manufacturing capacity growth in China and India is concentrating demand for hard chrome finishes on hydraulic rods and machine tool surfaces.
Market Restraints
- Input cost volatility:Chromium metal prices fluctuate with South African mining output disruptions, compressing margins for decorative finish operators.
- Technical limitation:Trivalent chrome chemistry still cannot achieve the thickness and hardness specifications required for aerospace landing gear and oilfield drill components.
- Substitution threat:Physical vapor deposition coatings are capturing electronics and medical device applications where precision thickness control outweighs chrome's cost advantage.
Strategic Opportunities
- Underpenetrated aerospace aftermarket:MRO facilities in Singapore and the United Arab Emirates lack qualified hard chrome plating capacity for landing gear overhaul.
- Technology convergence:Integration of real-time bath monitoring with predictive maintenance systems is reducing chemistry waste and unplanned downtime.
- Regulatory tailwind:The US Inflation Reduction Act's domestic content incentives are pulling automotive supplier investment toward captive plating operations in Michigan and Ohio.
Industry Challenges
- Certification timeline compression:NADCAP accreditation for aerospace plating now requires 18-24 month validation cycles that delay contract awards.
- Capex intensity:Wastewater treatment upgrades for trivalent chrome conversion demand multi-million dollar investments that mid-tier job shops cannot finance.
- Talent scarcity:Experienced platers with hexavalent bath expertise are retiring faster than vocational programs can certify trivalent chemistry operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chrome Plating Market |
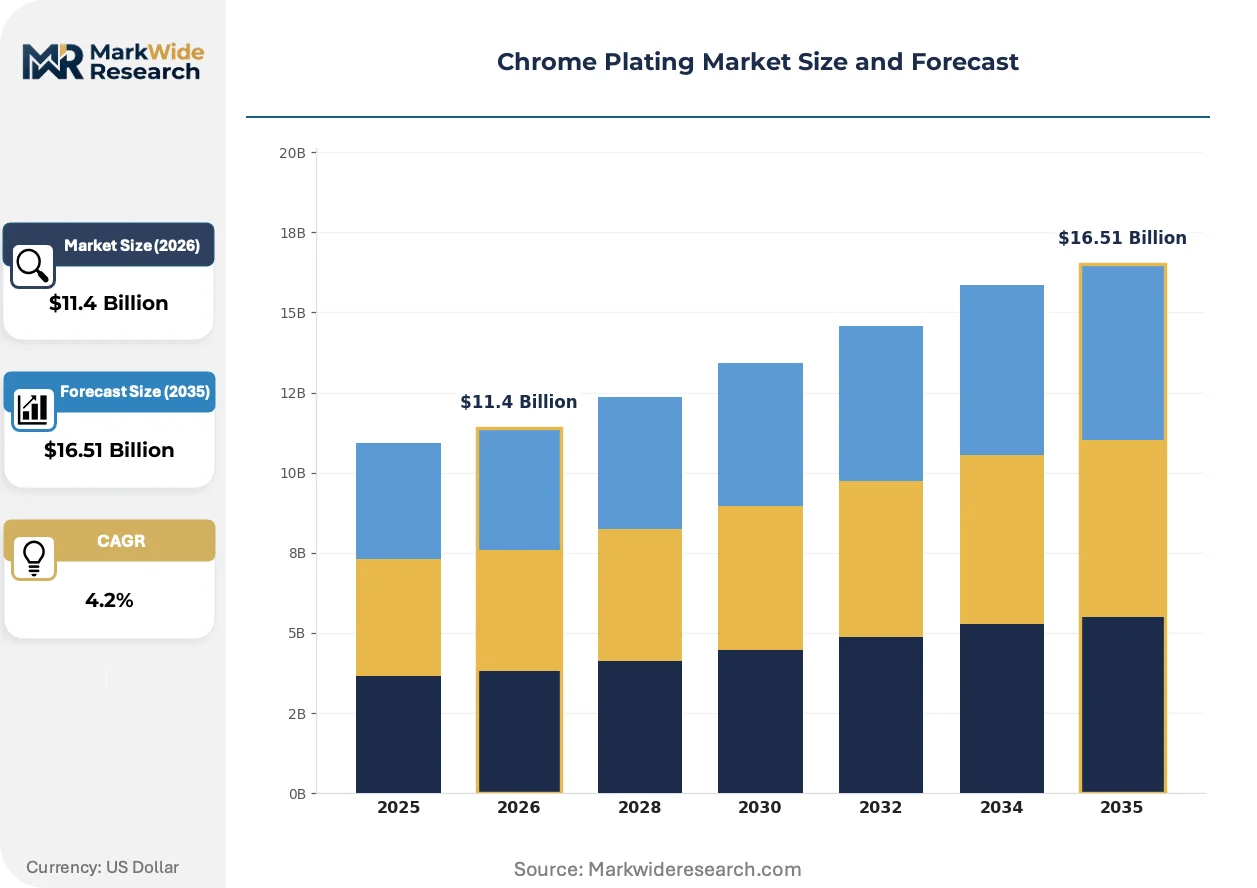
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Chrome, Hard Chrome, Trivalent Chrome, Hexavalent Chrome End User: Aerospace, Automotive, Electronics, Medical Devices Application: Industrial Machinery, Automotive Components, Household Fixtures, Aerospace Parts Technology: Electroplating, Vacuum Plating, Plasma Spraying, Spray Coating |
| Companies Covered | US Chrome, Pioneer Metal Finishing, MacDermid Enthone (Element Solutions), Interplex Industries, Allied Finishing, Atotech, Lincoln Industries, Sharretts Plating, Trinity Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chrome Plating Market Emerging Trajectories
Plating chemistry suppliers and equipment manufacturers are racing to close the performance gap between environmental compliance and industrial durability specifications.
Advanced trivalent chrome formulations with sulfate-based catalyst systems are achieving hardness values approaching hexavalent deposits. Automotive decorative trim suppliers in Germany and Japan are adopting these chemistries at scale despite 15-20% throughput penalties. The technology is rendering obsolete the regulatory exemption arguments that previously justified continued hexavalent use in consumer-facing applications.
EPA enforcement of the Clean Air Act National Emission Standards for Hazardous Air Pollutants is tightening hexavalent chromium emission limits for existing plating facilities. Shop owners face six-figure abatement investments or production curtailments. Hard chrome operators serving aerospace and defense are absorbing these costs while decorative finishers in California and Illinois exit the market.
Buyer concentration among Tier 1 automotive suppliers is compressing plating contract durations from multi-year frameworks to 12-18 month agreements with price reopeners. Heavy equipment OEMs in the US Midwest are consolidating vendor panels from twelve suppliers to four, demanding statistical process control data and dock-to-stock qualification. This pattern is most visible in Illinois and Ohio, where Caterpillar and Deere & Company procurement teams have implemented vendor scorecard systems that disqualify job shops without ISO 14001 certification.
Chrome Plating Market Segmentation
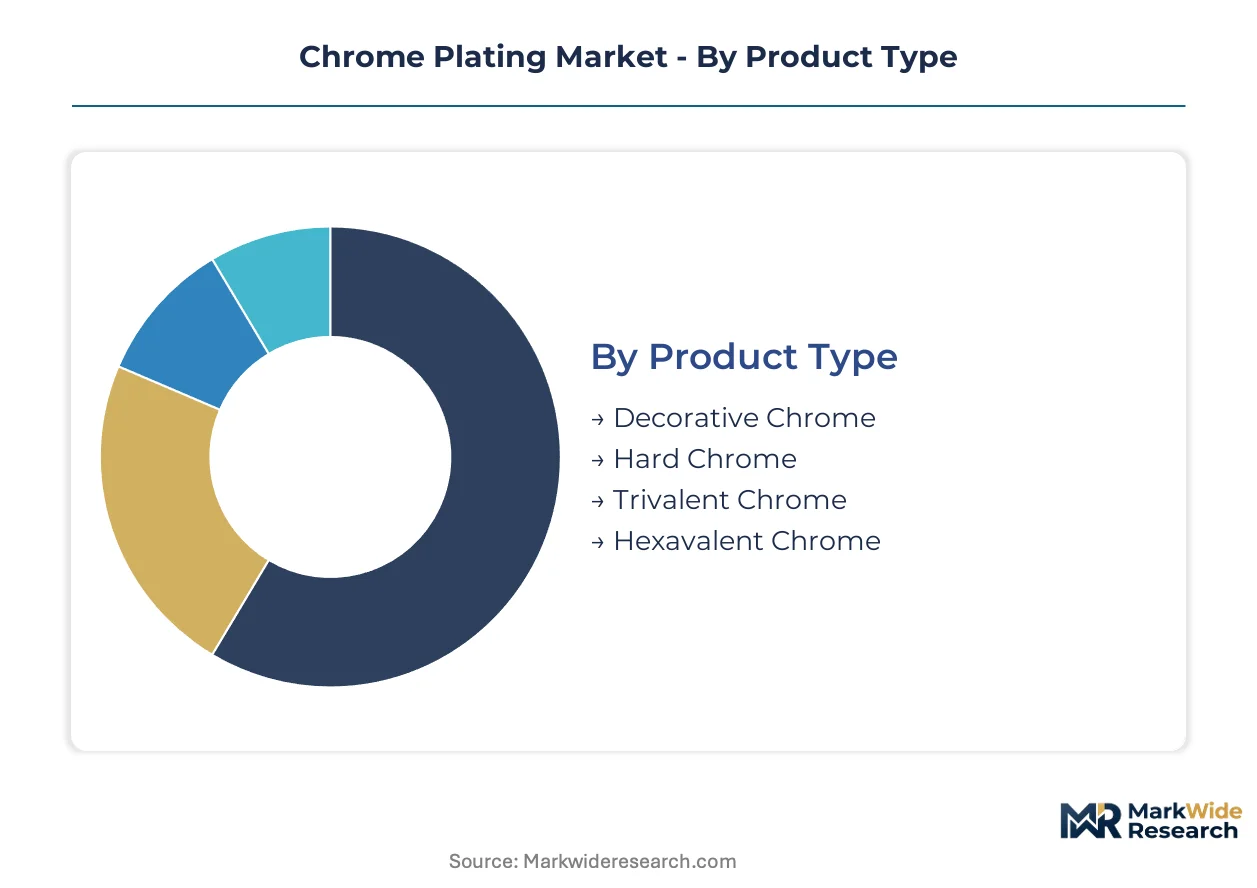
Chrome plating market segmentation reveals divergent margin structures and capital intensity across chemistry types and end-use verticals. Cycle times vary dramatically between decorative trim orders turning in weeks versus aerospace landing gear contracts spanning years.
Product Type:
Decorative chrome turns inventory fastest with automotive trim programs cycling quarterly, while hard chrome aerospace contracts lock capacity for 18-24 month qualification periods.
- Decorative Chrome:Thin deposits ranging 0.0001-0.0005 inch deliver mirror finishes on automotive trim and consumer goods. German OEMs in Stuttgart and Munich are expanding sulfate-based bright chrome specifications for electric vehicle exterior accents as platform weights drop.
- Hard Chrome:Engineering-grade deposits from 0.002-0.010 inch provide wear resistance for hydraulic cylinders and machine tools. Oilfield service companies in Texas and Louisiana are specifying thicker hard chrome on downhole drilling components as shale formations toughen.
- Trivalent Chrome:Reduced toxicity chemistry achieves decorative brightness with lower wastewater treatment burdens. REACH compliance deadlines in the European Union are accelerating bath conversions at plating facilities in France and Italy.
- Hexavalent Chrome:Legacy chemistry retains hardness supremacy for aerospace and defense specifications despite regulatory pressure. EPA enforcement under the Clean Air Act National Emission Standards for Hazardous Air Pollutants is forcing abatement investments at US-based hard chrome operators.
Hard chrome anchors the volume base while trivalent chrome gains share at the steepest rate.
End User:
Customer concentration and certification requirements create four distinct margin tiers, with aerospace commanding premium pricing against commoditized electronics applications.
- Aerospace:NADCAP-accredited plating for landing gear and engine components demands 130,000-150,000 psi deposit hardness. MRO facilities in Singapore lack qualified hard chrome capacity for regional landing gear overhaul demand.
- Automotive:Tier 1 suppliers in Michigan and Ohio specify decorative chrome for grilles and mirror housings with 12-18 month contract durations. The US Inflation Reduction Act's domestic content incentives are pulling supplier investment toward captive plating operations.
- Electronics:Precision thickness requirements favor vacuum plating over electroplated chrome for connector and shielding applications. Physical vapor deposition coatings are capturing smartphone and medical electronics share where nanometer control outweighs cost.
- Medical Devices:Biocompatibility standards restrict hexavalent chrome in surgical instruments and implantable components. FDA 510(k) pathways for chrome-plated devices require extensive cytotoxicity validation.
Automotive anchors the volume base while aerospace commands the steepest pricing premiums.
Application:
Operating environment severity determines specification stringency, with aerospace parts facing salt spray requirements tenfold stricter than household fixtures.
- Industrial Machinery:Hard chrome on hydraulic rods and machine tool surfaces extends service life in abrasive environments. Domestic manufacturing expansion in China and India is concentrating demand for heavy equipment refurbishment.
- Automotive Components:Chassis and underbody hardware require corrosion resistance for 10-year warranty compliance. German and US manufacturers are expanding orders for corrosion-resistant components as electric vehicle platforms require lighter underbody structures.
- Household Fixtures:Decorative chrome on faucets and lighting delivers aesthetic durability at commodity price points. Input cost volatility from South African chromium supply disruptions compresses margins for decorative finish operators.
- Aerospace Parts:Landing gear and actuator components require fatigue-resistant deposits meeting AMS 2460 specifications. Certification timeline compression now demands 18-24 month NADCAP validation cycles that delay contract awards.
Industrial machinery anchors the volume base while aerospace parts expand most quickly on aftermarket demand.
Technology:
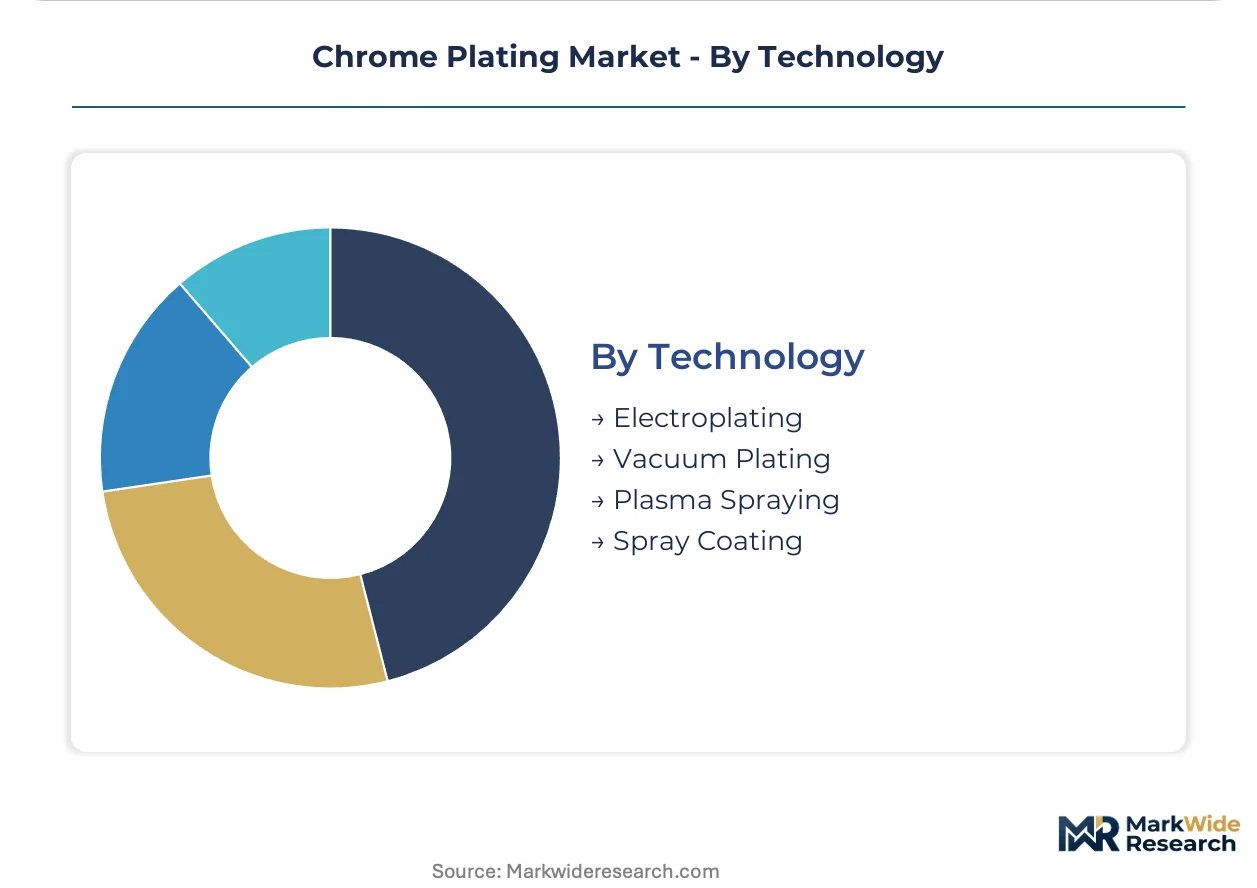
Capital intensity and throughput rates separate batch electroplating from continuous vacuum systems, with plasma spraying occupying a narrow niche for extreme temperature applications.
- Electroplating:Immersion-based chromium reduction in sulfate or fluoride baths remains the volume leader across automotive and industrial applications. Real-time bath monitoring integration is reducing chemistry waste and unplanned downtime.
- Vacuum Plating:Physical vapor deposition achieves angstrom-level thickness control for electronics and precision optics. The technology is capturing medical device applications where chrome's cost advantage previously dominated.
- Plasma Spraying:Thermal spray processes deposit chrome carbide composites for extreme wear and temperature resistance. Applications concentrate in gas turbine components and steel rolling mill equipment.
- Spray Coating:Cold spray and HVOF alternatives offer portable repair solutions for field-service hydraulic cylinder refurbishment. The technology is displacing tank-based plating for oversized components that cannot be transported.
Electroplating anchors the volume base while vacuum plating climbs the fastest on electronics precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany favor decorative trivalent chrome for electric vehicle exterior accents, while hard chrome dominates aerospace landing gear specifications in the United States. Industrial machinery demand concentrates in China's manufacturing belts and India's supplier corridors. REACH restrictions in the European Union accelerate chemistry conversions that diverge from EPA enforcement patterns in North America.
United States
Caterpillar and Deere procurement teams in Illinois and Ohio consolidate vendor panels from twelve suppliers to four, demanding ISO 14001 certification and statistical process control data. EPA enforcement under the Clean Air Act National Emission Standards for Hazardous Air Pollutants forces six-figure abatement investments at hard chrome operators. US Chrome leverages captive plating capacity across the Midwest to serve heavy equipment OEMs with consistent turnaround times.
Germany
Stuttgart and Munich OEMs expand sulfate-based bright chrome specifications for electric vehicle exterior accents as platform weights drop. REACH authorization requirements for hexavalent chromium compounds force retooling across plating facilities in Bavaria and Baden-Württemberg. KBA vehicle certification standards reinforce quality thresholds that favor established chemistry suppliers with validated trivalent bath formulations.
China
Domestic manufacturing capacity expansion concentrates demand for hard chrome finishes on hydraulic rods and machine tool surfaces across Yangtze River Delta industrial zones. MIIT emission standards for electroplating operations tighten discharge limits that elevate wastewater treatment investments. Shanghai and Jiangsu plating clusters absorb technology upgrades faster than inland provinces, widening regional capability gaps.
India
Expanding automotive supplier bases in Maharashtra and Tamil Nadu reshape regional sourcing patterns for decorative and hard chrome finishes. BIS standards for surface treatment quality create compliance thresholds that disqualify unorganized sector job shops. Pune and Chennai industrial corridors attract captive plating investments from Tier 1 component manufacturers serving export markets.
Singapore
MRO facilities lack qualified hard chrome plating capacity for regional landing gear overhaul demand from Southeast Asian airline fleets. The country's national aviation regulator maintains alignment with FAA and EASA standards that require NADCAP-accredited suppliers. Seletar Aerospace Park anchors maintenance operations that must source plating services from qualified vendors in Australia or the United States.
Chrome Plating Market Vendor Landscape
Capability concentration sits with chemistry suppliers controlling proprietary trivalent formulations; scale advantage sits with captive plating operators serving automotive OEMs with dedicated capacity. The market structures around three tiers: integrated chemical-process providers, regional job shop networks, and specialized aerospace-accredited finishers. Strategic moves center on bath chemistry licensing partnerships and captive capacity expansion near OEM assembly plants.
Among chemistry-integrated providers, MacDermid Enthone and Atotech occupy positions defined by proprietary trivalent bath formulations that reduce wastewater treatment burdens for licensee operations. US Chrome exemplifies the captive capacity archetype with Midwest-based plating operations positioned for heavy equipment OEM service. Pioneer Metal Finishing anchors the specialized tier through aerospace approvals that competitors struggle to replicate.
| Leading Market Players |
|---|
| US Chrome |
| Pioneer Metal Finishing |
| MacDermid Enthone (Element Solutions) |
| Interplex Industries |
| Allied Finishing |
| Atotech |
| Lincoln Industries |
| Sharretts Plating |
| Trinity Holdings |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Singapore's aerospace MRO plating sector is compressing turnaround premiums while forcing buyers toward distant qualified suppliers, simultaneously elevating spot pricing for emergency hard chrome work and incentivizing captive capacity investments near OEM assembly plants.
Pricing Analysis
Contract structures in chrome plating split between long-term offtake agreements for automotive Tier 1 programs and spot-market transactions for aerospace MRO emergencies. Pricing stratifies across NADCAP-accredited aerospace tiers, ISO-certified automotive standards, and unaccredited decorative job shops. Cost compression in decorative finishes is intensifying because South African chromium supply disruptions feed raw material volatility. Electronics buyers exhibit highest price sensitivity as physical vapor deposition coatings narrow chrome's cost advantage.
Supply Chain Analysis
Contract manufacturing concentration sits with MacDermid Enthone and Atotech controlling proprietary trivalent bath formulations licensed across plating networks. Chromium metal supply draws from South African mining operations, Chinese refining capacity, and Turkish ferrochrome production. Single-source vulnerability concentrates in sulfate-based catalyst systems for advanced trivalent chemistries. Distribution runs through regional chemical distributors serving captive OEM plating lines and independent job shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive procurement teams that compressed vendor panels from twelve suppliers to four in Illinois and Ohio, extracting statistical process control requirements and dock-to-stock qualification as price conditions.
For Market Incumbents: Insulate aerospace margins by deepening NADCAP accreditation moats before 18-24 month validation cycles lock out competitors. Prioritize backward integration into trivalent chemistry supply through licensing partnerships with MacDermid Enthone or Atotech to capture REACH-driven conversion demand. Physical vapor deposition substitution in electronics and medical devices threatens decorative finish volumes; redirect capacity toward hard chrome oilfield and aerospace specifications where thickness requirements bar alternatives. For New Entrants and Emerging Players: Establish a beachhead in Singapore's underpenetrated aerospace MRO plating market where regional landing gear overhaul demand exceeds qualified hard chrome capacity. Target captive plating investments in Michigan and Ohio leveraging US Inflation Reduction Act domestic content incentives pulling automotive supplier investment. Lead with real-time bath monitoring integration as a service differentiator reducing chemistry waste and unplanned downtime for mid-tier job shops. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chemistry-integrated providers controlling proprietary trivalent formulations through licensing arrangements rather than capital-intensive plating operations. Long-term viability favors specialized aerospace-accredited finishers with NADCAP credentials that competitors cannot replicate within a standard investment horizon. Monitor EPA enforcement patterns under the Clean Air Act National Emission Standards for Hazardous Air Pollutants as an inflection signal for decorative finish exit acceleration and hard chrome operator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chemistry Licensing Partnership | MacDermid Enthone and Atotech formulations reduce wastewater burdens for REACH-compliant EU plating lines. |
| Captive Capacity Expansion | US Chrome leverages Midwest plating operations to serve Caterpillar and Deere with consistent turnaround. |
| NADCAP Accreditation Investment | Pioneer Metal Finishing anchors aerospace positioning through approvals competitors struggle to replicate. |
| Real-Time Bath Monitoring Integration | Predictive maintenance systems reduce chemistry waste and unplanned downtime across electroplating lines. |
| Aerospace MRO Geographic Expansion | Singapore facilities lack qualified hard chrome capacity for Southeast Asian airline fleet overhaul demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plating facility managers, automotive Tier 1 procurement leads, aerospace MRO operations directors, chemical formulation R&D heads, and environmental compliance officers. Secondary validation drew from EPA enforcement records, REACH authorization databases, SEC 10-K filings from listed chemical companies, and customs trade data on chromium metal flows. Bottom-up capacity assessments across plating facilities were triangulated against top-down chemical consumption estimates.
Calibration against historical capacity utilization rates and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry type, end-use vertical, application severity, and technology platform, with additional granularity on certification tier. CAGRs were derived from elasticity-adjusted demand curves incorporating OEM production forecasts and substitution dynamics. Key inputs included South African mining output volatility patterns and REACH compliance deadline acceleration scenarios.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, chromium commodity prices, or regulatory enforcement intensity would shift the trajectory. Quarterly review of EPA penalty issuance rates, EU authorization application volumes, and NADCAP accreditation queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Global Industrial Separators Market