
 Rapid Self-Healing Gel Market | 2026-2036
Rapid Self-Healing Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Self-Healing Gel Market Analysis
ISO 10993 biocompatibility certification is collapsing the qualification timeline for new entrants, forcing smaller developers to partner with established testing laboratories before commercialization. Cardinal Health leverages its hospital distribution network to sustain volume leadership across North American wound care channels. Hydromer Inc. anchors its position through specialized coating chemistry expertise that extends into gel-based barrier applications.
Rapid self-healing gel comprises cross-linked polymer networks, typically silicone or polyurethane matrices, that autonomously restore structural integrity after mechanical damage through dynamic covalent or non-covalent bond reformation; these materials functionally seal wounds, protect electronic components, or repair automotive coatings without external intervention. Silicone gel dominates medical applications due to established clinical acceptance and favorable moisture vapor transmission rates, while gel with microcapsules represents the fastest-expanding category as encapsulated healing agents enable multi-cycle repair functionality in electronics protection. Polyurethane gel occupies the automotive repairs segment where abrasion resistance and paint compatibility determine specification adherence.
FDA biocompatibility requirements under ISO 10993 and the EU MDR framework govern medical-grade gel approvals, with REACH compliance adding material disclosure obligations for European manufacturers. Japan's PMDA enforces additional local clinical testing protocols that extend market access timelines for foreign suppliers. Stakeholders must monitor evolving polymer substance restrictions under ECHA and FDA guidance updates to anticipate reformulation costs and qualification bottlenecks.
Market Dynamics
ISO 10993 biocompatibility certification timelines are compressing competitive entry windows, forcing capital-light developers into laboratory partnerships and redistributing margin capture toward established testing infrastructure holders.
Growth Catalysts
- EU MDR compliance mandates:Hospital procurement departments in Germany now require ISO 10993-5 cytotoxicity documentation for wound care gel contracts, accelerating replacement of legacy silicone dressings.
- Microcapsule chemistry advances:Multi-cycle repair functionality in electronics protection gels is unlocking industrial maintenance budgets previously allocated to component replacement.
- Japan PMDA pathway formalization:Local clinical testing protocols, though extending timelines, are creating predictable qualification roadmaps that reduce regulatory uncertainty for compliant entrants.
Market Restraints
- Silicone feedstock concentration:Dow and Wacker Chemie control over 60% of medical-grade silicone precursor supply, exposing formulators to input cost volatility and allocation risk.
- Polyurethane technical ceiling:Abrasion-resistant automotive repair gels face hard limits on paint compatibility across OEM clear coat chemistries, constraining specification breadth.
- REACH substance disclosure:ECHA polymer restriction updates force European manufacturers into costly reformulation cycles without grandfathering provisions.
Strategic Opportunities
- Underpenetrated US outpatient wound clinics:Freestanding ambulatory surgical centers in Texas and Florida lack dedicated gel formulary managers, creating first-mover advantage for direct distribution models.
- China NMPA Class II pathway:Streamlined biocompatibility recognition for ISO 10993-tested materials is shortening market access for foreign gel manufacturers with existing EU or US approvals.
- Convergence with printed electronics:Self-healing gel integration into flexible circuit substrates enables repairable wearable health monitors, opening device OEM partnerships.
Industry Challenges
- Cross-functional talent scarcity:Polymer chemists with simultaneous expertise in dynamic covalent bond chemistry and FDA 510(k) documentation command premium compensation, constraining R&D scaling.
- ISO 10993-18 material characterization:Extractables and leachables testing for novel gel formulations extends certification timelines by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Self-Healing Gel Market |
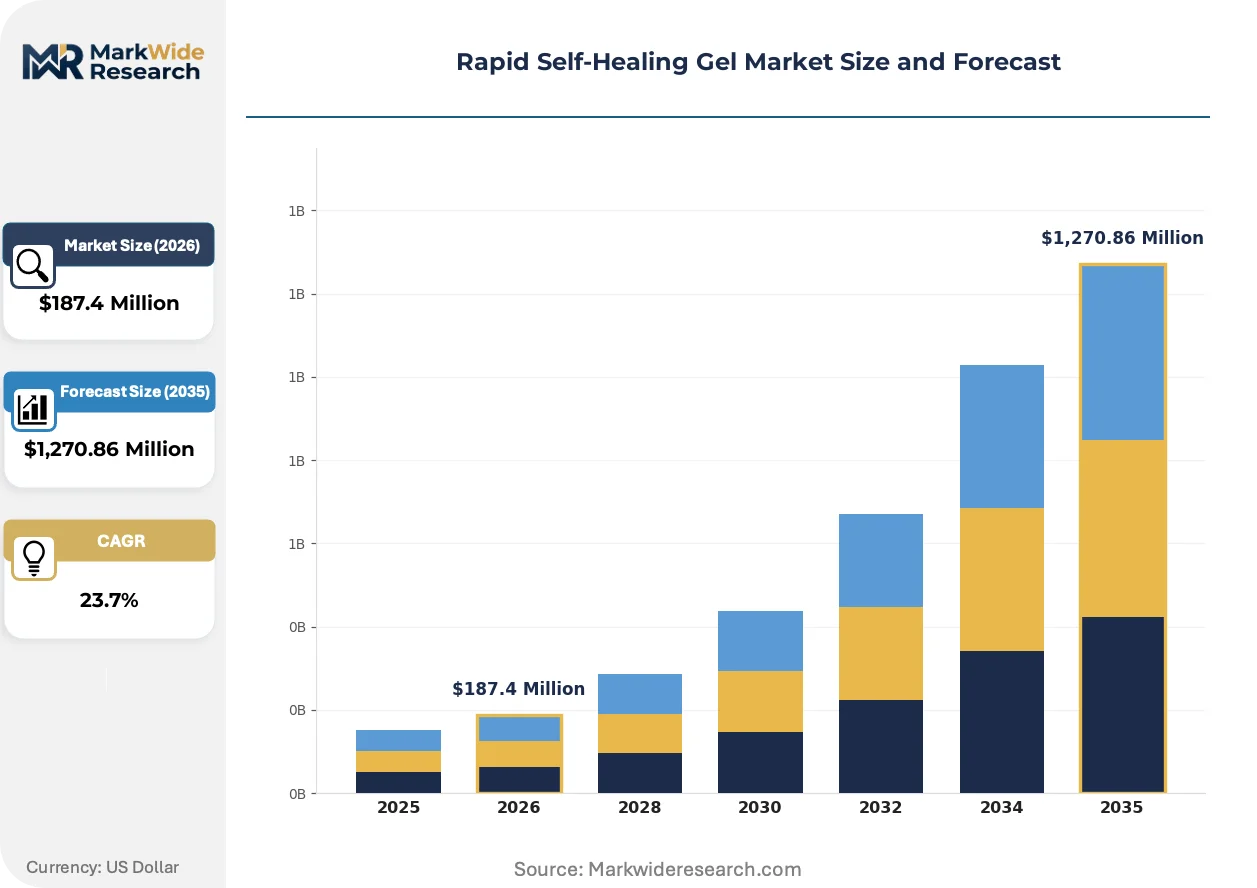
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Polyurethane Gel, Acrylic Gel, Gel with Microcapsules Application: Medical Wound Care, Cosmetic Applications, Automotive Repairs, Electronics Protection End User: Hospitals, Clinics, Cosmetic Manufacturers, Electronics Companies Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Advanced Medical Solutions Group PLC, Cardinal Health, Axelgaard Manufacturing, Scapa Healthcare, Hydromer Inc., Alliqua Biomedical, Contura International, Cytogel Pharma, Katecho Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Self-Healing Gel Market Emerging Trajectories
Dynamic bond chemistry and regulatory data recognition agreements are actively redistributing competitive advantage from raw material suppliers toward integrated testing-formulation entities.
Microcapsule-embedded self-healing gel is bifurcating the electronics protection segment. Industrial maintenance teams at semiconductor fabrication facilities are adopting these materials for multi-cycle substrate repair. The technology is compressing capital expenditure cycles previously dedicated to cleanroom component replacement, shifting spend toward consumable gel formulations.
REACH polymer restriction updates under ECHA consultation are forcing reformulation investments. European manufacturers must disclose substance volumes above 1 tonne annually, triggering supply chain audits for cross-linked network precursors. Medical-grade gel producers with established ISO 10993-18 characterization datasets are accelerating compliance, while smaller compounders face qualification bottlenecks.
Hospital procurement departments are consolidating wound care gel suppliers around documented biocompatibility credentials. Group purchasing organizations in the United States now weight ISO 10993 certification scores above unit pricing in formulary decisions. This behavioral shift concentrates contract awards among three to four testing-integrated manufacturers, marginalizing distributors without laboratory partnerships.
Rapid Self-Healing Gel Market Segmentation
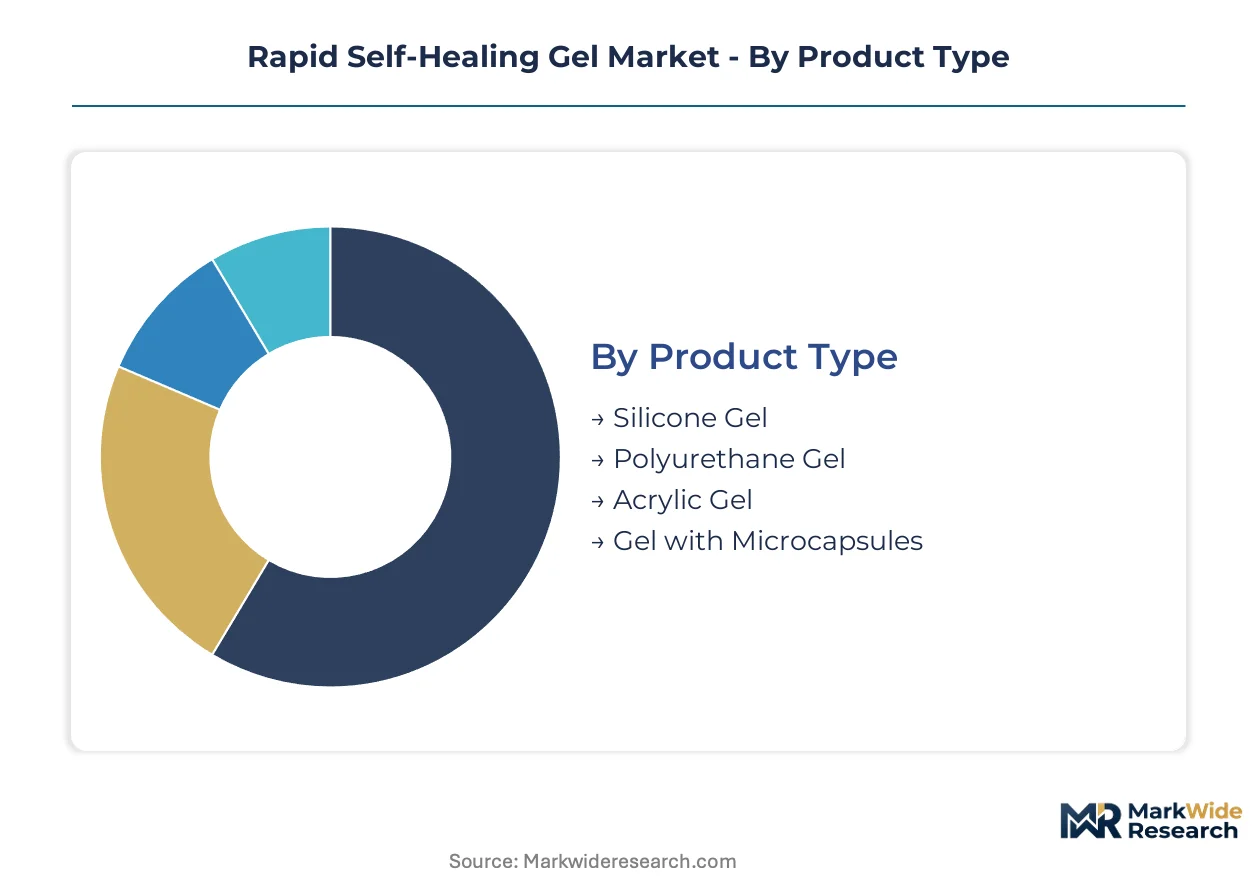
Segmentation in the rapid self-healing gel market reveals distinct supply chain configurations and qualification requirements across product chemistries and end-use verticals. Each category carries unique regulatory burdens and margin structures that determine competitive positioning.
Product Type:
Silicone gel production concentrates in Germany and the United States where medical-grade precursor supply chains are captive to Dow and Wacker Chemie facilities. Polyurethane gel manufacturing spreads across automotive coating clusters in Japan and industrial chemical hubs in the Netherlands. Acrylic gel and microcapsule-embedded variants originate primarily from specialty polymer developers in Switzerland and South Korea serving export markets.
- Silicone Gel:Cross-linked polydimethylsiloxane networks deliver established moisture vapor transmission rates and biocompatibility profiles. Hospital procurement departments in Germany and the United States prioritize ISO 10993-5 cytotoxicity documentation, compressing supplier qualification windows toward testing-integrated manufacturers.
- Gel with Microcapsules:Encapsulated healing agents enable autonomous multi-cycle repair through dynamic bond reformation upon capsule rupture. Semiconductor fabrication facilities in Japan and South Korea are redirecting maintenance budgets from component replacement toward consumable gel formulations.
- Polyurethane Gel:Abrasion-resistant matrices formulated for paint compatibility across OEM automotive clear coats.
- Acrylic Gel:UV-curable systems serving cosmetic barrier applications with rapid film formation characteristics.
Silicone gel commands the established base. The steepest expansion runs through gel with microcapsules.
Application:
Cost tier differentiation separates premium medical-grade formulations from industrial maintenance applications. Medical wound care carries ISO 10993 certification costs that exclude commodity suppliers. Electronics protection and automotive repair segments compete on technical performance metrics without equivalent regulatory overhead.
- Medical Wound Care:Moisture-retentive dressings leveraging silicone matrices for post-surgical and chronic wound management. FDA 510(k) pathways and EU MDR compliance mandates in Germany and France are accelerating replacement of legacy dressing categories.
- Electronics Protection:Conformal coatings and substrate repair materials for printed circuit boards and flexible wearable devices. Device OEMs in Japan and South Korea are integrating self-healing layers into next-generation health monitor form factors.
- Automotive Repairs:Clear coat-compatible formulations addressing stone chip and abrasion damage in OEM refinish channels.
- Cosmetic Applications:Barrier films and delivery matrices for topical active ingredient release.
Medical wound care absorbs the highest certification investment. Electronics protection is climbing the fastest on convergence with flexible device architectures.
End User:
Volume concentration varies sharply across customer types. Hospital group purchasing organizations in the United States consolidate contracts around biocompatibility scores. Cosmetic manufacturers and electronics companies source through formulation partnerships rather than spot procurement.
- Hospitals:Centralized procurement departments in Germany and the United States weight ISO 10993 certification above unit pricing, concentrating awards among three to four testing-integrated suppliers with captive laboratory partnerships.
- Electronics Companies:Device OEMs and semiconductor fabricators specifying gel integration into substrate designs during product development phases.
- Clinics:Freestanding ambulatory surgical centers in Texas and Florida operating without dedicated formulary managers.
- Cosmetic Manufacturers:Formulation houses requiring batch consistency and regulatory dossier support for finished goods registration.
Hospitals anchor volume concentration through consolidated procurement. Electronics companies are gaining share fastest on device integration partnerships.
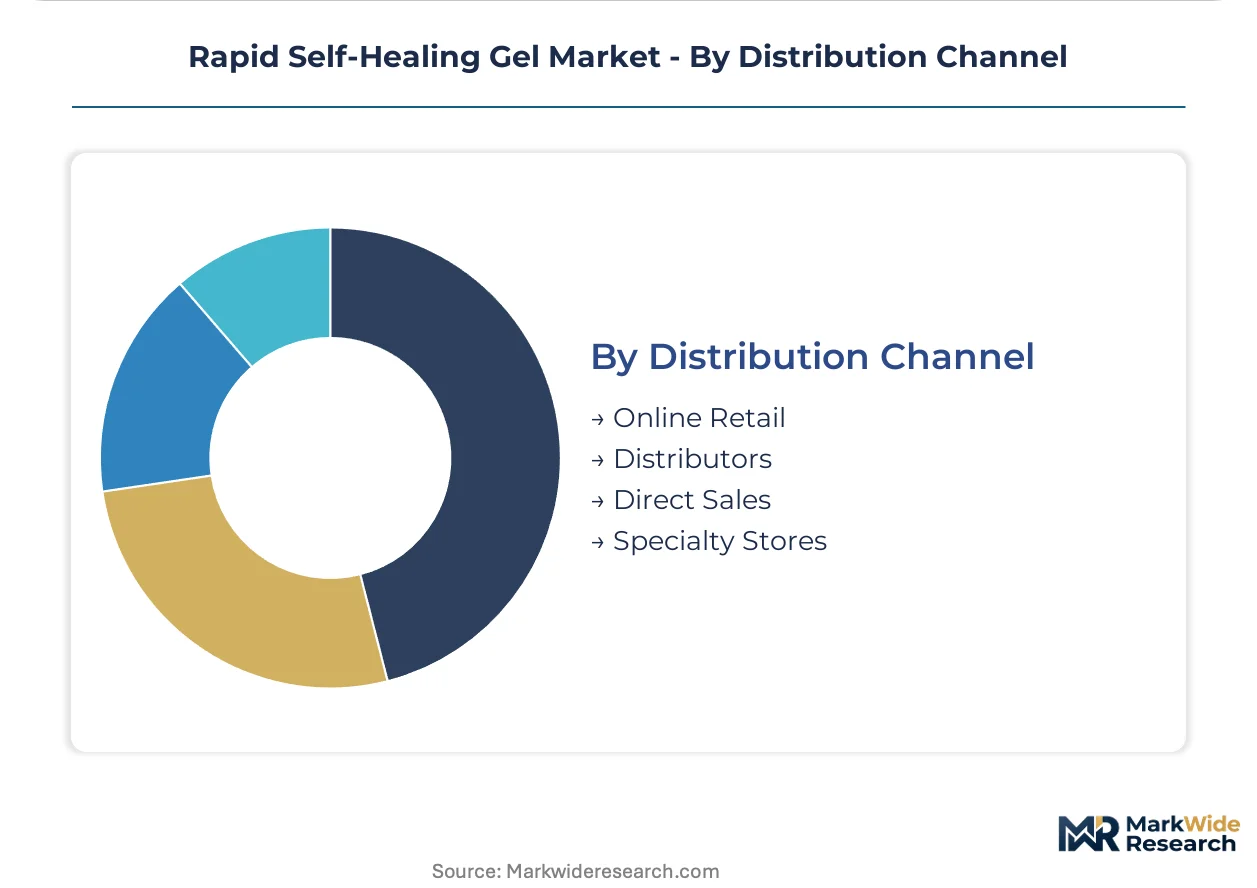
Distribution Channel:
Margin capture redistributes toward channels controlling qualification documentation. Direct sales and distributor networks with laboratory partnerships retain premium positioning. Online retail and specialty stores serve price-sensitive segments without regulatory filing requirements.
- Distributors:Cardinal Health and regional medical supply houses leverage hospital network access to sustain volume leadership across North American wound care channels.
- Direct Sales:Technical specification negotiation with device OEMs and automotive coating formulators requiring customized rheology and cure profiles.
- Online Retail:Consumer-facing channels for cosmetic and minor wound care applications without prescription or clinical supervision requirements.
- Specialty Stores:Professional supply outlets serving automotive refinish technicians and electronics repair specialists.
Distributors command the established base. Direct sales channels are expanding most quickly on OEM partnership complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR compliance mandates and FDA biocompatibility standards are redrawing competitive boundaries across major demand centers. Hospital procurement departments now weight ISO 10993 certification above unit pricing, concentrating contract awards among testing-integrated suppliers in Germany, the United States, and Japan.
United States
Freestanding ambulatory surgical centers in Texas and Florida operate without dedicated gel formulary managers, creating first-mover advantage for direct distribution models. FDA 510(k) pathways govern medical-grade approvals, with Cardinal Health leveraging hospital network access to sustain volume leadership. The Greater Boston cluster anchors electronics protection R&D through device OEM partnerships.
Germany
Hospital procurement departments now require ISO 10993-5 cytotoxicity documentation for wound care contracts, accelerating replacement of legacy silicone dressings. EU MDR compliance mandates reshape qualification requirements, with ECHA polymer restrictions forcing supply chain audits. The Rhine-Ruhr industrial corridor concentrates polyurethane gel manufacturing for automotive coating compatibility testing.
Japan
PMDA local clinical testing protocols extend market access timelines while creating predictable qualification roadmaps. Semiconductor fabrication facilities in Kyushu redirect maintenance budgets toward microcapsule-embedded gel formulations for multi-cycle substrate repair. METI standards coordination supports convergence with flexible wearable device architectures.
South Korea
Electronics protection applications climb fastest on device integration partnerships with flexible circuit substrate developers. MFDS streamlined biocompatibility recognition shortens pathways for ISO 10993-tested materials. The Seoul Capital Area anchors specialty polymer development serving export markets.
Switzerland
Swissmedic regulations enforce premium positioning for medical-grade formulations through batch consistency documentation requirements. Specialty polymer developers in Basel serve global pharmaceutical and cosmetic barrier applications. The country's precision chemistry heritage supports acrylic gel innovation for topical active ingredient delivery.
Rapid Self-Healing Gel Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure, creating tiered competitive dynamics. The vendor base clusters around three strategic archetypes: testing-integrated manufacturers capturing hospital procurement contracts, specialty coating chemists extending into gel-based barriers, and distribution-heavy players leveraging network access. Dominant competitive moves include laboratory partnerships that collapse qualification timelines and direct sales investments targeting device OEM specification phases.
Within the testing-integrated tier, Cardinal Health exemplifies distribution-network leverage across North American wound care channels. Hydromer Inc. occupies a position among specialty coating chemists with expertise extending into gel-based barrier applications. Advanced Medical Solutions Group PLC represents the listed manufacturer archetype navigating EU MDR compliance mandates.
| Leading Market Players |
|---|
| Advanced Medical Solutions Group PLC |
| Cardinal Health |
| Axelgaard Manufacturing |
| Scapa Healthcare |
| Hydromer Inc. |
| Alliqua Biomedical |
| Contura International |
| Cytogel Pharma |
| Katecho Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 10993-18 characterization timelines stretching 8-14 months compress inventory turnover for novel gel formulations, concentrating pricing power with testing-integrated manufacturers who can pre-qualify polymer networks ahead of procurement cycles. Hospital group purchasing organizations in Germany and the United States now weight certification documentation above unit cost, redistributing margin capture toward laboratories with captive biocompatibility datasets.
Pricing Analysis
Certification grade (ISO 10993-5 cytotoxicity tier versus uncertified industrial grade) creates the primary spread between premium medical formulations and commodity alternatives. Three-tier pricing structure across ISO-certified premium, CE-marked standard, and uncertified economy levels reflects differential qualification investment recovery. Cost compression in the economy tier intensifies as REACH substance disclosure forces European compounders into reformulation cycles without grandfathering provisions. Electronics protection buyers demonstrate lowest price sensitivity due to multi-cycle repair value, while cosmetic barrier applications face spot-market volatility.
Supply Chain Analysis
Container availability constraints on trans-Pacific routes from South Korean specialty polymer hubs elevate inbound logistics costs for microcapsule-embedded gel precursors. Medical-grade silicone feedstock concentrates in Germany and the United States where Dow and Wacker Chemie facilities anchor precursor supply. Formulation draws from polyurethane matrices sourced through Dutch automotive coating clusters and acrylic systems from Swiss precision chemistry developers. Single-source vulnerability runs through medical-grade silicone precursor allocation, exposing formulators to input rationing during demand spikes. Distribution runs through Cardinal Health's hospital network access and direct technical sales to device OEM specification phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microcapsule chemistry enabling autonomous multi-cycle repair represents a technological inflection compressing capital expenditure cycles in semiconductor fabrication, positioning rapid self-healing gel as a high-growth disruption across industrial maintenance budgets.
For Market Incumbents: Compound laboratory partnership density to collapse ISO 10993-18 characterization timelines for novel polymer networks, preempting qualification bottlenecks that marginalize distributors without testing infrastructure. Deepen backward integration into medical-grade silicone precursor supply through long-term offtake agreements with Dow and Wacker Chemie, defending against allocation risk that exposes formulators to margin compression. For New Entrants and Emerging Players: China NMPA Class II biocompatibility recognition for ISO 10993-tested materials offers the fastest regulatory pathway for foreign manufacturers with existing EU or US approvals. Target freestanding ambulatory surgical centers in Texas and Florida operating without dedicated gel formulary managers, deploying direct distribution models that bypass consolidated hospital procurement channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive gel formulation capabilities but lacking dedicated medical-device commercial infrastructure. Long-term viability hinges on convergence with flexible wearable device architectures requiring repairable substrate integration. Watch for PMDA local clinical testing protocol formalization in Japan as the signal indicating reduced regulatory uncertainty for compliant entrants.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Cytotoxicity Certification | Hospital procurement departments in Germany now mandate documentation, accelerating legacy dressing displacement. |
| Microcapsule Chemistry Scale-Up | Semiconductor fabrication facilities in Kyushu redirect maintenance budgets toward consumable gel formulations. |
| Direct Distribution Model Deployment | Freestanding ambulatory surgical centers in Texas and Florida lack formulary managers, enabling first-mover capture. |
| China NMPA Class II Pathway Navigation | Streamlined biocompatibility recognition shortens market access for ISO 10993-tested foreign manufacturers. |
| Flexible Device OEM Partnership | Integration into printed circuit substrates opens repairable wearable health monitor specifications. |
Methodological Framework
A spread of perspectives from polymer chemists, FDA regulatory consultants, hospital procurement managers, and semiconductor fabrication maintenance directors converged on the working assumptions governing qualification timeline compression and procurement behavior shifts. Primary interviews with biomedical engineers and group purchasing organization contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, ECHA polymer restriction consultations, and SEC 10-K disclosures from listed medical device manufacturers. Bottom-up gel formulation volume estimates triangulated against top-down wound care dressing market allocations.
Segmentation dimensions modeled span product chemistry (silicone, polyurethane, acrylic, microcapsule-embedded), application vertical (medical wound care, electronics protection, automotive repair, cosmetic barrier), end-user archetype (hospitals, clinics, electronics companies, cosmetic manufacturers), and distribution channel (distributors, direct sales, online retail, specialty stores) across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating ISO 10993 certification penetration rates and REACH compliance cost pass-through assumptions. Industry-specific forecast inputs include moisture vapor transmission rate specifications for silicone matrices and multi-cycle repair functionality adoption in semiconductor cleanroom protocols.
Underlying assumptions cover sustained EU MDR enforcement stringency and stable silicone precursor supply allocation, with deviation risk concentrated in ECHA polymer substance restriction scope expansion and PMDA local clinical testing timeline variability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Smart Card Materials Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Thin Film Materials Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functional Composites Market
Functional Materials
Functional Acids Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Global Smart Material Market