
 Thin Film Materials Market | 2026-2036
Thin Film Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Materials Market Intelligence
ISO 9001 and IATF 16949 qualification cycles is bifurcating the supplier base into qualified tier-one vendors and excluded regional challengers. Umicore leverages its integrated refining-to-target vertical to sustain rare earth and precious metal supply security. First Solar anchors cadmium telluride sourcing through captive thin-film photovoltaic manufacturing in Malaysia and Vietnam. JX Nippon Mining & Metals competes on ultra-high-purity sputtering target production for semiconductor lithography.
Thin film materials comprise engineered layers ranging from nanometers to micrometers in thickness, deposited through vacuum or solution-based processes to confer electrical, optical, or protective functionality on substrates. Chemical vapor deposition and physical vapor deposition dominate manufacturing, with atomic layer deposition gaining traction for sub-10nm precision in advanced logic chips. Semiconductor films lead value generation due to silicon wafer expansion and compound semiconductor RF device proliferation, while dielectric films capture margin pools in high-k gate stack applications for sub-7nm nodes. Photovoltaics application growth concentrates in cadmium telluride and perovskite tandem architectures, displacing conventional silicon in utility-scale deployments.
REACH in Europe restricts hazardous substance use in electronic thin films, while China's GB standards and dual carbon goals mandate cleaner deposition chemistries and energy-efficient manufacturing. The US EPA and OSHA regulate volatile organic compound emissions from solvent-based coating processes, tightening compliance costs for domestic producers. Japan's METI promotes JIS-certified high-purity metals through strategic material security programs. Stakeholders must monitor evolving purity thresholds and carbon border adjustments to preserve qualification status and avoid supply exclusion.
Market Dynamics
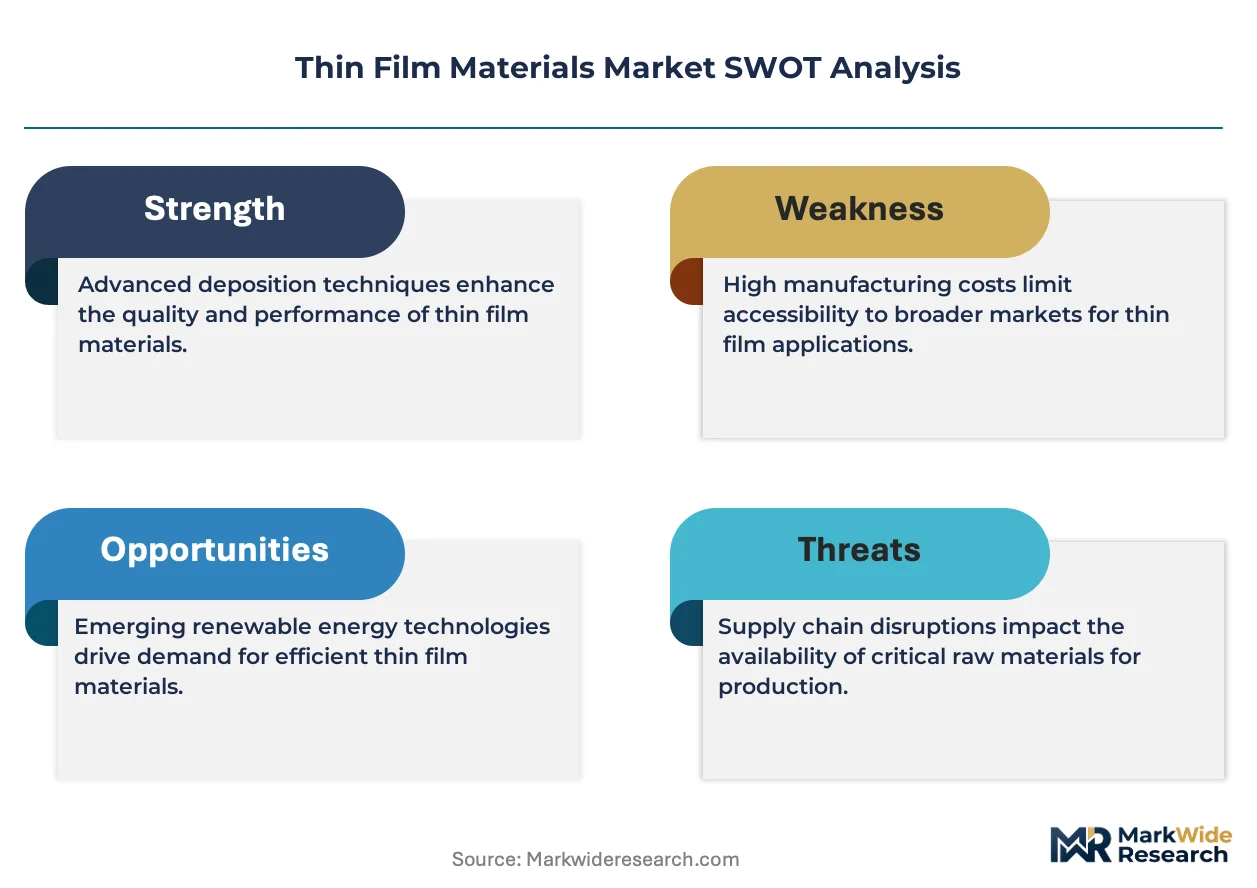
Atomic layer deposition precision requirements below 10 nanometers are compressing supplier qualification timelines and bifurcating the thin film materials vendor base into certified tier-one suppliers and excluded regional challengers.
Growth Catalysts
- Sub-7nm Logic Node Expansion:Silicon wafer foundries in Taiwan and South Korea are scaling high-k dielectric gate stacks, pulling ultra-high-purity precursor demand for atomic layer deposition processes.
- REACH Compliance Deadlines:ECHA substance restriction timelines are accelerating substitution toward halogen-free sputtering targets and solvent-reduced deposition chemistries across European electronics manufacturing.
- Perovskite Tandem Commercialization:Utility-scale photovoltaic developers are piloting cadmium telluride-perovskite tandem architectures, opening precursor material specifications beyond conventional silicon supply chains.
Market Restraints
- Rare Earth Supply Concentration:Heavy rare earth refining capacity concentrates in Chinese state-controlled processing facilities, exposing sputtering target manufacturers to quota volatility and export license delays.
- Precious Metal Input Volatility:Ruthenium and platinum group metal price swings compress margin pools for barrier seed layer films used in copper interconnect stacks at advanced nodes.
- Technical Limitation in Film Uniformity:Large-area coating for perovskite photovoltaics faces pinhole defect rates above commercial thresholds, constraining module efficiency and warranty coverage.
Strategic Opportunities
- India PLI Scheme for Semiconductors:Ministry of Electronics and Information Technology production-linked incentives are attracting compound semiconductor foundry investments, opening domestic sputtering target qualification pathways.
- EU Green Deal Carbon Border Adjustments:CBAM implementation on embedded emissions in imported electronics is incentivizing European deposition equipment makers to source regionally refined high-purity metals.
- Automotive Radar Substrate Convergence:Gallium nitride-on-silicon carbide and gallium arsenide epitaxial growth technologies are converging for 77GHz automotive radar, expanding precursor material addressable markets beyond traditional RF defense applications.
Industry Challenges
- Atomic Layer Deposition Process Engineering Talent:Semiconductor fabs face acute shortages of technicians trained in precursor pulse sequencing and reactor chamber thermal management for sub-5nm film stacks.
- IATF 16949 Certification Timelines:Automotive electronics qualification cycles spanning 18-24 months delay thin film material supplier entry into electric vehicle power module and sensor markets.
- Legacy Wet Etch Compatibility:New dry-deposited barrier films require revalidation against existing semiconductor fab chemical mechanical planarization and wet clean infrastructure, extending integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Materials Market |
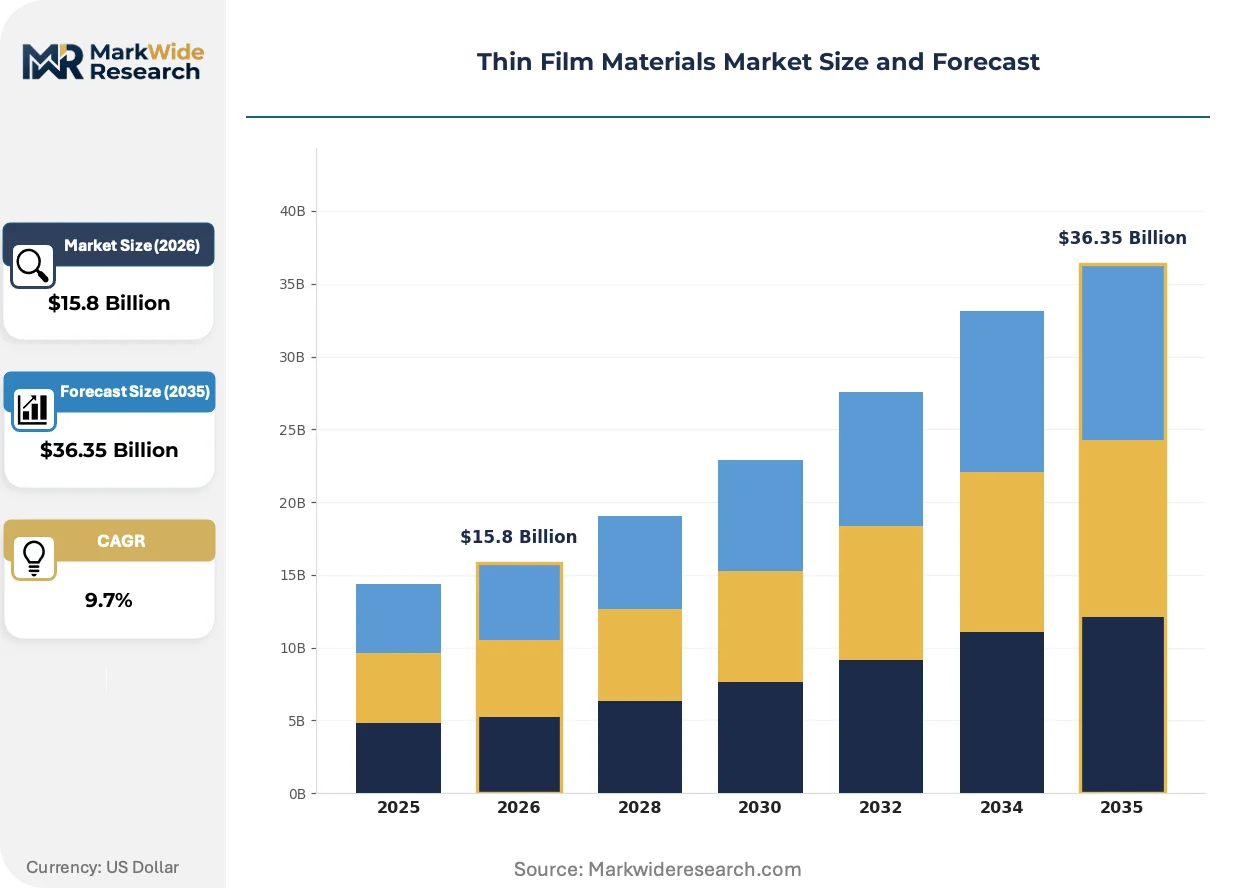
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $36.35 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Films, Dielectric Films, Semiconductor Films, Polymer Films, Composite Films Technology: PVD, CVD, Atomic Layer Deposition, Sputtering, Electroplating Application: Photovoltaics, Data Storage, Display Panels, Optical Coatings, Sensors End User Industry: Consumer Electronics, Aerospace Components, Solar Energy, Telecommunication Devices, Scientific Instrumentation |
| Companies Covered | Vital Materials, Umicore, Indium Corporation, JX Nippon Mining & Metals, Stanford Advanced Materials, Ascent Solar Technologies, Cicor Management AG, Kaneka Corporation, First Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Materials Market Strategic Shifts & Innovations
Precision deposition technologies and regulatory chemistry restrictions are simultaneously pulling process innovation toward atomic-scale control and material substitution, reshaping supplier technical roadmaps and foundry procurement specifications.
Atomic layer deposition is fragmenting process equipment architectures as sub-7nm logic and 3D NAND memory fabs demand single-wafer thermal reactors with sub-angstrom thickness uniformity. Samsung and TSMC are qualifying precursor chemistries from multiple suppliers simultaneously to avoid single-source risk. This fragmentation is compressing equipment vendor margins while expanding specialty chemical supplier addressable markets.
REACH authorization requirements for cadmium and lead compounds are forcing photovoltaic manufacturers to accelerate perovskite formulation development with tin and bismuth substitutions. ECHA sunset date pressures have triggered First Solar and European tandem cell developers to pre-qualify alternative absorber precursors before 2027 restriction windows. Cadmium telluride module producers face accelerated R&D timelines to maintain utility-scale project financing eligibility.
Long-term supply agreements are displacing spot market purchasing for high-purity sputtering targets as semiconductor foundries lock in rare earth and refractory metal volumes through 2028. Japanese trading houses and Korean chaebol materials divisions are capturing procurement function influence, consolidating supplier relationships into three-year minimum purchase commitments. Taiwan-based foundries exhibit the strongest contracting velocity, driven by geopolitical risk mitigation and buffer stock requirements.
Thin Film Materials Market Segmentation
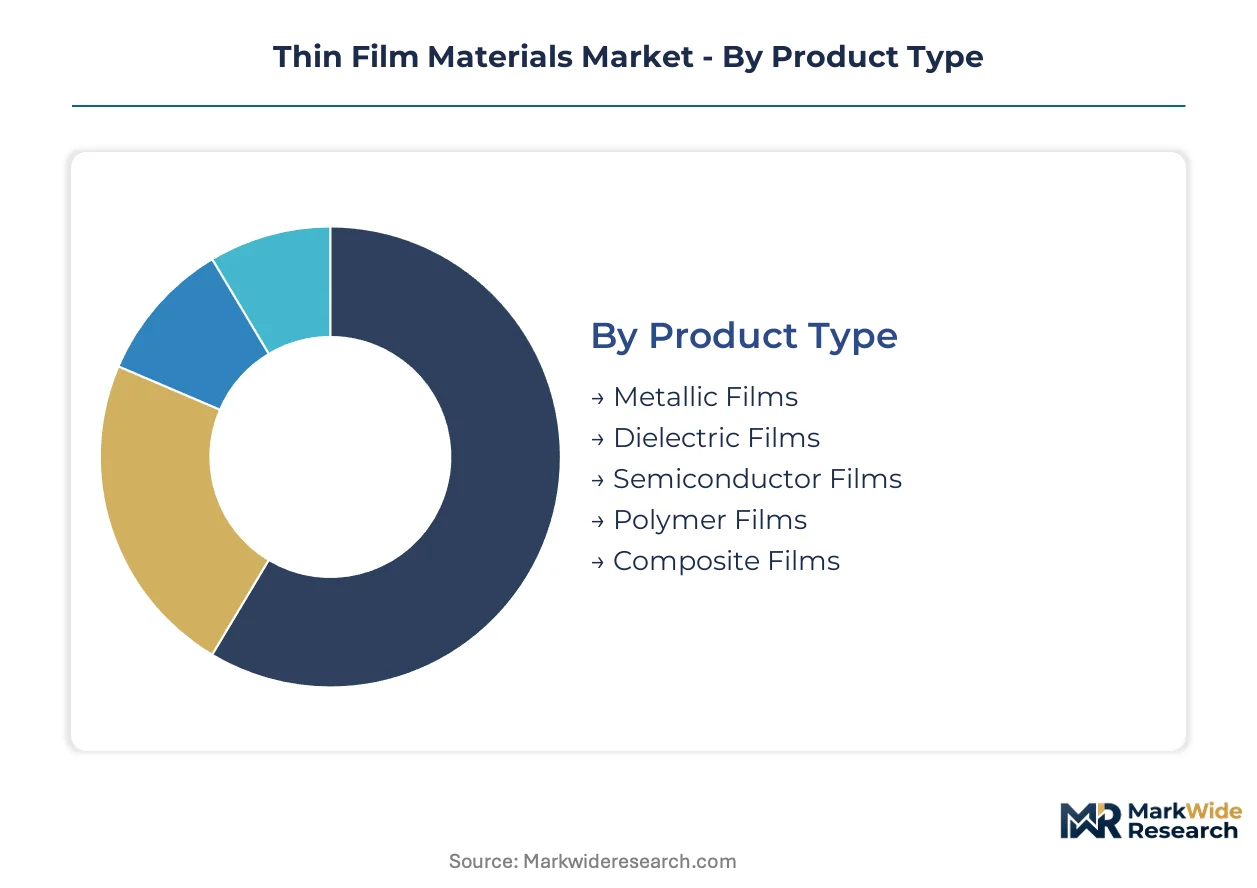
Thin film materials span deposition chemistries, equipment technologies, and end-use specifications that fragment procurement requirements across semiconductor fabs, photovoltaic module lines, and precision optics manufacturers. Segmentation reveals where qualification barriers concentrate and which material categories command premium pricing through purity thresholds.
Product Type:
Metallic films serve predominantly export-led demand from East Asian semiconductor clusters, while dielectric and polymer films anchor domestic consumption in regional display and packaging applications.
- Metallic Films:Aluminum, copper, and refractory metal layers deposited as interconnects, barrier seeds, and reflective coatings. Taiwan and South Korea foundries pull ultra-high-purity tantalum and ruthenium for sub-7nm copper damascene stacks, with supply security concerns accelerating long-term contracting.
- Semiconductor Films:Silicon, germanium, and compound semiconductor epitaxial layers engineered for bandgap control and carrier mobility. Gallium arsenide and gallium nitride films concentrate in RF device and power electronics foundries, driven by 5G base station and electric vehicle inverter demand.
- Dielectric Films:High-k metal oxides and low-k organosilicates for gate stacks and interlayer insulation.
- Polymer Films:Polyimide and fluoropolymer barriers for flexible substrate protection.
- Composite Films:Multi-layer stacks combining metallic, ceramic, and organic phases for multifunctional performance.
Semiconductor films hold the largest share; momentum sits with metallic films as interconnect scaling drives refractory metal consumption.
Technology:
Cost tier stratification separates capital-intensive vacuum deposition methods from lower-capex solution-based alternatives, with qualification requirements widening the gap between certified and uncertified equipment suppliers.
- Atomic Layer Deposition:Self-limiting surface reactions enabling sub-angstrom thickness control for high-k gate dielectrics and 3D NAND charge trap layers. Samsung and TSMC have qualified multiple precursor suppliers simultaneously to mitigate single-source risk at advanced nodes.
- PVD:Thermal evaporation and electron beam deposition for metal electrode and mirror coating applications. Solar energy manufacturers in Malaysia and Vietnam deploy inline PVD systems for cadmium telluride absorber deposition, constrained by vacuum chamber scaling limits for utility-scale throughput.
- CVD:Gas-phase precursor decomposition for conformal step coverage in high-aspect-ratio features.
- Sputtering:Ion bombardment of target materials for alloy film composition control.
- Electroplating:Solution-based metal deposition for cost-sensitive large-area coatings.
PVD commands the installed base; atomic layer deposition is climbing the fastest as logic node shrinkage mandates angstrom-scale precision.
Application:
Volume concentration diverges between mass-production segments requiring square-kilometer annual throughput and specialty applications demanding batch-level customization.
- Photovoltaics:Cadmium telluride, copper indium gallium selenide, and emerging perovskite absorber layers deposited on glass and flexible substrates. First Solar's Malaysia and Vietnam manufacturing anchors captive thin-film production, while European developers pilot tin-bismuth perovskite formulations to preempt REACH cadmium restrictions.
- Display Panels:Indium tin oxide transparent conductors and quantum dot color conversion films for OLED and micro-LED architectures. South Korean and Chinese panel makers consume the majority of global indium refining capacity, with supply agreements extending through 2028.
- Data Storage:Magnetic cobalt-platinum multilayers and heat-assisted recording media.
- Optical Coatings:Anti-reflective and high-reflectivity dielectric stacks for laser systems and imaging.
- Sensors:Piezoelectric and pyroelectric films for MEMS and infrared detection.
Photovoltaics holds the largest share; momentum sits with display panels as micro-LED commercialization expands indium gallium nitride epitaxy demand.
End User Industry:
Customer type fragmentation separates automotive and aerospace buyers with 18-24 month IATF 16949 qualification cycles from consumer electronics procurement with compressed 6-12 month vendor approval timelines.
- Consumer Electronics:Smartphones, tablets, and wearables driving dielectric and transparent conductor films for touch sensors and RF shielding. Chinese original equipment manufacturers dominate procurement volume, with specifications tightening around foldable display hinge durability testing.
- Solar Energy:Utility-scale and distributed generation project developers specifying module efficiency warranties that cascade back to absorber layer uniformity requirements. Cadmium telluride producers face accelerated R&D timelines to maintain project financing eligibility under evolving ECHA substance restrictions.
- Aerospace Components:Thermal barrier and erosion-resistant coatings for turbine blades and satellite systems.
- Telecommunication Devices:Gallium nitride high-electron-mobility transistors for 5G base station power amplifiers.
- Scientific Instrumentation:Precision optical and cryogenic thin films for research-grade equipment.
Consumer electronics holds the largest share; solar energy is expanding most quickly as tandem cell architectures open new precursor material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and carbon border adjustment mechanisms in Europe are redrawing procurement geography for thin film materials. National semiconductor strategies and dual carbon mandates are accelerating qualification timelines in East Asian manufacturing clusters.
China
MIIT domestic wafer fab expansion and SAMR antitrust scrutiny on rare earth processing are reshaping sputtering target supply security. GB standards on deposition chemistry emissions tighten quarterly, forcing Yangtze River Delta equipment makers to retrofit CVD reactors. Shanghai and Suzhou industrial parks concentrate atomic layer deposition precursor qualification for domestic logic foundries.
South Korea
Samsung and SK Hynix 3D NAND capacity ramps pull ultra-high-purity precursor volumes through 2026. MFDS chemical substance notification requirements delay new precursor introductions by 8-12 months. Seoul Capital Area and Yongin semiconductor complexes anchor captive sputtering target recycling infrastructure to mitigate rare earth import exposure.
Japan
METI strategic material security programs subsidize JIS-certified high-purity metal refining for domestic lithography supply chains. Chubu region Nagoya industrial corridor concentrates electron beam evaporation equipment manufacturing for global export. Osaka-based trading houses lock in three-year tantalum and ruthenium purchase commitments with Taiwanese foundries.
United States
CHIPS Act fab construction subsidies in Arizona and Texas are pulling sputtering target qualification demand forward by 18 months. EPA VOC emission limits on solvent-based coating processes tighten compliance costs for domestic PVD equipment operators. Greater Phoenix and Austin semiconductor clusters concentrate atomic layer deposition technician training programs with community college partnerships.
Germany
ECHA REACH authorization timelines for cadmium compounds are forcing photovoltaic equipment makers to pre-qualify tin-bismuth perovskite precursors. EU Green Deal carbon border adjustments incentivize regional refining of high-purity metals for deposition equipment export. Saxony and Bavaria microelectronics clusters anchor EUV lithography material R&D consortia with Fraunhofer institute partnerships.
Thin Film Materials Market Key Industry Players
Player mix skews toward integrated materials-to-target refiners and specialized precursor chemical suppliers. Market structure concentrates around three to five dominant vendors with captive rare earth processing capabilities, while regional challengers face exclusion from automotive qualification cycles. Strategic archetypes include backward-integrated mining-to-target conglomerates, fabless precursor formulation specialists, and captive thin-film photovoltaic manufacturers. Competitive moves center on long-term offtake agreements with foundry customers and geographic expansion into Indian PLI-subsidized semiconductor corridors.
Among integrated refining conglomerates, Umicore and JX Nippon Mining & Metals exemplify the backward-integrated archetype with captive control over rare earth and refractory metal supply chains. First Solar occupies a distinct position as a captive thin-film photovoltaic manufacturer with integrated cadmium telluride sourcing. These three entities represent contrasting strategic postures: European refining integration, Japanese ultra-high-purity metal production, and American vertical manufacturing for utility-scale solar deployment.
| Leading Market Players |
|---|
| Vital Materials |
| Umicore |
| Indium Corporation |
| JX Nippon Mining & Metals |
| Stanford Advanced Materials |
| Ascent Solar Technologies |
| Cicor Management AG |
| Kaneka Corporation |
| First Solar |
| Others |
Cost & Logistics Intelligence
Ninety-day precursor inventory buffers at Taiwanese foundries concentrate procurement leverage among qualified suppliers while compressing margin pools for unqualified challengers excluded from long-term contracting. This lead-time discipline reinforces pricing power for IATF 16949-certified vendors serving automotive power module demand.
Pricing Analysis
Certification level (ISO 9001/IATF 16949-grade) creates the primary spread between qualified tier-one suppliers and excluded regional challengers. Three-tier pricing structure across automotive-qualified, semiconductor-grade, and industrial-standard levels captures the divergence in qualification investment recovery. Cost compression in industrial-standard sputtering targets is intensifying because Chinese state-controlled rare earth processors are absorbing margin to maintain volume quotas. Automotive electronics buyers exhibit the lowest price sensitivity due to 18-24 month requalification costs, while photovoltaic developers show highest sensitivity as module efficiency warranties cascade to absorber layer specifications.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are extending inbound logistics costs for European deposition equipment makers sourcing Chinese-processed rare earth feedstock. Heavy rare earth refining capacity concentrates in China, with tantalum and ruthenium sourcing anchored in Japanese trading house inventories. The supply chain draws from Chinese state-controlled processing facilities, Japanese ultra-high-purity metal refiners, and Korean chaebol materials divisions. Single-source vulnerability in heavy rare earth quotas exposes sputtering target manufacturers to export license delays. Distribution runs through three-year minimum purchase commitments locked in by Japanese trading houses and Korean materials divisions with Taiwanese foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thin film materials market functions as a defensive-moat industry where regulatory entrenchment through REACH authorization timelines and IATF 16949 qualification cycles erects structural barriers against unqualified entrants.
For Market Incumbents: Fortify backward integration into rare earth refining to mitigate Chinese quota volatility exposure. Secure captive tantalum and ruthenium supply through long-term offtake agreements with Australian and African concentrate producers. Expand JIS-certified refining capacity in Japan's Chubu region to capture EU Green Deal carbon border adjustment premiums on embedded emissions. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized semiconductor corridors where domestic sputtering target qualification pathways remain underdeveloped. Target compound semiconductor foundry investments in Gujarat and Karnataka where Ministry of Electronics and Information Technology incentives are attracting gallium nitride epitaxy capacity. Pursue partnership models with Japanese trading houses to bypass 18-24 month automotive qualification cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across atomic layer deposition precursor formulation as sub-7nm logic nodes demand sub-angstrom thickness uniformity. Five-to-ten year viability favors backward-integrated refiners with captive rare earth processing over fabless precursor specialists exposed to feedstock volatility. Monitor ECHA substance restriction sunset dates as inflection indicators for cadmium telluride displacement by tin-bismuth perovskite architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Refining | Umicore's captive processing secures supply against Chinese export quota volatility. |
| Long-term Supply Agreement with Foundry Customers | Taiwanese foundries lock in three-year tantalum commitments through Osaka trading houses. |
| Geographic Expansion into Indian PLI Corridors | Domestic sputtering target qualification opens access to compound semiconductor fabs. |
| REACH-Compliant Precursor Substitution R&D | First Solar accelerates tin-bismuth perovskite development ahead of cadmium restrictions. |
| Atomic Layer Deposition Technician Training Programs | Greater Phoenix community college partnerships address sub-5nm process engineering shortages. |
Research Approach
Desk research of SEC 10-K filings from deposition equipment manufacturers, ECHA substance restriction databases, and Japanese METI strategic material security program disclosures preceded structured interviews with semiconductor fab procurement directors, atomic layer deposition process engineers, sputtering target manufacturing plant managers, and rare earth trading house commodity specialists. Primary fieldwork combined with secondary validation from customs/trade data and industry association technical reports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Variance decomposition across product type, technology platform, application segment, and end-user industry dimensions shaped the analytical framework. Modeled segmentation captured metallic films, dielectric films, and semiconductor films by deposition chemistry; atomic layer deposition, physical vapor deposition, and chemical vapor deposition by equipment architecture; photovoltaics, display panels, and data storage by application; and consumer electronics, solar energy, and automotive electronics by customer type. CAGRs derived from regression analysis against wafer fab equipment spending and photovoltaic module deployment trajectories. Forecast inputs incorporated REACH authorization timeline assumptions and rare earth quota allocation patterns.
Material uncertainties — ECHA substance restriction acceleration, Chinese rare earth export license delays, perovskite tandem cell commercialization timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding qualification cycle durations and carbon border adjustment implementation scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Functional Composites Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Smart Card Materials Market
Functional Materials
Functional Acids Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Global Smart Material Market