
 Global Anti-Reflective Glass Market | 2026-2036
Global Anti-Reflective Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Reflective Glass Market Analysis
The specialty glass distribution channel is narrowing as technical buyers consolidate procurement around certified coating suppliers. Saint-Gobain leverages its integrated float-to-coat operations across France and Germany to control substrate quality from melt to final optical layer. Schott AG anchors its position through deep specialization in borosilicate and aluminosilicate formulations for high-transmission applications. Corning Incorporated competes by extending its fusion-draw expertise into thin, lightweight anti-reflective substrates for electronics.
Anti-reflective glass consists of soda-lime or borosilicate substrates engineered with nanometer-scale interference coatings—typically multi-layer stacks of metal oxides such as silicon dioxide and titanium dioxide—to suppress surface reflectance below 2% across visible wavelengths. Physical Vapor Deposition commands the technology segment due to its precision in depositing uniform quarter-wave optical thickness layers on large-area substrates. The electronics end-user category leads value contribution as smartphone and tablet manufacturers specify anti-reflective cover glass for outdoor readability. Double-sided coated products are gaining share in architectural applications where both interior and exterior surfaces require glare reduction.
The EPA regulates volatile organic compound emissions from sol-gel and spray coating operations in the United States, pushing manufacturers toward closed-loop PVD systems. REACH restricts hexavalent chromium and certain fluorinated compounds in European coating chemistries, reshaping supplier qualification requirements for glass processors. China's MEE enforces dual carbon-aligned energy intensity standards on float glass furnaces, raising barriers for uncertified coating houses. Stakeholders must monitor evolving building energy codes in India and Brazil to anticipate specification shifts in commercial glazing tenders.
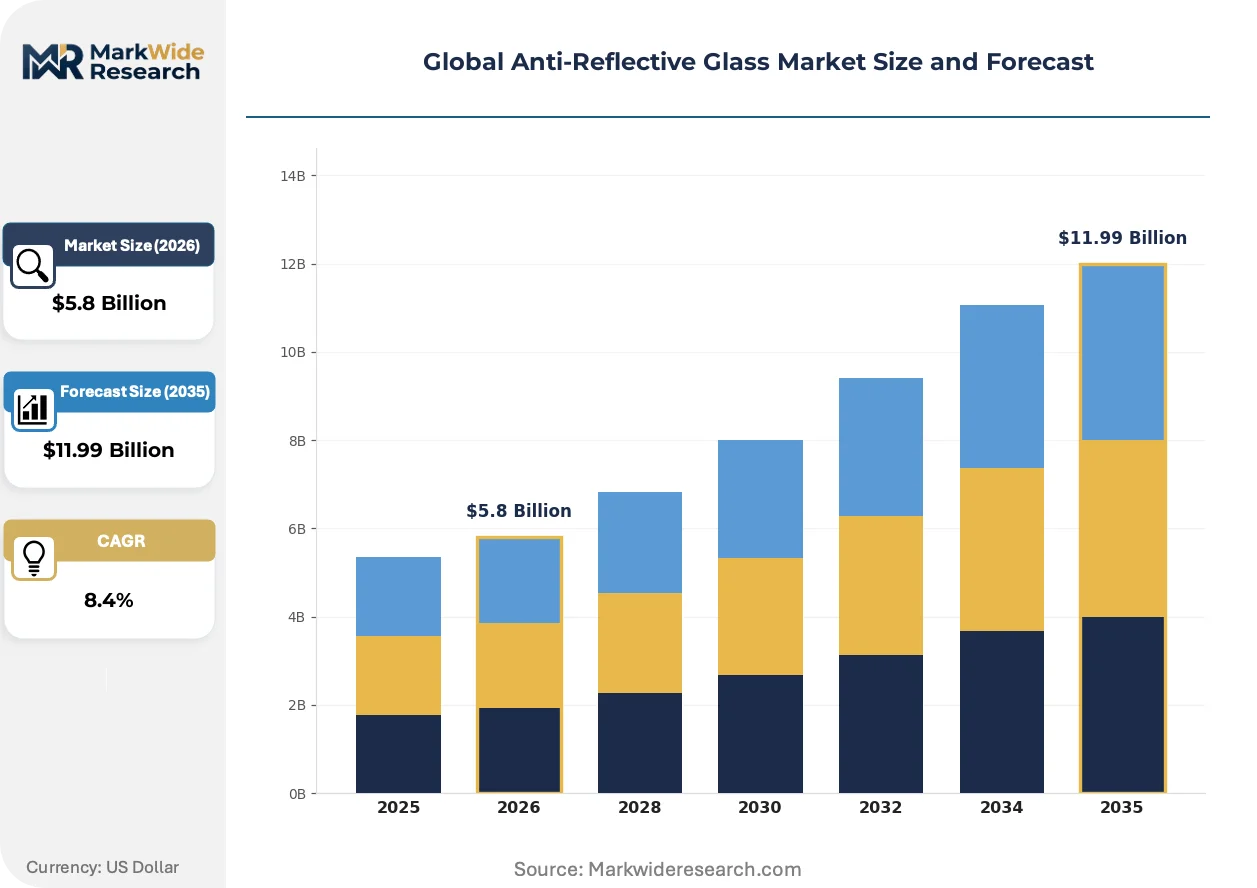
Market Dynamics
Coating chemistry standardization under REACH and China's dual carbon framework is compressing supplier qualification timelines while concentrating procurement around certified float-to-coat integrators with in-house PVD capability.
Growth Catalysts
- Photovoltaic module specification:Solar farm developers in Germany and Japan are mandating anti-reflective glass with sub-2% reflectance to maximize energy yield per installed watt.
- REACH compliance deadlines:ECHA's restriction of hexavalent chromium and fluorinated compounds is disqualifying uncertified coating houses and redirecting volume toward qualified suppliers.
- Building code evolution:Commercial construction codes in Mumbai and Delhi now require visible light transmission thresholds that only low-iron anti-reflective substrates can satisfy.
Market Restraints
- High-purity silica sand concentration:Low-iron substrate production depends on captive access to ultra-low-iron sand deposits concentrated in limited geographies.
- PVD equipment capex intensity:Closed-loop physical vapor deposition systems require substantial capital outlay, freezing out regional coating processors without balance sheet depth.
- Substitute material threat:Etched nanostructured polymers for display cover applications are capturing share in price-sensitive consumer electronics segments.
Strategic Opportunities
- Brazilian commercial glazing underpenetration:São Paulo and Rio de Janeiro building energy codes are tightening without local anti-reflective glass production, creating import substitution potential.
- Automotive head-up display convergence:Windshield-integrated HUD systems require anti-reflective properties combined with laminated safety glass, opening specification overlap with architectural suppliers.
- India PLI scheme alignment:The country's production-linked incentive scheme for solar module manufacturing is pulling anti-reflective glass localization into the subsidy perimeter.
Industry Challenges
- Thin-film coating technician scarcity:Precision PVD operation and nanolayer defect detection require specialized skills concentrated among German and Japanese equipment specialists.
- Dual certification timeline compression:Simultaneous REACH and China's GB standard compliance is extending qualification cycles for new coating formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Reflective Glass Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Coated, Laminated End User: Automotive, Electronics, Architectural, Optical Application: Displays, Glasses, Windows, Mirrors Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Sol-Gel, Spray Coating |
| Companies Covered | Abrisa Technologies, Essilor International, Saint-Gobain, PPG Industries, EuropeTec Groupe, 3M Company, Schott AG, Corning Incorporated, Guardian Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Reflective Glass Market Emerging Trajectories
Interference coating architectures and deposition methods are undergoing rapid revision as regulatory chemistry restrictions collide with demand for thinner, lighter substrates in mobile electronics and building integration.
Atomic layer deposition is rendering obsolete conventional sol-gel coating for high-precision electronics applications. Smartphone manufacturers in South Korea and Taiwan are specifying ALD-coated cover glass for flagship devices. The technology's angstrom-level thickness control is compressing acceptable defect tolerances and disqualifying spray-coating operations from premium supply chains.
China's MEE enforcement of dual carbon-aligned energy intensity standards on float glass furnaces is reshaping substrate supply economics. The regulation mandates specific carbon intensity thresholds per ton of melted glass. European coating houses dependent on Chinese low-iron substrate are accelerating supplier audits and diversifying toward German and French float operations.
Specification consolidation around certified coating suppliers is compressing distributor margins and eliminating non-specialized intermediaries. Large architectural glazing contractors in India and the UAE are issuing master service agreements directly to Saint-Gobain and Schott AG. The channel compression is most visible in Mumbai's commercial tower segment, where facade contractors now specify substrate and coating as a single procurement lot.
Global Anti-Reflective Glass Market Segmentation
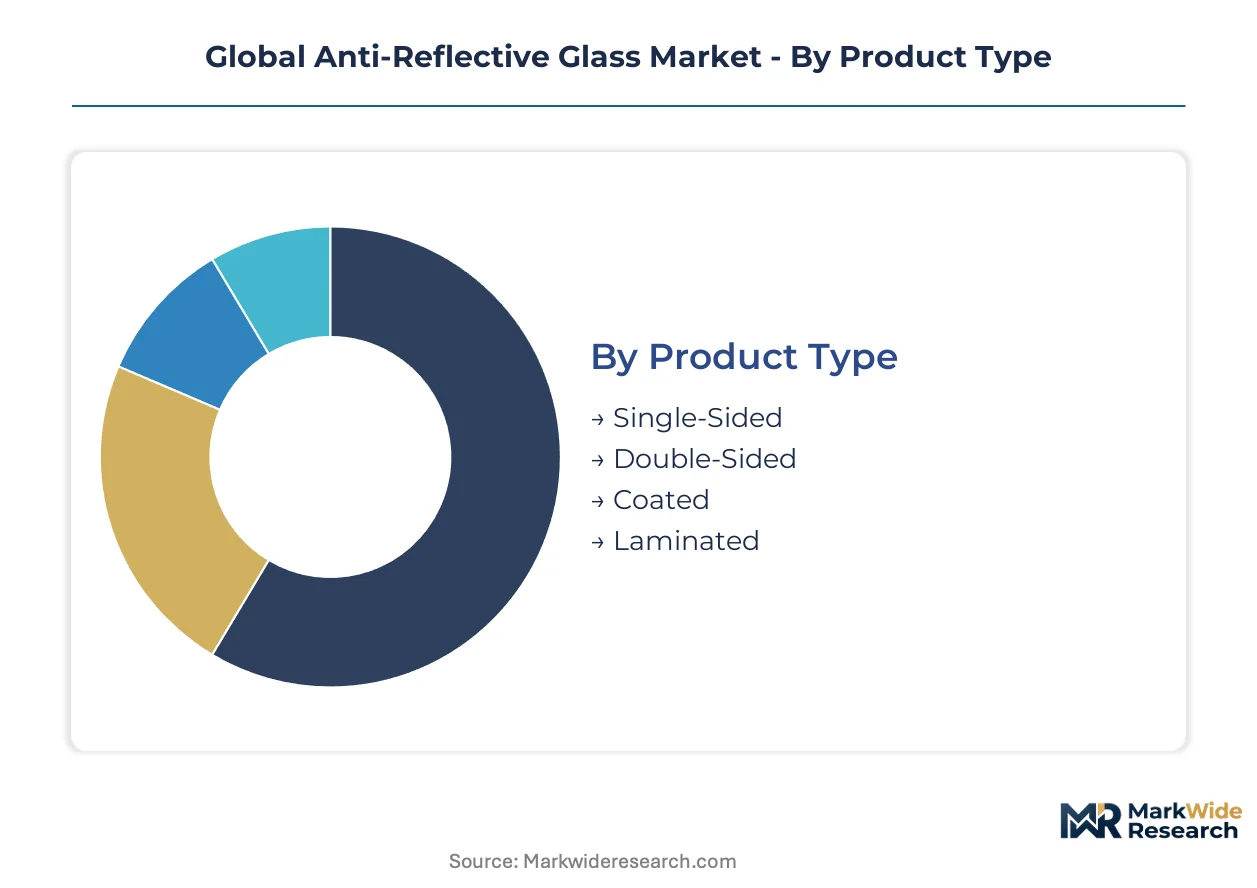
Anti-reflective glass procurement patterns diverge sharply by technical specification and end-use durability requirements. Solar farm developers, smartphone manufacturers, and facade engineers each impose distinct coating performance standards that reshape supplier qualification priorities across segment boundaries.
Product Type:
Double-sided products turn over fastest in commercial glazing tenders where both surfaces face optical demands; single-sided variants cycle slower in consumer electronics with one-sided exposure.
- Double-Sided:Nanometer-scale interference coatings on both substrate faces suppress reflectance below 2% across visible wavelengths. Mumbai and Delhi commercial tower specifications now mandate this configuration for curtain wall applications under tightened visible light transmission codes.
- Single-Sided:One-surface coating reduces material cost and processing time for applications where rear-surface reflection is tolerable. Solar photovoltaic installations in Germany and Japan favor this format for rear-contact cell architectures where backside optical performance matters less.
- Coated:Generic category covering substrate-plus-interference-layer systems without lamination. Electronics cover glass procurement in South Korea and Taiwan concentrates here for cost-sensitive mid-tier devices.
- Laminated:Anti-reflective layers bonded within safety glass sandwiches for impact resistance. Automotive head-up display windshields require this construction to combine optical clarity with crash performance.
Established volume favors single-sided; emerging adoption favors double-sided.
End User:
Cost tier stratification separates premium electronics specifications from price-sensitive architectural bulk procurement.
- Electronics:Smartphone and tablet manufacturers specify sub-1% reflectance for outdoor readability. Atomic layer deposition is displacing conventional coating for flagship devices in South Korea and Taiwan.
- Architectural:Commercial glazing contractors in India and the UAE issue master service agreements directly to certified suppliers. Low-iron substrate requirements under Mumbai and Delhi building codes concentrate procurement among float-to-coat integrators.
- Automotive:Windshield-integrated HUD systems demand anti-reflective properties combined with laminated safety construction. German and Japanese OEMs are tightening specification overlap with architectural suppliers.
- Optical:Precision instruments and scientific equipment require angstrom-level thickness control. German and Japanese equipment specialists dominate technician supply for this segment.
Electronics commands premium pricing; architectural drives absolute volume expansion.
Application:
Volume concentration clusters in displays and windows where scale economies justify dedicated coating lines.
- Displays:Cover glass for smartphones, tablets, and monitors represents the largest value concentration. ALD-coated variants for flagship devices in South Korea and Taiwan are climbing the fastest.
- Windows:Commercial and residential glazing absorbs bulk architectural volume. India's PLI scheme for solar module manufacturing is pulling anti-reflective glass localization into the subsidy perimeter.
- Glasses:Eyewear applications demand lightweight substrates with durable coatings. Etched nanostructured polymers are capturing share in price-sensitive consumer segments.
- Mirrors:Specialized anti-reflective rear-surface treatments for precision optical systems. German and Japanese equipment specialists maintain capability scarcity here.
Displays lead value contribution; windows dominate physical square meterage.
Technology:
Supply concentration favors PVD integrators with captive float glass operations; spray coating and sol-gel face regulatory compression.
- Physical Vapor Deposition:Closed-loop systems deposit uniform quarter-wave optical thickness layers on large-area substrates. EPA volatile organic compound regulations in the United States push manufacturers toward this technology.
- Chemical Vapor Deposition:Gas-phase precursor reactions enable conformal coating on complex geometries. Electronics applications in Taiwan and South Korea favor CVD for high-aspect-ratio features.
- Sol-Gel:Liquid-phase coating faces REACH restriction of hexavalent chromium and fluorinated compounds in Europe. ECHA deadlines are disqualifying uncertified coating houses.
- Spray Coating:Lowest capital intensity but poorest thickness uniformity. China's MEE dual carbon-aligned energy intensity standards raise barriers for uncertified processors.
PVD anchors established production; ALD variants within CVD are gaining fastest in premium electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's substrate distribution network, channeling low-iron float glass from French and domestic furnaces toward photovoltaic installations across Northern Europe and export markets.
Germany
Solar farm developers in Bavaria and Brandenburg mandate anti-reflective glass with sub-2% reflectance for utility-scale installations. ECHA's REACH restrictions on hexavalent chromium disqualify uncertified coating houses, redirecting volume toward qualified float-to-coat integrators. The Dresden-Leipzig corridor concentrates technician expertise for precision PVD operations serving optical instrument manufacturers.
China
Photovoltaic module assembly lines in Jiangsu and Zhejiang provinces drive substrate demand for export-oriented solar farms. MEE enforcement of dual carbon-aligned energy intensity standards on float glass furnaces raises barriers for uncertified coating processors. The Yangtze River Delta hosts captive low-iron sand processing and integrated float-to-coat operations serving domestic electronics manufacturers.
India
Commercial tower construction in Mumbai and Delhi mandates visible light transmission thresholds that only low-iron anti-reflective substrates satisfy. The PLI scheme for solar module manufacturing pulls anti-reflective glass localization into the subsidy perimeter. Gujarat's Mundra Port cluster emerges as the primary import gateway for float glass feeding western Indian glazing contractors.
Japan
Residential and utility-scale photovoltaic installations expand procurement of anti-reflective glass modules with stringent durability specifications. METI efficiency standards for building-integrated photovoltaics tighten coating performance requirements. The Nagoya-Osaka industrial corridor maintains specialized PVD technician training programs for high-precision electronics applications.
United States
Smartphone and tablet manufacturers specify anti-reflective cover glass for outdoor readability in flagship devices. EPA volatile organic compound regulations push coating operations toward closed-loop PVD systems and away from sol-gel processes. The Pacific Northwest hosts electronics assembly clusters sourcing ALD-coated substrates from Asian suppliers.
Global Anti-Reflective Glass Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling substrate quality and coating chemistry. The vendor base stratifies between float-to-coat integrators with captive furnace operations and independent coating houses dependent on merchant substrate supply. Three archetypes dominate: integrated glass-chemical conglomerates, specialized optical coating houses, and diversified materials science platforms. Competitive moves concentrate on backward integration into low-iron sand mining and strategic partnerships with photovoltaic module assemblers.
Within the integrated conglomerate tier, Saint-Gobain and Schott AG exemplify float-to-coat control extending from melt to final optical layer. Corning Incorporated occupies a position representing fusion-draw expertise adapted to thin, lightweight substrates. Abrisa Technologies and Essilor International sit within the specialized coating house archetype, dependent on qualified substrate supply from certified float operations. These five entities collectively span the technology spectrum from architectural bulk procurement to precision electronics specifications.
| Leading Market Players |
|---|
| Abrisa Technologies |
| Essilor International |
| Saint-Gobain |
| PPG Industries |
| EuropeTec Groupe |
| 3M Company |
| Schott AG |
| Corning Incorporated |
| Guardian Glass |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta's captive low-iron sand processing and integrated float-to-coat operations concentrate substrate supply leverage, translating furnace energy efficiency into pricing power over European coating houses dependent on merchant substrate. REACH compliance deadlines and China's MEE dual carbon standards compress qualification timelines, forcing uncertified processors to absorb certification costs or exit tender pools.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified float-to-coat integrators from qualified coating houses and uncertified regional processors. Premium tier pricing draws from Saint-Gobain and Schott AG's captive substrate control and REACH-compliant chemistry; standard tier hinges on volume scale for architectural glazing contractors in India and the UAE. Price erosion runs through the economy tier as etched nanostructured polymers capture display cover share from spray-coating operations. Solar farm developers in Germany and Japan exhibit least price sensitivity due to energy yield specifications; consumer electronics mid-tier device manufacturers face acute cost compression.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for coating houses sourcing low-iron substrate across the Pacific corridor. Captive supply concentrates in China, Germany, and France; merchant substrate flows from Australian and Brazilian ultra-low-iron sand deposits. Raw material dependencies rest on high-purity silica sand, titanium dioxide precursor chemicals, and specialized PVD equipment from German and Japanese specialists. Single-source vulnerability sits with thin-film coating technician training concentrated in the Dresden-Leipzig and Nagoya-Osaka corridors. Distribution runs through direct master service agreements between facade contractors and certified integrators, bypassing traditional specialty glass distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-reflective glass penetration sits at early-cycle expansion as building-integrated photovoltaics and automotive HUD convergence accelerate specification beyond traditional solar and display applications. Regulatory chemistry restrictions and dual carbon alignment create durable tailwinds for qualified suppliers with integrated float-to-coat control.
For Market Incumbents: Build technical certification moats by accelerating REACH and GB standard compliance for coating formulations before ECHA deadline compression eliminates competitor qualification windows. Saint-Gobain and Schott AG should extend captive low-iron sand mining partnerships in Australia and Brazil to offset Chinese substrate tariff exposure. Channel control through direct master service agreements with Mumbai and Delhi facade contractors locks out independent coating houses from premium architectural tenders. For New Entrants and Emerging Players: Brazilian commercial glazing underpenetration offers white-space entry as São Paulo and Rio de Janeiro building energy codes tighten without local anti-reflective glass production. India's PLI scheme for solar module manufacturing pulls localization into the subsidy perimeter, creating joint venture opportunity with Gujarat-based float glass operations. Go-to-market angle: import substitution partnerships with Mundra Port cluster distributors serving western Indian glazing contractors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because coating chemistry standardization under REACH and China's dual carbon framework concentrates procurement around certified integrators with durable qualification barriers. Acquisition target archetype: specialized optical coating houses with established PVD technician training programs and existing supplier audits from European architectural glazing contractors. Signal to watch: master service agreement consolidation rates in Mumbai commercial tower tenders indicating channel compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Iron Sand Mining | Australian and Brazilian deposit control secures substrate supply against Chinese MEE energy intensity enforcement. |
| Dual Certification Investment | Simultaneous REACH and GB standard compliance extends qualification cycles but eliminates uncertified competitor volume. |
| Direct Master Service Agreements | Mumbai and Delhi facade contractor bypass of distributors compresses channel margins and locks specification control. |
| Automotive HUD Specification Convergence | German and Japanese OEM windshield-integrated display demand opens architectural supplier overlap. |
| ALD Technology Transition | South Korean and Taiwanese smartphone manufacturer flagship specifications displace sol-gel from premium electronics supply chains. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with photovoltaic module procurement leads, architectural glazing contractors, thin-film coating technicians, float glass plant managers, and electronics cover glass specification engineers. Secondary validation drew from ECHA REACH restriction documentation, China's MEE dual carbon enforcement circulars, Indian PLI scheme administrative guidelines, EPA volatile organic compound regulatory filings, and customs trade data for low-iron float glass substrate flows. Bottom-up segment sizing across product type, end user, application, and technology dimensions was triangulated against top-down macroeconomic indicators for construction and electronics manufacturing.
Calibration against historical capacity expansion patterns and regulatory compliance timeline compression informed projection framework construction across the analysis window. Segmentation modeling incorporated coating chemistry type, substrate iron content grade, deposition technology precision tier, and regional regulatory cluster. CAGRs were derived from installed base growth in solar photovoltaic and commercial glazing applications, adjusted for specification upgrade rates from single-sided to double-sided configurations. Industry-specific forecast inputs included Mundra Port import volume trajectories and Nagoya-Osaka PVD technician training program graduation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed float-to-coat integrators or rapid etched nanostructured polymer substitution in consumer electronics would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Tableware Market
Glass
Glass Lens Market
Glass
Silica Sand Market
Glass
Europe Glassware Market
Glass
Recycled Glass Market
Glass
Crystalware and Glassware Market
Glass
Porous Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
India Flat Glass Market
Glass
Tinted Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Solar Control Glass Market
Glass
Europe Flat Glass Market
Glass
Global Laminated Glass Market
Glass
Metallic Glass Market
Glass
Glass Reactors Market