
 Energy Efficient Materials Market | 2026-2036
Energy Efficient Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Materials Market Analysis
Green project finance and performance-based leasing is fragmenting the competitive landscape for energy efficient materials, allowing mid-sized contractors and retrofit specialists to bid on large-scale building envelope projects without carrying full capital burdens. Saint-Gobain leverages its vertically integrated glass and insulation portfolio to control raw material flows across multiple product lines. Owens Corning anchors its position through dense fiberglass manufacturing networks and building science expertise in North American residential envelopes. Kingspan Group specializes in insulated panel systems and competes through rapid-build modular construction partnerships.
Energy efficient materials encompass engineered substances designed to reduce thermal transfer, minimize energy consumption, and improve building or equipment performance through low thermal conductivity, high reflectance, or latent heat storage properties; these include aerogel insulations, low-emissivity glass coatings, and paraffin-based phase change materials that stabilize indoor temperatures. Insulating materials dominate current volume as mature fiberglass and mineral wool products serve baseline retrofit demand, while phase change materials represent the fastest-expanding segment as architects integrate thermal mass into lightweight structures. Reflective coatings concentrate margin pools in warm-climate commercial roofing where cool roof mandates expand addressable market scope.
The EU Green Deal and REACH chemical standards shape product formulations and market access for European suppliers, while the EPA Energy Star program and ASHRAE building standards drive specification requirements in the United States. China's GB standards for building energy efficiency and MIIT industrial policy directives enforce domestic material performance benchmarks that foreign entrants must satisfy. Stakeholders must monitor how evolving carbon border adjustment mechanisms and embodied carbon disclosure rules will reshape sourcing decisions and supplier qualification criteria across major construction markets.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing building material suppliers to requalify supply chains around embodied carbon disclosure, compressing qualification timelines for insulation and glazing products destined for European retrofit projects.
Growth Catalysts
- EU Green Deal enforcement:The EU Green Deal and tightening building energy codes across Germany, France, and Italy accelerate material substitution in existing building stock, pulling demand toward low-carbon insulation and high-performance glazing systems.
- Phase change material integration:Architects in lightweight commercial construction are embedding paraffin-based phase change materials to stabilize indoor temperatures without structural thermal mass, expanding addressable applications for thermal storage solutions.
- China retrofit mandates:China's GB standards for building energy efficiency and MIIT industrial policy directives enforce domestic material performance benchmarks that foreign entrants must satisfy, concentrating demand in tier-one cities.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and polystyrene insulation manufacturers face margin compression from benzene and propylene price swings, limiting pricing flexibility for large-scale envelope projects.
- Silica supply concentration:Aerogel production depends on specialized silica precursors concentrated in Chinese industrial zones, creating single-source vulnerability for North American and European insulation suppliers.
- REACH compliance friction:ECHA chemical standards restrict certain flame retardant formulations used in rigid foam insulation, forcing reformulation cycles that delay product launches by 18-24 months.
Strategic Opportunities
- India commercial building codes:India's Energy Conservation Building Code enforcement in Mumbai, Delhi, and Bangalore creates first-mover advantage for cool roof coating and high-performance glass suppliers as local manufacturing scales.
- Modular construction partnerships:Rapid-build modular construction partnerships with hospital and school developers in Germany and the Netherlands open specification channels for insulated panel systems outside traditional general contractor relationships.
- Carbon accounting integration:Embodied carbon disclosure rules in California, New York, and Washington State position environmental product declaration-certified materials for premium specification in public procurement.
Industry Challenges
- Building science expertise scarcity:Deep energy retrofit contractors struggle to hire certified energy auditors and envelope commissioning agents, slowing project throughput in Massachusetts and British Columbia markets.
- Multi-certification stacking:Manufacturers must simultaneously satisfy EPA Energy Star, ASHRAE 90.1, and local utility rebate program requirements, fragmenting R&D resources across incompatible testing protocols.
- Legacy HVAC integration:High-performance envelope upgrades in 1970s commercial buildings create control system conflicts with existing pneumatic thermostats, requiring costly BAS replacements that stall owner commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Materials Market |
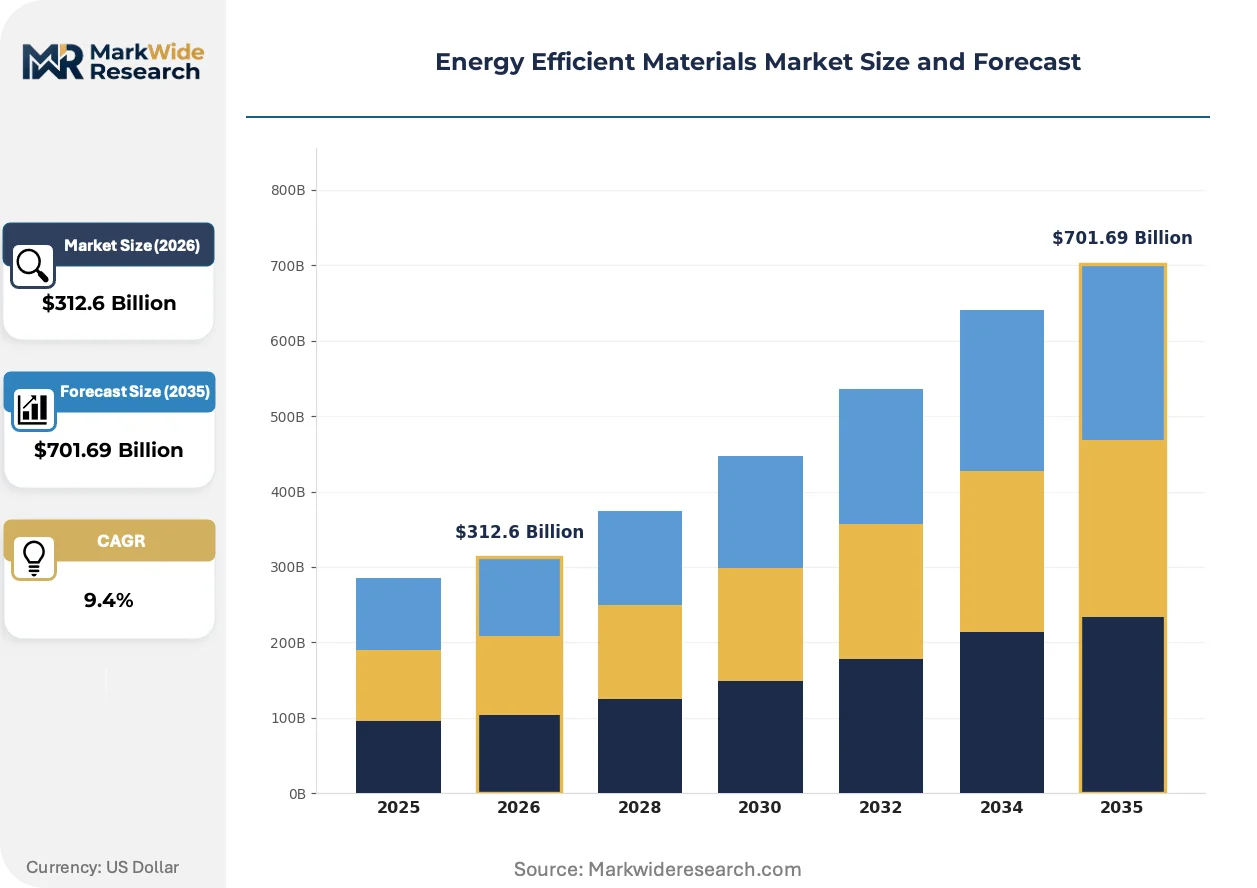
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $701.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulating Materials, Reflective Coatings, Energy-Efficient Windows, Phase Change Materials Application: Building Construction, Automotive, Electronics, Renewable Energy Systems End User: Residential, Commercial, Industrial, Government Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Saint-Gobain, Owens Corning, PPG Industries, AGC, NSG, BASF, Rockwool International, Kingspan Group, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Materials Market Emerging Trajectories
Material science breakthroughs and procurement model reinvention are compressing traditional specification cycles, enabling performance-based material selection that bypasses incumbent brand relationships in commercial construction.
Aerogel blanket insulation is collapsing the thickness-performance tradeoff that has governed envelope design for decades. Data center operators and cold storage developers in Northern Europe are specifying 10mm aerogel layers in place of 100mm mineral wool, cutting structural load and footprint requirements. This substitution is collapsing the installed cost gap between premium and conventional insulation in space-constrained retrofits.
REACH chemical standards and the EU F-Gas Regulation are eliminating hydrofluorocarbon blowing agents from polyurethane foam production. European insulation manufacturers are retrofitting production lines to pentane and hydro-olefin alternatives, with Germany and Poland experiencing the fastest formulation turnover. The regulatory pressure is compressing the supply base to suppliers with in-house chemical synthesis capabilities.
Performance-based leasing is fragmenting traditional material specification authority. Institutional asset managers in London, Singapore, and Sydney are writing energy use intensity guarantees into lease structures, giving facilities operators direct procurement control over envelope upgrades. This shift is bypassing architect-specifier relationships and concentrating purchasing power with technical property management platforms.
Energy Efficient Materials Market Segmentation
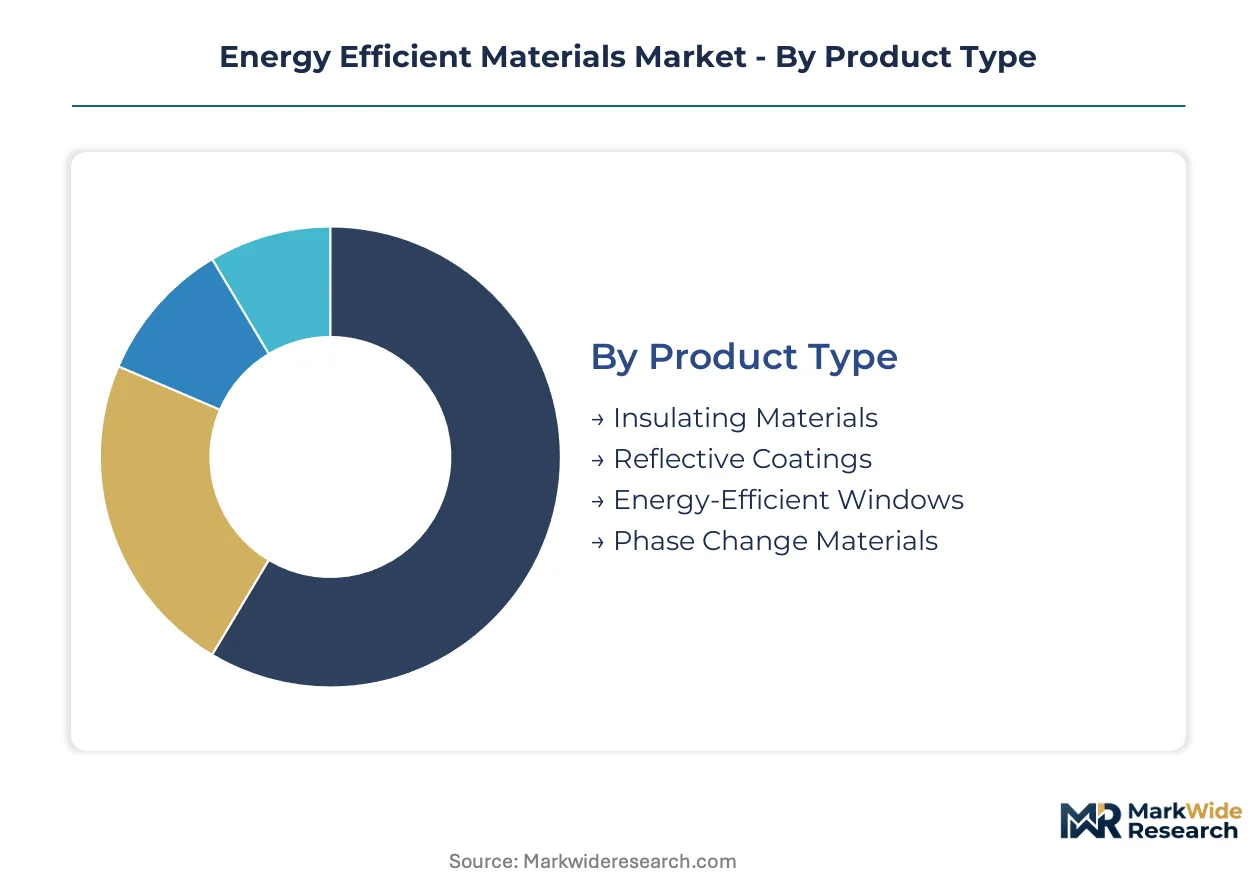
Energy efficient materials serve divergent thermal performance requirements across building envelopes, transportation systems, and industrial equipment. Segmentation reveals how formulation chemistry and installation methods must adapt to structural constraints, fire safety codes, and lifecycle cost calculations in each application cluster.
Product Type:
Use-case spectrum spans from baseline thermal barriers in residential retrofits to precision temperature stabilization in semiconductor manufacturing environments.
- Insulating Materials:Fiberglass, mineral wool, and rigid foam boards provide foundational thermal resistance for wall cavities and roof assemblies. Demand concentrates in German and Polish residential retrofit programs where building energy codes mandate minimum R-value upgrades in post-war housing stock.
- Phase Change Materials:Paraffin-based and salt hydrate formulations absorb and release latent heat to dampen indoor temperature swings. Architects in lightweight commercial construction across the Netherlands and Singapore embed these materials to compensate for reduced structural thermal mass in modular building systems.
- Reflective Coatings:Acrylic and silicone-based roof coatings with high solar reflectance index values reduce cooling loads. Specifications are climbing fastest in Indian and Australian commercial roofing where cool roof mandates intersect with extreme solar exposure.
- Energy-Efficient Windows:Low-emissivity glass with argon gas fills and warm-edge spacers cut conductive and radiative heat transfer. Procurement concentrates in California and New York high-rise residential where stringent envelope performance targets drive glazing replacement cycles.
Established volume favors insulating materials; emerging adoption favors phase change materials.
Application:
Cost tier stratification separates commodity envelope products from engineered thermal solutions in precision manufacturing environments.
- Building Construction:Wall insulation, roofing systems, and fenestration dominate material consumption by tonnage and value. Retrofit mandates in China, Germany, and the United States pull demand toward low-carbon insulation and high-performance glazing systems.
- Automotive:Lightweight thermal barriers for battery enclosures and cabin insulation reduce HVAC energy draw in electric vehicles. Cell manufacturers in South Korea and Germany specify aerogel layers to manage thermal runaway risks in high-density battery packs.
- Electronics:Thermal interface materials and phase change compounds stabilize operating temperatures in data centers and telecommunications equipment. Hyperscale operators in Northern Europe deploy thin-profile aerogel insulation to maximize server density in space-constrained facilities.
- Renewable Energy Systems:High-temperature insulation for concentrated solar power receivers and thermal storage vessels. Project developers in Spain and Morocco integrate molten salt-compatible insulation systems for grid-scale energy storage.
Building construction commands the highest absolute volume; electronics applications show the steepest expansion trajectory as data center thermal loads intensify.
End User:
Customer type determines specification authority, procurement cycle length, and sensitivity to lifecycle cost versus first-cost tradeoffs.
- Residential:Single-family and multifamily building owners prioritize utility rebate eligibility and installer availability. Retrofit demand concentrates in Massachusetts and British Columbia where energy audit requirements and financing programs lower adoption barriers.
- Commercial:Office, retail, and hospitality developers face energy use intensity targets in lease structures and green building certifications. Asset managers in London and Sydney write thermal performance guarantees that shift envelope upgrade decisions to facilities operators.
- Industrial:Manufacturing facilities and cold storage operators optimize for process temperature stability and refrigeration energy reduction. Food processing and pharmaceutical cold chain operators in Germany and the United States specify high-performance envelope systems to maintain stringent temperature bands.
- Government:Public procurement mandates embodied carbon disclosure and environmental product declaration certification. State-level procurement rules in California, New York, and Washington position low-carbon insulation materials for premium specification in schools and municipal buildings.
Commercial end users drive specification innovation; government procurement is accelerating carbon accounting integration across supplier qualification.
Distribution Channel:
Supply concentration varies by product complexity, with engineered materials bypassing traditional wholesale channels.
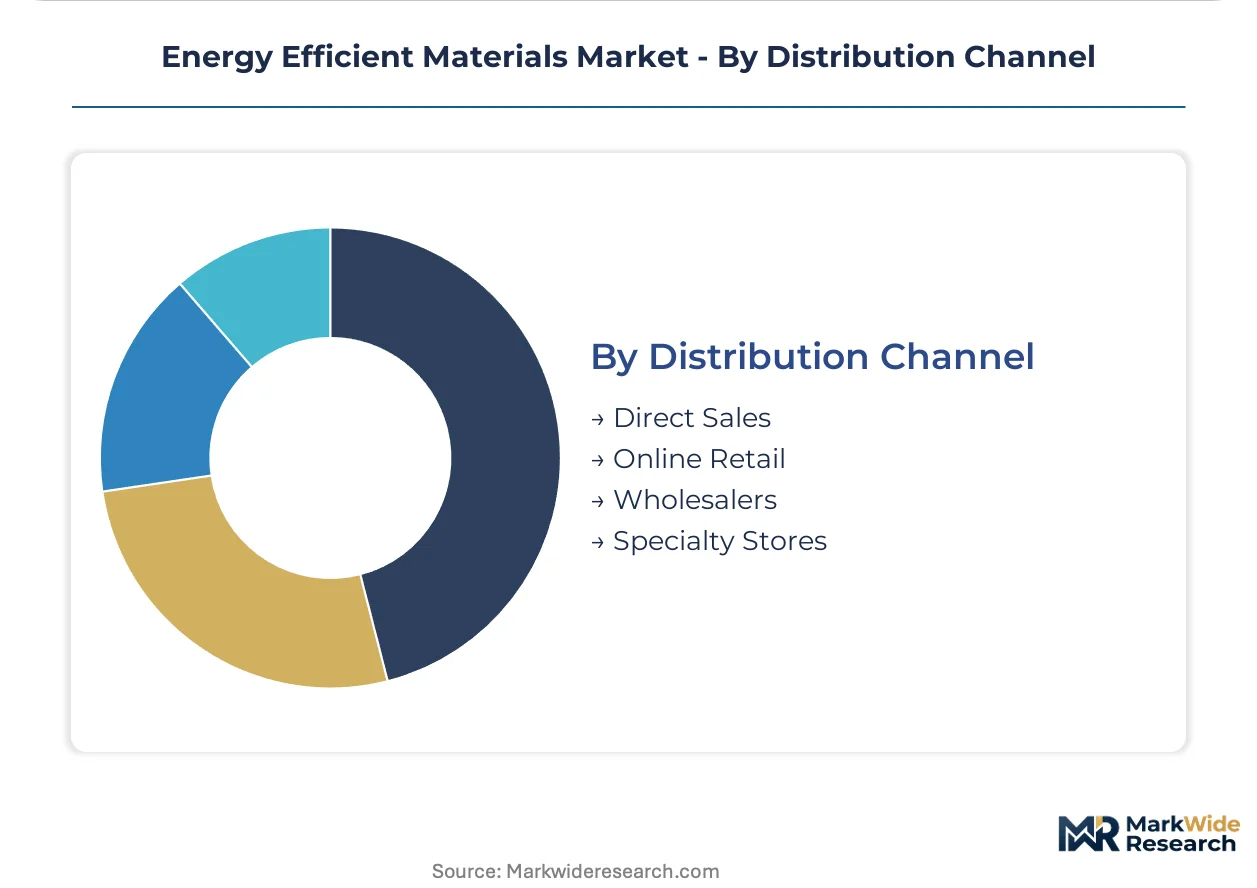
- Direct Sales:Manufacturers engage large-scale developers and general contractors for project-specific envelope engineering. Major retrofit contractors in Germany and the Netherlands source insulated panel systems directly from Kingspan and similar specialists to coordinate rapid-build schedules.
- Wholesalers:Regional distributors stock commodity insulation and glazing for residential and light commercial contractors. Independent distributors in the United States maintain dense fiberglass and mineral wool inventories to serve same-day contractor demand.
- Specialty Stores:Focused retailers serve professional installers with technical product support and building science guidance. Certified passive house suppliers in Austria and Sweden provide specification assistance for high-performance envelope assemblies.
- Online Retail:E-commerce platforms capture small-scale residential retrofit and DIY thermal improvement projects. Digital channels gain traction for reflective roof coatings and weatherization kits in markets with mature contractor networks.
Direct sales capture the most complex engineered systems; wholesalers retain dominance in high-volume commodity insulation flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset managers in London, Singapore, and Sydney drive specification authority for envelope upgrades, while retrofit contractors in Germany and Massachusetts compete for certified energy auditors. Demand clusters where green building mandates intersect with performance-based leasing structures.
United States
State-level procurement rules in California, New York, and Washington position low-carbon insulation materials for premium specification in schools and municipal buildings. The EPA Energy Star program and ASHRAE building standards drive specification requirements across commercial construction. Retrofit demand concentrates in Massachusetts and British Columbia markets where energy audit requirements lower adoption barriers.
Germany
Building energy codes mandate minimum R-value upgrades in post-war housing stock, pulling demand toward low-carbon insulation and high-performance glazing systems. The EU Green Deal and REACH chemical standards shape product formulations and market access for European suppliers. Major retrofit contractors in Germany and the Netherlands source insulated panel systems directly from specialists to coordinate rapid-build schedules.
China
MIIT industrial policy directives enforce domestic material performance benchmarks that foreign entrants must satisfy, concentrating demand in tier-one cities. GB standards for building energy efficiency mandate retrofit compliance in urban building stock. Silica supply concentration in Chinese industrial zones creates single-source vulnerability for North American and European insulation suppliers sourcing aerogel precursors.
India
Energy Conservation Building Code enforcement in Mumbai, Delhi, and Bangalore creates first-mover advantage for cool roof coating and high-performance glass suppliers. Specifications climb fastest in Indian and Australian commercial roofing where cool roof mandates intersect with extreme solar exposure. Local manufacturing scales to meet public procurement requirements for embodied carbon disclosure.
Netherlands
Architects in lightweight commercial construction embed paraffin-based phase change materials to compensate for reduced structural thermal mass in modular building systems. Rapid-build modular construction partnerships with hospital and school developers open specification channels for insulated panel systems outside traditional general contractor relationships. Certified passive house suppliers in Austria and Sweden provide specification assistance for high-performance envelope assemblies.
Energy Efficient Materials Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification-heavy segments. The vendor base clusters around three strategic archetypes: vertically integrated material conglomerates controlling raw material flows, dense manufacturing network operators anchoring regional distribution, and rapid-build modular specialists partnering directly with developers. M&A activity concentrates on chemical synthesis capabilities for blowing agent transitions, while strategic partnerships target modular construction channels.
Within the integrated-materials tier, Saint-Gobain and Owens Corning occupy positions that exemplify contrasting scale strategies. Kingspan Group sits within the modular-specialist archetype, representing the partnership-driven specification channel. These three anchors illustrate how competitive positioning fragments across channel control, manufacturing density, and direct-developer relationships.
| Leading Market Players |
|---|
| Saint-Gobain |
| Owens Corning |
| PPG Industries |
| AGC |
| NSG |
| BASF |
| Rockwool International |
| Kingspan Group |
| 3M |
| Others |
Supply Flow & Price Mechanics
Shandong Province's silica precursor concentration grants Chinese aerogel suppliers outsized leverage over global insulation pricing, compressing margin buffers for European and North American manufacturers who lack backward integration into specialized feedstock production.
Pricing Analysis
Cost-plus contracts with benzene and propylene indexation dominate polyurethane foam procurement, insulating manufacturers from acute margin swings while locking in thinner spreads during petrochemical volatility. Price differentiation separates EPD-certified low-carbon insulation from commodity fiberglass, with California public procurement paying premiums for embodied carbon disclosure. Pricing pressure stems from REACH reformulation cycles, where flame retardant compliance delays product launches and extends R&D payback periods. Residential retrofit contractors show highest price sensitivity, while data center operators prioritize space-constrained aerogel performance over per-unit cost.
Supply Chain Analysis
Upstream petrochemical feedstocks concentrate in China, Germany, and the United States, with benzene and propylene derivatives feeding rigid foam insulation production across all three hubs. Silica precursors for aerogel manufacturing draw from Shandong industrial zones, creating single-source vulnerability for insulation suppliers without captive supply arrangements. Tariff exposure on Chinese silica imports threatens North American aerogel cost structures. Distribution runs through regional wholesalers for commodity fiberglass, while engineered systems bypass to direct sales with major retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional asset managers in London, Singapore, and Sydney are consolidating envelope upgrade procurement authority through performance-based leasing structures, fragmenting traditional architect-specifier relationships and shifting bargaining power toward technical property management platforms.
For Market Incumbents: Pre-empt modular construction channel capture by partnering directly with hospital and school developers in Germany and the Netherlands before specification authority migrates to facilities operators. Anchor position through in-house production of pentane and hydro-olefin blowing agents as REACH eliminates hydrofluorocarbon alternatives, compressing the supply base to chemically integrated manufacturers.
For New Entrants and Emerging Players: Establish a beachhead in India's commercial roofing segment as Energy Conservation Building Code enforcement in Mumbai, Delhi, and Bangalore creates first-mover advantage for cool roof coating suppliers before local manufacturing scales. Target specification channels through certified passive house suppliers in Austria and Sweden who provide technical guidance for high-performance envelope assemblies.
For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because embodied carbon disclosure rules in California, New York, and Washington State are repositioning EPD certification as a procurement gate. Target acquisition candidates with in-house chemical synthesis capabilities for blowing agent transitions. The signal to watch is carbon border adjustment mechanism enforcement timelines for European retrofit project qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursors | Captive supply of Shandong-sourced feedstock insulates aerogel margins from import tariff exposure. |
| REACH-Compliant Blowing Agent Transition | Pentane and hydro-olefin retrofit lines in Germany and Poland secure European market access. |
| Modular Construction Partnership | Direct relationships with Dutch hospital developers bypass traditional general contractor channels. |
| EPD Certification Investment | California public procurement rules position certified materials for premium specification in schools. |
| Performance-Based Leasing Integration | Energy use intensity guarantees in London lease structures concentrate purchasing with technical operators. |
Methodological Framework
Initial hypotheses were tested against primary input from building envelope engineers, retrofit contractors, facilities operators at institutional asset managers, and procurement leads at modular construction developers, then refined through secondary validation against EU Green Deal implementation documents, EPA Energy Star certification databases, MIIT industrial policy directives, and ASHRAE 90.1 standard revisions. Bottom-up project pipeline analysis and top-down construction spend allocation were triangulated to anchor volume estimates.
Demand-supply balance across insulating materials, phase change materials, reflective coatings, and energy-efficient windows was modeled against retrofit mandate enforcement timelines and green building certification adoption curves. CAGRs were derived from segment-level growth rate reconciliation with macro construction indicators. Forecast inputs included building energy code stringency indices and carbon border adjustment mechanism implementation schedules.
Stress conditions across petrochemical feedstock volatility, REACH reformulation delays, and silica supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against national building permit databases and utility rebate program disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Thin Film Materials Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Smart Card Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Functional Composites Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Rapid Self-Healing Gel Market