

Adaptive Camouflage Materials Market Size, Share, and Industry Trends Forecast 2026-2036
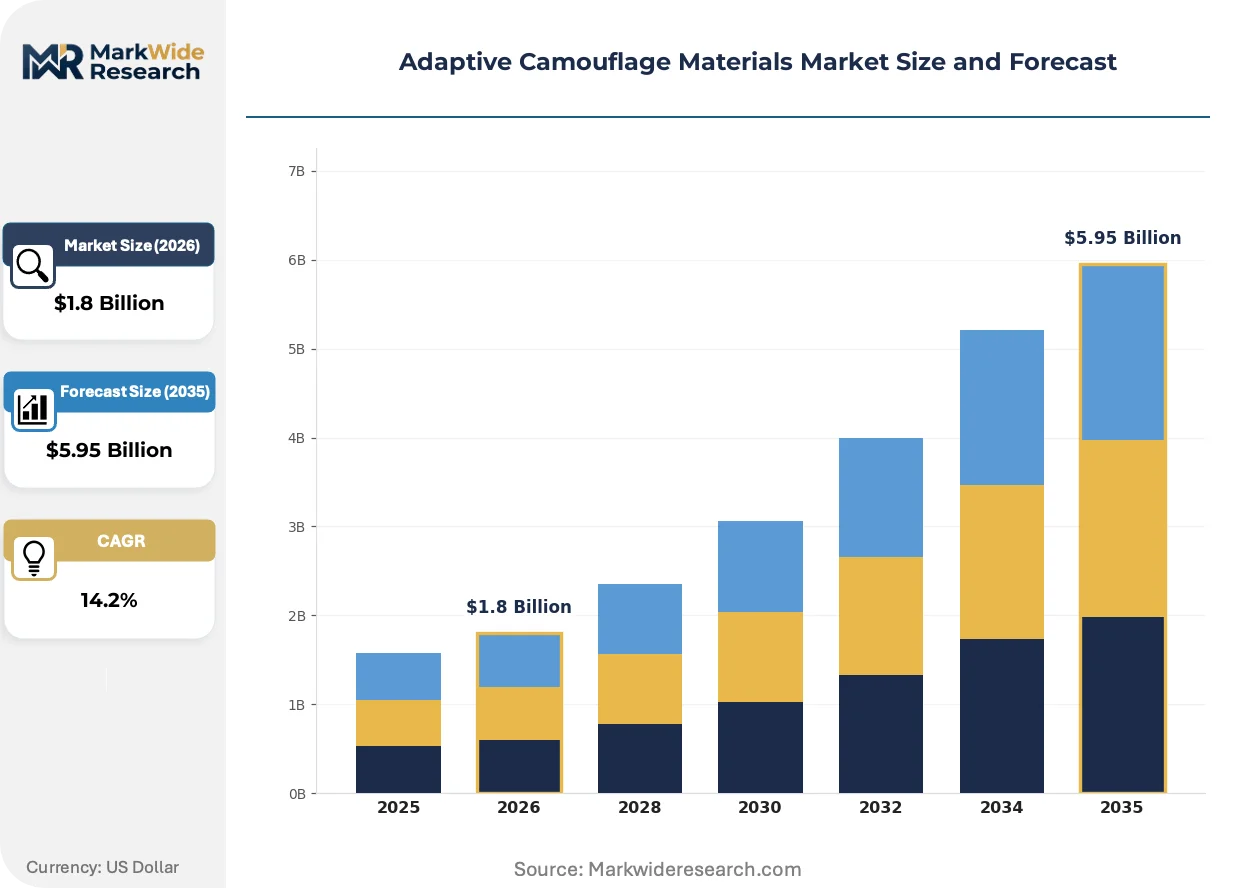
Adaptive Camouflage Materials Market Insights
The gap between premium metamaterial systems and commodity chromic coatings is rebalancing as defense procurement shifts from demonstration contracts to volume orders. BAE Systems leverages its UK manufacturing base to sustain electrochromic production lines for vehicle applications. Rheinmetall anchors European supply through its Bundeswehr-focused R&D programs. Saab AB competes in Nordic markets with specialized UAV coating solutions.
Adaptive camouflage materials comprise engineered substrates—metamaterials, photonic crystals, conductive polymers, and electroluminescent films—that modulate visible, infrared, or radar signatures through active stimulus response, typically operating across wavelength bands from 400 nm to 14 μm for military concealment purposes. Chromic materials dominate current volume shipments due to lower unit costs and simpler integration pathways, while metamaterials command premium positioning where multi-spectral stealth performance justifies expenditure. Military apparel and UAV coating applications absorb the majority of program funding, with wearable devices representing an emerging demand pocket as law enforcement agencies evaluate civilian variants.
Defense procurement standards from the US Department of Defense, CE marking requirements under EU defense procurement directives, and South Korean DAPA specifications collectively determine product qualification pathways and market access conditions. The US ITAR regime restricts technology transfer for advanced metamaterial architectures, compressing competitive options for non-US suppliers. Stakeholders must monitor evolving electromagnetic spectrum allocation decisions by national regulators, as these directly constrain the operational envelope for active camouflage systems and shape long-term R&D allocation priorities.
Market Dynamics
Defense procurement's pivot from demonstration contracts to volume production orders is compressing lead times and forcing substrate suppliers to reconfigure manufacturing footprints for chromic and metamaterial lines simultaneously.
Growth Catalysts
- Soldier Modernization Mandates:NATO member defense agencies allocate procurement budgets toward signature management systems, with electrochromic vehicle coatings absorbing program funding increases.
- REACH Compliance Pathways:EU defense procurement directives incorporating CE marking requirements accelerate material certification timelines for conductive polymer substrates entering European supply chains.
- Multi-Spectral Stealth Performance:Photonic crystal architectures enable simultaneous visible-infrared-radar signature modulation, justifying premium positioning in UAV coating applications where detection avoidance spans 400 nm to 14 μm wavelength bands.
Market Restraints
- ITAR Technology Transfer Restrictions:US export controls on advanced metamaterial architectures compress competitive options for non-US suppliers seeking Pentagon contract eligibility.
- Raw Material Concentration:Rare earth element processing for electrochromic oxides concentrates in Chinese supply chains, exposing European and North American coaters to input cost volatility.
- Metamaterial Scalability Limits:Precision fabrication requirements for negative-index substrates constrain batch sizes, preventing unit cost reductions comparable to chromic material production curves.
Strategic Opportunities
- Law Enforcement Wearable Devices:Civilian variants of adaptive camouflage apparel attract evaluation budgets from municipal police departments in Germany and South Korea seeking tactical concealment for urban operations.
- FCC Spectrum Allocation Decisions:Electromagnetic spectrum rulings for active camouflage system operation create regulatory tailwinds for electroluminescent film manufacturers qualifying devices under revised frequency bands.
- Metamaterial-Chromic Hybrid Architectures:Convergence of engineered substrates with simpler chromic coatings enables tiered product portfolios spanning premium multi-spectral and standard single-band applications.
Industry Challenges
- Multi-Domain Certification Timelines:Simultaneous qualification against US Department of Defense, EU defense procurement, and South Korean DAPA specifications extends product development cycles by 18-24 months.
- Electrochromic Integration Complexity:Power supply and control system compatibility with legacy vehicle electronics platforms requires specialized engineering teams scarce in regional defense industrial bases.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Camouflage Materials Market Trends and Innovations
Active stimulus-response substrates are fragmenting into application-specific configurations as end-users reject universal camouflage solutions in favor of wavelength-optimized performance.
Metamaterial architectures incorporating tunable plasmonic resonators is modularizing across vehicle, soldier, and UAV platforms. Bundeswehr procurement offices specify interchangeable substrate panels for Leopard fleet upgrades. This modularity enables suppliers to standardize core fabrication processes while customizing surface patterning for specific operational environments.
FCC electromagnetic spectrum rulings for 5G and defense frequency sharing reshape active camouflage system operational envelopes. Manufacturers must redesign electroluminescent film drive electronics to avoid interference with commercial communications bands. US Army ground vehicle programs absorb the majority of compliance engineering resources as they prioritize uninterrupted multi-spectrum concealment.
Defense procurement offices compress supplier qualification cycles through pre-certified substrate libraries. South Korean DAPA maintains approved vendor lists for chromic coating formulations, displacing traditional bilateral contracting. Tier-2 coaters in Busan and Daegu specialize in rapid color-matching services for these pre-qualified material sets.
Adaptive Camouflage Materials Market Segmentation
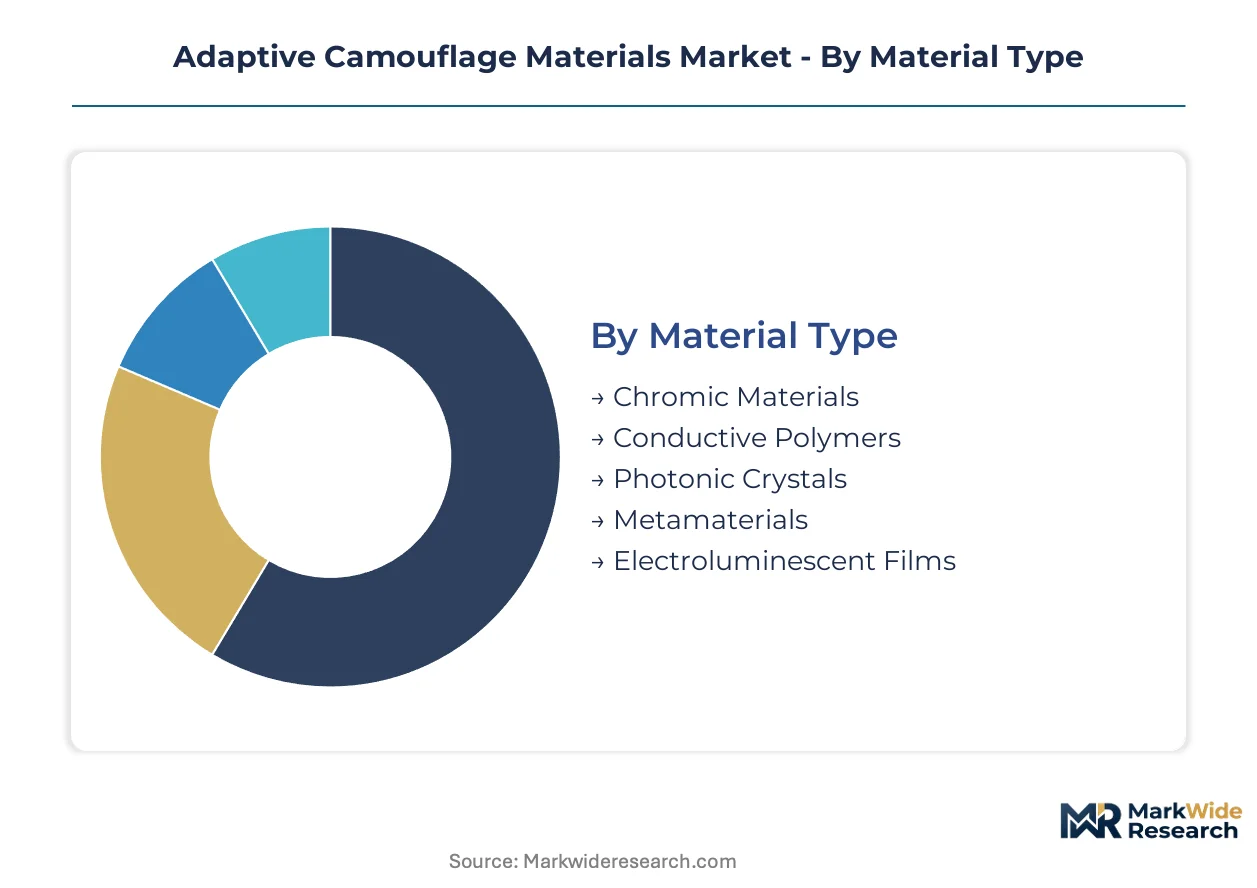
Segmentation in adaptive camouflage materials reveals distinct integration pathways. Standalone systems demand complete power and control architectures, while embedded configurations leverage host platform infrastructure. Procurement patterns diverge sharply across these boundaries.
Material Type:
Integration depth varies substantially: chromic and conductive polymers embed readily into existing textile and coating processes, whereas metamaterials and photonic crystals require dedicated fabrication lines and system-level engineering.
- Chromic Materials:Thermochromic and photochromic oxides modulate visible and near-infrared signatures through passive thermal or optical stimulus. Defense agencies in the United States and Germany absorb volume shipments for soldier modernization programs where battery-free operation proves advantageous. REACH compliance pathways under ECHA accelerate European certification timelines.
- Metamaterials:Engineered negative-index substrates with tunable plasmonic resonators enable simultaneous multi-spectral stealth across 400 nm to 14 μm bands. UAV coating applications in South Korea justify premium positioning where detection avoidance spans radar through thermal detection. ITAR restrictions constrain non-US supplier participation in Pentagon procurement cycles.
- Conductive Polymers:PEDOT:PSS and polyaniline formulations integrate into textile weaving processes for military apparel with moderate electrochromic response.
- Photonic Crystals:Periodic dielectric structures provide angular-dependent color shifting for specialized vehicle applications requiring precise viewing-angle concealment.
- Electroluminescent Films:Thin-film phosphor layers require external AC drive electronics, limiting deployment to platforms with available power infrastructure.
Volume placements concentrate in chromic materials; the faster expansion belongs to metamaterials.
Technology:
Cost stratification separates passive stimulus-response mechanisms from active powered systems, with procurement budgets allocating disproportionately to battery-dependent configurations for multi-spectral performance.
- Electrochromic:Voltage-driven tungsten oxide and viologen systems achieve rapid color switching for vehicle signature management. BAE Systems sustains UK production lines for Bundeswehr Leopard fleet upgrades. Power supply integration with legacy military electronics platforms extends engineering qualification cycles.
- Thermochromic:Temperature-responsive liquid crystals and leuco dyes operate without external power, dominating disposable military apparel applications where battery weight proves prohibitive.
- Electromagnetic:Radar-absorbent ferrite and carbonyl iron composites embed into UAV airframes for reduced cross-section returns.
- Photochromic:UV-triggered silver halide and naphthopyran compounds serve consumer transition lens markets with limited military crossover.
- Mechanoluminescent:Stress-activated crystal structures remain experimental, attracting R&D funding for structural health monitoring rather than concealment.
Defense procurement tilts toward electrochromic systems; mechanoluminescent approaches remain pre-commercial.
Application:
Customer type determines margin structure: military end-users accept extended qualification timelines for certified performance, while commercial segments prioritize rapid color-matching and supply responsiveness.
- Military Apparel:Combat uniforms and load-bearing equipment incorporate electrochromic panels for dynamic background matching. Tier-2 coaters in Busan specialize in rapid turnaround for South Korean DAPA pre-qualified material sets. Multi-domain certification against US DoD, EU defense procurement, and DAPA specifications extends development cycles.
- UAV Coating:Airframe skins demand simultaneous visible-infrared-radar signature suppression across 400 nm to 14 μm. Photonic crystal architectures justify premium positioning where detection avoidance determines mission survivability.
- Wearable Devices:Law enforcement agencies in Germany evaluate civilian variants for urban tactical operations.
- Consumer Electronics:Smartphone and laptop aesthetic applications drive chromic film volumes with minimal performance requirements.
- Industrial Equipment:Machinery concealment for surveillance firms represents a niche demand pocket with irregular procurement patterns.
Program funding concentrates in military apparel; UAV coating applications are climbing the fastest.
End User:
Procurement authority concentration shapes supplier access: defense agencies maintain approved vendor lists, while fashion and automotive segments operate through conventional commercial contracting.
- Defense Agencies:NATO member states and South Korean DAPA drive volume through soldier modernization and vehicle signature management programs. FCC electromagnetic spectrum rulings constrain active system operational envelopes for electroluminescent film deployments.
- Surveillance Firms:Private intelligence contractors purchase chromic coatings for fixed-site concealment with limited multi-spectral requirements.
- Security Services:Municipal police departments in Germany and South Korea evaluate wearable adaptive camouflage for specialized urban operations.
- Automotive Manufacturers:Concept vehicle demonstrations consume small-batch electrochromic films without production-scale commitment.
- Fashion Designers:Runway and luxury apparel applications prioritize aesthetic novelty over functional performance specifications.
Contract value concentrates with defense agencies; security services demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan anchors the Asia-Pacific defense coating cluster, with Daegu-Gyeongbuk forming a secondary hub for chromic material processing. European concentration centers on German Bundeswehr procurement corridors, while US manufacturing gravitates toward ITAR-compliant facilities serving Pentagon modernization programs.
United States
Pentagon soldier modernization programs and UAV signature management contracts absorb the majority of North American procurement volume. FCC electromagnetic spectrum rulings constrain active electroluminescent film operational envelopes, forcing drive electronics redesigns. Defense industrial base concentration in Virginia and Texas sustains ITAR-compliant metamaterial fabrication for multi-spectral stealth applications.
Germany
Bundeswehr Leopard fleet upgrades and NATO cooperative defense initiatives channel investment toward electrochromic vehicle coatings. REACH compliance pathways under ECHA accelerate conductive polymer substrate certification for European supply chain entry. Bavaria-based R&D programs anchor continental metamaterial development for visible-infrared signature modulation.
South Korea
DAPA pre-qualified material sets and rapid color-matching services drive procurement centralization in the Seoul Capital Area. MFDS-equivalent defense procurement specifications govern chromic coating formulation approvals for military apparel integration. Busan-Ulsan coating clusters specialize in volume production for UAV airframe applications requiring 400 nm to 14 μm band suppression.
United Kingdom
UK Ministry of Defence electrochromic vehicle programs sustain manufacturing throughput at specialized production facilities. CE marking requirements under EU defense procurement directives shape material qualification pathways for cross-border NATO supply. Greater London defense contracting offices compress supplier evaluation cycles through pre-certified substrate library adoption.
Sweden
Nordic cooperative defense procurement and Arctic warfare signature management requirements concentrate demand in specialized UAV coating solutions. Swedish Defence Materiel Administration specifications emphasize multi-spectral performance in extreme thermal environments. Saab AB's Linköping operations exemplify regional concentration in photonic crystal architecture development for detection-critical missions.
Adaptive Camouflage Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and multi-spectral performance tiers. Defense procurement consolidation around approved vendor lists compresses competitive access for unqualified suppliers, while chromic material commoditization sustains price pressure at volume-tier positions. Three archetypes dominate: ITAR-compliant US system integrators, European Bundeswehr-focused R&D anchors, and Asian rapid-turnaround coating specialists. Capacity expansion and strategic technology licensing represent the dominant competitive moves as suppliers reconfigure manufacturing footprints for simultaneous chromic and metamaterial production.
Among defense prime contractors, BAE Systems and Rheinmetall occupy positions exemplifying the European system integrator archetype, with Saab AB representing Nordic specialization in wavelength-optimized concealment. These entities anchor regional procurement clusters through sustained electrochromic production line investment and Bundeswehr-focused development programs. Their geographic positioning reflects the concentration of NATO member defense spending in signature management modernization.
| Leading Market Players |
|---|
| BAE Systems |
| Rheinmetall |
| Saab AB |
| HyperStealth Biotechnology |
| Raytheon Technologies |
| Lockheed Martin |
| QinetiQ |
| Elbit Systems |
| Leonardo S.p.A. |
| Others |
Pricing and Supply Chain Analysis
REACH compliance under ECHA gates both qualified supply and premium-tier pricing access, as chromic coating formulations without full substance registration face exclusion from Bundeswehr procurement corridors while certified metamaterial architectures command multi-spectral performance premiums.
Pricing Analysis
Value-based pricing anchors on mission-critical detection avoidance outcomes, with UAV coating applications absorbing the steepest premiums where simultaneous visible-infrared-radar suppression determines survivability. Three-tier pricing structure across premium metamaterial systems, standard electrochromic configurations, and economy chromic coatings reflects certification grade differentiation and volume scale. Cost compression in commodity chromic tiers intensifies because South Korean DAPA pre-qualified material sets displace bilateral contracting. Defense agencies exhibit the lowest price sensitivity; municipal police departments evaluating wearable law enforcement variants demonstrate the highest.
Supply Chain Analysis
Regional distribution centers in Busan, Ulsan, and Daegu anchor hub-and-spoke patterns for chromic material processing serving Asia-Pacific defense procurement clusters. Rare earth element processing for electrochromic oxides concentrates in Chinese supply chains, while metamaterial fabrication draws from ITAR-compliant facilities in Virginia and Texas. Single-source vulnerability in tungsten oxide feedstocks exposes European coaters to input cost volatility. Distribution runs through defense agency approved vendor lists with pre-certified substrate libraries displacing traditional bilateral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where ITAR technology transfer restrictions and multi-domain certification timelines force weaker substrate suppliers without qualified manufacturing footprints into exit or acquisition.
For Market Incumbents: Hedge against chromic commoditization by deepening captive supply of rare earth oxide processing and securing Bundeswehr-approved vendor status for electrochromic vehicle coating programs. Capacity addition in Busan-Ulsan clusters captures DAPA procurement centralization while certification investment against EU defense procurement directives defends European access against REACH-registered competitors. For New Entrants and Emerging Players: FCC electromagnetic spectrum allocation rulings in the United States open a window for electroluminescent film manufacturers qualifying active camouflage systems under revised frequency bands. Law enforcement wearable devices in Germany represent the most penetrable segment; rapid color-matching service capabilities provide the essential go-to-market angle against established defense primes. For Investors and Strategic Acquirers: South Korean DAPA pre-qualified material set adoption is the leading indicator that procurement centralization will concentrate contract value among approved substrate libraries. Five-to-ten year viability favors acquisition targets with simultaneous chromic and metamaterial production footprints and existing CE marking or ITAR compliance infrastructure. Monitor FCC spectrum rulings for active system operational envelope expansion as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive tungsten oxide supply secures electrochromic coating margins against Chinese feedstock volatility. |
| Multi-Domain Certification Investment | Simultaneous US DoD, EU defense procurement, and DAPA qualification compresses competitor access to NATO modernization programs. |
| Pre-Qualified Substrate Library Expansion | South Korean approved vendor list positioning displaces bilateral contracting and accelerates procurement cycles. |
| Metamaterial-Chromic Hybrid Architecture Development | Tiered product portfolios span premium multi-spectral stealth and standard single-band concealment applications. |
| Regional Distribution Hub Establishment | Busan-Ulsan cluster presence captures DAPA procurement centralization and rapid color-matching service demand. |
Research Methodology
Defense procurement databases, ECHA REACH registration filings, and FCC electromagnetic spectrum rulings formed the secondary backbone, supplemented by primary interviews with Bundeswehr procurement officers, DAPA certification specialists, chromic coating plant managers, and UAV platform engineers. Bottom-up triangulation across substrate shipment volumes and top-down validation against defense agency modernization budget allocations ensured cross-verification. Stakeholder conversations addressed ITAR compliance pathways, metamaterial fabrication yield rates, and electrochromic integration complexity with legacy vehicle electronics.
Historical trendline analysis of soldier modernization program funding trajectories and UAV signature management contract awards established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include material type, technology mechanism, application platform, and end-user procurement authority. CAGRs derived from volume-weighted average growth rates across chromic, metamaterial, conductive polymer, and photonic crystal substrate categories. Industry-specific inputs encompassed rare earth element price indices, defense procurement cycle timing, and electromagnetic spectrum allocation decisions.
The model assumes a particular technology adoption path; alternative pathways for active electroluminescent film systems would alter the outlook if FCC rulings expand operational frequency envelopes or compress them through 5G interference constraints. Forecasts reflect stated assumptions regarding REACH compliance timelines, ITAR restriction continuity, and NATO member defense spending prioritization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.